
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
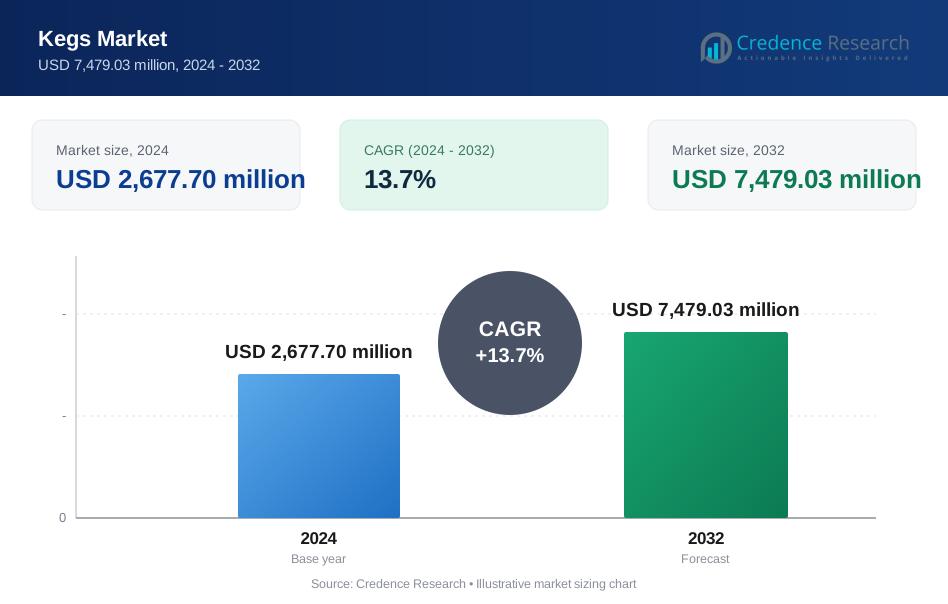
| Kegs Market Size 2024 | USD 2,677.70 Million |
| Kegs Market, CAGR | 13.7% |
| Kegs Market Size 2032 | USD 7,479.03 Million |
Market Overview
The global Kegs Market is projected to grow from USD 2,677.70 million in 2024 to USD 7,479.03 million by 2032, expanding at a CAGR of 13.7%.
The growth of the kegs market is driven by the increasing demand for sustainable packaging solutions, as businesses shift away from single-use bottles and cans. Additionally, the rising popularity of craft beer and the expanding global beverage industry contribute to market growth. The trend toward automation in beverage production also boosts demand for high-quality, reusable kegs. Technological advancements in keg manufacturing, such as lightweight designs and enhanced durability, are gaining traction. Furthermore, the growing preference for environmentally-friendly solutions aligns with the increasing adoption of kegs in breweries and beverage companies worldwide.
The kegs market shows considerable growth across key regions, with demand driven by expanding breweries and evolving beverage preferences. North America and Europe lead, supported by a well-established craft beer industry and rising environmental awareness that encourages reusable packaging. Meanwhile, Asia-Pacific is emerging as a significant market due to the growing popularity of Western drinking trends and increasing investment in the hospitality sector. Prominent companies like American Keg Company, NDL Keg Inc., Schaefer Container Systems, and Petainer UK Holdings Ltd. play pivotal roles, focusing on durable, sustainable kegs that cater to varying regional demands.
Market Drivers
Rising Demand for Craft Beer
The craft beer segment is rapidly expanding, driven by breweries offering diverse and unique flavors, brewing techniques, and styles. Consumers are drawn to the local and sustainable appeal of craft beer, which aligns with growing preferences for ethical and eco-conscious products. For instance, a report by the Brewers Association highlights that the number of craft breweries has been steadily increasing, reflecting the growing consumer interest in artisanal and locally produced beers. Furthermore, the premiumization trend in the beverage industry is elevating demand for high-quality, specialty beers, many of which are dispensed through kegs, further boosting the keg market.
Growing Popularity of Draft Beer
Draft beer continues to gain traction due to its perceived superior taste and freshness compared to bottled or canned alternatives. It is especially popular in social settings, with bars and restaurants emphasizing draft beer as part of the overall experience. For instance, a study by the Brewers Association found that draft beer sales in bars and restaurants have been rising, driven by consumer preferences for fresh and flavorful beer. The availability of a broad range of draft beer styles, from lagers to IPAs, appeals to a wide variety of consumer preferences, supporting the growing demand for kegs in both the domestic and commercial sectors.
Sustainability and Environmental Concerns
The environmental impact of packaging is a major driver of the keg market. Kegs generate significantly less waste than bottles or cans and are highly recyclable, positioning them as a more sustainable option. In addition, kegs are more efficient to transport and store, reducing the carbon footprint associated with beverage distribution, making them a preferred choice for environmentally conscious businesses and consumers alike.
Increasing Focus on Food and Beverage Service
Kegs are becoming an essential component of the food and beverage industry, particularly in enhancing dining experiences. By offering a diverse selection of draft beers, establishments can cater to a wide variety of tastes while also increasing revenue through premium beer offerings. Kegs also allow for customization and innovation, enabling the creation of unique beer blends and specialized cocktails, which help businesses differentiate themselves in a competitive market.
Market Trends
Rising Popularity of Craft Beer and Sustainability Trends
The increasing demand for craft beer, with its diverse flavors and styles, is significantly influencing the growth of the keg market. As consumers seek unique and artisanal beers, craft breweries are rising in popularity, driving the demand for kegs, which are ideal for preserving the taste and freshness of these beverages. In addition, the premiumization trend-where consumers are willing to pay more for high-quality craft beers-is further bolstering the demand for kegs in both commercial and residential settings. Moreover, sustainability concerns are accelerating the adoption of kegs as they generate less waste compared to bottles or cans, positioning them as an eco-friendly option. Kegs are also highly recyclable, promoting circular economy practices and supporting environmentally conscious consumption. Their efficient distribution and storage capabilities further reduce the carbon footprint associated with the beverage industry, making them increasingly attractive to businesses and consumers committed to sustainability.
Growth in the Foodservice Industry, Technological Advancements, and Global Expansion
The foodservice industry’s growth is another key trend propelling the demand for kegs. Restaurants and bars are leveraging kegs to offer a broader selection of draft beers, enhancing the overall dining experience for customers. For instance, a report by the Indian Brand Equity Foundation (IBEF) indicates that the Indian food services sector is poised for robust growth, driven by factors such as rapid urbanization and increased consumer spending. The ability to up-sell premium draft beers also contributes to increased revenue for these establishments. Additionally, kegs enable customization and innovation, allowing businesses to create unique beer blends and innovative beverage offerings, which help differentiate them in a competitive market. Technological advancements in keg systems, such as smart keg systems that provide real-time data on inventory, temperature, and pressure, are improving operational efficiency. Enhanced keg designs are also focusing on better durability, hygiene, and overall efficiency, making the product more attractive to businesses. Furthermore, the global expansion of the beverage industry, particularly in emerging markets, is driving increased demand for kegs as these regions adopt Western drinking habits. International beer festivals and events also contribute to this trend by showcasing diverse craft beers, heightening global awareness and increasing consumer interest in kegs.
Market Challenges Analysis
Initial Investment and Maintenance Costs
The initial investment in kegs can be a significant barrier, especially for smaller breweries and bars that may have limited budgets. Purchasing kegs requires substantial upfront capital, which can be a challenge for new or expanding businesses. For instance, a survey indicated that 80% of craft beverage producers purchase their kegs, with an average cost of around $69.48 per keg, while leasing costs average $61.50 annually for those who opt for that route. These activities can incur additional costs that strain the financial resources of smaller operations. For businesses looking to optimize their keg investment, the cumulative expenses associated with maintenance can sometimes outweigh the perceived benefits, particularly if volume and turnover are not high enough to justify the costs.
Logistical and Supply Chain Challenges
Kegs pose logistical challenges due to their size, weight, and the complexity of their transportation and storage. Their bulky nature makes it difficult to store them efficiently, and transporting large quantities of kegs can be costly and logistically demanding. Moreover, the return logistics for empty kegs can be time-consuming, adding to the overall cost structure for businesses. Supply chain disruptions, such as keg shortages or delayed deliveries, can also cause significant disruptions. During peak seasons or unforeseen crises, businesses may face difficulties in securing an adequate supply of kegs, leading to production delays and missed sales opportunities. Additionally, the rigorous cleaning and sanitation required to maintain kegs involve labor-intensive processes that further add to operational burdens. While kegs are more sustainable than single-use containers, their transportation and cleaning contribute to their carbon footprint. Moreover, the waste management of damaged or obsolete kegs is an environmental concern that must be addressed to minimize impact. Lastly, the growing popularity of single-serve packaging options like cans and bottles offers convenience to consumers, which can impact the demand for kegs in certain market segments.
Market Segmentation Analysis:
By Capacity:
The kegs market can be segmented by capacity, ranging from small, up to 20 L kegs, to large, above 60 L units. Smaller kegs, up to 20 L, are often preferred in niche markets, such as craft breweries, where smaller volumes suit limited production runs and taproom settings. The 20 L to 40 L range is widely used across various establishments, providing a balance between capacity and ease of handling, which is ideal for medium-scale breweries and local bars. Larger kegs, particularly those between 40 L to 60 L, cater to higher volume demands and are popular in commercial brewing and high-traffic establishments. For industrial-scale breweries and large event spaces, kegs above 60 L are essential, supporting substantial on-tap beverage supplies and high turnover demands. This segmentation addresses a diverse range of consumers, allowing manufacturers to tailor keg solutions to specific requirements across the beverage industry.
By Material:
Kegs are manufactured using various materials, with stainless steel, plastic, and tin as key options. Stainless steel kegs dominate the market due to their durability, resistance to corrosion, and suitability for preserving the quality and freshness of beverages. These qualities make them highly popular in commercial and craft brewing applications. Plastic kegs are gaining traction as a lightweight and cost-effective alternative, especially for small breweries and venues seeking portable and recyclable options. Their affordability and ease of handling make them suitable for short-term storage or limited release products. Tin kegs, though less common, are used in specific regional markets where tin is readily available and affordable. Each material type offers unique benefits and challenges, allowing brewers to select keg materials that align with their operational, environmental, and budgetary needs.
Segments:
Based on Capacity:
- Up to 20 L
- 20 L to 40 L
- 40 L to 60 L
- Above 60 L
Based on Material:
- Plastic
- Tin
- Stainless Steel
Based on End User:
- Alcoholic Beverages
- Beer
- Wine
- Spirits
- Cider
- Non-alcoholic Beverages
- Soft Drinks
- RTD Beverages
- Juices
- Others
- Cooking Oil
- Chemicals
- Others
Based on the Geography:
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis
North America
In North America, kegs command a significant portion of the market, with the region estimated to hold around 30% of the global keg market share in 2024. This is largely attributed to the region's thriving craft beer industry and a strong consumer preference for premium, draft-quality beverages. In particular, the United States drives regional growth, where the expansion of independent breweries and increasing demand for artisanal beers fuel keg demand. Additionally, North America's commitment to sustainable practices encourages the use of stainless steel kegs, which align with consumers’ environmental priorities. The well-established distribution channels across the U.S. ensure a steady supply of kegs to bars, restaurants, and events, creating an extensive market presence for kegs across diverse settings.
Europe
Europe follows closely, holding approximately 25% of the global keg market share, thanks to its longstanding beer culture and the high consumption of draft beer across countries like Germany, the UK, and Belgium. The region’s emphasis on traditional beer halls and pubs, particularly in Germany, where draft beer is a cultural staple, sustains the demand for larger-capacity kegs. Environmental regulations in Europe further support the preference for durable, reusable stainless steel kegs, contributing to the region's reputation for sustainable beverage dispensing practices. Europe’s market growth is additionally bolstered by tourism and international beer festivals that expose consumers to a wider variety of beers, driving keg demand across both metropolitan and rural pubs, restaurants, and hotels.
Key Player Analysis
- American Keg Company, LLC
- NDL Keg Inc.
- Shinhan Industrial Co, Ltd
- Ningbo BestFriends Beverage Containers Co. Ltd
- Blefa GmbH
- Schaefer Container Systems
- Petainer UK Holdings Ltd
- Ardagh Group S.A.
- Julius Kleemann GmbH & Co KG
- The Metal Drum Company
- THIELMANN - The Container Company
- Maisonneuve Group
Competitive Analysis
The kegs market is highly competitive, with leading players focused on durability, innovation, and sustainability to meet the needs of breweries and beverage producers. Companies such as American Keg Company, NDL Keg Inc., Shinhan Industrial Co., Ltd., Blefa GmbH, and Schaefer Container Systems emphasize robust stainless steel and recyclable materials that appeal to environmentally conscious consumers and businesses. Leading players are prioritizing the development of durable, recyclable materials, especially stainless steel and PET kegs, to meet both functional and environmental requirements. With sustainability concerns influencing consumer choices, companies are investing in eco-friendly kegs that reduce packaging waste and support circular economy practices. In addition to standardization, businesses are also focusing on product customization to cater to the diverse needs of breweries, bars, and beverage companies globally. Enhanced manufacturing processes and regional product variations allow manufacturers to deliver quality and meet specific regulatory standards across different markets. The competitive landscape is expected to grow further as companies strive for product differentiation through efficiency, durability, and improved logistics, meeting the evolving demands of the beverage industry.
Recent Developments
- In February 2024, Freedom Brewery, a British premium lager producer, launched a new contract brewing service to help producers meet increasing demands. With over US$ 2.68 million invested in production facilities, they offer brewing, bottling, canning, and kegging services.
- In February 2024, Tilray Brands planned to streamline its keg supply chain by transitioning to MicroStar's comprehensive outsourced keg management solution, ensuring efficient, sustainable, and high-quality growth.
- In February 2024, Community Groceries partnered with Tea-Biotics Kombucha to open Missouri's largest kombucha taproom, focusing on peach pineapple and grapefruit hibiscus flavors, replacing the former Community Groceries Crossroads Market.
- In October 2023, Konvoy Kegs, a keg rental company, raised US$ 13 million in funding to expand into the United Kingdom and Ireland, with plans to raise an additional US$ 10 million to rent kegs to 600 brewers in Australia and Asia.
Market Concentration & Characteristics
The kegs market is moderately concentrated, with a mix of established players and new entrants competing to meet the demands of the rapidly growing beverage industry. The market’s concentration is largely driven by the dominance of companies specializing in durable, high-quality kegs, particularly in stainless steel and recyclable materials, which align with sustainability trends. Additionally, keg manufacturers benefit from strong relationships with breweries, beverage distributors, and foodservice establishments, contributing to stable demand. Despite this, smaller players are making inroads by offering customizable and eco-friendly options, appealing to craft brewers and environmentally conscious consumers. Key characteristics of this market include a focus on durability, sustainability, and design innovation to enhance operational efficiency and extend product life. Technological advancements, such as smart kegs with tracking features, further distinguish offerings, and growing demand from emerging markets is encouraging geographic expansion. As competition intensifies, companies continue investing in product differentiation and logistics to capture market share.
Report Coverage
The research report offers an in-depth analysis based on Capacity, Material, End User and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The demand for kegs will increase as the popularity of craft and premium beers grows globally.
- Sustainability concerns will drive breweries to prefer kegs over disposable packaging due to reduced waste.
- Emerging markets will offer significant growth potential as Western beverage trends gain popularity.
- Technological innovations, such as smart kegs, will enhance inventory tracking and improve operational efficiency.
- The foodservice industry’s expansion will continue to elevate keg usage for enhanced dining experiences.
- Plastic and other recyclable materials will gain traction as eco-friendly alternatives to traditional stainless steel kegs.
- Supply chain optimization will become essential as logistics challenges and costs impact the industry.
- Increasing focus on quality and safety standards will lead to innovations in keg cleaning and maintenance.
- Keg manufacturers will benefit from partnerships with beverage brands and event organizers worldwide.
- Competition from alternative packaging formats may influence keg manufacturers to improve convenience and portability.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Kegs Market?
What factors are driving the growth of the Kegs Market?
What are the key segments within the Kegs Market?
What are some challenges faced by the Kegs Market?
Who are the major players in the Kegs Market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue) (Volume Where Applicable)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Kegs Scope – Segments & Subsegments Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 Industry Classification & Applicable Codes
- 1.5 Currency, Measurement Units & Valuation Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Kegs Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 2,677.70 million → 2032: USD 7,479.03 million)
- 2.1.2 Volume & Revenue – Global Totals (Volume Where Applicable)
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Kegs Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024 (Volume Where Applicable)
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Kegs Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Kegs Market Position in the Broader Industry Value Chain
- 3.1.2 Demand Structure & Purchasing Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Kegs Market Drivers
- 3.3 Kegs Market Restraints & Challenges
- 3.4 Kegs Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Kegs Value Chain Analysis
- 3.6.1 Upstream – Key Inputs, Resources & Suppliers
- 3.6.1.1 Key Input/Resource 1
- 3.6.1.2 Key Input/Resource 2
- 3.6.1.3 Key Input/Resource 3
- 3.6.2 Midstream – Core Operations & Value Creation
- 3.6.2.1 Operating Model & Process Overview
- 3.6.2.2 Key Operating Locations & Capabilities by Company
- 3.6.3 Downstream – Market Channels & End Users
- 3.6.3.1 Direct Sales & Customer Engagement Channels
- 3.6.3.2 Indirect Sales, Intermediaries & Partner Channels
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Key Inputs, Resources & Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Kegs Supply Chain Analysis
- 3.8.1 Critical Input & Resource Availability Risk Assessment
- 3.8.2 Supplier & Operational Concentration Risk (Geographic Exposure)
- 3.8.3 Supply & Service Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Kegs category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Kegs Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Market Size × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute Revenue Growth Through 2032
- 4.3 Incremental Demand Opportunity
- 4.3.1 By Region – Incremental Demand Through 2032
- 4.3.2 Segment – Incremental Demand
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Priority Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Priority market opportunity scorecards reflect the geographic scope and strategic relevance of the study. Listed markets are indicative and may be adapted to the industry.
Chapter 5. Kegs Cross-Border Trade & Market Access Analysis
- 5.1 International Trade & Cross-Border Activity Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024) (Volume Where Applicable)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024) (Volume Where Applicable)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Category 1 (Applicable Classification Code)
- 5.2.2 Category 2 (Applicable Classification Code)
- 5.2.3 Category 3 (Applicable Classification Code)
- 5.2.4 Category 4 (Applicable Classification Code)
- 5.2.5 Category 5 (Applicable Classification Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Category 1 (Applicable Classification Code)
- 5.3.2 Category 2 (Applicable Classification Code)
- 5.3.3 Category 3 (Applicable Classification Code)
- 5.3.4 Category 4 (Applicable Classification Code)
- 5.3.5 Category 5 (Applicable Classification Code)
- 5.4 Cross-Border Pricing & Transaction Benchmarks
- 5.4.1 Export Pricing – Segment & Country
- 5.4.2 Import Pricing – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Cross-Border Trade & Delivery Routes
- 5.5.1 Cross-Border Trade/Delivery Route 1
- 5.5.2 Cross-Border Trade/Delivery Route 2
- 5.5.3 Cross-Border Trade/Delivery Route 3
- 5.5.4 Cross-Border Trade/Delivery Route 4
- 5.5.5 Cross-Border Trade/Delivery Route 5
- 5.6 Trade Policy & Market Access Impact Assessment
- 5.6.1 Tariff & Non-Tariff Barriers
- 5.6.2 Regional Trade & Economic Integration Frameworks
- 5.6.3 Bilateral & Multilateral Trade Agreements
- 5.6.4 Cross-Border Operating, Licensing & Localization Requirements
Note: This chapter applies where cross-border trade or delivery is relevant to Kegs. Goods, services, and digital offerings are assessed using applicable classifications and transaction measures. Import-export volumes, trade balances, and route analyses are included only where meaningful to the market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Kegs Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – the historical period vs. 2024
- 6.1.2 Leading, Mid-Sized & Emerging Player Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Kegs Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company (Volume Where Applicable)
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution (the historical period vs. 2024)
- 6.2.5 Company Market Share by Key Segment
- 6.2.6 Company Market Share by Customer Group
- 6.3 Operating Scale, Capacity & Infrastructure Analysis
- 6.3.1 Global Operating Scale & Supply Capacity
- 6.3.2 Resource Utilization & Operating Efficiency
- 6.3.3 Output, Service Delivery & Activity Metrics
- 6.3.4 Operating Footprint & Infrastructure Map
- 6.3.5 Planned Operational & Capacity Expansion
- 6.4 Kegs Competitive Benchmarking Matrix
- 6.4.1 Revenue, Growth, Profitability & Operating Metric Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Kegs (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Products, Services & Solutions in Kegs
- 6.5.3 Operational & Infrastructure Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Kegs Market – By Sales & Delivery Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032) (Volume Where Applicable)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share (Volume Where Applicable)
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region (Volume Where Applicable)
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Sales & Delivery Channel
- 8.2.2 By Competitive Positioning & Price Tier
Chapter 9. North America Kegs Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Kegs Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Kegs Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Kegs Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Kegs Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Kegs Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Kegs Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Supply, Output & Operating Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Demand, Adoption & Usage Assumptions
- Appendix F – Pricing & Revenue Metric Reference Tables
- Appendix G – Company Operations & Infrastructure Database
- Appendix H – Cross-Border Trade & Activity Data Tables (Where Applicable)
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
