
Market Overview:
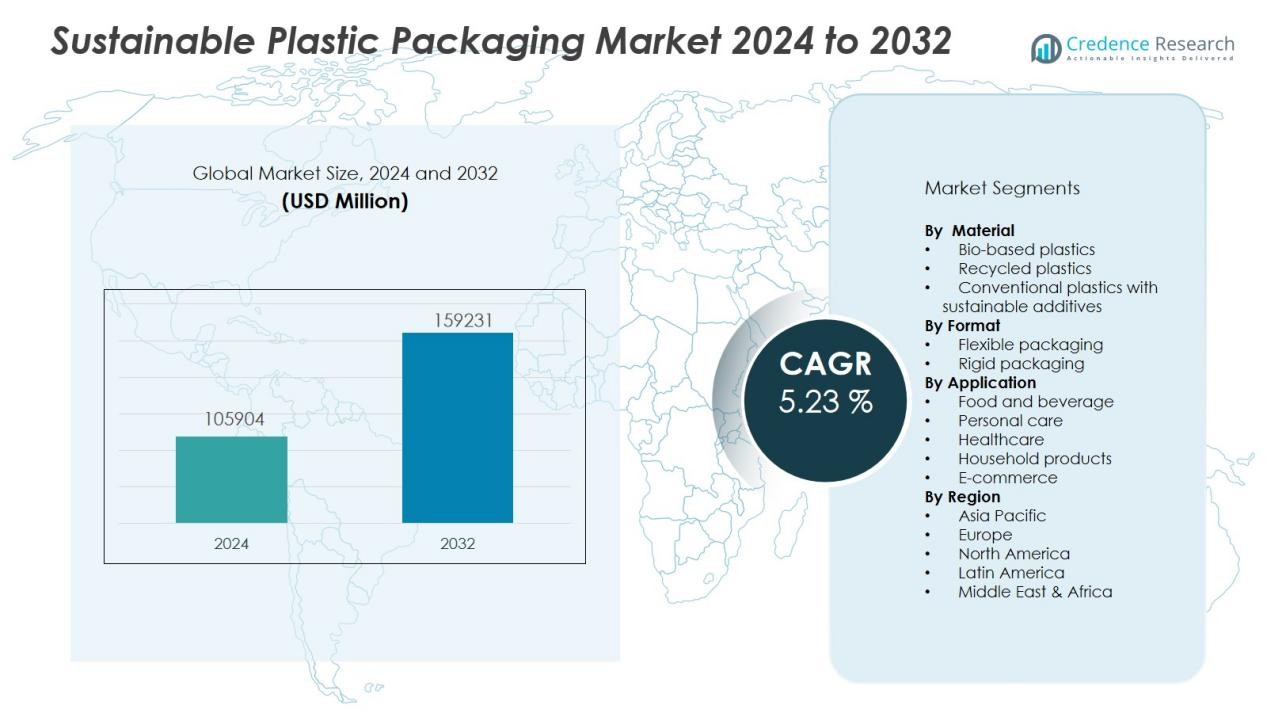
The Sustainable plastic packaging market size was valued at USD 105904 million in 2024 and is anticipated to reach USD 159231 million by 2032, at a CAGR of 5.23 % during the forecast period (2024-2032).
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2024 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Sustainable plastic packaging market Size 2024 | USD 105904 Million |
| Sustainable plastic packaging market, CAGR | 5.23 % |
| Sustainable plastic packaging market Size 2032 | USD 159231 Million |
Key drivers fueling market expansion include stringent government regulations targeting single-use plastics, growing consumer awareness of environmental sustainability, and strong demand from end-use sectors such as food and beverage, healthcare, and personal care. Companies are prioritizing lightweight packaging, reducing carbon footprints, and improving recyclability to meet both regulatory standards and evolving consumer preferences. Technological advancements, such as bio-based resins and advanced recycling techniques, further enhance product performance and support large-scale adoption.
Regionally, Europe leads the sustainable plastic packaging market, supported by rigorous sustainability mandates and proactive government initiatives. North America follows closely, with substantial investments in green technologies and corporate sustainability goals. The Asia-Pacific region is poised for the fastest growth, driven by rapid urbanization, expanding manufacturing bases, and rising regulatory focus on plastic waste management.
Market Insights:
- The sustainable plastic packaging market was valued at USD 105,904 million in 2024 and is forecast to reach USD 159,231 million by 2032, growing at a CAGR of 5.23%.
- Stringent government regulations targeting single-use plastics and mandates for recyclability drive rapid adoption of sustainable packaging solutions.
- Consumer demand for environmentally friendly packaging continues to rise, motivating brands to reduce plastic usage and increase transparency around sustainability.
- Advances in bio-based resins, compostable polymers, and recycling technologies enable the development of high-performance, eco-friendly packaging options.
- High production costs and limited supply of advanced materials challenge large-scale adoption, while inconsistent recycling infrastructure limits progress in many regions.
- Europe leads with a 36% market share, benefiting from strict environmental regulations, proactive investments, and strong public support for green packaging.
- North America and Asia-Pacific follow, with North America at 28% driven by innovation and sustainability goals, and Asia-Pacific at 24% supported by rapid urbanization, regulatory changes, and investment in recycling infrastructure.
Market Drivers:
Stringent Regulatory Frameworks Accelerate Adoption of Sustainable Plastic Packaging:
Government policies and regulations targeting single-use plastics significantly drive the sustainable plastic packaging market. Authorities worldwide are enforcing strict limits on plastic waste and mandating the use of recyclable or compostable materials. The push for compliance with global environmental standards compels manufacturers to prioritize sustainable solutions. Companies in the packaging sector respond by investing in eco-friendly materials and technologies.
- For instance, Amcor surpassed its target of incorporating 10% post-consumer recycled content one year ahead of schedule and procured 254,000 metric tons of recycled plastic for its packaging solutions in FY24.
Rising Consumer Demand for Environmentally Friendly Packaging Solutions:
Heightened environmental awareness among consumers strongly influences purchasing decisions. Shoppers increasingly seek brands that demonstrate commitment to sustainability and responsible packaging practices. The sustainable plastic packaging market benefits from this shift, with businesses redesigning products to minimize plastic usage and promote recyclability. It motivates brands to communicate their environmental credentials more transparently.
- For instance, Coca-Cola European Partners eliminated over 10,000 tonnes of virgin plastic per year by transitioning its small PET bottles to 100% rPET in the Netherlands, reducing carbon footprint by 21% percent.
Innovations in Material Science and Recycling Technologies Drive Market Growth:
Advancements in bio-based resins, compostable polymers, and mechanical recycling methods provide new opportunities for sustainable plastic packaging. Industry players develop innovative packaging solutions that deliver both performance and reduced environmental impact. The sustainable plastic packaging market witnesses rapid product launches and collaborations aimed at scaling advanced materials. Companies focus on enhancing material strength, shelf life, and end-of-life recyclability.
Corporate Sustainability Goals and Brand Reputation Fuel Market Expansion:
Leading companies prioritize sustainability targets within their business strategies, recognizing the direct link between environmental stewardship and brand value. Many organizations set ambitious goals for reducing plastic use and increasing the share of sustainable packaging in their portfolios. The sustainable plastic packaging market responds to these corporate commitments with customized solutions that align with brand image. Transparent reporting and third-party certifications help build consumer trust and competitive advantage.
Market Trends:
Rapid Shift Toward Biodegradable and Compostable Materials Reshapes Packaging Landscape:
The sustainable plastic packaging market sees a significant transition toward biodegradable and compostable materials, driven by both regulatory mandates and consumer demand. Packaging producers expand their portfolios to include bioplastics derived from renewable sources such as corn starch, sugarcane, and cellulose. These materials help companies address environmental concerns by reducing reliance on traditional petrochemical plastics. Brands leverage these innovations to differentiate themselves and appeal to environmentally conscious consumers. The industry adopts clear labeling and certification standards to build trust and demonstrate compliance with environmental regulations. Companies invest in research and development to improve the performance and scalability of these materials while maintaining cost competitiveness. Strong interest from the food and beverage, personal care, and e-commerce sectors accelerates market transformation.
- For instance, NatureWorks is constructing a fully integrated Ingeo™ PLA biopolymer plant in Thailand with an annual capacity of 75,000 tons of bioplastic scheduled to come online in 2025 to meet rising demand.
Circular Economy Principles and Advanced Recycling Technologies Gain Momentum:
Emphasis on circular economy models drives major changes in product design, material selection, and end-of-life management. The sustainable plastic packaging market benefits from advancements in chemical recycling, closed-loop systems, and reusable packaging formats. Industry participants work with stakeholders across the value chain to enable effective collection, sorting, and repurposing of used packaging. It prioritizes collaboration between manufacturers, retailers, and policymakers to achieve higher recycling rates and reduce landfill waste. Digital tracking systems, eco-design strategies, and integration of recycled content into new products reflect the growing importance of resource efficiency. Companies strengthen their sustainability commitments by launching pilot projects and scaling circular solutions, reinforcing the shift toward a low-waste, regenerative packaging ecosystem.
- For instance, Eastman’s Kingsport molecular recycling plant in Tennessee processes 110,000 metric tons of hard-to-recycle plastic waste annually, converting it into virgin-quality polymers
Market Challenges Analysis:
High Production Costs and Limited Availability of Advanced Materials Restrict Market Expansion:
The sustainable plastic packaging market faces persistent challenges from the high production costs and limited supply of eco-friendly raw materials. Biodegradable and compostable alternatives often require more complex manufacturing processes and costly feedstocks compared to conventional plastics. Many companies struggle to absorb these expenses, which can impact product pricing and limit widespread adoption. Supply chain constraints further complicate efforts to scale up production, with bio-based materials sometimes in short supply. The industry must address these barriers to support broader market penetration and meet sustainability targets.
Lack of Standardized Recycling Infrastructure and Consumer Awareness Hinders Progress:
Disparities in recycling infrastructure and inconsistent collection systems present significant obstacles for the sustainable plastic packaging market. Many regions lack the necessary facilities to process new materials, creating gaps in the circular economy. It creates confusion among consumers about proper disposal methods, reducing the effectiveness of recycling programs. Limited public awareness and education around sustainable packaging further impede recycling rates. Stakeholders across the value chain must coordinate efforts to build robust infrastructure and increase public engagement for true progress.
Market Opportunities:
Expansion into Emerging Markets Unlocks New Growth Avenues for Sustainable Packaging:
The sustainable plastic packaging market holds strong opportunities in emerging economies, where rapid urbanization and rising consumer awareness drive demand for eco-friendly solutions. Businesses can capitalize on evolving regulatory frameworks and increased environmental focus in Asia-Pacific, Latin America, and Africa. Local governments invest in waste management infrastructure and promote sustainable practices, creating favorable conditions for market entry. Companies introducing affordable, scalable, and region-specific packaging options can gain early-mover advantages. The market benefits from strategic partnerships with local manufacturers and stakeholders, which enable faster adaptation to regional preferences. Growth in organized retail and e-commerce further supports market expansion across these dynamic regions.
Advancements in Smart and Functional Packaging Enhance Value Propositions:
Integration of smart and functional technologies offers fresh opportunities for differentiation within the sustainable plastic packaging market. Brands adopt packaging with features such as QR codes, freshness indicators, and traceability elements to improve consumer engagement and product safety. These innovations enable companies to add value beyond sustainability by addressing transparency, shelf life, and quality concerns. It encourages R&D investment in packaging that combines eco-friendly materials with digital capabilities. The trend toward personalized and intelligent packaging solutions positions market players to tap into evolving customer expectations. Forward-thinking companies that embrace smart packaging technology set themselves apart and strengthen long-term competitiveness.
Market Segmentation Analysis:
By Material:
The sustainable plastic packaging market segments by material into bio-based plastics, recycled plastics, and conventional plastics with additives. Bio-based plastics, derived from renewable resources, see rapid growth due to increasing environmental regulations and consumer demand for low-impact products. Recycled plastics remain a key segment, benefiting from investments in advanced recycling processes and closed-loop supply chains. Conventional plastics with sustainable additives hold a smaller share but provide transitional solutions for manufacturers adapting to stricter standards.
- For instance, U.S.-based Brightmark operates the world’s largest advanced plastics recycling plant in Indiana, with a capacity to convert 100,000tons of plastic waste annually into fuels and waxes, significantly reducing landfill contributions.
By Format:
By format, the market divides into rigid and flexible packaging solutions. Flexible packaging dominates due to its lightweight, cost-effective, and versatile nature, supporting a wide range of end uses. Rigid packaging, while maintaining a steady share, appeals to sectors requiring durability and product protection, such as food, beverages, and personal care. The shift toward formats that minimize material use and improve recyclability drives continuous product innovation in both segments.
- For instance, Amcor partnered with Bulldog to reduce the wall thickness of its 100 mL and 150 mL flexible skincare tubes by 16.67%, saving 8.5 metric tonnes of plastic annually.
By Application:
The sustainable plastic packaging market, by application, includes food and beverage, personal care, healthcare, household products, and e-commerce. Food and beverage lead adoption, responding to consumer demand and regulatory requirements for safe, sustainable packaging. Personal care and healthcare sectors prioritize sustainable options to align with brand values and address rising health and safety standards. E-commerce growth accelerates demand for protective and lightweight sustainable packaging solutions that reduce waste and logistics costs.
Segmentations:
By Material:
- Bio-based plastics
- Recycled plastics
- Conventional plastics with sustainable additives
By Format:
- Flexible packaging
- Rigid packaging
By Application:
- Food and beverage
- Personal care
- Healthcare
- Household products
- E-commerce
By Region:
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis:
Europe :
Europe holds a 36% share of the sustainable plastic packaging market, supported by comprehensive policies targeting plastic waste reduction and resource efficiency. The European Union enforces strict directives that mandate recyclability, eco-design, and reduced single-use plastics. Leading economies, including Germany, France, and the United Kingdom, spearhead investments in advanced recycling technologies and infrastructure upgrades. The region benefits from high consumer awareness and strong public support for green packaging solutions. Major brands collaborate with regulatory bodies to launch new products that comply with evolving standards. Industry participants respond quickly to shifting regulations and sustainability trends, reinforcing Europe’s leadership position.
North America :
North America commands a 28% share of the sustainable plastic packaging market, with the United States and Canada at the forefront of innovation. Major corporations set ambitious sustainability goals, driving demand for recyclable, compostable, and bio-based packaging options. Government support through funding and public-private partnerships strengthens market momentum. The region features a robust recycling infrastructure and a vibrant start-up ecosystem focused on material innovation. It benefits from strong retail and e-commerce sectors that prioritize sustainable packaging to meet evolving consumer preferences. Collaboration between academia, industry, and government accelerates the commercialization of new technologies.
Asia-Pacific :
Asia-Pacific captures a 24% share of the sustainable plastic packaging market, driven by rapid industrialization, population growth, and rising environmental consciousness. China, Japan, and India invest heavily in waste management and recycling initiatives, shaping new market opportunities. Regional governments introduce regulations targeting plastic waste, encouraging local manufacturers to adopt sustainable practices. Growing middle-class populations demand eco-friendly products, prompting retailers and FMCG companies to expand green packaging portfolios. It benefits from international investments in technology transfer and infrastructure development. Strategic collaborations between global and local players foster innovation and market penetration across diverse economies.
Key Player Analysis:
- Amcor plc
- DS Smith
- Elopak AS
- Smurfit Kappa
- Berry Global Inc.
- Sealed Air
- Sonoco Products Company
- Tetra Pak
- Mondi
- Elevate Packaging
- Huhtamaki Oyj
- UFlex Limited
Competitive Analysis:
The sustainable plastic packaging market features a competitive landscape led by global giants such as Amcor plc, DS Smith, Elopak AS, Smurfit Kappa, Berry Global Inc., Sealed Air, Sonoco Products Company, and Tetra Pak. These companies leverage advanced R&D, strategic acquisitions, and broad distribution networks to maintain leadership positions. It demonstrates rapid innovation in material science, design, and recyclability to align with evolving regulatory standards and consumer preferences. Companies compete on factors such as product performance, sustainability credentials, and cost efficiency. They form strategic partnerships with retailers, raw material suppliers, and technology providers to expand market presence and accelerate new product launches. The competitive environment remains dynamic, with new entrants and established players pursuing growth through sustainable product portfolios and digital transformation initiatives.
Recent Developments:
- In April 2025, Amcor completed its all-stock combination with Berry Global, creating a leading force in consumer and healthcare packaging.
- In Feb 2025, DS Smith was acquired by International Paper, resulting in the formation of a new global leader in sustainable packaging.
- In June 2025, Elopak, together with Orkla Home and Personal Care and Dow, launched the first cartons using both recycled and renewable polymers in their D-PAK™ carton line.
Market Concentration & Characteristics:
The sustainable plastic packaging market exhibits moderate concentration, with a mix of global leaders and strong regional players shaping its competitive landscape. Leading companies, such as Amcor, Berry Global, Sealed Air, and DS Smith, command significant shares due to extensive R&D, broad product portfolios, and established supply chains. It features frequent partnerships, mergers, and acquisitions that accelerate innovation and geographic expansion. The market remains highly dynamic, characterized by rapid material advancements, regulatory compliance pressures, and shifting consumer preferences. Companies continuously invest in eco-friendly technologies and digital solutions to strengthen differentiation and meet evolving industry standards.
Report Coverage:
The research report offers an in-depth analysis based on Material, Format, Application and Region. It details leading Market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current Market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven Market expansion in recent years. The report also explores Market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on Market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the Market.
Future Outlook:
- Demand for sustainable plastic packaging will accelerate due to stricter environmental regulations and government bans on single-use plastics.
- Industry leaders will expand investment in research and development to advance biodegradable, compostable, and recyclable packaging technologies.
- Consumer preferences will continue shifting toward eco-friendly packaging, prompting brands to adopt more transparent sustainability practices.
- Companies will increasingly incorporate circular economy principles, focusing on closed-loop systems and improved recycling infrastructure.
- Smart and functional packaging solutions will gain momentum, offering features such as traceability, product authentication, and interactive consumer engagement.
- Collaboration among manufacturers, retailers, and policymakers will intensify to standardize materials and streamline end-of-life management.
- The food and beverage, personal care, and e-commerce sectors will drive the fastest adoption rates for sustainable plastic packaging.
- Expansion into emerging markets will present new opportunities, fueled by urbanization, growing consumer awareness, and regulatory support.
- Material innovation will accelerate, with companies focusing on bio-based resins, enhanced recyclability, and lightweight designs.
- The competitive landscape will remain dynamic, with frequent mergers, partnerships, and new entrants pursuing leadership in sustainable solutions.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Stringent Regulatory Frameworks
Government policies and regulations targeting single-use plastics and mandating recyclability are compelling manufacturers to adopt sustainable plastic packaging solutions, accelerating market growth as companies strive to comply with evolving standards.
Rising Consumer Environmental Awareness
Consumers are increasingly demanding eco-friendly packaging, prompting brands to reduce plastic usage, improve recyclability, and communicate sustainability efforts more transparently, thereby driving adoption of sustainable plastic packaging.
Technological Advancements in Materials and Recycling
Innovations in bio-based resins, compostable polymers, and advanced recycling technologies are enabling the development of high-performance, sustainable packaging options, making it easier for companies to meet both regulatory and consumer expectations.
Corporate Sustainability Goals
Major companies are setting ambitious targets to reduce plastic use and increase the share of sustainable packaging in their portfolios, fueling market expansion as sustainability becomes integral to brand reputation and competitive differentiation.
Expansion in Emerging Markets
Rapid urbanization, regulatory changes, and growing consumer awareness in emerging economies are creating new opportunities for sustainable plastic packaging, with investments in waste management and recycling infrastructure supporting market entry and growth.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for the sustainable plastic packaging market, and what is its projected size in 2032?
At what compound annual growth rate is the sustainable plastic packaging market projected to grow between 2024 and 2032?
Which sustainable plastic packaging market segment held the largest share in 2024?
What are the primary factors fueling the growth of the sustainable plastic packaging market?
Who are the leading companies in the sustainable plastic packaging market?
Which region commanded the largest share of the sustainable plastic packaging market in 2024?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Format
- 1.2.1 Flexible packaging
- 1.2.2 Rigid packaging
- 1.3 By Material
- 1.3.1 Bio-based plastics
- 1.3.2 Recycled plastics
- 1.3.3 Conventional plastics with sustainable additives
- 1.4 By Application
- 1.4.1 Food and beverage
- 1.4.2 Personal care
- 1.4.3 Healthcare
- 1.4.4 Household products
- 1.4.5 E-commerce
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 105,904 million → 2032: USD 159,231 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Sustainable Plastic Packaging Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Sustainable Plastic Packaging Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Sustainable Plastic Packaging Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Sustainable Plastic Packaging Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Sustainable Plastic Packaging Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Sustainable Plastic Packaging Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Sustainable Plastic Packaging Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Sustainable Plastic Packaging Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 105,904 million → 2032: USD 159,231 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Sustainable Plastic Packaging Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Format - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Flexible packaging
- 12.3.7.2 Rigid packaging
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Material - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Bio-based plastics
- 12.4.7.2 Recycled plastics
- 12.4.7.3 Conventional plastics with sustainable additives
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Application - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Food and beverage
- 12.5.7.2 Personal care
- 12.5.7.3 Healthcare
- 12.5.7.4 Household products
- 12.5.7.5 E-commerce
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global Sustainable Plastic Packaging End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Sustainable Plastic Packaging Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Sustainable Plastic Packaging Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Sustainable Plastic Packaging Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Amcor plc
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 DS Smith
- 18.4 Elopak AS
- 18.5 Smurfit Kappa
- 18.6 Berry Global Inc.
- 18.7 Sealed Air
- 18.8 Sonoco Products Company
- 18.9 Tetra Pak
- 18.10 Mondi
- 18.11 Huhtamaki Oyj
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

