
Market Overview
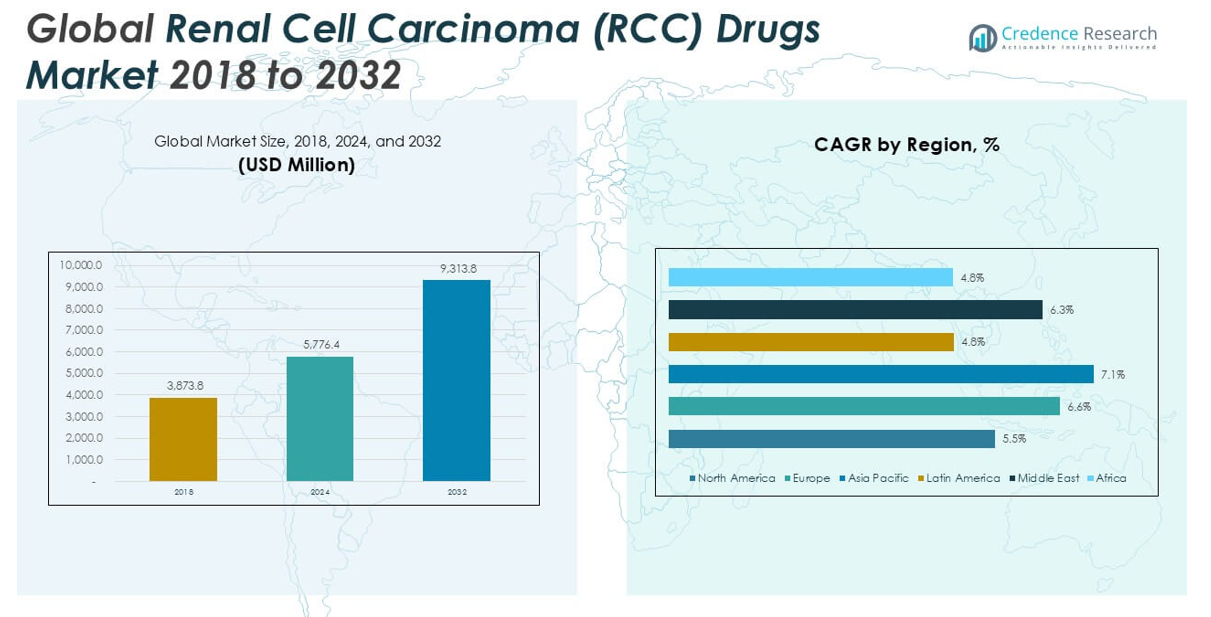
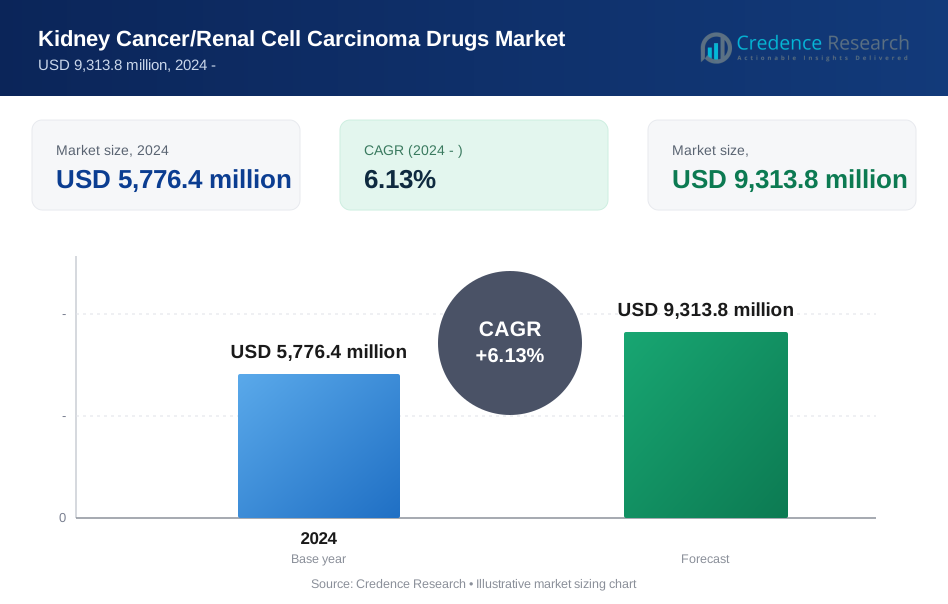
The Renal Cell Carcinoma (RCC) Drugs Market size was valued at USD 3,873.8 million in 2018, increased to USD 5,776.4 million in 2024, and is anticipated to reach USD 9,313.8 million by 2032, at a CAGR of 6.13% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Renal Cell Carcinoma (RCC) Drugs Market Size 2024 | USD 5,776.4 million |
| Renal Cell Carcinoma (RCC) Drugs Market, CAGR | 6.13% |
| Renal Cell Carcinoma (RCC) Drugs Market Size 2032 | USD 9,313.8million |
The Renal Cell Carcinoma (RCC) Drugs market is driven by leading pharmaceutical companies such as Active Biotech AB, Amgen, Bayer AG, Cipla Limited, F. Hoffmann-La Roche AG, GSK plc, Novartis AG, Pfizer, Inc., and AstraZeneca PLC. These players maintain a strong competitive position through robust product pipelines, strategic collaborations, and continuous innovation in targeted and immunotherapy treatments. North America leads the global RCC Drugs market, holding approximately 33.9% of the total market share in 2024, supported by advanced healthcare infrastructure, high treatment adoption rates, and the strong presence of key market participants. Europe and Asia Pacific follow as significant regions contributing to market growth.
Market Insights
- The Renal Cell Carcinoma (RCC) Drugs market was valued at USD 3,873.8 million in 2018, reached USD 5,776.4 million in 2024, and is expected to grow to USD 9,313.8 million by 2032 at a CAGR of 6.13%.
- The market is primarily driven by the rising prevalence of RCC, increasing demand for targeted therapies, and advancements in immunotherapy that improve patient survival rates.
- A major trend in the market is the growing preference for combination therapies and oral drugs, with the oral segment leading due to convenience and better patient adherence.
- Key players such as Pfizer, Novartis, Roche, and AstraZeneca dominate the market, with competition focused on expanding drug pipelines, clinical trials, and approvals for novel therapies.
- North America holds the largest regional share at 33.9% in 2024, followed by Asia Pacific at 25.5%, while angiogenesis inhibitors remain the leading drug class segment globally.
Market Segmentation Analysis:
By Drug Class
In the Renal Cell Carcinoma (RCC) Drugs market, angiogenesis inhibitors dominate the drug class segment, accounting for the largest market share in 2024. The significant demand for angiogenesis inhibitors is driven by their proven efficacy in targeting the vascular endothelial growth factor (VEGF) pathway, which plays a critical role in tumor growth and metastasis. Additionally, the increasing adoption of targeted therapies over traditional chemotherapy fuels the growth of this sub-segment. Monoclonal antibodies and mTOR inhibitors are also gaining traction, supported by advancements in immunotherapy and ongoing clinical trials introducing newer, more effective treatment combinations.
- For instance, Pfizer’s sunitinib (Sutent), an angiogenesis inhibitor, has demonstrated a median progression-free survival (PFS) of 11 months in clinical studies, significantly improving treatment outcomes compared to interferon-alpha, which showed a PFS of 5 months.
By Route of Administration
The oral route of administration leads the market with the highest share, primarily due to patient preference for ease of consumption and improved treatment adherence compared to intravenous or subcutaneous options. The availability of several leading RCC drugs, such as tyrosine kinase inhibitors, in oral formulations has further strengthened this dominance. Oral therapies enable outpatient treatment, reduce hospitalization rates, and offer convenience, which collectively drive their widespread acceptance. Intravenous administration remains crucial for advanced or hospital-based treatments, while subcutaneous delivery holds a smaller share, typically limited to specific immunotherapy drugs.
- For instance, Novartis’ everolimus (Afinitor), administered orally, has been shown to provide a median overall survival of 14.8 months in patients with advanced RCC following VEGF-targeted therapy, highlighting its effectiveness and patient-centric dosing advantage.
By Distribution Channel
Hospital pharmacies hold the largest share in the distribution channel segment of the RCC drugs market, supported by the high reliance on hospitals for the administration of intravenous drugs and the management of advanced-stage cancer treatments. The critical need for controlled and supervised drug dispensation in clinical settings strengthens the hospital pharmacy segment’s dominance. Retail pharmacies follow, benefiting from the growing availability of oral RCC drugs that patients can access post-prescription. Online pharmacies are rapidly emerging, driven by increasing digital adoption, patient preference for home delivery, and improved access to maintenance medications.
Market Overview
Rising Incidence of Renal Cell Carcinoma
The increasing global prevalence of renal cell carcinoma significantly drives the demand for RCC drugs. Factors such as aging populations, rising obesity rates, smoking habits, and genetic predispositions contribute to the growing number of RCC cases worldwide. Early detection initiatives and improved diagnostic techniques have further increased the identification of RCC at various stages, necessitating more advanced and targeted drug therapies. This escalating disease burden compels healthcare providers and pharmaceutical companies to invest in effective treatment solutions, propelling market growth.
- For instance, the American Cancer Society estimated 81,800 new cases of kidney cancer in the United States in 2024, of which renal cell carcinoma accounts for approximately 90%, underscoring the urgent demand for effective RCC treatments.
Advancements in Targeted Therapies and Immunotherapies
Rapid advancements in targeted therapies and immunotherapy options have revolutionized RCC treatment and are key growth drivers for the market. The introduction of immune checkpoint inhibitors, tyrosine kinase inhibitors, and combination therapies has significantly improved survival rates and treatment outcomes. Pharmaceutical companies are increasingly focusing on developing next-generation RCC drugs that offer higher efficacy with fewer side effects. These innovations, supported by an expanding clinical pipeline and regulatory approvals, are accelerating the adoption of novel therapies, thereby boosting market expansion.
- For instance, Bristol Myers Squibb’s nivolumab (Opdivo) combined with ipilimumab (Yervoy) demonstrated an overall survival rate of 47 months in intermediate- and poor-risk RCC patients in the CheckMate 214 trial, compared to 26.6 months with sunitinib alone.
Increasing Healthcare Expenditure and Access to Novel Treatments
Rising healthcare spending across developed and emerging markets has enhanced patient access to novel RCC treatment options. Governments and private insurers are expanding reimbursement coverage for advanced cancer therapies, reducing the financial barriers for patients. Additionally, increasing awareness regarding the availability of innovative RCC drugs, coupled with growing investments in oncology care infrastructure, supports the timely diagnosis and administration of effective treatments. This broadening healthcare access fosters a more favorable environment for market growth globally.
Key Trends & Opportunities
Growing Focus on Combination Therapies
A major trend in the RCC drugs market is the growing adoption of combination therapies, particularly immune checkpoint inhibitors combined with targeted agents. These combinations have demonstrated superior clinical outcomes compared to monotherapies, offering extended progression-free survival and improved overall survival rates. The success of clinical trials focusing on combination regimens is encouraging pharmaceutical companies to develop and commercialize more multi-drug treatment protocols. This trend represents a significant opportunity for both new entrants and established players to introduce differentiated products.
- For instance, Merck’s pembrolizumab (Keytruda) in combination with axitinib achieved a median progression-free survival of 15.1 months in treatment-naïve advanced RCC patients, compared to 11.1 months with sunitinib alone, as per the KEYNOTE-426 trial results.
Expansion in Emerging Markets
Emerging economies present untapped growth opportunities for the RCC drugs market due to their large patient populations and increasing healthcare investments. Countries in Asia-Pacific, Latin America, and the Middle East are witnessing rapid improvements in cancer care infrastructure and drug accessibility. Pharmaceutical companies are actively expanding their distribution networks, forging partnerships, and pursuing regulatory approvals in these regions. The rising affordability of targeted therapies and improving insurance coverage in these markets create a favorable landscape for sustained market penetration.
- For instance, in Japan, Takeda received approval in 2020 to commercialize Exelixis’ cabozantinib (Cabometyx) for unresectable or metastatic RCC, based on data from the CABOSUN study in which 79 treated patients had a median progression‑free survival of 8.6 months extending access to advanced RCC treatment across Asia‑Pacific markets.
Key Challenges
High Cost of Advanced RCC Therapies
One of the primary challenges in the RCC drugs market is the high cost associated with novel targeted and immunotherapy treatments. Many of the latest RCC drugs come with substantial price tags, making them inaccessible to a significant portion of the patient population, especially in low- and middle-income countries. Despite insurance support, out-of-pocket expenses for patients can be considerable, potentially limiting the widespread adoption of these life-extending therapies and posing barriers to equitable treatment access.
Adverse Side Effects and Drug Resistance
Adverse side effects associated with RCC therapies, including fatigue, hypertension, and immune-related complications, remain a significant concern. These side effects can lead to treatment discontinuation, negatively affecting patient outcomes. Additionally, the issue of drug resistance over time reduces the long-term effectiveness of targeted therapies, necessitating the continuous development of alternative treatment options. Managing toxicity and resistance remains a clinical and research challenge that could impede optimal disease management and market growth.
Stringent Regulatory Requirements
The RCC drugs market faces stringent regulatory hurdles that can delay product approvals and market entry. Regulatory agencies demand comprehensive clinical trial data to ensure drug safety and efficacy, which extends development timelines and increases costs. For pharmaceutical companies, navigating these rigorous approval processes, especially in multiple international markets, can present significant operational and financial challenges. Delays in approval or post-marketing safety concerns can limit the commercial success of new RCC therapies.
Regional Analysis
North America
North America held the largest share of the Renal Cell Carcinoma (RCC) Drugs market, accounting for approximately 33.9% in 2024, with a market size of USD 1,933.86 million, up from USD 1,343.05 million in 2018. The market is projected to reach USD 2,970.16 million by 2032, growing at a CAGR of 5.5% during the forecast period. This growth is driven by the high prevalence of RCC, advanced healthcare infrastructure, and the rapid adoption of novel immunotherapies and targeted drugs. Increased healthcare spending and strong presence of key pharmaceutical players further bolster regional market expansion.
Europe
Europe captured around 22.5% of the RCC Drugs market in 2024, with a market size of USD 1,291.03 million, rising from USD 843.72 million in 2018. The market is anticipated to reach USD 2,152.41 million by 2032, registering a CAGR of 6.6%. Growth in Europe is supported by increasing early-stage cancer diagnoses, favorable reimbursement policies, and the expanding availability of advanced RCC therapies. Countries such as Germany, France, and the UK are leading the regional market, driven by their strong oncology research and access to cutting-edge treatments through well-established healthcare systems.
Asia Pacific
Asia Pacific accounted for approximately 25.5% of the RCC Drugs market in 2024, with a market size of USD 1,474.47 million, up from USD 929.72 million in 2018. The market is forecasted to reach USD 2,566.88 million by 2032, growing at the fastest CAGR of 7.1%. The region's rapid growth is fueled by rising RCC incidence, improving cancer care infrastructure, and growing healthcare investments in countries like China, Japan, and India. Increasing patient awareness, favorable government initiatives, and expanding access to advanced treatments are further driving market development across Asia Pacific.
Latin America
Latin America held about 10% of the RCC Drugs market in 2024, with a market size of USD 575.00 million, growing from USD 413.34 million in 2018. The market is projected to reach USD 838.24 million by 2032, at a CAGR of 4.8% during the forecast period. Growth in this region is supported by improving healthcare accessibility, expanding pharmaceutical distribution networks, and gradual adoption of targeted RCC therapies. Brazil and Mexico are among the leading contributors, driven by their growing healthcare expenditures and increasing patient demand for innovative cancer treatments.
Middle East
The Middle East accounted for approximately 5.4% of the RCC Drugs market in 2024, reaching a market size of USD 314.65 million, up from USD 209.19 million in 2018. By 2032, the market is expected to grow to USD 513.19 million, registering a CAGR of 6.3%. Market growth is supported by the rising prevalence of RCC, increasing cancer awareness, and the gradual enhancement of oncology treatment infrastructure. The Gulf Cooperation Council (GCC) countries, particularly Saudi Arabia and the UAE, are driving market demand through healthcare modernization initiatives and improved access to advanced oncology drugs.
Africa
Africa held the smallest share, approximately 3.3% of the RCC Drugs market in 2024, with a market size of USD 187.40 million, up from USD 134.81 million in 2018. The market is forecasted to reach USD 272.89 million by 2032, growing at a CAGR of 4.8%. Market growth in Africa is relatively modest due to limited access to advanced treatments and constrained healthcare infrastructure. However, gradual improvements in cancer diagnostics, increasing awareness, and the growing presence of international pharmaceutical companies are expected to contribute to steady regional development over the forecast period.
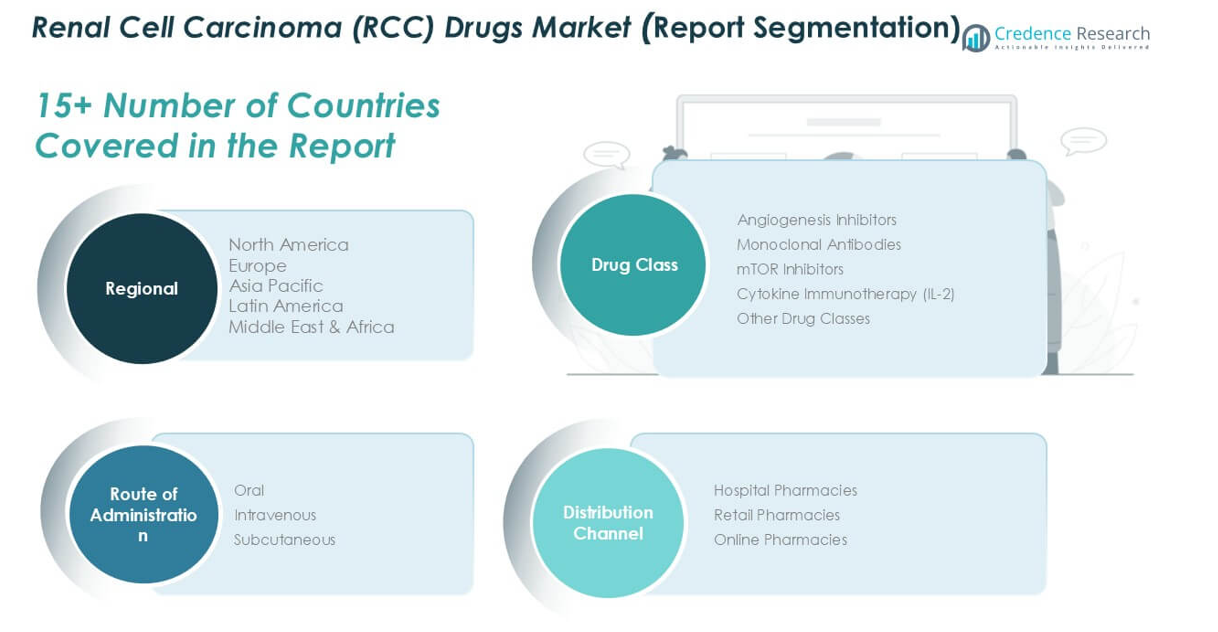
Market Segmentations:
By Drug Class
- Angiogenesis Inhibitors
- Monoclonal Antibodies
- mTOR Inhibitors
- Cytokine Immunotherapy (IL-2)
- Other Drug Classes
By Route of Administration
- Oral
- Intravenous
- Subcutaneous
By Distribution Channel
- Hospital Pharmacies
- Retail Pharmacies
- Online Pharmacies
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
The Renal Cell Carcinoma (RCC) Drugs market is highly competitive, with major pharmaceutical companies actively engaged in expanding their oncology portfolios and developing innovative therapies. Key players such as Active Biotech AB, Amgen, Bayer AG, Cipla Limited, F. Hoffmann-La Roche AG, GSK plc, Novartis AG, Pfizer, Inc., and AstraZeneca PLC dominate the market through extensive product pipelines, strategic collaborations, and frequent regulatory approvals. Companies are focusing on combination therapies, immunotherapies, and targeted drugs to enhance treatment efficacy and address the growing demand for personalized medicine. Competitive intensity is further driven by continuous investments in clinical trials, geographic expansion, and aggressive marketing strategies. Several players are also exploring partnerships to co-develop and commercialize promising drug candidates, particularly in emerging markets. The competitive landscape is shaped by rapid advancements in immuno-oncology, patent expirations, and pricing pressures, compelling companies to innovate and differentiate their offerings to maintain a competitive edge in this evolving market.
Key Player Analysis
- Active Biotech AB
- Amgen
- Bayer AG
- Cipla Limited
- Hoffmann-La Roche AG
- GSK plc
- Novartis AG
- Pfizer, Inc.
- AstraZeneca PLC
Recent Developments
- In October 2023, The Novartis investigationaliptacopan Phase III research showed clinically relevant and statistically significant reductions in proteinuria in patients with IgA nephropathy (IgAN).
- In September 2023, Pfizer added ABRYSVOTM for RSV to its portfolio of respiratory vaccines recommended by the CDC Advisory Committee.
Market Concentration & Characteristics
The Renal Cell Carcinoma (RCC) Drugs Market is moderately concentrated, with a few global pharmaceutical companies holding significant market shares. It is shaped by the dominance of established players with strong oncology portfolios and extensive geographic presence. The market exhibits high barriers to entry due to complex regulatory requirements, long drug approval timelines, and substantial R&D investments. It focuses heavily on innovation, with leading companies advancing targeted therapies and immuno-oncology drugs. Product differentiation, clinical success, and strategic collaborations strongly influence competitive positioning. The market shows a clear preference for oral drugs and combination therapies that improve treatment outcomes. Demand remains driven by rising RCC incidence and expanding healthcare access in both developed and emerging regions. Pricing pressures and patent expirations continue to challenge profitability, encouraging companies to pursue pipeline diversification and cost optimization. The hospital pharmacy segment dominates distribution, reflecting the need for clinical supervision and specialized care in RCC management. The market is responsive to technological advancements and evolving treatment guidelines that prioritize patient-centric therapies with improved efficacy and reduced side effects.
Report Coverage
The research report offers an in-depth analysis based on Drug Class, Route of Administration, Distribution Channel and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The Renal Cell Carcinoma (RCC) Drugs market is expected to experience steady growth driven by increasing RCC incidence worldwide.
- Ongoing advancements in immunotherapy and targeted therapies will continue to shape treatment approaches.
- Combination therapies are anticipated to gain wider acceptance due to their improved clinical outcomes.
- Patient preference for oral RCC drugs is likely to strengthen, promoting the development of more oral formulations.
- North America will maintain its market leadership, supported by advanced healthcare infrastructure and strong drug availability.
- Asia Pacific is projected to be the fastest-growing region due to expanding healthcare access and rising awareness.
- Pharmaceutical companies will intensify their focus on clinical trials and expanding their oncology pipelines.
- Increasing healthcare investments and favorable reimbursement policies will support broader patient access to advanced therapies.
- Growing use of online pharmacies and home care treatments will gradually influence the distribution landscape.
- Pricing pressures and generic competition are expected to challenge market players, encouraging innovation and cost-effective drug development.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Rising Prevalence of Renal Cell Carcinoma
The increasing global incidence of RCC, driven by aging populations, lifestyle factors, and improved diagnostics, is expanding the patient pool and fueling demand for advanced drug therapies.
Advancements in Targeted Therapies and Immunotherapies
Breakthroughs in targeted agents and immuno-oncology, such as immune checkpoint inhibitors and tyrosine kinase inhibitors, have significantly improved survival rates and are rapidly being adopted as standard treatments.
Preference for Oral and Combination Therapies
Patient-centric trends favor oral formulations and combination regimens, which offer greater convenience, better adherence, and superior clinical outcomes, thus accelerating market uptake.
Expanding Healthcare Access and Reimbursement
Broader insurance coverage, rising healthcare expenditure, and government initiatives in both developed and emerging markets are increasing patient access to novel RCC drugs and supporting market growth.
Strong Pharmaceutical Pipeline and Innovation
Major pharmaceutical companies are investing heavily in R&D, clinical trials, and strategic collaborations, leading to a robust pipeline of next-generation RCC therapies and driving competitive market expansion.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Renal Cell Carcinoma (RCC) Drugs Market?
What are the key segments within the Renal Cell Carcinoma (RCC) Drugs Market?
What are some challenges faced by the Renal Cell Carcinoma (RCC) Drugs Market?
Who are the major players in the Renal Cell Carcinoma (RCC) Drugs Market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Drug Class
- 1.2.1 Angiogenesis Inhibitors
- 1.2.2 Monoclonal Antibodies
- 1.2.3 mTOR Inhibitors
- 1.2.4 Cytokine Immunotherapy (IL-2)
- 1.2.5 Other Drug Classes
- 1.3 By Route of Administration
- 1.3.1 Oral
- 1.3.2 Intravenous
- 1.3.3 Subcutaneous
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 5,776.4 million → 2032: USD 9,313.8 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Kidney Cancer/Renal Cell Carcinoma Drugs Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Kidney Cancer/Renal Cell Carcinoma Drugs Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Kidney Cancer/Renal Cell Carcinoma Drugs Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Kidney Cancer/Renal Cell Carcinoma Drugs Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Kidney Cancer/Renal Cell Carcinoma Drugs Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Kidney Cancer/Renal Cell Carcinoma Drugs Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Kidney Cancer/Renal Cell Carcinoma Drugs Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Kidney Cancer/Renal Cell Carcinoma Drugs Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 5,776.4 million → 2032: USD 9,313.8 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Kidney Cancer/Renal Cell Carcinoma Drugs Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Drug Class - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Angiogenesis Inhibitors
- 12.3.7.2 Monoclonal Antibodies
- 12.3.7.3 mTOR Inhibitors
- 12.3.7.4 Cytokine Immunotherapy (IL-2)
- 12.3.7.5 Other Drug Classes
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Route of Administration - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Oral
- 12.4.7.2 Intravenous
- 12.4.7.3 Subcutaneous
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 Segment Growth Comparison
- 12.6 Segment Attractiveness and Priority Matrix
Chapter 13 Global Kidney Cancer/Renal Cell Carcinoma Drugs Geographic Market Outlook, 2024-2032
- 13.1 Regional Market Size and Share, 2024
- 13.2 Regional Market Forecast, 2024-2032
- 13.3 Regional Pricing, Production and Demand Differences
- 13.4 North America
- 13.4.1 United States
- 13.4.2 Canada
- 13.4.3 Mexico
- 13.5 Europe
- 13.5.1 Germany
- 13.5.2 France
- 13.5.3 Italy
- 13.5.4 United Kingdom
- 13.5.5 Spain
- 13.5.6 Poland
- 13.5.7 Russia
- 13.5.8 Netherlands
- 13.5.9 Belgium
- 13.5.10 Sweden
- 13.5.11 Denmark
- 13.5.12 Norway
- 13.5.13 Rest of Europe
- 13.6 Asia Pacific
- 13.6.1 China
- 13.6.2 India
- 13.6.3 Japan
- 13.6.4 South Korea
- 13.6.5 Thailand
- 13.6.6 Indonesia
- 13.6.7 Vietnam
- 13.6.8 Malaysia
- 13.6.9 Australia
- 13.6.10 Rest of Asia Pacific
- 13.7 Latin America
- 13.7.1 Brazil
- 13.7.2 Argentina
- 13.7.3 Colombia
- 13.7.4 Chile
- 13.7.5 Rest of Latin America
- 13.8 Middle East
- 13.8.1 Saudi Arabia
- 13.8.2 United Arab Emirates
- 13.8.3 Turkey
- 13.8.4 Israel
- 13.8.5 Iran
- 13.8.6 Rest of the Middle East
- 13.9 Africa
- 13.9.1 South Africa
- 13.9.2 Egypt
- 13.9.3 Nigeria
- 13.9.4 Morocco
- 13.9.5 Rest of Africa
- 13.10 Regional Investment, Policy and Supply Chain Differences
- 13.11 Regional Competitive Landscape
- 13.12 Geographic Growth Hotspots
Chapter 14 Global Kidney Cancer/Renal Cell Carcinoma Drugs Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2024-2032
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 Global Kidney Cancer/Renal Cell Carcinoma Drugs Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2024
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2024-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Pfizer, Inc.
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 Novartis AG
- 17.4 F. Hoffmann-La Roche AG
- 17.5 AstraZeneca PLC
- 17.6 Bayer AG
- 17.7 Amgen
- 17.8 Active Biotech AB
- 17.9 Cipla Limited
- 17.10 GSK plc
- 17.11 Bristol Myers Squibb
- 17.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

