
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
| Kidney Cancer Drugs Market Size 2024 | USD 6,895.5Million |
| Kidney Cancer Drugs Market, CAGR | 5.6% |
| Kidney Cancer Drugs Market Size 2032 | USD 10,662.94 Million |
Market Overview:
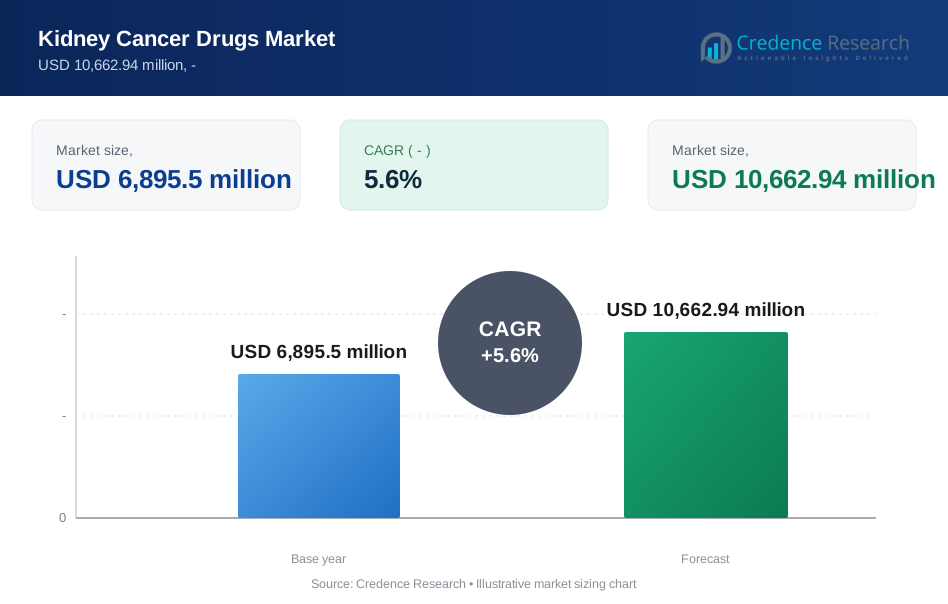
The Kidney Cancer Drugs Market is poised for substantial growth, driven by the increasing prevalence of kidney cancer and advancements in therapeutic options. As of 2024, the global Kidney Cancer Drugs Market is valued at approximately USD 6,895.5 million and is projected to grow at a compound annual growth rate (CAGR) of 5.6% over the forecast period, reaching around USD 10,662.94 million by 2032. This robust growth underscores the ongoing innovation in drug development and the rising demand for effective treatment options for kidney cancer.
Several factors are propelling the market's expansion. The rising incidence of kidney cancer, coupled with an aging population, necessitates the development of new and effective therapeutics. Additionally, the increasing focus on personalized medicine and targeted therapies is driving investment in research and development, leading to the introduction of novel drugs that cater to specific patient profiles.
Regionally, North America dominates the Kidney Cancer Drugs Market, attributed to a strong healthcare infrastructure, high levels of investment in R&D, and a growing awareness of cancer treatment options. Europe follows, supported by similar trends and an emphasis on innovative therapies. Meanwhile, the Asia-Pacific region is expected to experience significant growth during the forecast period, fueled by rising healthcare expenditures, increasing awareness of kidney cancer treatments, and expanding access to advanced healthcare services. Emerging markets in this region, particularly China and India, present considerable growth opportunities, driven by their large patient populations and ongoing improvements in healthcare infrastructure.
Market Drivers:
Increasing Prevalence of Kidney Cancer:
The rising incidence of kidney cancer is a significant driver of the Kidney Cancer Drugs Market. According to the World Health Organization (WHO), kidney cancer cases are projected to rise by approximately 2% annually, reflecting an urgent need for effective treatment options. The International Agency for Research on Cancer (IARC) reported that kidney cancer accounted for about 3.8% of all new cancer cases worldwide in 2020. This growing prevalence underscores the importance of ongoing research and development of innovative therapies to meet the needs of an expanding patient population. For instance, data from the American Cancer Society indicates that in the United States alone, the estimated new cases of kidney cancer were about 76,000 in 2021. The Centers for Disease Control and Prevention (CDC) also highlights that the mortality rate for kidney cancer has been gradually increasing, emphasizing the necessity for effective treatment solutions in light of this growing patient demand.
Advancements in Research and Development:
Ongoing advancements in medical research and technology are pivotal to the evolution of the Kidney Cancer Drugs Market. Increased investment in R&D, driven by both government and private sectors, is leading to the development of targeted therapies that are more effective and have fewer side effects than traditional treatments. The National Institutes of Health (NIH) reported a 5% increase in funding for cancer research in 2022, highlighting the commitment to tackling diseases like kidney cancer. Furthermore, collaborations between pharmaceutical companies and academic institutions are fostering innovation. For instance, major pharmaceutical firms like Pfizer and Bristol-Myers Squibb have made significant strides in developing novel immunotherapies for kidney cancer, reflecting a trend toward personalized medicine. The FDA has also been proactive in facilitating the approval of these new therapies, which encourages further investments in R&D and aids in the rapid development of innovative treatment options.
Growing Focus on Personalized Medicine:
The shift toward personalized medicine is transforming the treatment landscape for kidney cancer. With advancements in genomics and biomarker identification, healthcare providers can now tailor therapies to individual patients, resulting in improved efficacy and reduced adverse effects. The Food and Drug Administration (FDA) has recognized the importance of personalized medicine, approving several targeted therapies based on specific genetic markers associated with kidney cancer. For instance, the approval of drugs like nivolumab and cabozantinib reflects this trend. According to the Personalized Medicine Coalition, approximately 25% of all newly approved drugs in recent years have been personalized therapies, indicating a robust growth trajectory in this area. Additionally, research funded by the National Cancer Institute shows that personalized approaches can lead to better treatment responses, further driving demand for new, targeted drugs in the market.
Increasing Government Initiatives and Funding:
Government initiatives play a crucial role in shaping the Kidney Cancer Drugs Market. Various national health agencies, including the Centers for Disease Control and Prevention (CDC) and the National Cancer Institute (NCI), are actively promoting awareness and funding research related to kidney cancer. For instance, the NCI has allocated significant funding for kidney cancer research, demonstrating the government's commitment to addressing this public health issue. According to the World Bank, investments in healthcare infrastructure and cancer treatment have risen by 7% annually in developing regions, which helps expand access to necessary treatments and fosters market growth. Additionally, initiatives from the CDC aimed at improving early detection and prevention of kidney cancer are expected to enhance patient outcomes, further increasing demand for effective kidney cancer drugs. The Kidney Cancer Drugs Market is driven by a combination of factors, including the increasing prevalence of kidney cancer, advancements in research and development, the growing focus on personalized medicine, and supportive government initiatives. As these drivers continue to influence the market landscape, stakeholders are likely to witness a significant expansion in the availability and effectiveness of kidney cancer treatments, ultimately improving patient care and outcomes.
Market Trends:
Emergence of Targeted Therapies:
The trend towards targeted therapies is gaining momentum in the Kidney Cancer Drugs Market. As researchers continue to uncover specific genetic mutations and pathways involved in kidney cancer, pharmaceutical companies are increasingly developing drugs that specifically target these mechanisms. The National Cancer Institute (NCI) has identified several genetic markers that play a role in kidney cancer, leading to the development of personalized treatment options. This focus on precision medicine allows for more effective treatments tailored to individual patients, resulting in improved outcomes. Major companies, such as Novartis and Merck, are investing heavily in the research and development of targeted therapies. Their collaborations with academic institutions have led to the advancement of innovative drug candidates that address specific tumor profiles. For instance, the FDA has approved targeted therapies like axitinib and tivozanib, showcasing the regulatory support for this trend. Additionally, the American Society of Clinical Oncology (ASCO) has reported that targeted therapies can significantly improve survival rates, with some studies indicating a 30% increase in progression-free survival for patients with advanced kidney cancer who receive these treatments, thereby driving further interest and investment in this area.
Increasing Use of Immunotherapy:
Immunotherapy is rapidly becoming a cornerstone of treatment for kidney cancer, reflecting a broader trend in oncology. This approach harnesses the body’s immune system to fight cancer more effectively. The approval of immune checkpoint inhibitors, such as nivolumab and pembrolizumab, has transformed the treatment landscape for kidney cancer. According to the World Health Organization (WHO), clinical trials have shown that immunotherapy can lead to response rates of over 40% in patients with advanced disease, underscoring its efficacy. Research funded by the National Institutes of Health (NIH) supports the efficacy of immunotherapies, revealing that they can offer durable responses and improve overall survival in a significant percentage of patients. For instance, recent data from clinical trials indicate that nivolumab can extend survival by an average of 5 months compared to traditional therapies. The growing acceptance of immunotherapy is also being reflected in treatment guidelines issued by prominent organizations such as the National Comprehensive Cancer Network (NCCN). As a result, pharmaceutical companies are increasingly focusing on developing next-generation immunotherapeutics that aim to enhance efficacy and minimize side effects. Ongoing clinical trials are exploring combination therapies, such as pairing nivolumab with targeted treatments, aiming to maximize patient response rates. These guidelines now recommend immunotherapy as a first-line treatment for certain stages of kidney cancer, reinforcing its role in contemporary treatment paradigms. The support from leading health authorities, along with promising clinical outcomes showing up to a 60% overall response rate in some cases, has fueled interest from both investors and researchers, resulting in an influx of funding aimed at advancing immunotherapy options.
Market Challenge Analysis:
High Cost of Treatment:
One of the primary challenges facing the Kidney Cancer Drugs Market is the high cost of treatment associated with advanced therapies. The development and production of targeted therapies and immunotherapies often require significant financial investment, leading to elevated prices for patients. Many of these innovative drugs, while effective, can be prohibitively expensive for individuals without adequate insurance coverage. According to the National Cancer Institute (NCI), the average annual cost of kidney cancer treatment can exceed several tens of thousands of dollars, which poses a financial burden for many patients and their families. This high cost can lead to disparities in access to treatment, as patients in lower socioeconomic groups may be unable to afford these therapies, resulting in suboptimal health outcomes and potentially higher mortality rates.
Furthermore, the complexity of treatment regimens often requires comprehensive follow-up care and monitoring, adding to the overall financial strain. Health insurance companies may also impose strict guidelines on coverage for these treatments, which can create barriers to access. The impact of high treatment costs is further exacerbated by the rising prevalence of kidney cancer, leading to increased demand for expensive therapies. As more patients seek advanced treatments, the healthcare system may struggle to accommodate these needs, resulting in a backlog of patients who cannot access timely care. Addressing this challenge requires concerted efforts from policymakers, healthcare providers, and pharmaceutical companies to ensure equitable access to effective treatments for all patients, regardless of their financial situation.
Limited Awareness and Education:
Another significant challenge in the Kidney Cancer Drugs Market is the limited awareness and education surrounding kidney cancer among both healthcare professionals and patients. Despite advances in research and treatment options, many individuals remain uninformed about the symptoms and risk factors associated with kidney cancer. According to a survey conducted by the American Urological Association, nearly 50% of respondents were unable to identify common symptoms of kidney cancer, leading to delays in diagnosis and treatment. This lack of awareness can hinder early detection, which is crucial for improving patient outcomes. When kidney cancer is diagnosed at a later stage, treatment options become limited, and the chances of successful outcomes diminish.
Moreover, healthcare providers may also lack sufficient training in the latest advancements in kidney cancer treatment, leading to suboptimal care. The rapid pace of research and development in this field means that clinicians must continuously update their knowledge to provide the best care for their patients. Inadequate education on the efficacy of new therapies can result in a reliance on traditional treatment methods, which may not be the most effective for certain patient populations. Addressing this challenge requires targeted educational initiatives aimed at both patients and healthcare professionals. Increasing awareness through community outreach, professional training programs, and accessible educational resources can help improve understanding of kidney cancer, enhance early detection rates, and ultimately lead to better treatment outcomes for patients.
Market Segmentation Analysis:
By Type
The Kidney Cancer Drugs Market is segmented by type into targeted therapies, immunotherapies, and traditional chemotherapies. Targeted therapies are gaining prominence due to their ability to specifically attack cancer cells while sparing healthy tissue, leading to fewer side effects. Drugs such as cabozantinib and axitinib are examples of targeted therapies that have shown significant efficacy in treating advanced kidney cancer. Immunotherapies, which harness the body’s immune system to combat cancer, are also rapidly emerging as a key segment. Treatments like nivolumab and pembrolizumab have demonstrated improved survival rates for patients with advanced disease. Traditional chemotherapies, while still in use, are gradually being overshadowed by these more advanced therapeutic options, though they continue to play a role in treatment protocols, particularly in earlier-stage cancers.
By Technology
In terms of technology, the Kidney Cancer Drugs Market can be classified into small molecule drugs, biologics, and combination therapies. Small molecule drugs, which typically target specific molecular pathways involved in cancer growth, remain a cornerstone of treatment, providing effective options for many patients. Biologics, including monoclonal antibodies and immune checkpoint inhibitors, are increasingly important as they represent a shift towards more personalized medicine approaches. Combination therapies, which involve using multiple treatment modalities-such as pairing targeted therapies with immunotherapy-are gaining traction as clinical studies demonstrate their potential to enhance efficacy and overcome resistance mechanisms in cancer cells. This technological diversity allows for tailored treatment strategies that can be customized to individual patient profiles and cancer characteristics.
By End-User
The Kidney Cancer Drugs Market is segmented by end-user into hospitals, clinics, and outpatient settings. Hospitals are the primary end-users, as they provide comprehensive cancer care and are equipped with advanced facilities for diagnosis and treatment. Many hospitals have specialized oncology departments that focus on kidney cancer, facilitating access to innovative therapies and clinical trials. Clinics also play a significant role, particularly in the management of outpatient care, where patients may receive ongoing treatment and monitoring. Outpatient settings are increasingly important as the healthcare system shifts towards more patient-centric models of care, emphasizing convenience and accessibility. This segmentation reflects the evolving landscape of cancer treatment, where different healthcare environments cater to the diverse needs of patients at various stages of their treatment journey.
Segmentation:
Based on Product Type:
- Targeted Therapies
- Immunotherapies
- Traditional Chemotherapies
Based on Technology:
- Small Molecule Drugs
- Biologics
- Combination Therapies
Based on End-User:
- Hospitals
- Clinics
- Outpatient Settings
Based on Region:
- North America
- United States
- Canada
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Asia-Pacific
- China
- India
- Japan
- Australia
- South Korea
- Latin America
- Brazil
- Mexico
- Argentina
- Middle East and Africa
- South Africa
- UAE
- Saudi Arabia
- Egypt
Regional Analysis:
North America (45% Market Share)
North America holds the largest share of the Kidney Cancer Drugs Market, accounting for approximately 45% of the total market revenue. This dominance is primarily driven by a strong healthcare infrastructure, significant investment in research and development, and a high prevalence of kidney cancer. The United States, in particular, benefits from advanced medical technologies and a well-established pharmaceutical industry, which facilitates the rapid development and approval of innovative treatments.
Government support through agencies like the National Institutes of Health (NIH) and the Food and Drug Administration (FDA) plays a crucial role in promoting kidney cancer research. For instance, funding from the NIH for cancer research has increased significantly in recent years, enhancing the capabilities of healthcare institutions to conduct clinical trials and develop novel therapies. Additionally, a robust network of healthcare providers ensures that patients have access to cutting-edge treatment options, further solidifying North America’s position in the market. However, challenges such as high treatment costs and insurance coverage limitations may affect patient access to these advanced therapies, creating disparities in treatment outcomes.
Europe (30% Market Share)
Europe is the second-largest region in the Kidney Cancer Drugs Market, holding approximately 30% market share. The region benefits from a combination of advanced healthcare systems, ongoing research initiatives, and a growing emphasis on innovative cancer treatments. Countries such as Germany, the United Kingdom, and France are at the forefront of kidney cancer research, with numerous clinical trials focusing on the development of targeted therapies and immunotherapies.
European health authorities, including the European Medicines Agency (EMA), actively support the approval of new drugs and the implementation of treatment guidelines, which fosters an environment conducive to innovation. For example, recent initiatives aimed at improving access to novel therapies have led to increased collaboration between pharmaceutical companies and healthcare providers. However, regional disparities in healthcare access and differences in reimbursement policies can pose challenges to market growth. Some countries may face barriers in the adoption of newer therapies due to varying levels of government funding and healthcare expenditure. Despite these challenges, the focus on personalized medicine and the integration of innovative therapies into standard treatment regimens are expected to drive market growth in Europe.
Asia-Pacific (20% Market Share)
The Asia-Pacific region is rapidly emerging as a significant player in the Kidney Cancer Drugs Market, holding approximately 20% market share. The increasing incidence of kidney cancer, driven by factors such as urbanization, changing lifestyles, and an aging population, has led to a growing demand for effective treatment options. Countries like China and India are witnessing substantial investments in healthcare infrastructure and pharmaceutical research, contributing to market expansion.
Government initiatives aimed at improving cancer care and increasing awareness about kidney cancer are also pivotal in shaping the market landscape. For instance, the Chinese government has introduced policies to enhance access to cancer treatments, thereby promoting early diagnosis and intervention. Additionally, collaborations between local pharmaceutical companies and international firms are fostering the development of innovative therapies tailored to the unique needs of patients in the region. However, challenges such as limited access to healthcare facilities in rural areas and varying levels of healthcare quality across different countries may impact market growth. Efforts to address these disparities through targeted healthcare programs and increased investment in cancer research will be essential for the continued expansion of the kidney cancer drugs market in the Asia-Pacific region.
Key Player Analysis:
- Pfizer Inc.
- Novartis AG
- Bristol-Myers Squibb Company
- Roche Holding AG (Genentech, Inc.)
- Bayer AG
- Exelixis, Inc.
- Merck & Co., Inc.
- Eisai Co., Ltd.
- Aveo Pharmaceuticals
- AstraZeneca PLC
- Ipsen Biopharmaceuticals, Inc.
- GlaxoSmithKline plc
- Abbott Laboratories Source
- Amgen Inc.
- Calithera Biosciences, Inc.
- Active Biotech
- Immatics Biotechnologies GmbH
Competitive Analysis:
The competitive landscape of the Kidney Cancer Drugs Market is characterized by a mix of established pharmaceutical giants and emerging biotech firms, each vying for market share through innovation and strategic partnerships. Major players such as Bristol-Myers Squibb, Merck, and Novartis dominate the market, leveraging their extensive R&D capabilities to develop advanced therapies like immunotherapies and targeted treatments. For instance, Bristol-Myers Squibb's nivolumab has gained significant traction due to its efficacy in treating advanced kidney cancer, while Merck's pembrolizumab has also become a leading option for patients. Emerging companies are focusing on niche areas within kidney cancer treatment, often exploring unique therapeutic targets or developing combination therapies that enhance treatment efficacy. Collaborations between pharmaceutical companies and academic institutions are fostering innovation, leading to breakthroughs that could reshape the treatment landscape. Additionally, the regulatory environment plays a crucial role, as timely approvals from authorities like the FDA and EMA can provide a competitive edge. While the high cost of treatment presents challenges, it also creates opportunities for companies that can develop more affordable and accessible solutions. Overall, the market remains dynamic, with ongoing clinical trials and research initiatives promising to introduce new players and therapies, intensifying competition in the coming years. The ability to adapt to changing patient needs and regulatory frameworks will be key for companies aiming to establish a strong foothold in this evolving market.
Recent Developments:
In December 2022, Exelixis, Inc., a biotechnology company specializing in oncology, announced the launch of the STELLAR-304 trial. This pivotal Phase 3 study aims to evaluate the efficacy of zanzalintinib combined with nivolumab compared to sunitinib in patients with advanced non-clear cell kidney cancer.
In October 2022, Health Canada approved KEYTRUDA (pembrolizumab) as a standalone treatment for adults with renal cell carcinoma (RCC) in the adjuvant setting. This approval targets individuals at intermediate-high or high risk of recurrence following nephrectomy or nephrectomy with resection of metastatic lesions.
In February 2022, Eisai Co., Ltd., a human health care company, and Merck & Co., Inc., a global health care company based in Rahway, NJ, announced that the Japanese Ministry of Health, Labour and Welfare (MHLW) approved their combination therapy of LENVIMA and KEYTRUDA. This approval applies to the treatment of radically unresectable or metastatic renal cell carcinoma, the most common form of kidney cancer.
Market Concentration & Characteristics:
The Kidney Cancer Drugs Market exhibits a moderate level of concentration, characterized by a few dominant players alongside a growing number of smaller biotech firms. The market is primarily driven by major pharmaceutical companies such as Bristol-Myers Squibb, Merck, Novartis, and Pfizer, which possess extensive resources for research and development, allowing them to innovate and launch new therapies effectively. These companies have established strong brand recognition and a broad portfolio of approved treatments, contributing to their market leadership. However, the entry of smaller biotech firms is notable, as they often focus on niche segments or novel therapeutic approaches, including personalized medicine and combination therapies. This dynamic creates a competitive environment where established firms may seek collaborations or acquisitions to enhance their product offerings and maintain their market positions. The market is also characterized by rapid technological advancements and evolving treatment paradigms, necessitating continuous investment in R&D. Regulatory factors play a significant role, as successful navigation of the approval process can significantly impact market share. Furthermore, the high cost of kidney cancer therapies prompts ongoing discussions about pricing and accessibility, influencing market dynamics. Overall, the blend of established players and innovative newcomers fosters a competitive landscape that is continuously evolving, driven by patient needs and advancements in cancer treatment.
Report Coverage:
This report provides a comprehensive analysis of the Kidney Cancer Drugs Market, focusing on key trends, drivers, challenges, and competitive dynamics that shape the industry. It covers market segmentation based on product type, technology, end-user, and regional dynamics, offering insights into how these factors influence market growth and development. The report includes an in-depth examination of major players in the market, highlighting their strategic initiatives, product offerings, and market shares. Additionally, it analyzes the impact of regulatory frameworks and healthcare policies on the market landscape, emphasizing the role of government agencies and funding in promoting research and development. Furthermore, the report addresses the evolving treatment paradigms, including the increasing emphasis on personalized medicine and immunotherapy, which are revolutionizing kidney cancer care. It also explores market challenges, such as high treatment costs and limited patient awareness, which may hinder growth. The geographical scope includes North America, Europe, Asia-Pacific, Latin America, and the Middle East and Africa, providing a global perspective on market opportunities and risks. By synthesizing qualitative and quantitative data, this report aims to equip stakeholders-including pharmaceutical companies, healthcare providers, and investors-with actionable insights to navigate the complex landscape of the Kidney Cancer Drugs Market and identify growth opportunities.
Future Outlook:
- The Kidney Cancer Drugs Market will continue to expand due to rising global awareness of kidney cancer and its treatment options.
- Increased funding for research and development will lead to more innovative therapies tailored for diverse patient profiles.
- The integration of advanced technologies, such as artificial intelligence and machine learning, will enhance drug discovery processes and improve patient outcomes.
- Partnerships between pharmaceutical companies and research institutions will drive the development of targeted therapies.
- Regulatory agencies are expected to streamline approval processes for new kidney cancer drugs, accelerating time-to-market.
- The demand for personalized medicine will shape the future landscape of treatment options, providing patients with more effective therapies.
- Expanding healthcare access in emerging markets will create significant opportunities for growth in the kidney cancer therapeutics segment.
- Increased focus on patient education and support programs will improve treatment adherence and outcomes.
- Collaborative initiatives among stakeholders will foster innovation and address unmet needs in kidney cancer care.
- Ongoing clinical trials and studies will provide critical insights into the efficacy of new drugs, further shaping treatment paradigms for kidney cancer.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Increasing Prevalence of Kidney Cancer
The global rise in kidney cancer incidence, driven by aging populations and lifestyle factors, is expanding the patient pool and fueling demand for effective drug therapies.
Advancements in Research and Development
Ongoing investment in R&D by both public and private sectors is leading to the introduction of innovative targeted therapies and immunotherapies, improving treatment outcomes and expanding market offerings.
Growing Focus on Personalized Medicine
The shift toward personalized medicine, enabled by advances in genomics and biomarker identification, allows for tailored therapies that improve efficacy and reduce side effects, increasing adoption of new kidney cancer drugs.
Government Initiatives and Funding
Supportive government policies, increased funding for cancer research, and initiatives to improve early detection and treatment access are accelerating the development and uptake of kidney cancer drugs, especially in emerging markets.
Emergence of Targeted and Immunotherapies
The development and regulatory approval of targeted therapies and immunotherapies, which offer improved survival rates and better tolerability, are transforming the treatment landscape and driving market growth.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size of the Kidney Cancer Drugs Market?
What is the projected growth rate for the Kidney Cancer Drugs Market?
What factors are driving the growth of the Kidney Cancer Drugs Market?
Which regions are expected to lead in the Kidney Cancer Drugs Market?
How is the focus on personalized medicine impacting the market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By End-User
- 1.2.1 Hospitals
- 1.2.2 Clinics
- 1.2.3 Outpatient Settings
- 1.3 By Technology
- 1.3.1 Small Molecule Drugs
- 1.3.2 Biologics
- 1.3.3 Combination Therapies
- 1.4 By Product Type
- 1.4.1 Targeted Therapies
- 1.4.2 Immunotherapies
- 1.4.3 Traditional Chemotherapies
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2032: USD 6,895.5 million → Forecast year: USD 10,662.94 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2032
- 3.3 Forecast Market Size
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Kidney Cancer Drugs Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Kidney Cancer Drugs Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Kidney Cancer Drugs Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Kidney Cancer Drugs Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Kidney Cancer Drugs Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Kidney Cancer Drugs Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Kidney Cancer Drugs Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Kidney Cancer Drugs Market Outlook
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2032: USD 6,895.5 million → Forecast year: USD 10,662.94 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2032
- 11.2 Market Forecast
- 11.2.1 Revenue Forecast
- 11.2.2 Volume Forecast
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Kidney Cancer Drugs Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2032
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By End-User - Market Size and Forecast
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast
- 12.3.4 Volume Forecast
- 12.3.5 Base-Year Market Share, 2032
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Hospitals
- 12.3.7.2 Clinics
- 12.3.7.3 Outpatient Settings
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Technology - Market Size and Forecast
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast
- 12.4.4 Volume Forecast
- 12.4.5 Base-Year Market Share, 2032
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Small Molecule Drugs
- 12.4.7.2 Biologics
- 12.4.7.3 Combination Therapies
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Product Type - Market Size and Forecast
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast
- 12.5.4 Volume Forecast
- 12.5.5 Base-Year Market Share, 2032
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Targeted Therapies
- 12.5.7.2 Immunotherapies
- 12.5.7.3 Traditional Chemotherapies
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global Kidney Cancer Drugs End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Kidney Cancer Drugs Geographic Market Outlook
- 14.1 Regional Market Size and Share, 2032
- 14.2 Regional Market Forecast
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Kidney Cancer Drugs Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Kidney Cancer Drugs Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2032
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Pfizer Inc.
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Novartis AG
- 18.4 Bristol-Myers Squibb Company
- 18.5 Roche Holding AG
- 18.6 Bayer AG
- 18.7 Exelixis, Inc.
- 18.8 Merck & Co., Inc.
- 18.9 Eisai Co., Ltd.
- 18.10 AstraZeneca PLC
- 18.11 GlaxoSmithKline plc
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

