
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
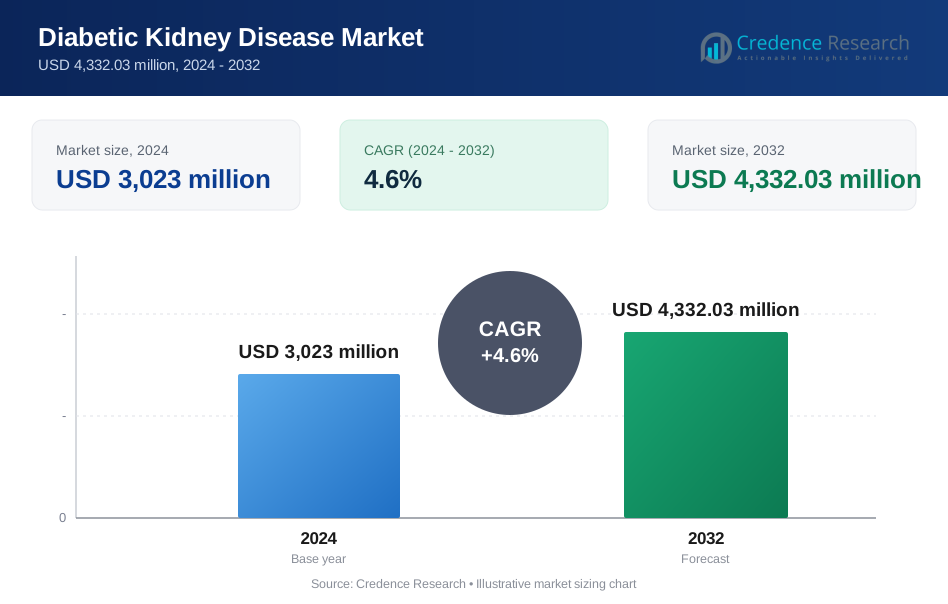
| Diabetic Kidney Disease Market Size 2024 | USD 3023 Million |
| Diabetic Kidney Disease Market , CAGR | 4.6% |
| Diabetic Kidney Disease Market Size 2032 | USD 4332.03 Million |
Market Overview:
The Diabetic Kidney Disease Market is projected to grow from USD 3023 million in 2024 to an estimated USD 4332.03 million by 2032, with a compound annual growth rate (CAGR) of 4.6% from 2024 to 2032.
Several key factors drive the diabetic kidney disease market. One of the primary drivers is the increasing prevalence of diabetes worldwide, particularly due to lifestyle factors like poor diet and lack of physical activity, which have led to rising cases of type 2 diabetes. As diabetic kidney disease is one of the most common and severe complications of diabetes, the need for effective treatments and preventive measures is growing rapidly. Additionally, advancements in diagnostic technology are enabling earlier detection of diabetic kidney disease, allowing for timely intervention and management. This trend is further supported by increased investment in research and development by pharmaceutical companies, resulting in the development of new drug therapies and treatment options specifically targeting diabetic kidney disease. Growing awareness of diabetes-related complications among patients and healthcare providers is also driving market demand, as more individuals seek regular screenings and treatments for early-stage kidney disease.
The diabetic kidney disease market has a diverse regional distribution, with North America holding a significant share due to high diabetes prevalence and advanced healthcare infrastructure. The United States, in particular, is a major contributor, driven by high diagnosis rates, comprehensive insurance coverage, and access to innovative treatment options. Europe follows closely, with countries such as Germany, France, and the United Kingdom experiencing steady demand due to an aging population and well-established healthcare systems. In the Asia-Pacific region, the market is expected to witness the fastest growth, especially in countries like China and India, where diabetes rates are rapidly increasing. This growth is bolstered by rising healthcare expenditure, improved access to medical services, and greater public awareness of diabetic complications. Latin America and the Middle East & Africa are anticipated to see moderate growth, largely driven by improved healthcare access and increased diabetes awareness, although limited by economic constraints in certain areas.
Market Drivers:
Rising Global Diabetes Prevalence:
The increasing prevalence of diabetes worldwide is one of the primary drivers of the diabetic kidney disease market. Factors such as sedentary lifestyles, unhealthy dietary habits, and an aging population have contributed to a rapid rise in diabetes cases, particularly type 2 diabetes, which is most closely linked with diabetic kidney disease. According to the International Diabetes Federation, the global diabetic population is expected to exceed 700 million by 2045, underscoring the critical need for effective treatments to manage diabetes and its complications. Diabetic kidney disease, also known as diabetic nephropathy, affects nearly one-third of all diabetes patients, creating a substantial demand for therapeutic solutions designed to manage and prevent disease progression.
Advancements in Diagnostic Technologies:
The development and adoption of advanced diagnostic technologies are playing a crucial role in driving the diabetic kidney disease market. Traditional methods often detect diabetic kidney disease only in later stages; however, new diagnostic tools and biomarkers are enabling earlier and more accurate detection. Technologies such as microalbuminuria tests, imaging techniques, and genetic profiling are becoming more widely available, allowing for the identification of diabetic kidney disease in its initial stages. Early diagnosis is critical as it allows for timely intervention, which can significantly delay disease progression and improve patient outcomes. These advancements have resulted in increased demand for diagnostic services and products, as healthcare providers and patients alike are prioritizing early detection and management.
Increasing Focus on Research and Development:
Rising investment in research and development by pharmaceutical and biotech companies is another key driver of the diabetic kidney disease market. Companies are focused on developing innovative drug therapies that target the underlying mechanisms of diabetic kidney disease. These include treatments designed to reduce proteinuria, inflammation, and oxidative stress, which are key factors contributing to disease progression. For instance, the FLOW trial enrolled 3,533 participants with a median follow-up period of 3.4 years to evaluate the efficacy of semaglutide in reducing major kidney disease events. The market is also seeing growth in biologic drugs and personalized medicine approaches, which offer more targeted and effective solutions for patients with diabetic kidney disease. Additionally, the FDA has been approving new drugs specifically for diabetic kidney disease, reflecting the growing recognition of this condition as a significant health concern. This emphasis on research and development is expected to yield a variety of new treatment options, enhancing the market’s growth potential.
Growing Awareness and Preventative Healthcare Initiatives:
Increased awareness of diabetic complications, including kidney disease, is driving market growth as more patients and healthcare providers emphasize preventative care and early intervention. Governments, non-profit organizations, and healthcare providers are implementing programs aimed at educating the public about the risks of diabetic kidney disease and promoting regular screenings for at-risk individuals. Campaigns such as World Kidney Day and Diabetes Awareness Month have been instrumental in raising awareness of diabetic complications and encouraging individuals with diabetes to seek proactive management. For example, the American Diabetes Association’s DKD Prevention Model highlights that more than 37 million people in the United States are affected by diabetes, with 30-40% of them developing diabetic kidney disease. Additionally, as healthcare systems shift toward value-based care, there is a stronger focus on managing chronic conditions effectively to reduce long-term healthcare costs. This focus on prevention and education is fostering greater demand for diagnostic tools, therapies, and ongoing management solutions, supporting the expansion of the diabetic kidney disease market.
Market Trends:
Shift Towards Personalized Medicine and Targeted Therapies:
A prominent trend in the diabetic kidney disease market is the growing focus on personalized medicine and targeted therapies. With advancements in genetics and molecular biology, researchers and pharmaceutical companies are developing treatments that address the underlying mechanisms of diabetic kidney disease in a more individualized manner. This approach involves tailoring treatment plans to patients based on genetic profiles, disease stage, and other individual characteristics, which can lead to more effective outcomes and fewer side effects. For example, a study identified and replicated four plasma proteins associated with diabetic kidney disease: CBLN1, COL6A2, ITIH3, and TGFBI. Targeted therapies are designed to address specific pathways involved in disease progression, such as inflammation and fibrosis. These innovative treatments reflect a significant shift from traditional broad-spectrum therapies to more specialized solutions, allowing for improved patient care and better disease management.
Increased Adoption of Non-Invasive Diagnostic Tools:
The diabetic kidney disease market is also seeing an increase in the adoption of non-invasive diagnostic tools. New technologies, such as advanced imaging techniques and biomarker-based tests, allow healthcare providers to detect early signs of kidney damage without the need for invasive procedures. For example, microalbuminuria tests, which measure protein levels in urine, have become a standard tool for assessing kidney function in diabetic patients. Additionally, emerging blood tests and genetic markers can identify patients at high risk for diabetic kidney disease before symptoms become evident. This trend aligns with the broader movement towards preventative healthcare, as early diagnosis enables timely intervention and potentially slows disease progression. The demand for non-invasive diagnostics is expected to continue rising as healthcare providers increasingly prioritize patient comfort and early detection.
Emphasis on Lifestyle Interventions and Preventative Care:
Alongside medical treatments, there is an increasing emphasis on lifestyle interventions and preventative care in managing diabetic kidney disease. Healthcare providers are advocating for lifestyle changes, such as improved diet, regular exercise, and better glucose management, as these can significantly impact disease progression. Additionally, many healthcare systems and organizations are investing in patient education programs to raise awareness about diabetic kidney disease and its risk factors. The trend towards integrating lifestyle interventions with pharmacological treatments highlights a holistic approach to managing the condition, which is seen as essential to reducing the long-term healthcare costs associated with diabetic kidney disease. This proactive approach aligns with the global shift towards value-based healthcare, where the focus is on improving patient outcomes and preventing complications rather than only treating symptoms.
Rise in Collaborative Research and Partnerships:
The diabetic kidney disease market is also experiencing a surge in collaborative research efforts and partnerships. Pharmaceutical companies, research institutions, and healthcare providers are increasingly joining forces to accelerate the development of new treatments and improve patient outcomes. For example, the Kidney Health Research Collaborative (KHRC) at the University of California San Francisco and the San Francisco Veterans Affairs Medical Center encompasses a group of leading scientists from multiple disciplines working to improve kidney health worldwide. Collaborations often focus on clinical trials, sharing of data and resources, and jointly conducting research to better understand the complexities of diabetic kidney disease. For instance, the Bilateral Collaborative Research Call for Proposals 2024 by Inserm and ICMR aims to fund up to two joint research projects with a maximum ceiling of Rs. 2.0 crore for each project over three years. These partnerships are essential for advancing drug development, as they allow organizations to pool expertise and resources, ultimately leading to more innovative solutions. Furthermore, partnerships with government agencies and non-profit organizations are helping to drive awareness and funding for diabetic kidney disease research, providing a solid foundation for continued progress in the market. This collaborative trend is expected to shape the market’s landscape in the coming years, fostering innovation and enhancing the quality of care for patients.
Market Restraints and Challenges:
High Treatment Costs and Limited Accessibility:
One of the primary restraints in the diabetic kidney disease market is the high cost associated with treatment, especially for advanced therapies and novel biologics. These treatments can be expensive, and they are often not fully covered by insurance, posing a financial burden on patients. This is particularly challenging in low- and middle-income regions, where access to specialized care and advanced medications is limited. Even in developed regions, the high cost of newer drugs can limit patient accessibility, restricting the market’s overall growth. Additionally, as diabetic kidney disease often requires ongoing and long-term management, the cumulative treatment costs can be prohibitive, leading some patients to discontinue treatment or seek alternative, less effective options.
Regulatory Challenges and Approval Delays:
Regulatory challenges present another significant barrier to the growth of the diabetic kidney disease market. Drug development and approval processes are often lengthy and costly, as regulatory agencies such as the U.S. Food and Drug Administration (FDA) and the European Medicines Agency (EMA) enforce stringent requirements to ensure the safety and efficacy of new treatments. These regulatory hurdles can delay the entry of innovative therapies into the market, slowing down the pace of development and limiting treatment options available to patients. Furthermore, the regulatory landscape for diabetic kidney disease treatments is continually evolving, making it challenging for pharmaceutical companies to keep up with changing guidelines and compliance requirements. This dynamic can increase costs and deter smaller companies from entering the market.
Lack of Awareness and Early Diagnosis:
Despite the growing prevalence of diabetic kidney disease, many patients remain unaware of the condition or its early symptoms, leading to delayed diagnosis and treatment. Early-stage diabetic kidney disease is often asymptomatic, and patients may not recognize the need for regular screenings until the disease has progressed to a more advanced stage. Additionally, awareness campaigns targeting diabetic kidney disease are limited compared to other chronic conditions, resulting in a lack of public knowledge. This challenge is particularly pronounced in low-resource settings where healthcare infrastructure and preventive screening programs are underdeveloped. Delayed diagnosis reduces the effectiveness of treatment options, as interventions are most successful in the early stages of the disease. This lack of awareness and proactive diagnosis ultimately limits the market’s potential by reducing the number of individuals seeking early treatment for diabetic kidney disease.
Market Segmentation Analysis:
By Type, the market is divided into Type 1 and Type 2 diabetes segments. Type 2 diabetes accounts for a larger share, as it is the most prevalent form, particularly among older adults. Type 2 diabetes is closely linked to lifestyle factors such as diet and physical inactivity, which contribute to a growing diabetic population worldwide. Type 1 diabetes, while less common, also represents a significant portion of the market due to the increased risk of kidney complications among this population, driving demand for long-term management solutions.
By Treatment, the market includes angiotensin receptor blockers (ARBs), angiotensin-converting enzyme (ACE) inhibitors, antioxidant inflammation modulators, calcium channel blockers, and other treatment options. ARBs and ACE inhibitors are widely prescribed, as they effectively reduce blood pressure and proteinuria, which are critical factors in managing diabetic kidney disease. Antioxidant inflammation modulators and calcium channel blockers are gaining attention as alternative or adjunctive therapies, particularly as research continues to uncover the complex mechanisms underlying diabetic kidney disease progression.
By Distribution Channel, the market is segmented into online pharmacies, hospital pharmacies, and retail pharmacies. Hospital pharmacies hold a significant share due to the high number of patients receiving treatment in medical facilities, especially for advanced diabetic kidney disease. Retail pharmacies are also essential, providing convenient access to medications for ongoing treatment. Online pharmacies are rapidly growing, driven by the increasing preference for convenient and contactless shopping, which allows patients to order medications and receive them directly at home. This trend is expected to continue as digital health solutions and telemedicine expand, enhancing access to diabetic kidney disease treatments across various regions.
Segmentation:
By Type
- Type 1 Diabetes
- Type 2 Diabetes
By Treatment
- Angiotensin Receptor Blockers (ARBs)
- Angiotensin-Converting Enzyme (ACE) Inhibitors
- Antioxidant Inflammation Modulator
- Calcium Channel Blockers
- Others
By Distribution Channel
- Online Pharmacy
- Hospital Pharmacy
- Retail Pharmacy
- North America
- US
- Canada
- Mexico
- Europe
- Germany
- France
- UK
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
Regional Analysis:
North America
North America holds the largest market share, accounting for approximately 35% of the global diabetic kidney disease market. This dominance is largely due to high diabetes prevalence, advanced healthcare infrastructure, and strong patient awareness. The United States is the primary contributor, with a significant diabetic population that has access to both advanced diagnostic tools and innovative treatment options. Comprehensive insurance coverage in the U.S. supports access to various therapies, including newer and more expensive options like ACE inhibitors and ARBs. Additionally, increasing healthcare expenditure and ongoing research into diabetic kidney disease treatments further drive market growth in this region. Canada also contributes to market demand, particularly as awareness of diabetic complications and access to specialized care improves.
Europe
Europe represents around 30% of the global market share, driven by a combination of factors, including an aging population, high diabetes prevalence, and well-developed healthcare systems. Key countries such as Germany, the United Kingdom, and France are prominent contributors to the market. Europe has a large elderly population, which is at a higher risk of developing diabetic kidney disease, increasing the demand for treatment options. The region is also marked by government-funded healthcare programs that provide access to essential medications, contributing to consistent demand for diabetic kidney disease treatments. However, regulatory restrictions and varying reimbursement policies across European countries can sometimes limit the availability of certain drugs, affecting the market’s growth rate.
Asia-Pacific
Asia-Pacific is expected to be the fastest-growing region in the diabetic kidney disease market, projected to account for approximately 20% of the market share. Countries like China, India, and Japan are seeing rapid increases in diabetes prevalence due to urbanization, changing lifestyles, and rising obesity rates. This rise in diabetic cases has created a significant need for diabetic kidney disease treatments. Additionally, growing healthcare expenditures and improved access to healthcare services are supporting market expansion in this region. The Asia-Pacific market is further driven by the increasing availability of generic drugs, which offer cost-effective alternatives to branded treatments. As awareness of diabetic complications grows and healthcare infrastructure continues to develop, demand for diabetic kidney disease treatments is expected to rise significantly.
Latin America
Latin America holds about 8% of the market share, with growth driven by increasing diabetes rates and improving healthcare access. Countries such as Brazil, Mexico, and Argentina are leading contributors, supported by efforts to expand healthcare services and improve patient education on diabetic complications. However, limited healthcare budgets and economic disparities across the region can restrict access to advanced treatments, which may moderate the market’s growth. Nevertheless, as awareness of diabetes management grows and governments invest in healthcare, the region is expected to see steady growth in demand for diabetic kidney disease treatments.
Middle East & Africa
The Middle East & Africa account for approximately 7% of the global market share. Growth in this region is driven by rising diabetes prevalence, particularly in urban areas with increasingly sedentary lifestyles. Countries like Saudi Arabia, the UAE, and South Africa are seeing increased awareness of diabetic complications, including kidney disease. While healthcare infrastructure and access to treatment are improving, economic limitations and disparities in access to care in rural areas continue to pose challenges. Despite these barriers, demand is expected to grow as healthcare services and patient education improve across the region, albeit at a slower pace compared to other regions.
Key Player Analysis:
- Abbott (US.)
- Allergan, Inc (Ireland)
- AstraZeneca (UK.)
- Aurobindo Pharma (India)
- Bristol-Myers Squibb Company (US.)
- CiplaInc (India)
- Dr. Reddy's Laboratories Ltd (India)
- Endo International plc (Ireland)
- F. Hoffmann-La Roche Ltd (Switzerland)
- Fresenius SE & Co. KGaA (Germany)
- Lupin (India)
- Mylan NV (US.)
- Novartis AG (Switzerland)
- Pfizer Inc (US.)
- Sanofi (France)
- Sun Pharmaceutical Industries Ltd (India)
- Takeda Pharmaceutical Company Limited (Japan)
- Teva Pharmaceutical Industries Ltd (Israel)
Competitive Analysis:
The diabetic kidney disease market is highly competitive, with key players including pharmaceutical giants such as AstraZeneca, Merck & Co., AbbVie, and Boehringer Ingelheim. These companies maintain a strong market presence by investing heavily in research and development to create advanced treatments, such as angiotensin receptor blockers (ARBs), ACE inhibitors, and novel biologic therapies. Large companies leverage their extensive distribution networks and strong brand recognition to dominate the market, especially in developed regions with established healthcare infrastructures. Additionally, smaller biotech firms and generics manufacturers play a crucial role, particularly in emerging markets where cost-effective treatment options are in high demand. Increasing competition from these companies is driving innovation and encouraging the development of alternative therapies targeting diabetic kidney disease progression. Strategic collaborations and partnerships are common, as companies seek to expand their portfolios and geographic reach, contributing to a dynamic and evolving market landscape.
Recent Developments:
- On March 5, 2024, Novo Nordisk, a multinational pharmaceutical company, announced results from its kidney outcomes trial, FLOW. This double-blind trial compared injectable semaglutide 1.0 mg with a placebo, used alongside standard care, to assess the prevention of kidney impairment progression and the reduction of kidney and cardiovascular mortality risks in people with type 2 diabetes and chronic kidney disease (CKD). The results indicated that semaglutide 1.0 mg demonstrated a safe and well-tolerated profile, consistent with previous studies.
- In February 2023, the European Commission approved a label extension for Kerendia (finerenone) in the European Union, incorporating cardiovascular outcomes from the Phase III FIGARO-DKD study. This research found that Kerendia significantly lowered the risk of cardiovascular events in a large group of patients with CKD stages 1-4 and type 2 diabetes. Kerendia is now recommended in the EU for the treatment of chronic kidney disease (albuminuria) in individuals with type 2 diabetes.
- In January 2023, Boehringer Ingelheim and Eli Lilly and Company announced that the U.S. Food and Drug Administration (FDA) had accepted a supplemental New Drug Application (sNDA) for Jardiance (empagliflozin) tablets. Jardiance is under investigation as a potential treatment to reduce the risk of kidney disease progression and cardiovascular death in adults with chronic kidney disease (CKD).
Market Concentration & Characteristics:
The diabetic kidney disease market is moderately concentrated, with major pharmaceutical companies such as AstraZeneca, Boehringer Ingelheim, Merck & Co., and Novo Nordisk leading due to their extensive portfolios and established brands. These companies dominate the market by investing heavily in research and development, focusing on novel treatments like angiotensin receptor blockers (ARBs), ACE inhibitors, and emerging biologics. Their substantial resources enable them to navigate regulatory challenges and expand their geographic reach, especially in regions with advanced healthcare infrastructure. However, the market also includes smaller biotech firms and generics manufacturers, which contribute by providing cost-effective treatment options, especially in emerging economies. The market is characterized by increasing innovation, with a focus on developing therapies that not only treat symptoms but also slow disease progression. Additionally, rising awareness of diabetic complications and the shift towards preventative healthcare are shaping the market's growth trajectory and encouraging competition among players.
Report Coverage:
The research report offers an in-depth analysis based on By Type, By Treatment and By Distribution Channel. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- Rising diabetes prevalence will continue to drive demand for diabetic kidney disease treatments globally.
- Advances in early diagnostic tools are expected to improve disease detection, enabling earlier interventions and better outcomes.
- Personalized medicine approaches will gain traction, allowing for more targeted and effective treatment options.
- Increased investment in research and development will lead to innovative therapies that address underlying disease mechanisms.
- The growing elderly population will sustain demand as age-related risk factors contribute to disease prevalence.
- Expansion of healthcare infrastructure in emerging markets will improve access to treatments, supporting market growth.
- Collaboration between pharmaceutical companies and research institutions will accelerate drug development and clinical trials.
- Digital health solutions, including telemedicine, will facilitate ongoing patient management and improve treatment adherence.
- Regulatory approvals for new drugs targeting diabetic kidney disease will diversify available treatment options.
- Increased awareness and preventative healthcare initiatives will drive early diagnosis and proactive disease management.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the projected growth of the Diabetic Kidney Disease Market?
What factors are driving market growth?
Which regions hold the largest market shares?
What challenges does the diabetic kidney disease market face?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Diabetic Kidney Disease Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Diabetic Kidney Disease Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 3,023 million → 2032: USD 4,332.03 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Diabetic Kidney Disease Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Diabetic Kidney Disease Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Diabetic Kidney Disease Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Diabetic Kidney Disease Market Drivers
- 3.3 Diabetic Kidney Disease Market Restraints & Challenges
- 3.4 Diabetic Kidney Disease Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Diabetic Kidney Disease Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Diabetic Kidney Disease Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Diabetic Kidney Disease category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Diabetic Kidney Disease Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Diabetic Kidney Disease Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Diabetic Kidney Disease market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Diabetic Kidney Disease Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Diabetic Kidney Disease Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Diabetic Kidney Disease Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Diabetic Kidney Disease (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Diabetic Kidney Disease Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Diabetic Kidney Disease Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Diabetic Kidney Disease Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Diabetic Kidney Disease Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Diabetic Kidney Disease Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Diabetic Kidney Disease Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Diabetic Kidney Disease Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Diabetic Kidney Disease Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Diabetic Kidney Disease Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
