
Kraft Box Market Overview:
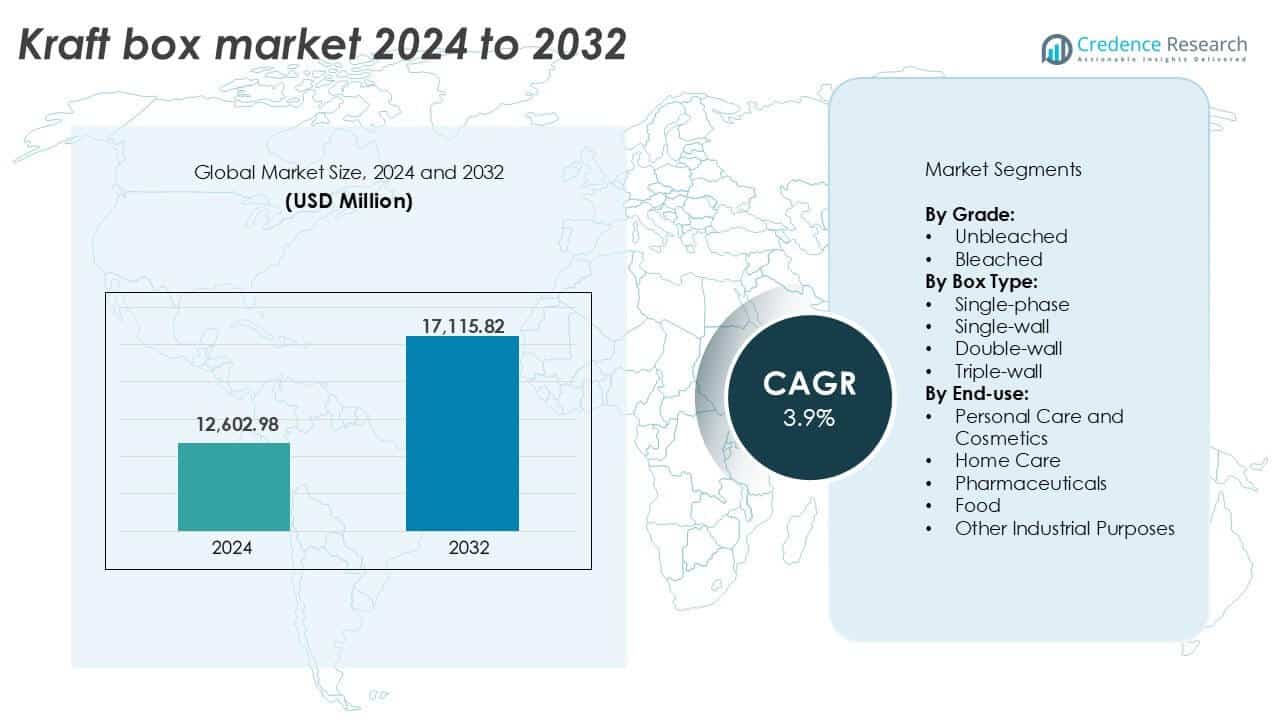
The Kraft Box Market size was valued at USD 12,602.98 million in 2024 and is anticipated to reach USD 17,115.82 million by 2032, at a CAGR of 3.9% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2032 |
| Kraft Box Market Size 2024 | USD 12,602.98 million |
| Kraft Box Market, CAGR | 3.9% |
| Kraft Box Market Size 2032 | USD 17,115.82 million |
Kraft Box Market Insights
- Market growth is driven by rising demand for sustainable packaging, strong e-commerce expansion, and increasing use in food delivery and FMCG logistics. Unbleached Kraft boxes dominate with over 60% segment share due to strength and eco-friendly appeal.
- Key trends include higher adoption of customized and printed Kraft boxes, lightweight corrugated designs, and growing use of single-wall boxes, which hold nearly 48% share among box types.
- The competitive landscape remains consolidated, led by players such as International Paper, WestRock, Smurfit Kappa, and Mondi, focusing on recycled content, capacity expansion, and regional penetration.
- Asia Pacific leads with around 34% regional share, followed by North America at 28% and Europe at 25%, supported by sustainability regulations and strong retail and foodservice demand.
Kraft Box Market Segmentation Analysis:
By Grade
The unbleached grade segment dominates the Kraft box market, accounting for over 60% of the market share in 2024. Unbleached Kraft boxes are preferred due to their superior strength, eco-friendly image, and cost-efficiency. They are widely used in food, industrial, and logistics sectors where durability outweighs aesthetic appeal. The rise in sustainable packaging practices further drives adoption. Bleached Kraft boxes, while visually appealing for premium products, hold a smaller share and cater primarily to cosmetics and personal care packaging where product presentation influences consumer preference.
- For instance, International Paper produces unbleached Kraft linerboard with basis weights up to 440 g/m², supporting high compression strength for bulk packaging.
By Box Type
The single-wall segment leads the market with around 48% share due to its balance of strength and cost-effectiveness. These boxes are widely used across medium-weight packaging needs, especially in food delivery, e-commerce, and retail logistics. Double-wall boxes follow in share, favored for heavier goods in industrial shipments. Triple-wall boxes serve niche sectors requiring extra protection, such as machinery parts. Single-phase boxes, although structurally different, remain limited in usage and are typically used in controlled packaging environments like pharmaceuticals or specialized personal care kits.
- For instance, Smurfit Kappa’s single-wall corrugated boxes achieve edge crush test values above 32 ECT, supporting stable stacking in transit.
By End-Use
The food segment holds the largest share at approximately 35% of the Kraft box market in 2024, driven by rising demand for sustainable and biodegradable packaging in restaurants, bakeries, and food delivery services. Quick-service restaurants and meal-kit companies rely heavily on Kraft boxes for safe, grease-resistant transport. Pharmaceuticals and home care products follow due to growing e-commerce packaging needs. Personal care and cosmetics demand bleached Kraft boxes for premium appeal. Other industrial purposes, including electronics and automotive components, use reinforced Kraft boxes for transit durability.
Key Growth Drivers
Rising Demand for Sustainable and Eco-Friendly Packaging
Sustainability remains a core driver for the Kraft box market as consumers and regulators push for reduced environmental impact. Kraft paper is biodegradable, recyclable, and often sourced from responsibly managed forests, making it a preferred material in green packaging initiatives. Brands across industries including food, cosmetics, and personal care adopt Kraft boxes to meet ESG goals and appeal to environmentally conscious consumers. In the food sector, compostable Kraft containers are gaining traction for takeout and delivery. Retailers are replacing plastic-based boxes with Kraft alternatives to reduce packaging waste. Governments in regions such as the EU and North America impose stricter packaging regulations, further accelerating the transition. This shift drives long-term demand for unbleached Kraft products, especially those made with minimal chemical processing. As more companies commit to carbon-neutral operations, Kraft packaging plays a key role in achieving sustainable logistics and brand differentiation through recyclable solutions.
- For instance, Mondi produces unbleached Kraft paper using 100% sustainably sourced raw materials with its entire portfolio certified as compostable-and operates an integrated network of mills with a combined annual paper and board production capacity of approximately 5.3 million tonnes.
Accelerated Growth of E-commerce and Last-Mile Delivery
The rapid expansion of e-commerce and direct-to-consumer retail channels significantly boosts Kraft box demand. Online retailers require robust, lightweight, and cost-effective packaging to ensure product safety during transit. Kraft boxes-especially single-wall and double-wall variants fulfill these needs while supporting branding through easy printability. Companies like Amazon, Flipkart, and Shopify-based merchants rely on Kraft boxes for product protection and easy recyclability. The rise of quick-commerce and meal-kit delivery also increases demand for temperature-resistant Kraft solutions with grease-proof liners. Subscription box services in beauty, wellness, and food favor custom-sized Kraft packaging for both function and visual appeal. With rising parcel volumes globally, logistics providers prefer uniform Kraft boxes that optimize storage and stacking. The need for tamper-evident, sustainable, and cost-efficient packaging fuels continuous market penetration in the e-commerce space, making it one of the most influential growth drivers for the Kraft box market globally.
- For instance, Amazon ships billions of parcels annually using corrugated Kraft boxes designed to pass ISTA 6-Amazon drop and vibration tests.
Expanding Food & Beverage Sector with Hygiene and Branding Needs
The food and beverage industry is a major consumer of Kraft packaging, particularly driven by the growth of QSRs, bakeries, catering services, and ready-to-eat meal providers. Kraft boxes offer a hygienic, biodegradable, and grease-resistant solution for food transport. As demand grows for healthier, clean-label foods, brands align their packaging with sustainable choices, positioning Kraft as the material of choice. In emerging economies, rising disposable income and urbanization support foodservice expansion, further driving Kraft box demand. Custom print options allow restaurants and cafes to use Kraft boxes for branding while complying with food safety regulations. Heat-sealable and vented Kraft containers are now preferred for hot and cold items. In institutional catering, bulk food packaging increasingly uses double-wall Kraft boxes for durability and compliance. The sector’s high-volume, daily-use nature ensures steady demand, making food and beverage a key revenue source for Kraft box manufacturers worldwide.
Key Trends & Opportunities
Customization and Branding in Packaging Solutions
Brand-conscious companies increasingly demand customizable Kraft box designs to enhance product visibility and customer experience. Kraft packaging, once limited to plain brown boxes, is now available in multiple print finishes, embossing, and die-cut formats. This shift allows brands in cosmetics, electronics, and specialty foods to use packaging as a marketing tool. Small businesses and D2C startups especially favor personalized Kraft boxes to differentiate in crowded markets. E-commerce brands use printed Kraft boxes with QR codes and unboxing experiences to foster customer loyalty. Digital printing advancements now enable short-run, high-resolution customization, making it affordable even for low-volume sellers. This trend unlocks opportunities for box makers offering design services, print-ready templates, or integrated packaging solutions. As online reviews and social sharing grow, the unboxing experience becomes critical placing aesthetic, branded Kraft packaging at the center of consumer engagement strategies.
- For instance, Smurfit Westrock’s digital print platform supports resolutions up to 1,200 dpi and produces customized corrugated Kraft boxes with the flexibility for print runs as low as 1 to 500 units.
Shift Toward Lightweight and Multi-Layer Packaging Structures
The Kraft box market is shifting toward lightweight yet durable packaging structures to optimize logistics and reduce material usage. Manufacturers increasingly offer single-wall boxes with high-burst strength liners or hybrid multilayer combinations for enhanced protection. These innovations reduce shipping costs, minimize carbon footprint, and support automation in fulfillment centers. Demand is also rising for Kraft boxes integrated with cushioning inserts or laminated barriers for perishable and sensitive items. Pharmaceutical, electronics, and high-value goods segments require packaging that balances strength, security, and minimal bulk. Suppliers are responding with double-fluted Kraft options and corrugated designs tailored to specific weight classes. This trend drives R&D investment in material engineering, giving companies a competitive edge through smarter packaging solutions. As supply chains prioritize cost and sustainability, lightweight Kraft box formats represent a scalable opportunity for innovation across industrial and consumer sectors.
Key Challenges
Volatile Raw Material Prices and Supply Chain Disruptions
The Kraft box market faces challenges from fluctuating raw material prices, particularly wood pulp and recycled fiber. These inputs are sensitive to global commodity markets, trade policies, and supply-demand imbalances. Rising energy costs, transportation bottlenecks, and labor shortages further impact production costs. Small and mid-size converters often struggle to maintain margins when input prices spike. In 2024, pulp price volatility across North America and Europe caused price adjustments in packaging grades, forcing buyers to seek cost-effective or downgauged options. Additionally, disruptions from geopolitical tensions or environmental events can restrict raw material flow, affecting lead times and order fulfillment. Kraft box producers must navigate this uncertainty through strategic sourcing, recycled content optimization, and price pass-through mechanisms. However, frequent changes in material cost reduce long-term contract viability, making cost stability a critical concern for both producers and end-users.
Competition from Alternative Packaging Materials
Kraft boxes face increasing competition from alternative packaging formats such as molded fiber, flexible films, and reusable containers. Molded pulp trays and compostable plastics offer similar sustainability credentials with added form flexibility. In retail-ready and high-moisture applications, plastic containers still dominate due to superior barrier properties. Brands aiming for shelf appeal may favor laminated paperboard cartons or coated folding boxes. Moreover, reusable packaging loops promoted by retailers and logistics firms aim to reduce single-use material waste, potentially impacting demand for disposable Kraft boxes. While Kraft maintains strength in protective and eco-conscious packaging, its limitations in moisture resistance and high-end printability pose challenges in select markets. Innovating within regulatory frameworks and expanding capabilities with coatings or hybrid structures is essential for Kraft box manufacturers to retain share amid rising pressure from material substitutes.
Regional Analysis
North America
North America holds approximately 28% share of the global Kraft box market, driven by strong demand from e-commerce, food delivery, and sustainable packaging trends. The U.S. leads with widespread adoption across consumer goods, personal care, and industrial packaging. Regulatory pressure to reduce plastic use accelerates Kraft box deployment. Quick-service restaurants and subscription box services in the region increasingly use customizable Kraft boxes for branding and sustainability. Canada supports growth through rising organic food exports and clean-label product packaging. Well-established recycling infrastructure and consumer awareness further strengthen market penetration across both urban and rural distribution channels.
Europe
Europe accounts for nearly 25% of the global Kraft box market, supported by stringent environmental regulations and growing demand for biodegradable packaging. Germany, France, and the U.K. dominate regional sales due to their strong manufacturing and retail sectors. The EU’s circular economy policies and ban on single-use plastics drive companies to adopt unbleached Kraft solutions. Food and beverage companies use Kraft boxes for both retail and delivery applications. Cosmetics and personal care brands favor premium bleached Kraft options for packaging appeal. Innovation in lightweight, recyclable materials continues to shape market expansion in both Western and Eastern Europe.
Asia Pacific
Asia Pacific leads the global Kraft box market with an estimated 34% share in 2024, supported by rapid industrialization, urbanization, and expanding e-commerce sectors. China and India are key growth engines, driven by rising demand for food delivery, electronics packaging, and fast-moving consumer goods. Southeast Asian countries witness strong adoption of Kraft boxes in logistics and retail. Government-led sustainability programs and bans on plastic packaging contribute to increased demand. Regional manufacturers invest in automation and print customization to meet high-volume and low-cost packaging requirements. Asia Pacific remains the fastest-growing region due to cost advantages and shifting consumer preferences.
Latin America
Latin America holds around 7% share of the global Kraft box market, with Brazil and Mexico as primary contributors. Growing e-commerce activity, along with the foodservice and retail sectors, drives demand for cost-effective and sustainable packaging. Kraft boxes are increasingly used for packaging fresh produce, bakery items, and personal care goods. Domestic manufacturing capacity expansion and trade incentives support regional supply chains. Awareness of recyclable packaging continues to rise, prompting gradual replacement of plastic-based options. However, fluctuating economic conditions and limited recycling infrastructure in some areas challenge faster market adoption across smaller economies.
Middle East & Africa (MEA)
The Middle East & Africa region accounts for approximately 6% of the global Kraft box market, with steady growth supported by retail modernization and food export industries. The Gulf Cooperation Council (GCC) countries lead adoption through luxury packaging in personal care and confectionery products. South Africa and Nigeria show rising demand for Kraft solutions in urban grocery and takeaway food segments. Governments promote eco-friendly packaging alternatives as part of waste reduction goals. While regional adoption is still emerging, increased investment in local manufacturing and packaging innovations is expected to boost future demand across both commercial and industrial segments.
Kraft Box Market Segmentations:
By Grade
- Unbleached
- Bleached
By Box Type:
- Single-phase
- Single-wall
- Double-wall
- Triple-wall
By End-use:
- Personal Care and Cosmetics
- Home Care
- Pharmaceuticals
- Food
- Other Industrial Purposes
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
The Kraft box market features a mix of global packaging giants and regional players competing across pricing, sustainability, and customization capabilities. Companies such as International Paper, Smurfit Kappa Group, and WestRock Company lead with extensive production networks, R&D investment, and strategic partnerships with major FMCG brands. These firms leverage vertically integrated supply chains and advanced printing technologies to meet high-volume, branded packaging demands. Mid-sized players like Pratt Industries and Klabin S.A. focus on regional dominance and recycled fiber innovations. Market players are also investing in lightweight and water-resistant Kraft solutions to capture foodservice and e-commerce segments. Mergers and acquisitions remain common as firms seek to expand geographic presence and capacity. Strategic differentiation now hinges on digital customization, ESG compliance, and responsiveness to shifting material regulations. With sustainability driving purchasing decisions, companies that offer certified, recyclable Kraft solutions with minimal environmental impact gain a competitive edge in both developed and emerging markets.
Key Player Analysis
- Cascades Inc.
- Georgia-Pacific LLC
- WestRock Company
- Oji Holdings Corporation
- Klabin S.A.
- Packaging Corporation of America
- International Paper
- DS Smith Plc
- Smurfit Kappa Group
- Pratt Industries
- Mondi Group
- Nippon Paper Industries Co., Ltd.
- Sonoco Products Company
- Stora Enso
Recent Developments
- In November 2025, Metsä Board revealed a micro-flute premium gift box solution for luxury products. Utilizing less material and boasting a 59% lower carbon footprint compared to traditional rigid boxes, it targeted sectors like cosmetics and beverages, offering production efficiency without retooling.
- In November 2023, Metsä Board revealed a micro-flute premium gift box solution for luxury products. Utilizing less material and boasting a 59% lower carbon footprint compared to traditional rigid boxes, it targeted sectors like cosmetics and beverages, offering production efficiency without retooling.
- In March 2023, WestRock broke ground on a new Kraft corrugated box facility in Longview, Washington. Announced in February 2022, this facility aims to meet rising demand and create approximately 40 jobs by the end of 2023. The plant will replace WestRock’s existing corrugated operations in Longview.
Report Coverage
The research report offers an in-depth analysis based on Grade, Box Type, End-Use and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Demand for Kraft boxes will rise steadily due to global sustainability mandates.
- E-commerce growth will continue to drive high-volume Kraft box consumption.
- Food delivery and takeaway services will remain major demand contributors.
- Unbleached Kraft grades will gain preference for eco-friendly packaging needs.
- Lightweight and high-strength box designs will see wider adoption.
- Custom printing and branding will become standard across consumer segments.
- Automation in packaging lines will support consistent Kraft box demand.
- Asia Pacific will remain the fastest-growing regional market.
- Use of recycled fiber will increase to meet environmental targets.
- Strategic partnerships will shape long-term competitive positioning.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for the Kraft box market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Kraft box market projected to grow between 2024 and 2032?
Which Kraft box market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Kraft box market?
Who are the leading companies in the Kraft box market?
Which region commanded the largest share of the Kraft box market in 2024?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 12,602.98 million → 2032: USD 17,115.82 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Kraft Box Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Kraft Box Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Kraft Box Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Kraft Box Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Kraft Box Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Kraft Box Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Kraft Box Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Kraft Box Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 12,602.98 million → 2032: USD 17,115.82 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Kraft Box Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 Segment Growth Comparison
- 12.4 Segment Attractiveness and Priority Matrix
Chapter 13 Global Kraft Box Geographic Market Outlook, 2024-2032
- 13.1 Regional Market Size and Share, 2024
- 13.2 Regional Market Forecast, 2024-2032
- 13.3 Regional Pricing, Production and Demand Differences
- 13.4 North America
- 13.4.1 United States
- 13.4.2 Canada
- 13.4.3 Mexico
- 13.5 Europe
- 13.5.1 Germany
- 13.5.2 France
- 13.5.3 Italy
- 13.5.4 United Kingdom
- 13.5.5 Spain
- 13.5.6 Poland
- 13.5.7 Russia
- 13.5.8 Netherlands
- 13.5.9 Belgium
- 13.5.10 Sweden
- 13.5.11 Denmark
- 13.5.12 Norway
- 13.5.13 Rest of Europe
- 13.6 Asia Pacific
- 13.6.1 China
- 13.6.2 India
- 13.6.3 Japan
- 13.6.4 South Korea
- 13.6.5 Thailand
- 13.6.6 Indonesia
- 13.6.7 Vietnam
- 13.6.8 Malaysia
- 13.6.9 Australia
- 13.6.10 Rest of Asia Pacific
- 13.7 Latin America
- 13.7.1 Brazil
- 13.7.2 Argentina
- 13.7.3 Colombia
- 13.7.4 Chile
- 13.7.5 Rest of Latin America
- 13.8 Middle East
- 13.8.1 Saudi Arabia
- 13.8.2 United Arab Emirates
- 13.8.3 Turkey
- 13.8.4 Israel
- 13.8.5 Iran
- 13.8.6 Rest of the Middle East
- 13.9 Africa
- 13.9.1 South Africa
- 13.9.2 Egypt
- 13.9.3 Nigeria
- 13.9.4 Morocco
- 13.9.5 Rest of Africa
- 13.10 Regional Investment, Policy and Supply Chain Differences
- 13.11 Regional Competitive Landscape
- 13.12 Geographic Growth Hotspots
Chapter 14 Global Kraft Box Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2024-2032
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 Global Kraft Box Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2024
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2024-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Leading Market Participants – Standard Profile Structure
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.
