
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
| Kraft Pouch Market Size 2024 | USD 1,656 Million |
| Kraft Pouch Market, CAGR | 3.50% |
| Kraft Pouch Market Size 2032 | USD 2,180.64 Million |
Market Overview
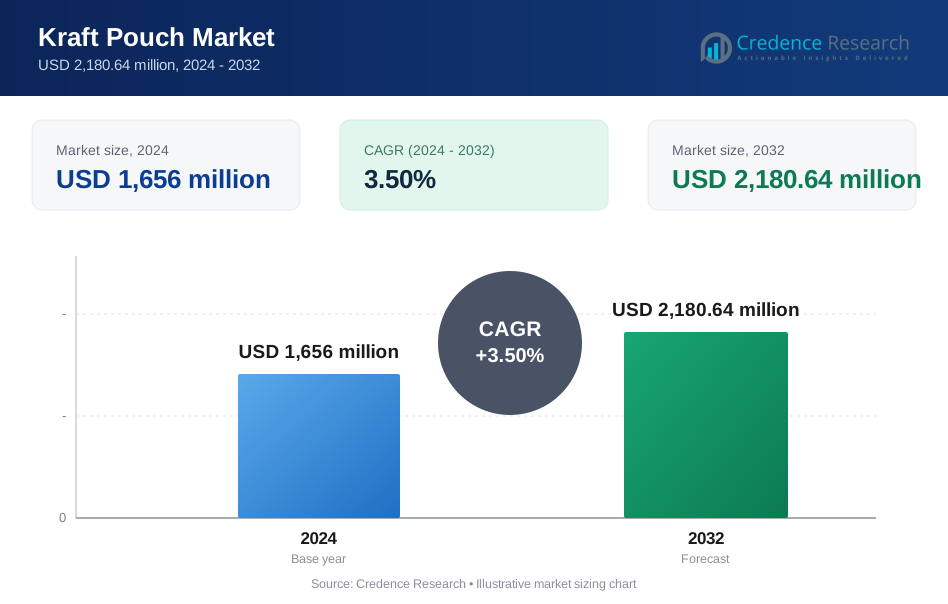
The Kraft Pouch Market is projected to grow from USD 1,656 million in 2024 to USD 2,180.64 million by 2032, reflecting a compound annual growth rate (CAGR) of 3.50%.
The Kraft Pouch Market is driven by increasing consumer demand for sustainable, eco-friendly packaging solutions. Rising environmental awareness and stringent regulations on plastic use propel the shift towards biodegradable materials. The market benefits from the growing food and beverage industry, which prefers kraft pouches for their durability and aesthetic appeal. Technological advancements in packaging and innovative designs also contribute to market growth. Additionally, the e-commerce sector's expansion boosts the demand for reliable and attractive packaging options, solidifying the market's upward trend.
The Kraft Pouch Market is geographically diverse, with significant growth in North America, Europe, and Asia-Pacific regions. North America and Europe lead in adopting sustainable packaging due to stringent environmental regulations and high consumer awareness. Meanwhile, Asia-Pacific is rapidly expanding due to its booming food and beverage industry and increasing urbanization. Key players in this market include Amcor Limited, Mondi Group, Sealed Air Corporation, Sonoco Products Company, and Huhtamäki Oyj. Other notable companies are ProAmpac Holdings, Inc., Berry Global Group, Inc., Printpack, Inc., Constantia Flexibles Group GmbH, and Uflex Ltd, all contributing to the market's competitive landscape.
Market Drivers
Sustainability Concerns and Eco-Friendly Packaging
Consumers are increasingly environmentally conscious, with surveys indicating that over 70% prioritize sustainable packaging solutions. Kraft paper pouches, made from recycled wood pulp, are a biodegradable and compostable alternative to traditional plastic packaging. Stringent government regulations in many countries, such as the EU’s Single-Use Plastics Directive, are driving the demand for eco-friendly alternatives like kraft pouches. Many brands are adopting sustainable packaging solutions to align with consumer preferences and enhance their brand image as environmentally responsible.
Versatility and Functionality of Kraft Pouches
Kraft pouches offer a versatile packaging solution for a wide range of products. They are used in various industries, from food items like coffee, snacks, and candy to personal care products such as cosmetics, toiletries, and even non-food items like stationery or small electronics. Kraft paper provides a surprising level of durability and can be reinforced with additional layers or coatings for extra protection against moisture, grease, or punctures. Additionally, kraft pouches offer excellent printability, allowing for high-quality branding, product information, and attractive designs to enhance shelf appeal.
Cost-Effectiveness and Efficiency
Compared to some rigid packaging options, kraft pouches are lightweight, leading to lower transportation costs and reduced environmental impact. They can be produced efficiently in bulk, making them a cost-effective packaging solution for manufacturers. Moreover, kraft pouches are often foldable and require less storage than rigid packaging materials, saving up to 50% of space in warehouses and retail stores. This efficiency in production and storage further boosts their appeal in the packaging industry.
Other Market Drivers
The booming e-commerce industry, which is expected to reach $6.5 trillion by 2023, demands flexible and lightweight packaging solutions for efficient product delivery. Kraft pouches are ideal for online retailers due to their protective nature and suitability for letterbox deliveries. The rising trend of on-the-go consumption is driving the demand for convenient and portable packaging solutions, with kraft pouches offering an ideal way to package snacks, beverages, and other portable items. Manufacturers are constantly innovating with features like resealable closures, tear-away tops, and integrated handles, enhancing the functionality and convenience of kraft pouches.
Market Trends
Focus on Enhanced Sustainability
The Kraft Pouch Market is increasingly prioritizing sustainability, focusing on bio-based and compostable materials. Companies are moving towards the use of biodegradable polymers and agricultural residues for kraft pouch production, further minimizing environmental impact and promoting industrial composting. These innovations reduce the carbon footprint and support the circular economy. Developments in recyclable coatings and laminations are also critical, allowing kraft pouches to have enhanced barrier properties while being more effectively recycled. This improvement is essential for promoting a circular economy for packaging materials, where waste is minimized, and resources are continuously reused. Additionally, the industry is focusing on sustainable inks made from renewable resources and water-based printing processes. These sustainable printing technologies help reduce the environmental impact of kraft pouch production, making the entire lifecycle of the product more eco-friendly.
Innovation in Functionality and Features
Innovation in the Kraft Pouch Market is driving advancements in functionality and features. Smart and interactive pouches are emerging, incorporating integrated sensors or RFID tags. These smart pouches can track product temperature during transport or provide consumers with interactive experiences through smartphone apps, enhancing product safety and user engagement. Additionally, advancements in pouch design include self-venting features that release pressure for hot or gaseous products, improving safety and product integrity. Improved resealable closures are also being developed to maintain product freshness and provide convenience for consumers. Customizable barrier properties are another innovation, with kraft pouches engineered to suit specific product needs. Depending on the packaged product, this customization involves selective barriers for oxygen, moisture, or light, ensuring optimal protection and shelf life.
Market Challenges Analysis
Limited Barrier Properties Compared to Plastics
Kraft pouches face significant challenges due to their limited barrier properties compared to plastic packaging. One of the primary issues is moisture and gas permeability. While kraft paper offers some level of protection, it is naturally permeable to moisture and gases, which can limit the shelf life of certain products. This is particularly problematic for highly perishable food items or products sensitive to oxidation, where extended shelf life is crucial. Additionally, packaging liquid products in kraft pouches poses considerable challenges. Without additional liners or coatings to prevent leaks, the integrity of the packaging can be compromised, leading to increased production complexity and higher costs. These additional barriers are necessary to maintain product quality, but they complicate the manufacturing process and can detract from the inherent sustainability advantages of kraft pouches.
Balancing Functionality with Sustainability
Finding the right balance between functionality and sustainability is a critical challenge for the Kraft Pouch Market. One key issue is the trade-off between barrier properties and recyclability. While adding liners or coatings to kraft pouches can significantly improve their barrier properties, it may compromise their recyclability. This poses a dilemma for manufacturers who strive to create functional and environmentally friendly packaging. Moreover, the availability of certified compostable pouches is limited by regional composting infrastructure. In many areas, commercially compostable kraft pouches with proper certifications are not readily available, hindering their widespread adoption. This lack of infrastructure can delay the transition to more sustainable packaging solutions.
Additionally, consumer perception and awareness present challenges. Some consumers might perceive kraft paper packaging as less premium, associating it with less expensive or generic products. Educating consumers about kraft pouches' sustainability benefits and premium possibilities is essential to shift these perceptions. Furthermore, there is limited awareness of the functionality and applications of kraft pouches. Many consumers may not fully understand the range of products suitable for kraft pouch packaging or the innovative functional features that are being developed in the market.
Market Segmentation Analysis:
By Product Type:
The Kraft Pouch Market is segmented by product type into flat pouches and stand-up pouches, each offering distinct advantages in packaging design and functionality. Flat pouches are widely used for their simplicity and cost-effectiveness, making them suitable for snacks, dry goods, and single-serving items. They are easy to produce and offer efficient use of space, both in storage and on retail shelves. On the other hand, stand-up pouches are gaining popularity due to their enhanced shelf presence and convenience. These pouches are ideal for products that require a more robust packaging solution, such as liquids, sauces, and bulkier food items. Their ability to stand upright provides better visibility and branding opportunities, which is a significant advantage in retail environments. The versatility of stand-up pouches also makes them suitable for a broader range of applications, from food and beverages to personal care products. Both types of pouches contribute significantly to the market, catering to different consumer needs and product specifications.
By Grade:
Kraft pouches are classified by grade into bleached and unbleached varieties, each offering unique attributes and applications. Bleached kraft pouches are favored for their cleaner and more refined appearance, making them ideal for products where visual appeal is critical. These pouches are often used in premium and luxury packaging, where a pristine, white appearance can enhance brand perception and attract consumers. In contrast, unbleached kraft pouches retain their natural, earthy look, which appeals to environmentally conscious consumers. The unbleached variety is typically perceived as more eco-friendly, aligning with the growing demand for sustainable packaging solutions. These pouches are popular in organic and natural product markets, where the rustic aesthetic complements the brand's environmental ethos. Both grades of kraft pouches offer functional benefits, such as durability and barrier properties, but their distinct visual characteristics cater to different market segments. The choice between bleached and unbleached pouches often depends on the product's branding strategy and the target consumer's preferences.
Segments:
Based on Product Type
- Flat Pouches
- Stand-Up Pouches
Based on Grade
- Bleached
- Unbleached
Based on Finish
- Glazed
- Finished
Based on End Use
- Food and Beverages
- Pharmaceuticals
- Cosmetics and Personal Care
- Electronics and Electricals
- Other Industrial Goods
Based on the Geography:
- North America
- US
- Canada
- Mexico
- Europe
- Germany
- France
- UK
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of Middle East and Africa
Regional Analysis
North America
North America dominates the market, holding approximately 35% of the global share. Consumers' increasing preference for convenience foods and sustainable packaging options drive this region's success. The United States, in particular, has witnessed a surge in demand for Kraft pouches in the snack and ready-to-eat meal segments. Europe follows closely, accounting for roughly 30% of the market share, with countries like Germany, France, and the UK at the forefront of adoption. The region's focus on eco-friendly packaging solutions and stringent plastic-use regulations have further propelled the growth of Kraft pouches.
Asia-Pacific
Asia-Pacific is emerging as a rapidly growing market for Kraft pouches, currently holding about 20% of the global share. Countries such as China, Japan, and India are experiencing a shift in consumer preferences towards packaged foods, driving the demand for flexible packaging solutions. The region's vast population and rising disposable incomes contribute to the market's expansion. Latin America and the Middle East & Africa collectively account for the remaining 15% of the market share, with Brazil and South Africa showing promising growth potential. These regions are witnessing increased urbanization and changing lifestyles, leading to a higher adoption of convenient packaging formats. As manufacturers continue to innovate and adapt to regional preferences, the Kraft pouch market is expected to maintain its upward trajectory across all geographies.
Key Player Analysis
- Amcor Limited
- Mondi Group
- Sealed Air Corporation
- Sonoco Products Company
- Huhtamäki Oyj
- ProAmpac Holdings, Inc.
- Coveris Holdings S.A.
- Berry Global Group, Inc.
- Bemis Company, Inc. (Now part of Amcor Limited)
- Printpack, Inc.
- Constantia Flexibles Group GmbH
- Uflex Ltd
- Glenroy, Inc.
- Winpak Ltd.
- Scholle IPN
- Swiss Pac Group
- Flair Flexible Packaging Corporation
- Eagle Flexible Packaging
- Ampac Holdings, LLC (Now part of ProAmpac Holdings, Inc.)
- Pouch Direct Pty Ltd
Competitive Analysis
The Kraft Pouch Market is highly competitive, with leading players such as Amcor Limited, Mondi Group, Sealed Air Corporation, and Sonoco Products Company dominating the landscape. These companies leverage their extensive research and development capabilities to innovate sustainable and functional packaging solutions. Amcor Limited and Mondi Group are particularly noted for their advanced technology and eco-friendly packaging options. Sealed Air Corporation excels in offering high-performance packaging with superior barrier properties, catering to diverse industry needs. Huhtamäki Oyj and ProAmpac Holdings, Inc. focus on custom solutions and expanding their global footprint through strategic acquisitions. Berry Global Group, Inc., and Printpack, Inc. are also significant contributors, emphasizing recyclable and compostable packaging innovations. Constantia Flexibles Group GmbH and Uflex Ltd stand out for their strong regional presence and competitive pricing strategies. The market is characterized by continuous innovation, strategic partnerships, and a commitment to sustainability, driving the competition among these key players.
Recent Developments
- In May 2024, responding to consumer demand and evolving preferences, Kraft Heinz further delighted Capri Sun fans by launching a family-size bottle adorned with a graphic depiction of the iconic pouch. This move honored the brand's legacy and addressed changing consumer preferences for larger servings.
- In 2023, Kraft Heinz, headquartered in the United States, introduced an innovative pouch technology designed to make microwaved grilled cheese sandwiches crispy. This groundbreaking advancement was initially featured in Lunchables, with plans to extend its application to three additional brands as part of the company's broader innovation strategy.
Market Concentration & Characteristics
The Kraft Pouch Market exhibits moderate concentration with a mix of large multinational corporations and regional players. Major companies such as Amcor Limited, Mondi Group, and Sealed Air Corporation hold significant market shares, leveraging their extensive resources and global distribution networks to influence market dynamics. These leading players often engage in strategic mergers and acquisitions to enhance their product offerings and expand their market reach. The market is characterized by its emphasis on sustainability, driven by increasing consumer demand for eco-friendly packaging solutions. Companies are investing in innovative technologies to improve functionality and environmental impact, including advancements in recyclable coatings and compostable materials. Additionally, the market features a diverse range of product types and end-use applications, from food and beverages to pharmaceuticals and personal care, reflecting its broad applicability and the varied needs of different industries. This competitive and evolving landscape underscores the importance of innovation and sustainability in shaping market trends.
Report Coverage
The research report offers an in-depth analysis based on Product Type, Grade, Finish, End Use and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The Kraft Pouch Market is expected to continue growing due to increasing consumer preference for sustainable packaging solutions.
- Advances in biodegradable and compostable materials will enhance the environmental benefits of kraft pouches.
- Innovations in pouch design, such as smart and interactive features, will drive market expansion.
- Increased adoption of stand-up pouches will improve shelf visibility and product convenience.
- Companies will focus on enhancing barrier properties to better compete with traditional plastic packaging.
- The market will see greater diversification in end-use applications, including pharmaceuticals and electronics.
- Regional growth will be driven by expanding e-commerce and urbanization in Asia-Pacific and Latin America.
- Rising environmental regulations will push more companies to adopt eco-friendly packaging solutions.
- Increased investment in research and development will lead to advanced functionality and customization in kraft pouches.
- Consumer education on the benefits of kraft pouches will boost market acceptance and demand.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Sustainability Concerns and Eco-Friendly Packaging
Growing environmental awareness and stricter regulations on plastic use are driving demand for biodegradable and compostable packaging like kraft pouches. Brands are adopting kraft pouches to align with consumer preferences for sustainable solutions and to enhance their eco-friendly image.
Versatility and Functionality of Kraft Pouches
Kraft pouches are used across diverse industries, from food and beverages to cosmetics and electronics, due to their durability, printability, and ability to be customized with features like resealable closures and barrier coatings. This versatility expands their market reach and application.
Cost-Effectiveness and Efficiency
Kraft pouches are lightweight and require less storage space compared to rigid packaging, reducing transportation and warehousing costs for manufacturers and retailers. Their efficient bulk production makes them a cost-effective solution, especially for high-volume applications.
Growth of E-Commerce and On-the-Go Consumption
The expansion of e-commerce and changing consumer lifestyles are increasing demand for flexible, protective, and convenient packaging. Kraft pouches are well-suited for online retail and portable products, supporting market growth in these fast-evolving channels.
Technological Advancements and Innovation
Ongoing innovations in materials, coatings, and pouch design - such as smart features, improved barrier properties, and sustainable inks - are enhancing the performance and appeal of kraft pouches. These advancements help kraft pouches compete with traditional plastics and meet evolving customer needs.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Kraft Pouch Market?
What factors are driving the growth of the Kraft Pouch Market?
What are the key segments within the Kraft Pouch Market?
What are some challenges faced by the Kraft Pouch Market?
Who are the major players in the Kraft Pouch Market?
Which segment is leading the market share?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Grade
- 1.2.1 Bleached
- 1.2.2 Unbleached
- 1.3 By Finish
- 1.3.1 Glazed
- 1.3.2 Finished
- 1.4 By End Use
- 1.4.1 Food and Beverages
- 1.4.2 Pharmaceuticals
- 1.4.3 Cosmetics and Personal Care
- 1.4.4 Electronics and Electricals
- 1.4.5 Other Industrial Goods
- 1.5 By Product Type
- 1.5.1 Flat Pouches
- 1.5.2 Stand-Up Pouches
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 1,656 million → 2032: USD 2,180.64 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Kraft Pouch Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Kraft Pouch Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Kraft Pouch Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Kraft Pouch Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Kraft Pouch Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Kraft Pouch Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Kraft Pouch Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Kraft Pouch Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 1,656 million → 2032: USD 2,180.64 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Kraft Pouch Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Grade - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Bleached
- 12.3.7.2 Unbleached
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Finish - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Glazed
- 12.4.7.2 Finished
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By End Use - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Food and Beverages
- 12.5.7.2 Pharmaceuticals
- 12.5.7.3 Cosmetics and Personal Care
- 12.5.7.4 Electronics and Electricals
- 12.5.7.5 Other Industrial Goods
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 By Product Type - Market Size and Forecast, 2024-2032
- 12.6.1 Segment Definition and Scope
- 12.6.2 Historical Market Size
- 12.6.3 Revenue Forecast, 2024-2032
- 12.6.4 Volume Forecast, 2024-2032
- 12.6.5 Base-Year Market Share, 2024
- 12.6.6 Segment CAGR and Growth Drivers
- 12.6.7 Subsegment Market Size and Forecast
- 12.6.7.1 Flat Pouches
- 12.6.7.2 Stand-Up Pouches
- 12.6.8 Subsegment Pricing and Adoption Trends
- 12.6.9 Leading Suppliers and Competition
- 12.6.10 Regional Demand and Opportunities
- 12.7 Segment Growth Comparison
- 12.8 Segment Attractiveness and Priority Matrix
Chapter 13 Global Kraft Pouch End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Kraft Pouch Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Kraft Pouch Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Kraft Pouch Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Amcor Limited
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Mondi Group
- 18.4 Sealed Air Corporation
- 18.5 Sonoco Products Company
- 18.6 Huhtamäki Oyj
- 18.7 ProAmpac Holdings, Inc.
- 18.8 Berry Global Group, Inc.
- 18.9 Printpack, Inc.
- 18.10 Constantia Flexibles Group GmbH
- 18.11 Uflex Ltd
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

