
Market Overview:
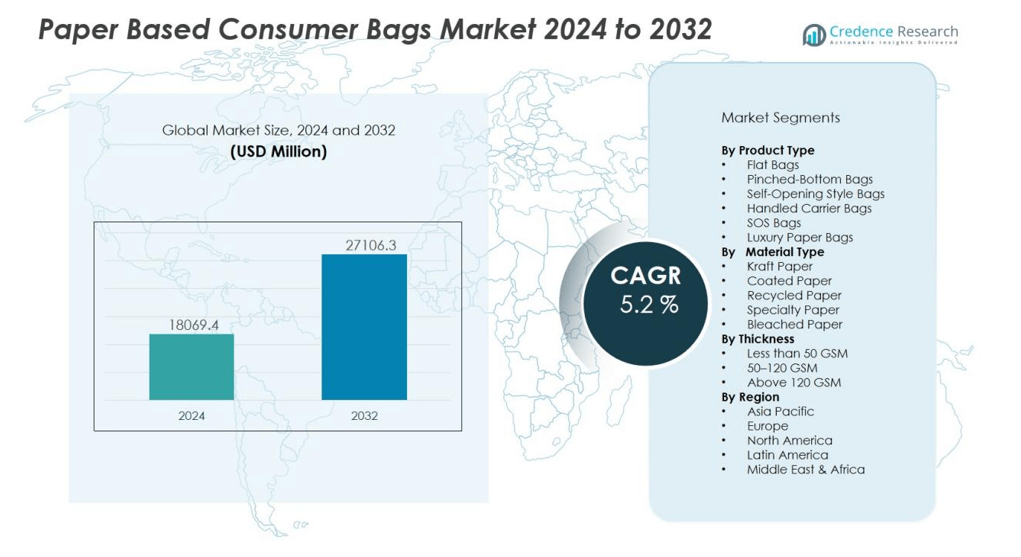
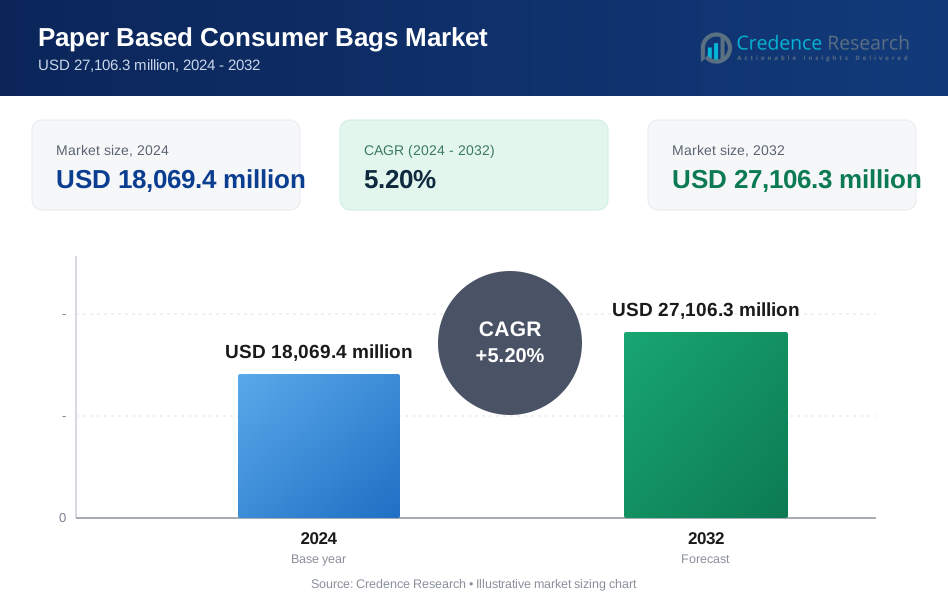
The paper based consumer bags market size was valued at USD 18069.4 million in 2024 and is anticipated to reach USD 27106.3 million by 2032, at a CAGR of 5.2 % during the forecast period (2024-2032).
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Paper Based Consumer Bags Market Size 2024 | USD 18069.4 million |
| Paper Based Consumer Bags Market, CAGR | 5.2% |
| Paper Based Consumer Bags Market Size 2032 | USD 27106.3 million |
Growth in this market is largely driven by consumer preference for sustainable packaging, government-imposed bans on plastic carry bags, and the growing retail and e-commerce industry that requires safe, durable, and environmentally compliant packaging. Technological advancements in manufacturing have improved the durability, printability, and moisture resistance of paper bags, further enhancing their adoption. Branding and customization opportunities also make paper bags attractive to businesses seeking both utility and marketing value.
Regionally, Europe dominates the paper-based consumer bags market due to stringent environmental policies and early adoption of sustainable packaging practices. North America shows strong demand driven by corporate sustainability commitments and consumer awareness, while Asia-Pacific is emerging as the fastest-growing region, supported by rapid urbanization, expanding retail markets, and increasing government-led initiatives to reduce plastic waste. Latin America and the Middle East & Africa are gradually adopting paper-based alternatives, with growth tied to improving retail infrastructure and evolving regulations.
Market Insights:
- The paper based consumer bags market was valued at USD 18,069.4 million in 2024 and is projected to reach USD 27,106.3 million by 2032, reflecting strong growth.
- Sustainability remains the primary driver, with consumers and businesses shifting toward biodegradable and recyclable alternatives to replace single-use plastics.
- Government-imposed bans and regulations on plastic bags are creating a steady demand base for paper-based alternatives across retail and food service.
- Expansion of retail, e-commerce, and food delivery sectors is boosting adoption due to the durability, branding flexibility, and compliance offered by paper bags.
- Technological advancements in coatings and manufacturing enhance water resistance, strength, and customization, improving market appeal.
- High production costs and raw material dependency remain key challenges, with manufacturers balancing affordability and environmental responsibility.
- Europe leads with 36% market share, North America follows with 28%, and Asia Pacific holds 25% while showing the fastest growth supported by urbanization and policy reforms.
Market Drivers:
Rising Demand for Sustainable and Eco-Friendly Packaging Solutions:
The growing emphasis on sustainability is a major driver for the paper based consumer bags market. Consumers are increasingly rejecting single-use plastics in favor of biodegradable and recyclable options. It benefits from stricter global regulations that mandate eco-friendly packaging alternatives. Retailers and brands leverage paper bags to meet consumer expectations while aligning with sustainability goals. This shift has positioned paper bags as a primary solution in both retail and food service sectors.
- For instance, IKEA replaced plastic fitting bags with paper-based alternatives across 451 global stores in FY25, eliminating 1,400 tons of virgin plastic annually.
Government Regulations and Bans on Plastic Bags Stimulating Adoption:
Stringent bans and restrictions on plastic bags across regions are accelerating the adoption of paper-based alternatives. Governments worldwide are implementing policies to curb plastic waste and promote sustainable practices. The paper based consumer bags market gains momentum from this regulatory push, creating a stable demand base. Compliance requirements have driven retailers and manufacturers to shift their packaging strategies. These measures continue to support long-term market expansion.
- For instance, Walmart transitioned from plastic to recyclable paper mailers across its fulfillment network, eliminating 65 million plastic bag mailers annually, which represents more than 2,000 tons of plastic reduction.
Expansion of Retail, E-Commerce, and Food Service Industries:
The rapid growth of retail and e-commerce is fueling the need for reliable and eco-friendly packaging. Paper bags offer strength, durability, and easy branding opportunities for businesses in these sectors. It provides both convenience and sustainability, making it suitable for mass adoption. The food service industry also contributes significantly, with increasing use of paper bags for takeaway and delivery. Together, these industries act as strong demand generators for the market.
Technological Advancements and Customization Driving Market Appeal:
Innovations in paper processing and bag manufacturing are enhancing product quality and functionality. Improved strength, water resistance, and printability increase the usability of paper bags across diverse applications. The paper based consumer bags market also benefits from customization options that allow businesses to use packaging as a branding tool. It creates added value by combining sustainability with marketing potential. These advancements continue to strengthen consumer and business adoption globally.
Market Trends:
Shift Toward Premiumization and Customizable Eco-Friendly Packaging:
One of the key trends shaping the paper based consumer bags market is the growing demand for premium and customizable packaging solutions. Brands are investing in high-quality paper bags with advanced printing techniques, attractive designs, and durable finishes to enhance consumer perception and brand identity. It has become common for retailers, especially in fashion, luxury, and specialty food sectors, to use paper bags as both a functional product and a marketing medium. Companies are increasingly offering personalized designs, logo printing, and creative finishes to differentiate themselves in competitive markets. The trend of aligning packaging with sustainability and brand storytelling strengthens the appeal of paper bags across industries. This movement toward premium eco-friendly solutions is expected to expand further as businesses prioritize both environmental responsibility and consumer experience.
- For instance, Ocean's Deep Printers utilized Heidelberg SM 74 printing technology to produce premium paper bags on 350-gsm white FBB featuring sophisticated geometric patterns, gold foil stamping, and golden thread accents.
Adoption of Advanced Manufacturing and Sustainable Material Innovations:
Technological innovation is another defining trend in the paper based consumer bags market, with manufacturers focusing on improving strength, water resistance, and recyclability. Advanced coatings and barrier technologies are being introduced to make paper bags suitable for a wider range of applications, including food delivery and e-commerce. It has also driven the adoption of recycled paper and renewable raw materials, aligning with circular economy initiatives. Brands are highlighting eco-certifications and material transparency to attract environmentally conscious consumers. The integration of automation in manufacturing is enabling faster production and better quality control, meeting the rising global demand efficiently. These advancements are reshaping the competitive landscape by pushing paper bags beyond traditional uses into diverse, high-volume industries.
- For instance, IPC has developed CelluLiner paper insulated delivery bags that maintain temperatures below 20°F for more than 3 hours using 100% paper construction with post-consumer recycled materials.
Market Challenges Analysis:
High Production Costs and Limited Durability Compared to Alternatives:
A major challenge for the paper based consumer bags market lies in higher production costs compared to plastic alternatives. The use of quality raw materials, advanced coatings, and sustainable sourcing practices increases overall expenses, which can limit affordability for small retailers. It also faces limitations in terms of durability, particularly under wet conditions or with heavy loads, which restricts adoption in some applications. Consumers often perceive paper bags as less convenient than sturdier options, creating resistance in price-sensitive markets. Balancing cost-efficiency while maintaining strength and eco-friendly credentials remains a critical issue for manufacturers. This challenge continues to influence competitive positioning and pricing strategies across the sector.
Raw Material Dependency and Environmental Trade-Offs:
The heavy reliance on paper production creates dependency on wood pulp, leading to concerns about deforestation and resource availability. The paper based consumer bags market must address these sustainability trade-offs to maintain credibility as an eco-friendly alternative. It faces scrutiny from environmental groups regarding energy-intensive manufacturing processes and the carbon footprint associated with large-scale production. Fluctuating raw material prices and supply chain disruptions further add to operational challenges. Manufacturers are under pressure to adopt recycled materials and renewable resources without compromising product quality. These factors collectively pose significant hurdles to the long-term growth of the market.
Market Opportunities:
Growing Demand from Emerging Economies and Expanding Retail Sector:
Rising urbanization, increasing disposable income, and expanding retail infrastructure in emerging economies create strong opportunities for the paper based consumer bags market. Consumers in these regions are becoming more conscious of sustainability and are shifting toward eco-friendly alternatives. It benefits from the rapid growth of supermarkets, convenience stores, and e-commerce platforms that require sustainable packaging solutions at scale. Governments in countries such as India, China, and Brazil are implementing stricter regulations on single-use plastics, which further accelerates adoption. Retailers and food service providers in these markets are also seeking affordable and customizable paper bag solutions. This expanding demand base provides manufacturers with a significant opportunity to establish long-term growth.
Innovation in Sustainable Materials and Circular Economy Integration:
Ongoing research and development in recycled paper and biodegradable coatings opens new avenues for the paper based consumer bags market. Innovations that enhance strength, water resistance, and reusability create opportunities for broader application across retail, e-commerce, and food delivery sectors. It gains momentum from increasing interest in closed-loop recycling and circular economy models. Businesses are eager to partner with suppliers that can deliver sustainable yet high-performance packaging. Opportunities also exist for companies to differentiate through eco-labeling, carbon-neutral production, and transparent supply chain practices. These advancements not only strengthen market adoption but also allow brands to align with global sustainability goals.
Market Segmentation Analysis:
By Product Type:
The paper based consumer bags market includes flat bags, pinched-bottom bags, self-opening style bags, and handled carrier bags. Flat and pinched-bottom bags dominate in retail and food service due to convenience and low production costs. Handled carrier bags are gaining preference in fashion and premium retail because they combine durability with branding opportunities. Self-opening style bags are widely used in grocery and bulk shopping, offering strength and ease of handling. It reflects diverse adoption patterns shaped by end-use applications.
- For instance, Mondi’s Eco/Vantage Light Fashion handled carrier bags are produced using 100 percent recycled fibres and feature reinforced handles to support high‐end brand printing on premium stock, enabling seamless integration into luxury retail packaging.
By Material Type:
Key material segments include kraft paper, coated paper, recycled paper, and specialty paper. Kraft paper leads the market due to its strength, cost efficiency, and recyclability. Coated paper finds demand in food packaging where moisture resistance is essential. Recycled and specialty papers are gaining traction, driven by sustainability initiatives and consumer preference for eco-certified solutions. It highlights the growing importance of materials that balance performance with environmental responsibility.
- For instance, Mondi’s Ad/Vantage StretchWrap kraft paper achieves a grammage of 70 g/m², enabling high tensile energy absorption on high-speed converting lines at this low basis weight.
By Thickness:
Segments by thickness include less than 50 GSM, 50–120 GSM, and above 120 GSM. Bags with less than 50 GSM are used for lightweight applications such as bakery and pharmacy packaging. The 50–120 GSM range dominates retail, apparel, and grocery due to its balance of strength and affordability. Bags above 120 GSM serve luxury retail and specialty goods where premium appearance and reusability matter. It reflects how thickness influences utility, cost, and consumer perception across industries.
Segmentations:
By Product Type:
- Flat Bags
- Pinched-Bottom Bags
- Self-Opening Style Bags
- Handled Carrier Bags
- SOS Bags
- Luxury Paper Bags
By Material Type:
- Kraft Paper
- Coated Paper
- Recycled Paper
- Specialty Paper
- Bleached Paper
By Thickness:
- Less than 50 GSM
- 50–120 GSM
- Above 120 GSM
By Region:
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis:
Europe:
Europe holds 36% market share in the paper based consumer bags market, making it the leading region. The dominance is driven by stringent environmental policies, high consumer awareness, and early adoption of eco-friendly alternatives. Governments across the region have imposed strict bans on plastic carry bags, encouraging rapid transition toward paper-based solutions. Retailers and luxury brands actively invest in premium and customizable paper bags, strengthening demand. It also benefits from robust recycling infrastructure and advanced manufacturing technologies. The European market is expected to maintain steady growth as sustainability regulations continue to evolve.
North America:
North America accounts for 28% market share in the paper based consumer bags market, supported by strong retail and food service sectors. Companies in the region are heavily focused on sustainability initiatives, making paper bags a preferred choice. Rising consumer demand for eco-friendly products and active corporate commitments to reduce plastic use are shaping growth. It also benefits from a well-established e-commerce industry that creates significant packaging demand. Manufacturers in the region emphasize product innovation, including durable and water-resistant bags. Favorable regulations and consumer preference will continue to sustain demand in the years ahead.
Asia Pacific:
Asia Pacific represents 25% market share in the paper based consumer bags market, with the fastest growth rate globally. Government-led plastic bans and rising urbanization are fueling adoption across retail, food delivery, and e-commerce. Countries such as India, China, and Indonesia are witnessing significant demand due to growing population and increasing disposable incomes. It also benefits from expanding manufacturing capacity and cost-effective raw material availability in the region. Local and international players are investing in new facilities to meet rising demand. This region is expected to emerge as a long-term growth hub, supported by regulatory enforcement and consumer preference for sustainable packaging.
Key Player Analysis:
- International Paper Company
- Oji Holdings
- Mondi Plc
- Smurfit Kappa
- Stora Enso
- Novolex
- Atlantic Packaging
- Ronpak
- Langston Companies
- Detmold Packaging
- McNairn Packaging
- Wisconsin Converting
- Welton Bibby and Baron
- JohnPac
Competitive Analysis:
The paper based consumer bags market is defined by the presence of global leaders and regional specialists that compete through innovation, sustainability, and scale. Key players include International Paper Company, Oji Holdings, Mondi Plc, Smurfit Kappa, Stora Enso, Novolex, Atlantic Packaging, Ronpak, and Langston Companies. It is marked by intense competition where established firms focus on expanding eco-friendly product portfolios and enhancing customization capabilities to meet retail and food service demand. Larger players leverage advanced manufacturing technologies and strong distribution networks to secure global reach, while regional companies emphasize flexibility and cost efficiency. Strategic partnerships, acquisitions, and investments in recycled materials are common as firms aim to strengthen their sustainability positioning. The market demonstrates a balance of consolidation among top players and opportunities for mid-sized companies to capture niche demand in premium, luxury, and specialty paper bag segments.
Recent Developments:
- In August 2025 Atlantic Packaging launched the second-generation Fishbone C-Clip beverage carrier, providing improved durability for refrigerated use and a fiber-based alternative to single-use plastics.
- In June 2025, Stora Enso partnered with Matrix Pack, acquiring a minority stake and joining its board to advance sustainable fiber packaging solutions as part of a strategic alliance.
Market Concentration & Characteristics:
The paper based consumer bags market is moderately concentrated, with a mix of global players and regional manufacturers competing across diverse segments. It is characterized by strong demand from retail, food service, and e-commerce sectors, where sustainability and regulatory compliance drive adoption. Large players focus on premium quality, innovation, and branding opportunities, while smaller firms cater to cost-effective and customized solutions. The market demonstrates high product differentiation through durability, recyclability, and design versatility. Competitive intensity remains strong, with companies investing in recycled materials, advanced coatings, and eco-certifications to strengthen positioning. It continues to evolve under the influence of environmental policies, consumer expectations, and technological advancements in packaging.
Report Coverage:
The research report offers an in-depth analysis based on Product Type, Material Type, Thickness and Region. It details leading Market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current Market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven Market expansion in recent years. The report also explores Market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on Market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the Market.
Future Outlook:
- The paper based consumer bags market will expand as global regulations continue to restrict single-use plastics and promote eco-friendly packaging.
- It will experience rising adoption in retail and e-commerce sectors due to durability, branding flexibility, and consumer preference for sustainable options.
- Companies will invest in advanced manufacturing technologies to improve strength, water resistance, and reusability of paper bags.
- The food service industry will drive strong demand, with increased use of paper bags for takeaway and delivery applications.
- Growth in emerging economies will accelerate, supported by urbanization, rising disposable incomes, and expanding retail infrastructure.
- Manufacturers will increasingly adopt recycled and renewable raw materials to meet sustainability goals and reduce environmental impact.
- Branding and customization will remain key, with businesses using paper bags as marketing tools to enhance brand identity.
- Global players will pursue partnerships, acquisitions, and expansions to strengthen supply chain resilience and market presence.
- Circular economy practices and eco-label certifications will influence purchasing decisions, shaping long-term consumer behavior.
- The market will remain competitive, with innovation and sustainability initiatives defining leadership across global and regional players.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Consumer Shift to Sustainable Packaging
Growing environmental awareness and consumer rejection of single-use plastics are driving demand for biodegradable and recyclable paper-based bags, especially as brands seek to align with sustainability values.
Government Regulations and Plastic Bag Bans
Stringent bans and restrictions on plastic bags across major markets are compelling retailers and manufacturers to adopt paper-based alternatives, creating a stable and expanding demand base.
Expansion of Retail, E-Commerce, and Food Service
Rapid growth in retail, online shopping, and food delivery sectors is increasing the need for durable, customizable, and compliant packaging solutions, making paper bags a preferred choice for both utility and branding.
Technological Advancements in Manufacturing
Innovations in coatings, barrier technologies, and automation are improving the strength, water resistance, and printability of paper bags, broadening their applications and enhancing market appeal.
Premiumization and Customization Trends
Brands are investing in high-quality, customizable paper bags to enhance consumer experience and brand identity, particularly in fashion, luxury, and specialty food sectors, further boosting market growth.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for the paper based consumer bags market, and what is its projected size in 2032?
Which paper based consumer bags market segment held the largest share in 2024?
What are the primary factors fueling the growth of the paper based consumer bags market?
Who are the leading companies in the paper based consumer bags market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Thickness
- 1.2.1 Less than 50 GSM
- 1.2.2 50–120 GSM
- 1.2.3 Above 120 GSM
- 1.3 By Product Type
- 1.3.1 Flat Bags
- 1.3.2 Pinched-Bottom Bags
- 1.3.3 Self-Opening Style Bags
- 1.3.4 Handled Carrier Bags
- 1.3.5 SOS Bags
- 1.3.6 Luxury Paper Bags
- 1.4 By Material Type
- 1.4.1 Kraft Paper
- 1.4.2 Coated Paper
- 1.4.3 Recycled Paper
- 1.4.4 Specialty Paper
- 1.4.5 Bleached Paper
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 18,069.4 million → 2032: USD 27,106.3 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Paper Based Consumer Bags Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Paper Based Consumer Bags Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Paper Based Consumer Bags Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Paper Based Consumer Bags Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Paper Based Consumer Bags Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Paper Based Consumer Bags Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Paper Based Consumer Bags Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Paper Based Consumer Bags Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 18,069.4 million → 2032: USD 27,106.3 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Paper Based Consumer Bags Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Thickness - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Less than 50 GSM
- 12.3.7.2 50–120 GSM
- 12.3.7.3 Above 120 GSM
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Product Type - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Flat Bags
- 12.4.7.2 Pinched-Bottom Bags
- 12.4.7.3 Self-Opening Style Bags
- 12.4.7.4 Handled Carrier Bags
- 12.4.7.5 SOS Bags
- 12.4.7.6 Luxury Paper Bags
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Material Type - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Kraft Paper
- 12.5.7.2 Coated Paper
- 12.5.7.3 Recycled Paper
- 12.5.7.4 Specialty Paper
- 12.5.7.5 Bleached Paper
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global Paper Based Consumer Bags Geographic Market Outlook, 2024-2032
- 13.1 Regional Market Size and Share, 2024
- 13.2 Regional Market Forecast, 2024-2032
- 13.3 Regional Pricing, Production and Demand Differences
- 13.4 North America
- 13.4.1 United States
- 13.4.2 Canada
- 13.4.3 Mexico
- 13.5 Europe
- 13.5.1 Germany
- 13.5.2 France
- 13.5.3 Italy
- 13.5.4 United Kingdom
- 13.5.5 Spain
- 13.5.6 Poland
- 13.5.7 Russia
- 13.5.8 Netherlands
- 13.5.9 Belgium
- 13.5.10 Sweden
- 13.5.11 Denmark
- 13.5.12 Norway
- 13.5.13 Rest of Europe
- 13.6 Asia Pacific
- 13.6.1 China
- 13.6.2 India
- 13.6.3 Japan
- 13.6.4 South Korea
- 13.6.5 Thailand
- 13.6.6 Indonesia
- 13.6.7 Vietnam
- 13.6.8 Malaysia
- 13.6.9 Australia
- 13.6.10 Rest of Asia Pacific
- 13.7 Latin America
- 13.7.1 Brazil
- 13.7.2 Argentina
- 13.7.3 Colombia
- 13.7.4 Chile
- 13.7.5 Rest of Latin America
- 13.8 Middle East
- 13.8.1 Saudi Arabia
- 13.8.2 United Arab Emirates
- 13.8.3 Turkey
- 13.8.4 Israel
- 13.8.5 Iran
- 13.8.6 Rest of the Middle East
- 13.9 Africa
- 13.9.1 South Africa
- 13.9.2 Egypt
- 13.9.3 Nigeria
- 13.9.4 Morocco
- 13.9.5 Rest of Africa
- 13.10 Regional Investment, Policy and Supply Chain Differences
- 13.11 Regional Competitive Landscape
- 13.12 Geographic Growth Hotspots
Chapter 14 Global Paper Based Consumer Bags Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2024-2032
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 Global Paper Based Consumer Bags Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2024
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2024-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 International Paper Company
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 Oji Holdings
- 17.4 Mondi Plc
- 17.5 Smurfit Kappa
- 17.6 Stora Enso
- 17.7 Novolex
- 17.8 Atlantic Packaging
- 17.9 Ronpak
- 17.10 Langston Companies
- 17.11 Detmold Packaging
- 17.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

