
Market Overview
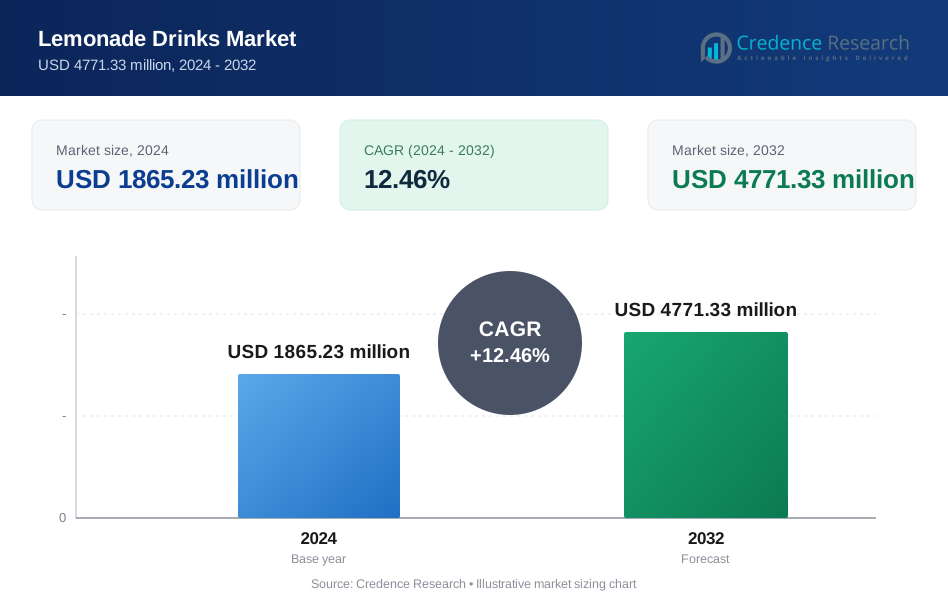
Lemonade Drinks market size was valued at USD 1865.23 million in 2024 and is anticipated to reach USD 4771.33 million by 2032, at a CAGR of 12.46% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2024 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Lemonade Drinks Market Size 2024 | USD 1865.23 Million |
| Lemonade Drinks Market, CAGR | 12.46% |
| Lemonade Drinks Market Size 2032 | USD 4771.33 Million |
The Lemonade Drinks market grows on the strength of rising health awareness, demand for natural ingredients, and expanding preference for low-sugar refreshment. It benefits from consumer shifts toward clean-label beverages and functional formulations that support hydration and wellness. Flavor innovation, seasonal demand, and convenience-focused packaging further accelerate adoption across demographics. Brands leverage organic sourcing, botanical infusions, and new product formats to enhance appeal and retain engagement.
The Lemonade Drinks market shows strong presence across North America, Europe, and Asia Pacific, with growing consumption in Latin America and the Middle East & Africa. North America leads innovation in spiked and functional lemonade products, while Europe emphasizes organic and botanical formulations. Asia Pacific demonstrates rising demand driven by urbanization and changing consumer lifestyles. Regional preferences influence flavor profiles and packaging formats, creating localized growth opportunities. Key players shaping the competitive landscape include Simply Beverages, Mike’s Hard Lemonade Co., and Snapple Beverages, each leveraging brand strength, product diversity, and wide distribution networks to sustain relevance across multiple regions.
Market Insights
- The Lemonade Drinks market was valued at USD 1865.23 million in 2024 and is projected to reach USD 4771.33 million by 2032, growing at a CAGR of 12.46% during the forecast period.
- Rising health awareness and demand for natural, low-sugar beverages drive increased consumption of lemonade products across both alcoholic and non-alcoholic categories.
- Functional enhancements such as probiotics, vitamins, and botanical infusions are shaping product innovation, with brands launching flavored, organic, and clean-label variants to meet evolving consumer expectations.
- The competitive landscape features established brands with extensive retail reach and smaller artisanal companies offering unique positioning through sustainability and regional appeal.
- Shelf life limitations, seasonal consumption patterns, and minimal product differentiation present operational and marketing challenges for both large and niche players.
- North America leads in innovation and volume consumption, while Asia Pacific and Europe exhibit high growth potential due to urbanization, retail expansion, and growing preference for health-oriented drinks.
- Companies focus on eco-friendly packaging, direct-to-consumer sales, and functional product lines to remain competitive and meet lifestyle-driven market shifts.

Market Drivers
Rising Health Awareness Fueling Demand for Natural Refreshments
Consumers increasingly prioritize low-calorie, natural beverages over carbonated or sugary soft drinks. The Lemonade Drinks market benefits from this shift as it offers products with simple ingredients such as lemon, water, and natural sweeteners. It appeals to health-conscious individuals seeking hydration and wellness without artificial additives. Companies leverage this preference by launching preservative-free and vitamin-fortified lemonade variants. Clean label trends further reinforce consumer trust in naturally formulated drinks. This momentum expands market reach across urban and semi-urban regions.
- For instance, Santa Cruz Organic expanded its lemonade range to include USDA-certified organic lemonades with no synthetic additives, achieving over 7.2 million units sold across U.S. retail chains.
Expanding Flavored Product Range Enhancing Consumer Engagement
Brands continuously diversify lemonade offerings with novel flavor combinations to capture broader audience interest. The Lemonade Drinks market responds to evolving tastes by introducing variants such as strawberry, mint, ginger, and cucumber-infused blends. It creates excitement among younger demographics and supports brand differentiation. Seasonal and limited-edition flavors increase product visibility and stimulate repeat purchases. Beverage manufacturers invest in flavor R&D to align with regional preferences and improve shelf appeal. This strategy strengthens consumer engagement and drives market expansion.
- For instance, Turkey Hill has introduced a Zero Sugar Lemonade within its fruit drink selection, available in both half-gallon and 18.5 oz sizes. This lemonade contains only 5 calories per 8-oz serving and has 0 grams of sugar, making it a low-calorie, sugar-free option.
Growing Preference for On-the-Go and Convenient Packaging Formats
Busy lifestyles push demand for portable and ready-to-consume beverage options. The Lemonade Drinks market adapts by offering single-serve bottles, tetra packs, and eco-friendly cans that cater to consumers seeking convenience. It aligns well with consumption patterns across workplaces, schools, gyms, and outdoor settings. Innovations in resealable packaging support multiple-use consumption and reduce spillage risks. Compact formats improve product placement in vending machines and retail coolers. This packaging shift increases product accessibility and supports higher retail penetration.
Expansion of Distribution Networks Across Online and Retail Channels
Wider availability through supermarkets, hypermarkets, cafes, and online platforms accelerates consumer access. The Lemonade Drinks market capitalizes on omnichannel strategies to build visibility and streamline sales. It benefits from online delivery platforms that enable direct-to-consumer reach with minimal logistics overhead. Retail partnerships allow cross-promotions and seasonal displays that attract foot traffic. Brand visibility improves through digital campaigns and influencer-driven product reviews. These efforts enhance consumer awareness and accelerate regional market growth.
Market Trends
Introduction of Functional Lemonade Driving Product Differentiation
Beverage manufacturers enhance lemonade with functional ingredients to meet wellness expectations. The Lemonade Drinks market witnesses launches that include electrolytes, probiotics, and adaptogens to support hydration, gut health, and stress relief. It allows brands to tap into the demand for multi-benefit beverages without altering the familiar taste profile. Functional lemonade appeals to consumers seeking purpose-driven refreshment during work, fitness, or recovery. This trend supports premium positioning and encourages repeat trials. It also opens collaboration opportunities with fitness centers and wellness-focused retailers.
- For instance, Me & the Bees Lemonade added two new flavors-Passion Fruit and Very Berry and reached placement in all 50 U.S. states.
Adoption of Organic and Locally Sourced Ingredients Gaining Traction
Consumers show rising preference for products made with organic and regionally sourced lemons. The Lemonade Drinks market incorporates this shift by emphasizing supply chain transparency and sustainable sourcing practices. It helps companies align with eco-conscious values and food safety concerns. Brands highlight origin stories and traceability to establish authenticity and build trust. This positioning resonates with premium buyers in metropolitan and health-forward markets. Product labels increasingly reflect certifications to strengthen shelf appeal and purchase intent.
- For instance, Me & the Bees Lemonade transitioned its entire line to sustainable packaging and, had expanded distribution into over 1,500 locations nationwide.
Growth in Craft and Small-Batch Lemonade Brands Targeting Niche Segments
Independent beverage companies focus on small-batch lemonade to deliver unique flavor experiences. The Lemonade Drinks market evolves to accommodate artisan-style production that emphasizes minimal processing and handmade appeal. It resonates with consumers who value exclusivity and storytelling behind their purchases. These brands use limited-run batches to test market responses and retain novelty. It encourages retailers to feature rotating stock and seasonal variants. Craft lemonade brands often operate through farmers’ markets, boutique stores, and direct-to-consumer platforms.
Rising Influence of Eco-Friendly Packaging on Purchase Decisions
Sustainability expectations drive the use of recyclable, compostable, or reusable packaging formats. The Lemonade Drinks market incorporates biodegradable cups, paper-based bottles, and aluminum cans to appeal to environmentally aware buyers. It supports corporate responsibility goals while reducing reliance on plastic. Brands display sustainability commitments prominently on packaging to influence shelf-based decisions. This trend gains strength in urban centers with higher green literacy and policy incentives. It pushes manufacturers to align design with environmental values without compromising functionality.
Market Challenges Analysis
Price Sensitivity and Low Product Differentiation Limiting Brand Loyalty
Intense competition among beverage brands drives price sensitivity across retail and online channels. The Lemonade Drinks market faces pressure to offer competitive pricing while maintaining product quality. It often results in reduced margins for smaller players that lack economies of scale. Minimal product differentiation across lemon-based drinks makes it difficult for consumers to perceive brand value. This challenge reduces customer retention and increases reliance on promotional discounts. Brands must invest in flavor innovation or packaging design to stand out without raising costs significantly.
Short Shelf Life and Seasonal Demand Disrupting Inventory Planning
Fresh ingredients and natural formulations reduce the shelf life of lemonade-based beverages. The Lemonade Drinks market struggles to balance production volume with fluctuating demand during colder months. It leads to inventory losses or stock shortages depending on the season. Storage and transportation of preservative-free lemonade require cold chain infrastructure, which increases operational complexity. Retailers may deprioritize shelf space for lemonade products during off-peak periods. This inconsistency forces producers to adapt logistics and marketing strategies to avoid revenue gaps.
Market Opportunities
Rising Demand for Clean Label and Low-Sugar Beverages Creating New Segments
Consumer demand for healthier refreshment options creates strong growth potential for transparent and low-sugar formulations. The Lemonade Drinks market can expand by offering products that meet clean label standards with natural sweeteners such as stevia or agave. It aligns with dietary shifts toward reduced sugar intake and fewer artificial additives. Beverage companies have the opportunity to position lemonade as both indulgent and health-conscious. This enables access to fitness-focused consumers and individuals managing lifestyle-related conditions. Brands that promote nutritional clarity and ingredient simplicity gain trust and wider adoption.
Untapped Growth Potential in Emerging Economies with Tropical Climates
Expanding middle-class populations and warm climates across Southeast Asia, Africa, and Latin America create fertile ground for market penetration. The Lemonade Drinks market can grow its footprint by targeting regions where year-round heat drives strong demand for affordable hydration. It benefits from local sourcing of citrus fruits, which reduces input costs and appeals to community-focused values. Distribution partnerships with regional retail chains and foodservice operators offer scalable entry strategies. Companies that adapt pricing and flavor profiles to local preferences can capture market share rapidly. Demand from urbanizing populations supports long-term consumption stability.
Market Segmentation Analysis:
By Type:
The Lemonade Drinks market includes three key variants-Cloudy Lemonade, Pink Lemonade, and Clear Lemonade. Cloudy Lemonade holds strong consumer appeal due to its traditional formulation and use of real lemon pulp, often perceived as more natural. It performs well in both retail and foodservice settings. Pink Lemonade attracts younger demographics and trend-driven buyers with its visual appeal and mild sweetness. Clear Lemonade, with its filtered and transparent composition, appeals to consumers seeking a cleaner aesthetic and lighter flavor. It finds favor in premium dining and wellness-oriented channels.
- For instance, during a 52-week period, Mike's Hard Lemonade sold 7.7 million cases, while Mike's Harder sold 8.6 million cases, according to IRI data. This indicates that Mike's Harder had higher case sales than Mike's Hard Lemonade in that timeframe.
By Product Type:
Alcoholic lemonade products represent a growing segment driven by demand for light and refreshing ready-to-drink alcoholic beverages. The Lemonade Drinks market benefits from innovation in hard lemonade cocktails, which blend citrus flavor with low-ABV formats. Non-Alcoholic lemonade remains the dominant category, supported by its broad appeal across all age groups. Carbonated variants target consumers seeking fizzy refreshment, especially in warmer climates and entertainment venues. Un-Carbonated lemonade provides a smoother taste experience and is popular in health-conscious segments. Others, including powder mix formulations, offer convenience and extended shelf life, appealing to budget buyers and institutional use.
- For instance, Bionade-a non-alcoholic fermented soft drink-grew sales from two million bottles in 2003 to 70 million bottles by 2006 in Germany, showcasing rising demand for health-oriented, non-carbonated beverages.
By Packaging:
Glass bottles serve the premium and eco-conscious segment, offering aesthetic value and recyclability. The Lemonade Drinks market uses glass packaging to differentiate artisanal or organic variants. PET bottles dominate mass retail due to affordability, lightweight properties, and widespread availability. Retort packaging, known for its thermal processing advantages, supports extended shelf life without preservatives, making it suitable for export markets. Cans cater to on-the-go consumers and ensure portability with minimal risk of breakage. It enables brands to penetrate convenience stores and vending machine channels effectively.
Segments:
Based on Type:
- Cloudy Lemonade
- Pink Lemonade
- Clear Lemonade
Based on Product Type:
- Alcoholic
- Non-Alcoholic
- Carbonated
- Un-Carbonated
- Others (Powder Mix)
Based on Packaging:
- Glass Bottle
- PET Bottle
- Retort Packaging
- Can
Based on Distribution Channel:
- E-commerce
- Supermarkets/Hypermarkets
- Departmental Stores
- Convenience Stores
- Others
Based on the Geography:
- North America
- U.S.
- Canada
- Mexico
- Europe
- UK
- France
- Germany
- Italy
- Spain
- Russia
- Belgium
- Netherlands
- Austria
- Sweden
- Poland
- Denmark
- Switzerland
- Rest of Europe
- Asia Pacific
- China
- Japan
- South Korea
- India
- Australia
- Thailand
- Indonesia
- Vietnam
- Malaysia
- Philippines
- Taiwan
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Peru
- Chile
- Colombia
- Rest of Latin America
- Middle East
- UAE
- KSA
- Israel
- Turkey
- Iran
- Rest of Middle East
- Africa
- Egypt
- Nigeria
- Algeria
- Morocco
- Rest of Africa
Regional Analysis
North America
North America holds the largest share in the Lemonade Drinks market, accounting for 34.2% of global consumption. The region shows sustained demand driven by health-conscious consumers and wide retail availability across the United States and Canada. It benefits from a mature beverage industry that supports continuous product innovation, including organic, low-sugar, and functional lemonade variants. Brands such as Minute Maid and Simply Lemonade maintain strong shelf presence through diversified flavor portfolios and multi-channel distribution. It capitalizes on seasonal consumption peaks during summer months, where lemonade serves both as a refreshment and a mixer in alcoholic beverages. The presence of established supply chains, cold storage infrastructure, and aggressive marketing campaigns further strengthen market dominance in this region.
Europe
Europe represents 25.8% of the global Lemonade Drinks market, driven by rising demand for natural beverages and premium refreshment categories. The market shows steady consumption patterns in the UK, Germany, France, and Nordic countries. It reflects consumer preference for carbonated lemonade varieties and clean-label beverages free from artificial preservatives. European manufacturers focus on sourcing organic lemons and incorporating botanical infusions to meet evolving wellness expectations. The region experiences seasonal demand but maintains stable year-round sales through café culture and multipurpose beverage use. It benefits from well-regulated food safety standards and an expanding network of supermarkets, specialty stores, and on-premise beverage channels.
Asia Pacific
Asia Pacific holds 18.7% of the global Lemonade Drinks market, supported by growing urbanization, rising disposable incomes, and a young population base. Countries such as China, India, Japan, and Australia contribute significantly through both domestic production and imports. It reflects rising adoption of international beverage trends, including low-calorie and vitamin-enriched lemonade options. Retail expansion and digital commerce platforms improve accessibility to both global and local lemonade brands. The region shows strong growth potential due to its year-round warm climate, where cold beverages maintain consistent demand. Manufacturers invest in cost-effective packaging formats to suit price-sensitive markets while adapting flavor profiles to regional preferences.
Latin America
Latin America accounts for 11.3% of the global Lemonade Drinks market, driven by the region’s tropical climate and strong cultural affinity for citrus-based beverages. Brazil and Mexico serve as major consumption hubs where local lemonade variants often incorporate native fruits and spices. It leverages growing supermarket chains and local beverage stalls that support volume sales. Lemonade is frequently consumed as a refreshment in foodservice, boosting its presence in restaurants, cafes, and street vendors. Domestic brands compete with global players through affordability and regional branding strategies. Rising health awareness contributes to gradual shifts toward less sugary formulations across urban centers.
Middle East & Africa
The Middle East & Africa represent 10.0% of the global Lemonade Drinks market, primarily influenced by high ambient temperatures and growing demand for non-alcoholic refreshments. Gulf countries exhibit strong preference for cold, citrus-based drinks during extended summer seasons. It benefits from increasing penetration of modern retail formats in the UAE, Saudi Arabia, and South Africa. Lemonade is widely consumed during social gatherings and religious occasions, supporting both seasonal and routine purchases. Local producers focus on affordability and simple formulations to appeal to middle-income consumers. The market shows steady growth with opportunities to expand through export-led partnerships and localized packaging innovations.
Key Player Analysis
- Prairie Farms Dairy Inc.
- Keurig Dr Pepper, Inc.
- Turkey Hill
- Me And The Bees Lemonade
- Simply Beverages
- Country Time
- Hydro One Beverages
- Mike’s Hard Lemonade Co.
- Lori’s Original Lemonade, LLC
- Whole Foods Market
- Newman’s Own
- Santa Cruz Organic
- Snapple Beverages
- Hubert’s Lemonade
Competitive Analysis
Simply Beverages, Country Time, Santa Cruz Organic, Mike’s Hard Lemonade Co., Snapple Beverages, Newman’s Own, Whole Foods Market, Hydro One Beverages, Me and the Bees Lemonade, Hubert’s Lemonade, Turkey Hill, Lori’s Original Lemonade, LLC, Keurig Dr Pepper, Inc., Prairie Farms Dairy Inc.These market leaders operate in a highly competitive environment where scale, consumer health trends, and innovation shape differentiation. Traditional giants like Simply Beverages, Keurig Dr Pepper, and Snapple leverage extensive distribution networks and brand equity to maintain high visibility across mass retail and grocery channels. These companies push product expansion through clean‑label and functional variants, attracting wellness-oriented consumers.Craft and niche brands-such as Me and the Bees Lemonade and Lori’s Original Lemonade, LLC-gain traction by delivering authentic, artisanal experiences. They stand out through storytelling and localized flavors that resonate with health-conscious and socially aware buyers, especially in digital and direct‑to‑consumer channels.Ready-to-drink alcohol options from Mike’s Hard Lemonade Co. allow the brand to tap into the growing low-ABV cocktail segment, offering an alternative to non-alcoholic lemonade and appealing to adult consumers seeking novelty with convenience. Meanwhile, private-label operators like Whole Foods Market and Hydro One Beverages focus on quality control and transparency to boost consumer trust, especially under store brand positioning.Diversified players like Keurig Dr Pepper and Prairie Farms Dairy Inc. benefit from cross-category synergies. They integrate lemonade into broader beverage portfolios to maximize scale, achieve cost efficiencies, and support seasonal promotions.
Recent Developments
- In June 2025, Turkey Hill Launched Turkey Hill Hard Iced Tea (which includes a Lemon flavor) in a collaboration with Scarlet Letter Beverage Co., time for National Iced Tea Day. Available in variety pack at select stores.
- In 2025, Prairie Farms Dairy Inc. Announced a major partnership with Alex's Lemonade Stand Foundation for Childhood Cancer™, rolling out special lemonade packaging and donating a portion of sales to childhood cancer research across participating retailers in the Midwest.
- In 2025, Keurig Dr Pepper, Inc. Released several new lemonade and lemon-flavored products, including Snapple Peach Tea & Lemonade and expanded the flavor portfolio for 2025 with other brands like Dr Pepper and 7UP.
Market Concentration & Characteristics
The Lemonade Drinks market displays a moderately fragmented structure, characterized by a mix of multinational beverage corporations and regionally focused artisanal brands. It operates across diverse product lines that include non-alcoholic, alcoholic, organic, and functional variants, allowing broad appeal across age groups and consumption settings. Large-scale players dominate shelf presence through widespread retail distribution, strategic pricing, and established brand equity, while emerging brands target niche segments with clean-label formulations and localized flavors. It shows seasonal demand patterns, with peak sales during warmer months, although functional and canned variants help stabilize year-round consumption. Consumer preference for low-sugar, preservative-free, and sustainable products influences formulation and packaging decisions across all market tiers. It also reflects dynamic innovation cycles, where frequent flavor introductions and cross-category integrations keep competition active and market positioning fluid.
Report Coverage
The research report offers an in-depth analysis based on Type, Product Type, Packaging, Distribution Channel and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Demand for low-sugar and clean-label lemonade products will continue to increase across global markets.
- Functional lemonade with added electrolytes, probiotics, and vitamins will gain traction among health-conscious consumers.
- Ready-to-drink alcoholic lemonade options will expand within the adult beverage segment.
- Brands will adopt eco-friendly packaging such as aluminum cans and biodegradable materials to align with sustainability goals.
- Online retail and direct-to-consumer platforms will strengthen as preferred distribution channels for specialty lemonade products.
- Regional flavors and limited-edition variants will drive seasonal sales and customer engagement.
- Private label offerings and store-brand lemonades will grow within supermarket and hypermarket formats.
- Technological advancements in cold chain logistics will support wider distribution of preservative-free lemonade.
- Collaborations with wellness brands and influencers will enhance visibility and market penetration.
- Emerging markets in Asia, Latin America, and the Middle East will offer significant expansion opportunities for global and local players.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Rising Health Awareness Fueling Demand for Natural Refreshments
Consumers are increasingly seeking beverages with simple, natural ingredients and lower sugar content, driving demand for lemonade drinks that offer hydration and wellness benefits without artificial additives. This trend is reinforced by clean-label preferences and the launch of preservative-free, vitamin-fortified lemonade variants.
Expanding Flavored Product Range Enhancing Consumer Engagement
Brands are innovating with new lemonade flavors such as strawberry, mint, and ginger, appealing to younger demographics and supporting brand differentiation. Seasonal and limited-edition flavors stimulate repeat purchases and broaden the market’s appeal.
Growing Preference for On-the-Go and Convenient Packaging Formats
Busy lifestyles are increasing demand for portable, single-serve lemonade options in bottles, cans, and tetra packs, making the product more accessible in workplaces, schools, gyms, and outdoor settings. Innovations in packaging also support retail penetration and reduce spillage risks.
Expansion of Distribution Networks Across Online and Retail Channels
The market benefits from omnichannel strategies, with lemonade drinks becoming widely available through supermarkets, hypermarkets, cafes, and online platforms. This expanded reach increases consumer access and accelerates regional market growth.
Introduction of Functional and Organic Lemonade Variants
Manufacturers are launching lemonade drinks with added functional ingredients like probiotics, vitamins, and electrolytes, as well as emphasizing organic and locally sourced lemons. These innovations meet evolving consumer expectations for wellness and sustainability, supporting premium positioning and market expansion.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Lemonade Drinks market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Lemonade Drinks Market projected to grow between 2025 and 2032?
Which Lemonade Drinks market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Lemonade Drinks market?
Who are the leading companies in the Lemonade Drinks Market?
Which region commanded the largest share of the Lemonade Drinks market in 2024?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Type
- 1.2.1 Cloudy Lemonade
- 1.2.2 Pink Lemonade
- 1.2.3 Clear Lemonade
- 1.3 By Packaging
- 1.3.1 Glass Bottle
- 1.3.2 PET Bottle
- 1.3.3 Retort Packaging
- 1.3.4 Can
- 1.4 By Product Type
- 1.4.1 Alcoholic
- 1.4.2 Non-Alcoholic
- 1.4.3 Carbonated
- 1.4.4 Un-Carbonated
- 1.4.5 Others (Powder Mix)
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 1865.23 million → 2032: USD 4771.33 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Lemonade Drinks Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Lemonade Drinks Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Lemonade Drinks Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Lemonade Drinks Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Lemonade Drinks Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Lemonade Drinks Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Lemonade Drinks Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Lemonade Drinks Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 1865.23 million → 2032: USD 4771.33 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Lemonade Drinks Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Type - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Cloudy Lemonade
- 12.3.7.2 Pink Lemonade
- 12.3.7.3 Clear Lemonade
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Packaging - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Glass Bottle
- 12.4.7.2 PET Bottle
- 12.4.7.3 Retort Packaging
- 12.4.7.4 Can
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Product Type - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Alcoholic
- 12.5.7.2 Non-Alcoholic
- 12.5.7.3 Carbonated
- 12.5.7.4 Un-Carbonated
- 12.5.7.5 Others (Powder Mix)
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global Lemonade Drinks Geographic Market Outlook, 2024-2032
- 13.1 Regional Market Size and Share, 2024
- 13.2 Regional Market Forecast, 2024-2032
- 13.3 Regional Pricing, Production and Demand Differences
- 13.4 North America
- 13.4.1 United States
- 13.4.2 Canada
- 13.4.3 Mexico
- 13.5 Europe
- 13.5.1 Germany
- 13.5.2 France
- 13.5.3 Italy
- 13.5.4 United Kingdom
- 13.5.5 Spain
- 13.5.6 Poland
- 13.5.7 Russia
- 13.5.8 Netherlands
- 13.5.9 Belgium
- 13.5.10 Sweden
- 13.5.11 Denmark
- 13.5.12 Norway
- 13.5.13 Rest of Europe
- 13.6 Asia Pacific
- 13.6.1 China
- 13.6.2 India
- 13.6.3 Japan
- 13.6.4 South Korea
- 13.6.5 Thailand
- 13.6.6 Indonesia
- 13.6.7 Vietnam
- 13.6.8 Malaysia
- 13.6.9 Australia
- 13.6.10 Rest of Asia Pacific
- 13.7 Latin America
- 13.7.1 Brazil
- 13.7.2 Argentina
- 13.7.3 Colombia
- 13.7.4 Chile
- 13.7.5 Rest of Latin America
- 13.8 Middle East
- 13.8.1 Saudi Arabia
- 13.8.2 United Arab Emirates
- 13.8.3 Turkey
- 13.8.4 Israel
- 13.8.5 Iran
- 13.8.6 Rest of the Middle East
- 13.9 Africa
- 13.9.1 South Africa
- 13.9.2 Egypt
- 13.9.3 Nigeria
- 13.9.4 Morocco
- 13.9.5 Rest of Africa
- 13.10 Regional Investment, Policy and Supply Chain Differences
- 13.11 Regional Competitive Landscape
- 13.12 Geographic Growth Hotspots
Chapter 14 Global Lemonade Drinks Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2024-2032
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 Global Lemonade Drinks Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2024
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2024-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Simply Beverages
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 Mike’s Hard Lemonade Co.
- 17.4 Snapple Beverages
- 17.5 Turkey Hill
- 17.6 Santa Cruz Organic
- 17.7 Keurig Dr Pepper, Inc.
- 17.8 Me And The Bees Lemonade
- 17.9 Country Time
- 17.10 Whole Foods Market
- 17.11 Prairie Farms Dairy Inc.
- 17.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

