
Market Overview
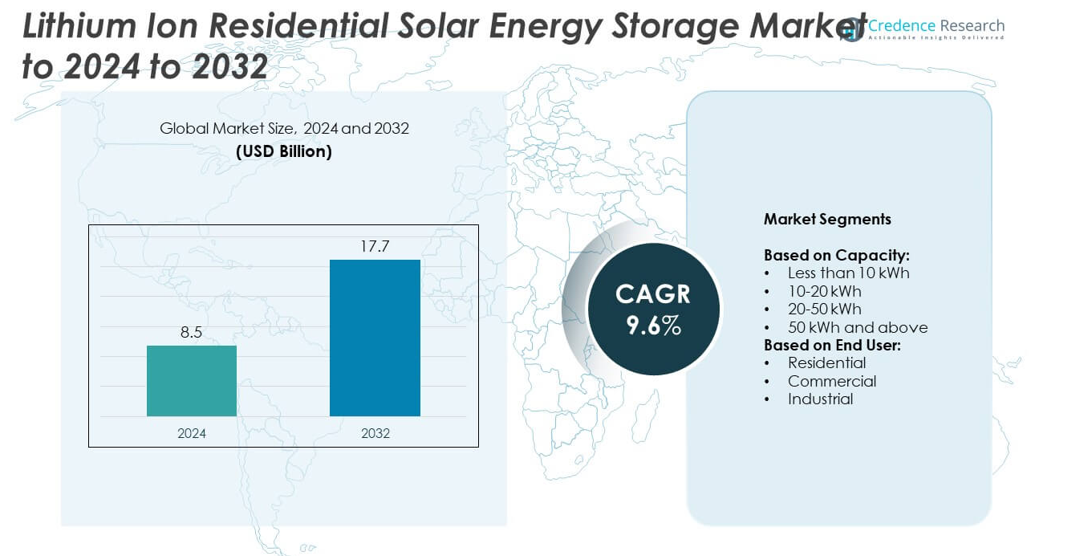
The Lithium Ion Residential Solar Energy Storage Market size was valued at USD 8.5 Billion in 2024 and is anticipated to reach USD 17.7 Billion by 2032, at a CAGR of 9.6% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Lithium Ion Residential Solar Energy Storage Market Size 2024 | USD 8.5 Billion |
| Lithium Ion Residential Solar Energy Storage Market, CAGR | 9.6% |
| Lithium Ion Residential Solar Energy Storage Market Size 2032 | USD 17.7 Billion |
The lithium-ion residential solar energy storage market is shaped by leading players such as Toshiba Corporation, Enphase Energy, Schneider Electric, Tesla, Johnson Controls, Huawei Technologies, LG Electronics, Samsung SDI, Fluence, and ABB. These companies focus on innovation in battery performance, integration with smart home technologies, and expansion across emerging markets to strengthen their competitive positions. North America emerged as the leading region in 2024, commanding a 35% share, driven by strong policy support, high rooftop solar adoption, and frequent grid outages. Europe followed with 28% share, supported by carbon neutrality targets, while Asia-Pacific held 25%, reflecting rapid solar deployment and favorable government incentives.
Market Insights
- The lithium-ion residential solar energy storage market was valued at USD 8.5 Billion in 2024 and is projected to reach USD 17.7 Billion by 2032, growing at a CAGR of 9.6%.
- Rising rooftop solar adoption, government incentives, and technological advancements in lithium-ion batteries are driving strong demand in residential applications.
- Key trends include integration with smart home systems, participation in virtual power plants, and increasing focus on recycling and sustainability for long-term growth.
- The market is competitive with global players focusing on product innovation, partnerships, and regional expansion to capture growing opportunities, particularly in North America, Europe, and Asia-Pacific.
- North America led with 35% share in 2024, followed by Europe at 28% and Asia-Pacific at 25%, while the 10–20 kWh capacity segment dominated with over 40% share due to strong adoption in single-family households seeking reliable energy storage solutions.
Market Segmentation Analysis:
By Capacity
In 2024, the 10–20 kWh segment dominated the lithium-ion residential solar energy storage market with over 40% share. Its leadership is attributed to strong adoption in single-family households that require moderate backup capacity for lighting, appliances, and EV charging. These systems balance affordability with performance, making them ideal for mainstream residential users. The growth of rooftop solar installations, coupled with rising electricity tariffs and increasing demand for self-sufficiency, further drives adoption. Larger segments like 20–50 kWh are gaining traction in premium homes, but remain secondary to 10–20 kWh solutions.
- For instance, Sonnen manufactures a range of home battery solutions, including the SonnenCore and SonnenBatterie, with scalable storage options. The SonnenCore is built around 5 kWh battery modules, allowing for various system capacities.
By End User
The residential segment accounted for more than 65% share of the market in 2024, leading over commercial and industrial users. Rising consumer focus on energy independence, combined with incentives for solar-plus-storage installations, has accelerated residential uptake. Government subsidies, net metering programs, and smart home integration support market penetration. Consumers increasingly seek systems that reduce reliance on grids, especially during outages and peak demand periods. While commercial and industrial applications are growing, residential demand remains dominant due to widespread adoption of rooftop solar and advancements in compact lithium-ion storage systems.
- For instance, in 2023, Hanwha Qcells demonstrated strong leadership in the U.S. residential solar market by achieving a 35% market share for the first quarter, according to a Wood Mackenzie report.
Key Growth Drivers
Rising Residential Solar Installations
The rapid adoption of rooftop solar systems is the key growth driver for the lithium-ion residential solar energy storage market. Homeowners are increasingly investing in solar-plus-storage solutions to maximize self-consumption and reduce dependency on traditional power grids. Declining solar panel costs, favorable policies, and growing awareness of renewable energy benefits support this trend. As more households adopt distributed solar energy systems, the demand for lithium-ion storage rises significantly. This integration ensures reliable backup power, enhances energy security, and reduces electricity bills, making it a central driver of market expansion.
- For instance, Sunrun significantly increased its storage installations in 2023, with its total installed storage capacity reaching 1.3 gigawatt-hours by the end of the year, representing an increase from 1.1 gigawatt-hours in Q3.
Government Incentives and Energy Policies
Supportive policies and subsidies are vital in accelerating market penetration of lithium-ion residential solar storage. Many governments provide tax credits, feed-in tariffs, and net metering programs that lower the upfront cost of installations. These incentives make storage solutions more affordable for residential consumers while encouraging sustainable energy practices. Strong policy support in regions like North America, Europe, and Asia-Pacific enhances adoption. Additionally, decarbonization targets and climate action plans push households toward storage adoption. These initiatives continue to position lithium-ion storage as a practical and attractive investment.
- For instance, according to a SunWiz report, a record 57,000 residential battery energy storage systems were installed in Australian homes in 2023, up 21% from the previous year, with a combined capacity of 656 MWh.
Advancements in Lithium-Ion Technology
Continuous improvements in lithium-ion battery technology drive cost reductions and performance enhancements. Higher energy density, longer cycle life, and compact designs make these systems increasingly suitable for residential use. Manufacturers are investing heavily in R&D to deliver efficient, safe, and reliable storage solutions. Falling battery costs over the past decade have made lithium-ion more competitive compared to alternatives like lead-acid. These advancements ensure broader accessibility for homeowners and stimulate market growth. The combination of efficiency improvements and declining costs makes technology development a crucial growth driver.
Key Trends & Opportunities
Integration with Smart Homes and IoT
The integration of lithium-ion storage with smart home systems presents significant opportunities. Advanced monitoring platforms allow homeowners to optimize energy usage, track consumption patterns, and control storage through mobile apps. IoT-enabled solutions enhance user experience and enable predictive maintenance. This trend aligns with the rise of connected living and energy-efficient smart homes. The ability to integrate storage with EV charging infrastructure further broadens opportunities. As digital technologies expand, the convergence of storage with smart platforms strengthens adoption and creates new growth avenues in residential energy markets.
- For instance, Huawei reported in 2023 that its FusionSolar Smart PV Management system connected over 3.3 million residential units globally, integrating storage and monitoring functions.
Emergence of Virtual Power Plants (VPPs)
The growing adoption of virtual power plants represents a key trend shaping the market. Residential lithium-ion storage systems can be aggregated into VPPs, allowing households to sell excess power back to the grid. This model increases grid stability, reduces peak demand, and generates additional income for homeowners. Utilities are increasingly encouraging participation in VPP programs, creating financial incentives for residential users. The rise of decentralized energy management and demand response initiatives makes VPPs a promising opportunity. This trend supports grid modernization and enhances the value proposition of home storage systems.
- For instance, Octopus Energy's Kraken platform significantly expanded its management of distributed energy resources in 2023. By April 2023, KrakenFlex (now part of the Kraken platform) had increased the number of assets it managed by more than fourfold, from 37,000 to 212,000, contributing to nearly 2.9 GW of flexible capacity.
Key Challenges
High Upfront Costs
Despite falling battery prices, high upfront costs remain a major barrier to widespread adoption. The initial investment in solar-plus-storage systems often exceeds affordability for average households, particularly in emerging economies. Financing solutions, leasing models, and subsidies help bridge this gap, but cost remains a limiting factor. Price sensitivity among residential consumers slows adoption, even in regions with strong policy support. Overcoming this challenge requires further price reductions, innovative financing, and expanded government support to make lithium-ion storage solutions more accessible to middle-income households.
Battery Recycling and Environmental Concerns
The challenge of recycling lithium-ion batteries raises sustainability and environmental concerns. Growing adoption leads to an increase in end-of-life storage systems, which require safe disposal or recycling. The limited availability of large-scale recycling infrastructure and the environmental impact of mining lithium and cobalt intensify the issue. Without effective recycling processes, the market faces criticism over its long-term sustainability. Addressing this challenge requires advancements in recycling technologies, regulatory frameworks, and circular economy practices to ensure environmentally responsible growth of the lithium-ion residential solar energy storage market.
Regional Analysis
North America
North America held the largest share of the lithium-ion residential solar energy storage market in 2024, accounting for around 35%. The region benefits from strong government incentives, net metering policies, and rising adoption of rooftop solar. The U.S. leads demand, supported by programs like the Investment Tax Credit (ITC) that reduce installation costs. Growing energy independence concerns, frequent grid outages, and integration with smart home systems further fuel adoption. Canada is also witnessing steady growth, driven by decarbonization targets and supportive renewable energy initiatives. The region’s focus on sustainability and advanced technologies ensures continued market leadership.
Europe
Europe accounted for nearly 28% share of the market in 2024, driven by stringent renewable energy targets and strong policy support. Countries such as Germany, Italy, and the UK lead adoption, supported by subsidies and feed-in tariffs. The push for carbon neutrality by 2050 accelerates residential solar-plus-storage deployment. Homeowners adopt lithium-ion storage to optimize self-consumption and reduce reliance on centralized grids. Growing interest in virtual power plants and energy communities enhances uptake. The region’s mature renewable infrastructure and regulatory frameworks position Europe as a key growth hub, with rising demand expected over the forecast period.
Asia-Pacific
Asia-Pacific captured about 25% share in 2024, emerging as one of the fastest-growing regions. Strong demand in countries like China, Japan, Australia, and India drives the market. Rising electricity costs, high rooftop solar installations, and government-backed incentives encourage households to adopt lithium-ion storage. Australia leads in residential adoption, with widespread deployment supported by battery rebate programs. China’s growing renewable energy push and Japan’s emphasis on energy security further expand the market. Increasing urbanization and frequent power outages in developing nations also support growth. Asia-Pacific is expected to record the fastest CAGR through 2032.
Latin America
Latin America held an 8% market share in 2024, with growth led by countries like Brazil, Mexico, and Chile. Rising electricity prices and increasing solar adoption drive the uptake of lithium-ion residential storage systems. Governments are expanding renewable energy programs and offering incentives to encourage household adoption. Brazil leads installations with strong solar potential and favorable regulations, while Mexico benefits from community-based solar initiatives. Although adoption is lower compared to developed regions, growing awareness of energy independence and decreasing storage costs provide opportunities. The region is set to witness steady growth during the forecast period.
Middle East and Africa
The Middle East and Africa accounted for 4% share of the market in 2024, representing the smallest but steadily growing region. High solar potential across countries like the UAE, Saudi Arabia, and South Africa drives demand. Governments are investing in residential solar projects as part of diversification and sustainability strategies. Energy security concerns and frequent power outages, particularly in parts of Africa, push adoption. However, high upfront costs and limited policy support restrain faster penetration. As financing solutions expand and technology costs decline, the region is expected to gain traction in the coming years.
Market Segmentations:
By Capacity:
- Less than 10 kWh
- 10-20 kWh
- 20-50 kWh
- 50 kWh and above
By End User:
- Residential
- Commercial
- Industrial
By Geography:
- orth America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
The competitive landscape of the lithium-ion residential solar energy storage market features prominent players such as Toshiba Corporation, Enphase Energy, Schneider Electric, Tesla, Johnson Controls, Maxwell Technologies, Huawei Technologies, LG Electronics, Saft, EnerSys, SolarEdge Technologies, Honeywell International, Primus Power, Samsung SDI, Uniper, Leclanché, Fluence, Siemens Energy, and ABB. These companies are focusing on advancing lithium-ion battery technologies with higher efficiency, longer life cycles, and compact designs to meet residential demands. Strategic initiatives include product innovations, collaborations with solar providers, and integration of storage systems with smart home solutions. Many players are also leveraging government policies and incentives to expand their footprint in high-growth regions like North America, Europe, and Asia-Pacific. Sustainability efforts, including recycling solutions and environmentally responsible supply chains, are gaining momentum. The competition remains intense, with companies striving to balance affordability, performance, and reliability while catering to the increasing global demand for decentralized clean energy solutions.
Key Player Analysis
- Toshiba Corporation
- Enphase Energy
- Schneider Electric
- Tesla
- Johnson Controls
- Maxwell Technologies
- Huawei Technologies
- LG Electronics
- Saft
- EnerSys
- SolarEdge Technologies
- Honeywell International
- Primus Power
- Samsung SDI
- Uniper
- Leclanché
- Fluence
- Siemens Energy
- ABB
Recent Developments
- In 2025, LG Energy Announced a major supply deal with Tesla in the U.S. for LFP batteries for energy storage systems (ESS).
- In 2025, Enphase Energy Introduced the IQ Battery 5P with FlexPhase in numerous European market, to offer flexible backup and phase-switching capabilities.
- In 2024, Tesla's strategy in the integrated residential solar energy storage market focused on launching the Powerwall 3 and expanding its flexibility to capture more market share amidst increased competition and a contracting US solar market.
Report Coverage
The research report offers an in-depth analysis based on Capacity, End-User and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The market will expand steadily, supported by rising rooftop solar adoption worldwide.
- Residential demand will dominate as households seek energy independence and backup power.
- Advancements in lithium-ion technology will lower costs and improve storage efficiency.
- Government incentives and renewable energy policies will continue to accelerate adoption.
- Integration with smart home systems will enhance monitoring and energy management.
- Virtual power plant participation will provide homeowners with new revenue opportunities.
- Recycling and sustainability practices will become critical for long-term market growth.
- Asia-Pacific will record the fastest growth, driven by strong policy and solar adoption.
- North America and Europe will remain major markets due to mature infrastructure.
- Financing models and leasing programs will make storage systems more accessible.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Lithium Ion Residential Solar Energy Storage Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Lithium Ion Residential Solar Energy Storage Market projected to grow between 2025 and 2032?
Which Lithium Ion Residential Solar Energy Storage Market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Lithium Ion Residential Solar Energy Storage Market?
Who are the leading companies in the Lithium Ion Residential Solar Energy Storage Market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue) (Volume Where Applicable)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Lithium Ion Residential Solar Energy Storage Scope – Segments & Subsegments Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 Industry Classification & Applicable Codes
- 1.5 Currency, Measurement Units & Valuation Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Lithium Ion Residential Solar Energy Storage Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 8.5 Billion → 2032: USD 17.7 Billion)
- 2.1.2 Volume & Revenue – Global Totals (Volume Where Applicable)
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Lithium Ion Residential Solar Energy Storage Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024 (Volume Where Applicable)
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Lithium Ion Residential Solar Energy Storage Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Lithium Ion Residential Solar Energy Storage Market Position in the Broader Industry Value Chain
- 3.1.2 Demand Structure & Purchasing Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Lithium Ion Residential Solar Energy Storage Market Drivers
- 3.3 Lithium Ion Residential Solar Energy Storage Market Restraints & Challenges
- 3.4 Lithium Ion Residential Solar Energy Storage Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Lithium Ion Residential Solar Energy Storage Value Chain Analysis
- 3.6.1 Upstream – Key Inputs, Resources & Suppliers
- 3.6.1.1 Key Input/Resource 1
- 3.6.1.2 Key Input/Resource 2
- 3.6.1.3 Key Input/Resource 3
- 3.6.2 Midstream – Core Operations & Value Creation
- 3.6.2.1 Operating Model & Process Overview
- 3.6.2.2 Key Operating Locations & Capabilities by Company
- 3.6.3 Downstream – Market Channels & End Users
- 3.6.3.1 Direct Sales & Customer Engagement Channels
- 3.6.3.2 Indirect Sales, Intermediaries & Partner Channels
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Key Inputs, Resources & Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Lithium Ion Residential Solar Energy Storage Supply Chain Analysis
- 3.8.1 Critical Input & Resource Availability Risk Assessment
- 3.8.2 Supplier & Operational Concentration Risk (Geographic Exposure)
- 3.8.3 Supply & Service Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Lithium Ion Residential Solar Energy Storage category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Lithium Ion Residential Solar Energy Storage Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Market Size × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute Revenue Growth Through 2032
- 4.3 Incremental Demand Opportunity
- 4.3.1 By Region – Incremental Demand Through 2032
- 4.3.2 Segment – Incremental Demand
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Priority Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Priority market opportunity scorecards reflect the geographic scope and strategic relevance of the study. Listed markets are indicative and may be adapted to the industry.
Chapter 5. Lithium Ion Residential Solar Energy Storage Cross-Border Trade & Market Access Analysis
- 5.1 International Trade & Cross-Border Activity Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024) (Volume Where Applicable)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024) (Volume Where Applicable)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Category 1 (Applicable Classification Code)
- 5.2.2 Category 2 (Applicable Classification Code)
- 5.2.3 Category 3 (Applicable Classification Code)
- 5.2.4 Category 4 (Applicable Classification Code)
- 5.2.5 Category 5 (Applicable Classification Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Category 1 (Applicable Classification Code)
- 5.3.2 Category 2 (Applicable Classification Code)
- 5.3.3 Category 3 (Applicable Classification Code)
- 5.3.4 Category 4 (Applicable Classification Code)
- 5.3.5 Category 5 (Applicable Classification Code)
- 5.4 Cross-Border Pricing & Transaction Benchmarks
- 5.4.1 Export Pricing – Segment & Country
- 5.4.2 Import Pricing – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Cross-Border Trade & Delivery Routes
- 5.5.1 Cross-Border Trade/Delivery Route 1
- 5.5.2 Cross-Border Trade/Delivery Route 2
- 5.5.3 Cross-Border Trade/Delivery Route 3
- 5.5.4 Cross-Border Trade/Delivery Route 4
- 5.5.5 Cross-Border Trade/Delivery Route 5
- 5.6 Trade Policy & Market Access Impact Assessment
- 5.6.1 Tariff & Non-Tariff Barriers
- 5.6.2 Regional Trade & Economic Integration Frameworks
- 5.6.3 Bilateral & Multilateral Trade Agreements
- 5.6.4 Cross-Border Operating, Licensing & Localization Requirements
Note: This chapter applies where cross-border trade or delivery is relevant to Lithium Ion Residential Solar Energy Storage. Goods, services, and digital offerings are assessed using applicable classifications and transaction measures. Import-export volumes, trade balances, and route analyses are included only where meaningful to the market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Lithium Ion Residential Solar Energy Storage Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – the historical period vs. 2024
- 6.1.2 Leading, Mid-Sized & Emerging Player Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Lithium Ion Residential Solar Energy Storage Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company (Volume Where Applicable)
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution (the historical period vs. 2024)
- 6.2.5 Company Market Share by Key Segment
- 6.2.6 Company Market Share by Customer Group
- 6.3 Operating Scale, Capacity & Infrastructure Analysis
- 6.3.1 Global Operating Scale & Supply Capacity
- 6.3.2 Resource Utilization & Operating Efficiency
- 6.3.3 Output, Service Delivery & Activity Metrics
- 6.3.4 Operating Footprint & Infrastructure Map
- 6.3.5 Planned Operational & Capacity Expansion
- 6.4 Lithium Ion Residential Solar Energy Storage Competitive Benchmarking Matrix
- 6.4.1 Revenue, Growth, Profitability & Operating Metric Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Lithium Ion Residential Solar Energy Storage (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Products, Services & Solutions in Lithium Ion Residential Solar Energy Storage
- 6.5.3 Operational & Infrastructure Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Lithium Ion Residential Solar Energy Storage Market – By Sales & Delivery Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032) (Volume Where Applicable)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share (Volume Where Applicable)
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region (Volume Where Applicable)
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Sales & Delivery Channel
- 8.2.2 By Competitive Positioning & Price Tier
Chapter 9. North America Lithium Ion Residential Solar Energy Storage Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Lithium Ion Residential Solar Energy Storage Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Lithium Ion Residential Solar Energy Storage Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Lithium Ion Residential Solar Energy Storage Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Lithium Ion Residential Solar Energy Storage Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Lithium Ion Residential Solar Energy Storage Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Lithium Ion Residential Solar Energy Storage Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Supply, Output & Operating Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Demand, Adoption & Usage Assumptions
- Appendix F – Pricing & Revenue Metric Reference Tables
- Appendix G – Company Operations & Infrastructure Database
- Appendix H – Cross-Border Trade & Activity Data Tables (Where Applicable)
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
