
Autogenous Vaccine Market Overview:
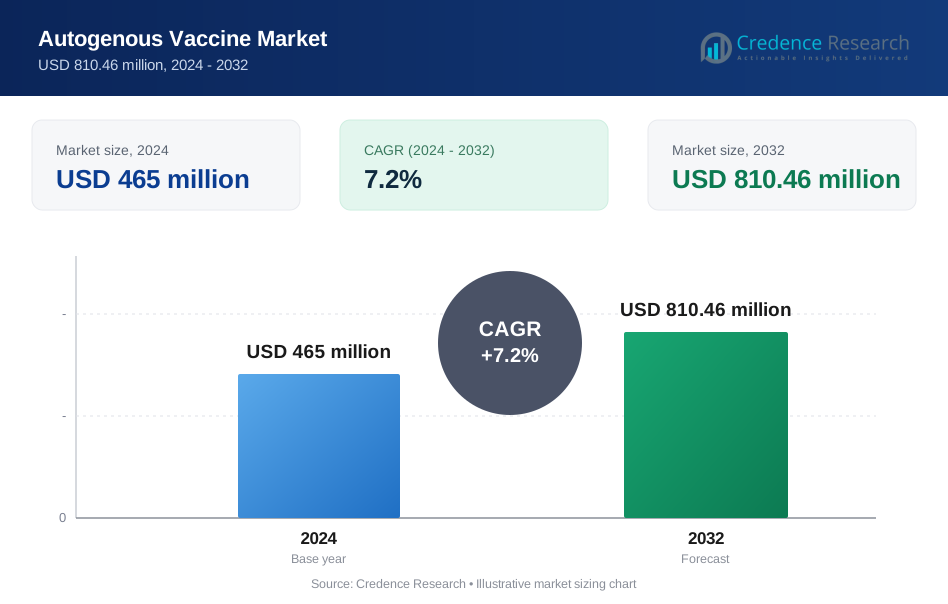
Autogenous Vaccine Market size was valued USD 465 million in 2024 and is anticipated to reach USD 810.46 million by 2032, at a CAGR of 7.2% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Autogenous Vaccine Market Size 2024 | USD 465 million |
| Autogenous Vaccine Market, CAGR | 7.2% |
| Autogenous Vaccine Market Size 2032 | USD 810.46 million |
Autogenous Vaccine Market Insights
- Market growth is driven by increasing disease outbreaks, growing focus on herd-specific prevention, and rising pressure to reduce antibiotic usage across veterinary and therapeutic applications.
- Key market trends include integration of advanced diagnostics, faster small-batch manufacturing, and increasing adoption in livestock and poultry, which together account for an estimated around 60% segment share.
- Competitive dynamics are shaped by global pharmaceutical and biotechnology players focusing on antigen-specific platforms, regulatory expertise, and collaborative development models to strengthen customization and speed to market.
- Regionally, North America leads with an exact 38% market share, supported by advanced healthcare infrastructure, favorable regulatory pathways, and high adoption, while Europe and Asia-Pacific follow with steady expansion.

Autogenous Vaccine Market Segmentation Analysis:
By Type
In the Autogenous Vaccine Market, therapeutic cancer vaccines dominate by type, accounting for an estimated 52–55% market share due to their personalized approach in treating established malignancies. These vaccines are designed using patient- or herd-specific tumor antigens, making them highly relevant for refractory and recurrent cancers. Strong adoption is driven by rising demand for precision oncology, improved antigen identification techniques, and growing clinical acceptance of individualized immunotherapy. Preventive cancer vaccines hold a smaller share, primarily limited by narrower indication scopes, while other autogenous formulations support niche research and compassionate-use applications.
- For instance, Dynavax Technologies’ CpG 1018 adjuvant is a 22-nucleotide synthetic oligodeoxynucleotide designed to activate Toll-like receptor 9, and it is formulated at a 3-milligram dose per injection, a quantified immune-stimulation parameter that has been validated across multiple late-stage clinical programs to enhance antigen-specific T-cell and antibody responses.
By Indication
By indication, cervical cancer represents the dominant sub-segment with approximately 45–48% market share, supported by high disease prevalence, well-characterized tumor antigens, and strong integration of immunotherapy in treatment protocols. Autogenous vaccines in cervical cancer benefit from established screening programs and biopsy-driven antigen sourcing, enabling effective customization. Prostate cancer follows with steady uptake driven by slow disease progression suited to immunotherapy timelines. Other indications, including melanoma and colorectal cancer, contribute incremental growth as personalized oncology pipelines expand across specialty care centers.
- For instance, Sanofi has advanced its mRNA and antigen-delivery platforms through its Translational Medicine and mRNA Center of Excellence the proprietary lipid nanoparticle (LNP) systems are engineered specifically in the 80–100 nanometer range. Research has identified this range as critical for maximizing immunogenicity and ensuring effective delivery of complex antigens.
By Technology
Based on technology, whole-cell cancer vaccines lead the Autogenous Vaccine Market, capturing nearly 40–42% share due to their ability to present a broad spectrum of tumor-associated antigens without complex genetic modification. This approach enhances immune recognition and reduces development time, making it attractive for personalized manufacturing. Recombinant cancer vaccines show strong growth as antigen engineering improves specificity, while viral vector and DNA vaccines gain traction through enhanced immune response durability. Continued advancements in cell processing and bioengineering support technology-driven differentiation.
Key Growth Drivers
Rising Demand for Personalized and Precision Therapies
The autogenous vaccine market benefits strongly from the healthcare shift toward personalized medicine. Autogenous vaccines are tailored to patient-specific or herd-specific pathogens, improving therapeutic relevance and immune response. This approach aligns well with oncology, infectious disease management, and veterinary applications where strain variability limits conventional vaccines. Increasing clinical evidence supporting customized immunotherapies, along with growing clinician preference for precision treatment protocols, continues to drive adoption. Regulatory flexibility for patient-specific biologics in several regions further strengthens market expansion.
- For instance, Moderna’s lipid nanoparticle (LNP) formulations used for its infectious disease and immuno-oncology programs are engineered to a controlled average diameter of 80–100 nanometers, an optimized range shown to enhance cellular uptake and antigen expression in vivo, as described in Moderna R&D platform disclosures and peer-reviewed lipid nanoparticle research.
Increasing Burden of Chronic, Recurrent, and Resistant Infections
The growing prevalence of chronic infections, recurrent bacterial diseases, and antimicrobial resistance significantly supports demand for autogenous vaccines. Conventional broad-spectrum treatments often fail against evolving or region-specific pathogens, creating a need for customized immunization strategies. Autogenous vaccines enable targeted immune stimulation against isolated strains, improving treatment outcomes and reducing reliance on antibiotics. This driver is particularly strong in veterinary medicine, aquaculture, and niche human therapeutic areas, where pathogen diversity and resistance patterns vary widely.
- For instance, AstraZeneca completed the acquisition of Icosavax, gaining IVX-A12 a protein virus-like particle (VLP) vaccine candidate that combines two prefusion F protein components (IVX-121 for RSV and IVX-241 for hMPV) into a single liquid, refrigerator-stable formulation, with Phase II clinical data showing robust dual antibody responses one month post-vaccination in adults aged 60–85 years, and Fast Track Designation from the U.S. FDA for its potential first-in-class profile against both respiratory pathogens.
Advancements in Microbial Isolation and Vaccine Manufacturing Technologies
Technological progress in pathogen isolation, genomic sequencing, and vaccine formulation enhances the feasibility and scalability of autogenous vaccines. Faster diagnostic tools allow precise identification of causative organisms, while improved inactivation, adjuvant systems, and quality control methods support consistent production. Automation in small-batch biologics manufacturing also reduces turnaround time. These advancements improve clinical confidence, expand application areas, and make autogenous vaccines more accessible across both human and animal health markets.
Key Trends & Opportunities
Expansion of Autogenous Vaccines in Oncology and Therapeutic Immunology
Therapeutic cancer vaccines represent a key growth opportunity within the autogenous vaccine market. Personalized tumor-derived antigen vaccines are increasingly explored to stimulate patient-specific immune responses. Research momentum in neoantigen discovery and immune profiling supports this trend. As combination therapies with checkpoint inhibitors gain traction, autogenous vaccines are positioned as complementary immunotherapy tools. Ongoing clinical research and early-stage approvals create long-term opportunities for market players specializing in customized vaccine platforms.
- For instance, Dendreon Pharmaceuticals LLC’s FDA-approved autologous cellular immunotherapy sipuleucel-T (PROVENGE®) is manufactured individually for each patient using leukapheresis-derived antigen-presenting cells activated ex vivo with a recombinant PAP-GM-CSF fusion protein, and each infusion is required to contain a minimum of 50 million CD54-positive cells, a quantified potency marker defined in Dendreon’s biologics license application and product label, demonstrating a validated, repeatable benchmark for personalized vaccine manufacturing in oncology.
Growing Adoption in Veterinary and Livestock Disease Management
Veterinary applications remain a dominant and expanding segment for autogenous vaccines. Livestock producers increasingly adopt customized vaccines to control farm-specific disease outbreaks and improve biosecurity. Autogenous vaccines help address regional pathogen mutations and reduce economic losses caused by ineffective mass vaccines. This trend is reinforced by stricter regulations on antibiotic usage in animal farming, pushing demand for immunological alternatives that support herd health and sustainable animal production practices.
- For instance, Amgen has published that its integrated generative biology platform which merges artificial intelligence, automation, and biological data has tripled the speed of protein engineering workflows and cut discovery timelines in half in internal R&D operations, and its AI-driven viscosity-prediction model achieves approximately 80 % predictive accuracy for injectable biologic properties, signifying concrete engineering advances that could inform future modulation of immune targets in veterinary and livestock disease contexts.
Integration of Genomics and Digital Diagnostics
The integration of genomic sequencing, bioinformatics, and digital diagnostic platforms is transforming autogenous vaccine development. Rapid pathogen characterization enables faster vaccine design and improved antigen selection. Digital traceability and data-driven decision-making enhance regulatory compliance and clinical monitoring. This convergence creates opportunities for collaborations between diagnostic companies, biotech firms, and vaccine manufacturers, strengthening innovation pipelines and improving turnaround efficiency for patient- or herd-specific vaccines.
Key Challenges
Complex Regulatory and Quality Compliance Requirements
Regulatory frameworks for autogenous vaccines vary significantly across regions, creating compliance complexity for manufacturers. While some markets allow flexible pathways for customized biologics, others impose stringent documentation, validation, and quality assurance standards. Maintaining consistency in small-batch production while meeting safety and efficacy requirements remains challenging. Regulatory uncertainty can delay approvals, limit cross-border commercialization, and increase operational costs, particularly for smaller manufacturers focused on niche applications.
High Production Costs and Limited Scalability
Autogenous vaccines rely on individualized or small-batch manufacturing, which limits economies of scale. Customized production increases costs related to diagnostics, formulation, validation, and logistics. Short shelf life and rapid turnaround requirements further add to operational complexity. These factors can restrict widespread adoption, especially in cost-sensitive healthcare systems. Manufacturers must balance customization with process efficiency to improve affordability and expand market penetration over the long term.
Regional Analysis
North America
North America leads the autogenous vaccine market with an estimated 38% market share, supported by advanced veterinary healthcare infrastructure and high awareness of herd-specific disease management. Strong adoption across livestock, poultry, and companion animals drives demand for customized vaccines tailored to regional pathogen profiles. Regulatory frameworks in the U.S. and Canada allow controlled use of autogenous vaccines, encouraging veterinary practices to integrate them into preventive health programs. High R&D investment, close collaboration between veterinarians and manufacturers, and rising concerns over antimicrobial resistance further strengthen market growth across the region.
Europe
Europe accounts for approximately 29% of the global autogenous vaccine market, driven by stringent animal health regulations and strong emphasis on biosecurity in livestock farming. Countries such as Germany, France, and the Netherlands show high adoption due to dense animal populations and recurring herd-specific disease outbreaks. Regulatory authorities permit autogenous vaccines under defined conditions, supporting their use when commercial vaccines are ineffective. Increasing focus on reducing antibiotic usage, coupled with advanced diagnostic capabilities and well-established veterinary networks, continues to support steady market expansion across both Western and Eastern Europe.
Asia-Pacific
Asia-Pacific holds around 21% market share in the autogenous vaccine market and represents the fastest-growing regional segment. Rapid expansion of the livestock and poultry industries in China, India, and Southeast Asia drives demand for customized disease-control solutions. High prevalence of region-specific pathogens and frequent disease outbreaks encourage the use of herd-specific vaccines. Improving veterinary infrastructure, rising awareness of biosecurity practices, and government initiatives to enhance animal productivity support adoption. Although regulatory frameworks vary across countries, increasing commercialization and local manufacturing capabilities strengthen regional market growth.
Latin America
Latin America contributes roughly 8% of the global autogenous vaccine market, supported by large-scale cattle, swine, and poultry production in countries such as Brazil, Argentina, and Mexico. Recurring endemic diseases and diverse pathogen strains increase the need for customized vaccination approaches. Growing awareness of preventive animal healthcare and gradual improvements in veterinary services support market uptake. Regulatory acceptance of autogenous vaccines remains selective but is expanding as producers seek alternatives to antibiotics. Export-oriented meat production and improving biosecurity standards continue to drive moderate yet consistent regional growth.
Middle East & Africa
The Middle East & Africa region holds an estimated 4% market share, reflecting early-stage but gradually expanding adoption of autogenous vaccines. Growth is driven by increasing investments in commercial livestock farming, particularly in the Gulf countries and parts of South Africa. Rising concerns over transboundary animal diseases and limited effectiveness of standard vaccines support interest in herd-specific solutions. However, uneven veterinary infrastructure and regulatory constraints limit rapid penetration. Ongoing improvements in animal health awareness, coupled with efforts to strengthen food security, are expected to support long-term market development.
Autogenous Vaccine Market Segmentations:
By Type:
- Preventive Cancer Vaccines
- Therapeutic Cancer Vaccines
By Indication:
- Cervical Cancer
- Prostate Cancer
By Technology:
- Recombinant Cancer Vaccines
- Viral Vector and DNA Cancer Vaccines
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
The autogenous vaccine market players such as Dynavax Technologies, Sanofi, Bristol-Myers Squibb Company, Moderna, Inc., Ferring B.V., AstraZeneca, Dendreon Pharmaceuticals LLC, Amgen, Inc., GSK plc, Merck & Co., Inc. The autogenous vaccine market exhibits a competitive environment driven by specialization, customization capability, and regulatory expertise rather than mass-market scale. Participants compete on their ability to rapidly develop herd- or patient-specific vaccines using precise pathogen identification and validated inactivation techniques. Strong integration with diagnostic laboratories and close collaboration with veterinarians and clinicians strengthen competitive positioning. Continuous investment in immunology research, formulation optimization, and flexible manufacturing processes supports consistent product quality and faster turnaround times. Regulatory compliance, batch traceability, and biosafety standards remain critical differentiators. As demand rises for targeted solutions that reduce reliance on conventional antibiotics and standard vaccines, competition increasingly centers on technical competence, responsiveness to outbreaks, and long-term customer relationships.
Key Player Analysis
- Dynavax Technologies
- Sanofi
- Bristol-Myers Squibb Company
- Moderna, Inc.
- Ferring B.V.
- AstraZeneca
- Dendreon Pharmaceuticals LLC
- Amgen, Inc.
- GSK plc
- Merck & Co., Inc.
Recent Developments
- In April 2025, Pfizer Inc. announced that the U.S. Centers for Disease Control and Prevention’s (CDC) Advisory Committee on Immunization Practices (ACIP) had voted to broaden its recommendation for RSV vaccines to include adults aged 50-59 who are at increased risk of RSV-related lower respiratory tract disease (LRTD).
- In March 2025, the U.S. Food and Drug Administration (FDA) cleared Everest Medicines' Investigational New Drug (IND) application for EVM14, a tumor-associated antigen (TAA) vaccine, making it the first internally developed mRNA therapeutic vaccine from the company to receive such approval for global clinical development in various cancers like lung and head/neck squamous cell carcinomas.
- In January 2025, GSK plc and the University of Oxford (Oxford) announced that they have entered a new research collaboration focused on the potential of cancer prevention through vaccination. GSK will invest up to over three years to support this early research.
Report Coverage
The research report offers an in-depth analysis based on Type, Indication, Technology and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Adoption of autogenous vaccines will increase as demand grows for pathogen-specific and herd-level disease control solutions.
- Regulatory clarity and standardized approval pathways will improve market confidence and clinical adoption.
- Integration of advanced diagnostics will accelerate faster identification of emerging and region-specific pathogens.
- Manufacturing processes will become more flexible to support small-batch, rapid-turnaround vaccine production.
- Reduced reliance on antibiotics will position autogenous vaccines as a key preventive healthcare alternative.
- Expansion of commercial livestock and poultry operations will drive sustained demand across emerging regions.
- Technological advances in antigen selection will enhance vaccine efficacy and consistency.
- Collaboration between veterinarians, laboratories, and manufacturers will strengthen customized vaccine programs.
- Digital traceability and quality control systems will improve regulatory compliance and safety assurance.
- Long-term growth will be supported by rising biosecurity awareness and food safety priorities.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Shift Toward Personalized and Precision Therapies
The autogenous vaccine market is expanding as healthcare systems increasingly prioritize personalized medicine, enabling vaccines to be tailored to patient- or herd-specific pathogens for improved therapeutic relevance and immune response. This is particularly impactful in oncology and veterinary applications where pathogen variability limits the effectiveness of conventional vaccines.
Rising Burden of Chronic, Recurrent, and Resistant Infections
The growing prevalence of chronic infections and antimicrobial resistance is driving demand for autogenous vaccines, as these allow for targeted immune stimulation against specific, often regionally unique, pathogens. This is especially critical in veterinary medicine and niche human therapeutic areas where standard treatments are less effective.
Advancements in Diagnostics and Manufacturing Technologies
Technological progress in pathogen isolation, genomic sequencing, and small-batch vaccine manufacturing has made autogenous vaccines more feasible and scalable. Faster diagnostics and improved production processes enable rapid, precise vaccine development, supporting broader adoption across both human and animal health sectors.
Regulatory Flexibility and Support for Customized Biologics
In several regions, regulatory agencies are providing more flexible pathways for the approval and use of autogenous vaccines, recognizing their importance in addressing unmet medical needs. This regulatory support encourages innovation and accelerates clinical adoption, particularly for patient- and herd-specific solutions.
Pressure to Reduce Antibiotic Usage in Livestock and Therapeutic Settings
Stricter regulations and growing awareness of antibiotic resistance are pushing both veterinary and human healthcare providers to seek alternatives to antibiotics. Autogenous vaccines offer a targeted, preventive approach that supports biosecurity and sustainable disease management, especially in livestock and poultry industries.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for the Autogenous Vaccine Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Autogenous Vaccine Market projected to grow between 2024 and 2032?
Which Autogenous Vaccine Market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Autogenous Vaccine Market?
Who are the leading companies in the Autogenous Vaccine Market?
Which region commanded the largest share of the Autogenous Vaccine Market in 2024?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Type
- 1.2.1 Preventive Cancer Vaccines
- 1.2.2 Therapeutic Cancer Vaccines
- 1.2.3 Other Autogenous Formulations
- 1.3 By Indication
- 1.3.1 Cervical Cancer
- 1.3.2 Prostate Cancer
- 1.3.3 Melanoma
- 1.3.4 Colorectal Cancer
- 1.3.5 Other Indications
- 1.4 By Technology
- 1.4.1 Whole-Cell Cancer Vaccines
- 1.4.2 Recombinant Cancer Vaccines
- 1.4.3 Viral Vector and DNA Cancer Vaccines
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 465 million → 2032: USD 810.46 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Autogenous Vaccine Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Autogenous Vaccine Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Autogenous Vaccine Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Autogenous Vaccine Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Autogenous Vaccine Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Autogenous Vaccine Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Autogenous Vaccine Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Autogenous Vaccine Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 465 million → 2032: USD 810.46 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Autogenous Vaccine Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Type - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Preventive Cancer Vaccines
- 12.3.7.2 Therapeutic Cancer Vaccines
- 12.3.7.3 Other Autogenous Formulations
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Indication - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Cervical Cancer
- 12.4.7.2 Prostate Cancer
- 12.4.7.3 Melanoma
- 12.4.7.4 Colorectal Cancer
- 12.4.7.5 Other Indications
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Technology - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Whole-Cell Cancer Vaccines
- 12.5.7.2 Recombinant Cancer Vaccines
- 12.5.7.3 Viral Vector and DNA Cancer Vaccines
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global Autogenous Vaccine Geographic Market Outlook, 2024-2032
- 13.1 Regional Market Size and Share, 2024
- 13.2 Regional Market Forecast, 2024-2032
- 13.3 Regional Pricing, Production and Demand Differences
- 13.4 North America
- 13.4.1 United States
- 13.4.2 Canada
- 13.4.3 Mexico
- 13.5 Europe
- 13.5.1 Germany
- 13.5.2 France
- 13.5.3 Italy
- 13.5.4 United Kingdom
- 13.5.5 Spain
- 13.5.6 Poland
- 13.5.7 Russia
- 13.5.8 Netherlands
- 13.5.9 Belgium
- 13.5.10 Sweden
- 13.5.11 Denmark
- 13.5.12 Norway
- 13.5.13 Rest of Europe
- 13.6 Asia Pacific
- 13.6.1 China
- 13.6.2 India
- 13.6.3 Japan
- 13.6.4 South Korea
- 13.6.5 Thailand
- 13.6.6 Indonesia
- 13.6.7 Vietnam
- 13.6.8 Malaysia
- 13.6.9 Australia
- 13.6.10 Rest of Asia Pacific
- 13.7 Latin America
- 13.7.1 Brazil
- 13.7.2 Argentina
- 13.7.3 Colombia
- 13.7.4 Chile
- 13.7.5 Rest of Latin America
- 13.8 Middle East
- 13.8.1 Saudi Arabia
- 13.8.2 United Arab Emirates
- 13.8.3 Turkey
- 13.8.4 Israel
- 13.8.5 Iran
- 13.8.6 Rest of the Middle East
- 13.9 Africa
- 13.9.1 South Africa
- 13.9.2 Egypt
- 13.9.3 Nigeria
- 13.9.4 Morocco
- 13.9.5 Rest of Africa
- 13.10 Regional Investment, Policy and Supply Chain Differences
- 13.11 Regional Competitive Landscape
- 13.12 Geographic Growth Hotspots
Chapter 14 Global Autogenous Vaccine Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2024-2032
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 Global Autogenous Vaccine Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2024
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2024-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Dynavax Technologies
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 Sanofi
- 17.4 Bristol-Myers Squibb Company
- 17.5 Moderna, Inc.
- 17.6 Ferring B.V.
- 17.7 AstraZeneca
- 17.8 Dendreon Pharmaceuticals LLC
- 17.9 Amgen, Inc.
- 17.10 GSK plc
- 17.11 Merck & Co., Inc.
- 17.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

