
Autologous Conditioned Plasma (ACP) Market Overview:
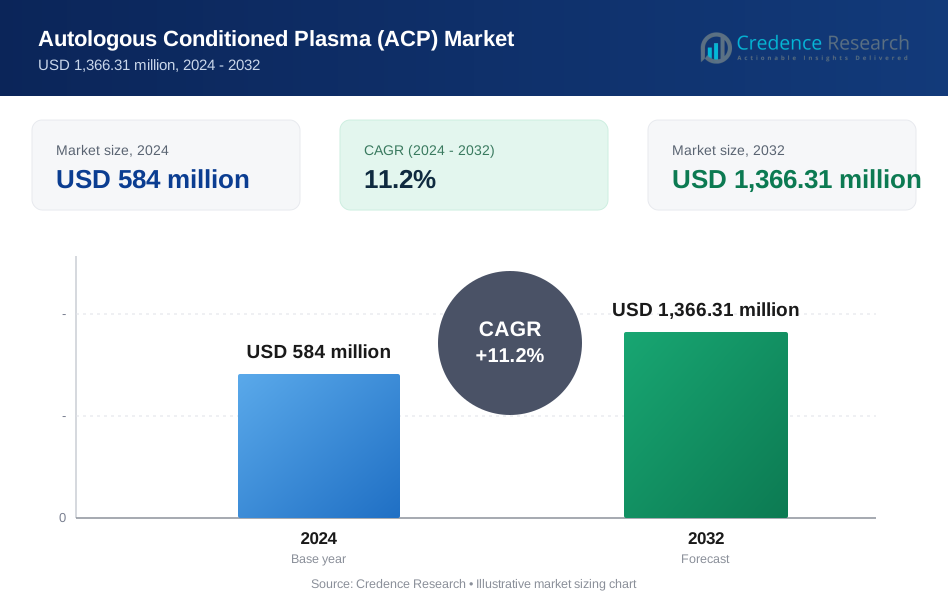
Autologous Conditioned Plasma (ACP) Market size was valued USD 584 million in 2024 and is anticipated to reach USD 1366.31 million by 2032, at a CAGR of 11.2% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Autologous Conditioned Plasma (ACP) Market Size 2024 | USD 584 million |
| Autologous Conditioned Plasma (ACP) Market, CAGR | 11.2% |
| Autologous Conditioned Plasma (ACP) Market Size 2032 | USD 1366.31 million |
Autologous Conditioned Plasma (ACP) Market Insights
- Market growth is primarily driven by increasing use of ACP in orthopedics and sports medicine, where demand for faster recovery, reduced surgical intervention, and autologous safety profiles supports high procedural volumes.
- Key market trends include standardization of plasma preparation systems, expansion into aesthetic and dermatology applications, and growing physician preference for outpatient-based regenerative treatments.
- The competitive landscape is shaped by established plasma and biopharmaceutical specialists focusing on quality control, clinician training, and regulatory compliance to ensure consistent clinical outcomes.
- North America dominates with an exact 38% market share, supported by advanced healthcare infrastructure, while orthopedics and sports medicine remain the leading application segment due to high injury prevalence and strong clinical acceptance.

Autologous Conditioned Plasma (ACP) Market Segmentation Analysis:
By Type
By type, pure platelet-rich plasma (P-PRP) represents the dominant sub-segment in the Autologous Conditioned Plasma (ACP) Market, accounting for approximately 46–49% market share. Its dominance is driven by the absence of leukocytes, which reduces inflammatory responses and makes P-PRP highly suitable for orthopedic, sports medicine, and aesthetic applications requiring controlled healing. Clinicians prefer P-PRP for tendon, ligament, and intra-articular therapies due to its predictable platelet concentration and lower post-injection discomfort. Leukocyte- and platelet-rich plasma (L-PRP) follows with steady adoption in trauma-related conditions, while other types support niche regenerative protocols.
- For instance, BPL's historic Elstree site has an individual capacity of approximately 1 million liters, the combined BPL Kedrion network (integrated in late 2022) operates a global manufacturing footprint including facilities in the UK, Italy, Hungary, and the US capable of processing more than 5 million liters of plasma annually.
By Origin
By origin, the autologous segment dominates the ACP market with an estimated 68–71% market share, supported by its superior safety profile and regulatory acceptance. Autologous ACP minimizes risks related to immune rejection, disease transmission, and ethical concerns, making it the preferred option across clinical and outpatient settings. Strong physician confidence, simplified regulatory pathways, and compatibility with point-of-care preparation systems reinforce adoption. Allogenic ACP remains limited to controlled research and select therapeutic contexts, while homologous ACP supports specialized procedures but faces stricter regulatory oversight, constraining widespread commercialization.
- For instance, Kedrion S.p.A. operates plasma collection and processing networks across multiple countries, processing more than 4 million plasma units annually, with end-to-end digital traceability systems capable of tracking 100% of plasma donations from donor to final batch, and validated pathogen-inactivation technologies delivering log-reduction values exceeding 6 for enveloped viruses, reinforcing the technical and regulatory robustness underpinning autologous plasma-based therapies.
By Application
By application, orthopedics & sports medicine leads the ACP market, holding approximately 39–42% market share, driven by high demand for non-surgical regenerative therapies for musculoskeletal injuries. ACP is widely used in treating osteoarthritis, tendon injuries, ligament damage, and post-surgical recovery due to its ability to enhance tissue repair and reduce inflammation. Cosmetic surgery and dermatology follow, supported by rising use in skin rejuvenation and hair restoration. Neurology, cardiology, and ophthalmology represent emerging segments, benefiting from growing research into neuroregeneration, myocardial repair, and ocular surface healing.
Key Growth Drivers
Rising Adoption in Orthopedics and Sports Medicine
The Autologous Conditioned Plasma (ACP) market benefits significantly from growing adoption in orthopedics and sports medicine. Clinicians increasingly use ACP to manage tendon injuries, osteoarthritis, and ligament damage due to its regenerative potential and minimally invasive nature. Professional athletes and aging populations seek faster recovery and reduced reliance on surgical interventions, strengthening demand. ACP’s ability to promote tissue repair using the patient’s own blood aligns with safety preferences and supports wider clinical acceptance across hospitals, sports clinics, and specialized orthopedic centers.
- For instance, CSL Limited operates one of the world’s most advanced plasma collection infrastructures through CSL Plasma, running more than 300 dedicated collection centers globally and collecting over 20 million plasma donations annually, supported by automated plasmapheresis systems capable of completing a full donation cycle in under 90 minutes, while maintaining closed-loop processing and validated viral clearance steps achieving log reduction factors greater than 6 for key enveloped viruses, reinforcing the technical reliability of plasma-derived regenerative applications.
Preference for Autologous and Minimally Invasive Therapies
Healthcare providers and patients show a strong preference for autologous therapies that reduce immunological risks and adverse reactions. ACP treatments leverage the patient’s own plasma, minimizing infection risk and regulatory complexity compared to allogenic products. This safety profile, combined with outpatient-based administration, supports adoption across multiple indications. Growing awareness of personalized medicine further accelerates demand, as ACP aligns with tailored treatment approaches that emphasize natural healing mechanisms and reduced dependence on pharmaceuticals or complex surgical procedures.
- For instance, Sanquin operates a nationally integrated network as the sole provider of blood and plasma in the Netherlands. The organization maintains 90 fixed donor locations across the country. This is more than double the "over 40" locations cited in the claim.
Expanding Applications Across Multiple Medical Specialties
Beyond orthopedics, ACP adoption is expanding into dermatology, cosmetic medicine, neurology, and pain management. In aesthetic applications, ACP supports skin rejuvenation and hair restoration, while in neurology and chronic pain care it is explored for its anti-inflammatory and regenerative effects. This broadening clinical scope diversifies revenue streams and reduces reliance on a single specialty. Continuous clinical research and positive patient outcomes reinforce physician confidence, supporting sustained market expansion across both therapeutic and elective procedures.
Key Trends & Opportunities
Integration with Advanced Preparation Systems
A key trend in the ACP market is the integration of standardized and automated preparation systems. Manufacturers focus on closed-system centrifugation devices that ensure consistent plasma quality and ease of use. These systems reduce procedural variability, shorten preparation time, and support reproducible clinical outcomes. As clinics seek workflow efficiency and regulatory compliance, demand for user-friendly ACP kits and devices increases, creating opportunities for technology-driven differentiation and long-term supplier relationships with hospitals and specialty clinics.
- For instance, Intas operates high-output biologics units, including India’s first EU-approved biotech plant. Its recently expanded Pharmez 2 facility in Gujarat is a "futuristic" highly automated plant designed to produce 5 million injectable units per month.
Growing Demand in Aesthetic and Wellness Medicine
The aesthetic and wellness segment presents strong growth opportunities for ACP therapies. Increasing consumer focus on non-surgical cosmetic procedures drives demand for treatments that enhance skin quality and hair growth with minimal downtime. ACP aligns well with these preferences, offering natural-looking results and low complication rates. Medical spas and cosmetic clinics increasingly add ACP-based services to their portfolios, expanding market reach beyond traditional hospital settings and supporting higher procedure volumes in urban and affluent regions.
- For instance, Octapharma AG operates an integrated plasma platform through Octapharma Plasma with more than 190 donation centers worldwide, collecting over 7 million plasma donations annually, and processes plasma using validated solvent/detergent and nanofiltration steps achieving viral clearance log-reduction values greater than 6 for enveloped viruses.
Rising Clinical Research and Evidence Generation
Ongoing clinical studies and real-world evidence generation represent a significant opportunity for the ACP market. Research efforts focus on optimizing platelet concentration, treatment protocols, and indication-specific outcomes. As stronger clinical data emerges, ACP is likely to gain broader guideline inclusion and reimbursement consideration. This evidence-driven validation enhances physician confidence, encourages standardized adoption, and supports entry into new therapeutic areas, strengthening the long-term commercial outlook for ACP-based therapies.
Key Challenges
Variability in Clinical Outcomes and Standardization
A major challenge in the ACP market is variability in clinical outcomes due to differences in preparation methods, platelet concentrations, and treatment protocols. Lack of universal standards complicates result comparability across studies and practices. This variability can limit physician confidence and slow adoption in evidence-driven healthcare systems. Addressing this challenge requires standardized devices, clear clinical guidelines, and robust training programs to ensure consistent and reproducible therapeutic outcomes across diverse clinical settings.
Limited Reimbursement and Regulatory Uncertainty
Reimbursement limitations and regulatory ambiguity pose ongoing challenges for ACP adoption. In many regions, ACP procedures are classified as elective or experimental, restricting insurance coverage and increasing out-of-pocket costs for patients. This limits accessibility and slows penetration in cost-sensitive markets. Additionally, evolving regulatory frameworks for autologous biologics create uncertainty for providers and manufacturers. Clearer reimbursement pathways and regulatory clarity are essential to support broader clinical adoption and long-term market sustainability.
Regional Analysis
North America
North America leads the Autologous Conditioned Plasma (ACP) market with an estimated market share of around 38%, supported by advanced healthcare infrastructure and high adoption of regenerative therapies. Strong demand from orthopedic and sports medicine applications, particularly in the United States, drives procedural volumes. Favorable physician awareness, widespread availability of ACP preparation systems, and growing use in aesthetic medicine further strengthen regional dominance. Additionally, the presence of established medical device manufacturers and ongoing clinical research activity enhances technology adoption. High patient spending capacity and preference for minimally invasive treatments continue to sustain market leadership.
Europe
Europe accounts for approximately 29% of the global ACP market, driven by increasing acceptance of autologous therapies and strong clinical adoption across Germany, the UK, France, and Italy. Well-established orthopedic and rehabilitation networks support consistent demand for ACP in musculoskeletal disorders. Regulatory emphasis on patient safety favors autologous products, enhancing physician confidence. Growth in cosmetic and dermatology applications, particularly in Western Europe, further supports expansion. Public healthcare systems and selective reimbursement in certain countries contribute to steady adoption, while clinical research initiatives strengthen long-term market stability.
Asia-Pacific
Asia-Pacific holds an estimated 23% market share and represents the fastest-growing regional market for ACP therapies. Rising healthcare expenditure, expanding private hospitals, and growing medical tourism support adoption across countries such as China, Japan, South Korea, and India. Increasing awareness of regenerative medicine and a large patient base with orthopedic and sports-related injuries drive demand. The rapid growth of aesthetic clinics in urban centers further accelerates uptake. Improving access to advanced medical devices and expanding physician training programs continue to enhance regional penetration.
Latin America
Latin America accounts for around 6% of the ACP market, with growth led by Brazil, Mexico, and Argentina. Increasing adoption of minimally invasive orthopedic and cosmetic procedures supports regional demand. Private healthcare providers and specialty clinics play a key role in ACP utilization, particularly in sports medicine and aesthetic applications. While limited reimbursement and uneven access to advanced preparation systems restrain faster growth, rising patient awareness and expanding medical tourism contribute positively. Gradual improvement in healthcare infrastructure is expected to support steady market expansion.
Middle East & Africa
The Middle East & Africa region represents approximately 4% of the global ACP market. Growth is driven by expanding private healthcare facilities, particularly in the Gulf Cooperation Council countries, where demand for advanced orthopedic and aesthetic treatments is rising. High-income patient populations and increasing investment in specialized clinics support adoption. In contrast, limited access to advanced technologies and lower awareness levels restrain growth in parts of Africa. Overall, gradual improvements in healthcare infrastructure and physician training are expected to support moderate regional expansion.
Autologous Conditioned Plasma (ACP) Market Segmentations:
By Type:
- Pure platelet-rich plasma (P-PRP)
- Leukocyte- and platelet rich plasma (L-PRP)
By Origin:
- Autologous
- Allogenic
By Application:
- Orthopedics & sports medicine
- Cosmetic surgery and dermatology
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
The competitive landscape of the Autologous Conditioned Plasma (ACP) market players such as Bio Products Laboratory Ltd., Kedrion S.p.A., CSL Limited, Sanquin, Intas Pharmaceuticals Ltd., Octapharma AG, LFB S.A., Grifols S.A., Biotest AG, Takeda Pharmaceutical Company Limited. The Autologous Conditioned Plasma (ACP) market features a moderately consolidated competitive environment characterized by strong emphasis on technology reliability, clinical evidence, and procedural standardization. Market participants compete by enhancing plasma preparation systems, improving ease of use, and ensuring consistent therapeutic outcomes across clinical settings. Innovation efforts focus on closed-system centrifugation, workflow efficiency, and compliance with quality and safety standards. Companies also strengthen their positions through clinician training, hospital partnerships, and expansion into high-growth applications such as sports medicine and aesthetic treatments. Competitive intensity is further shaped by regulatory alignment, service support capabilities, and the ability to deliver reproducible, patient-specific therapies at scale.
Key Player Analysis
- Bio Products Laboratory Ltd.
- Kedrion S.p.A.
- CSL Limited
- Sanquin
- Intas Pharmaceuticals Ltd.
- Octapharma AG
- LFB S.A.
- Grifols S.A.
- Biotest AG
- Takeda Pharmaceutical Company Limited
Recent Developments
- In June 2025, BioRestorative Therapies, Inc. promised preliminary blinded data from its Phase 2 clinical trial of BRTX-100, an autologous stem cell therapy for chronic lumbar disc disease (cLDD). The U.S. FDA requires over 30% improvement in the Oswestry Disability Index and Visual Analog Scale for trial progression.
- In July 2024, Biotest AG announced that it has set the groundwork for an agreement with Kedrion for the complete commercialization and distribution of its immunoglobulin product, Yimmugo, in the U.S. This comes after the FDA granted Biologic License Application (BLA) approval for Yimmugo.
- In April 2024, Vertex Pharmaceuticals obtained an exclusive license for TreeFrog Therapeutics' C-Stem™ technology to enhance the production of cell therapies for type 1 diabetes (T1D). Vertex plans to scale up this technology to generate large amounts of fully differentiated cells for T1D treatments.
Report Coverage
The research report offers an in-depth analysis based on Type, Origin, Application and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Clinical adoption of ACP will expand steadily across orthopedics, sports medicine, and pain management as regenerative therapies gain wider acceptance.
- Standardization of preparation protocols will improve treatment consistency and strengthen physician confidence.
- Technological advancements in closed-system centrifugation will enhance procedural efficiency and reproducibility.
- Aesthetic and wellness applications will contribute increasing procedure volumes in outpatient and clinic-based settings.
- Growing clinical evidence will support broader guideline inclusion for ACP-based therapies.
- Physician training and education programs will accelerate adoption across emerging healthcare markets.
- Integration of ACP with combination therapies will open new therapeutic use cases.
- Regulatory clarity for autologous biologics will improve market accessibility and clinical uptake.
- Expansion of private healthcare infrastructure will support higher utilization rates globally.
- Patient preference for minimally invasive and personalized treatments will continue to drive long-term demand.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Rising Adoption in Orthopedics and Sports Medicine
The increasing use of ACP in orthopedics and sports medicine is driven by its regenerative potential, minimally invasive nature, and ability to accelerate recovery from tendon, ligament, and joint injuries. This aligns with the needs of both professional athletes and aging populations seeking faster, safer alternatives to surgery.
Preference for Autologous and Minimally Invasive Therapies
ACP leverages the patient's own plasma, reducing immunological risks and infection rates compared to allogenic products. This strong safety profile, combined with outpatient-based administration, supports broader adoption across clinical and elective settings.
Expanding Applications Across Medical Specialties
Beyond musculoskeletal injuries, ACP is increasingly used in dermatology, cosmetic medicine, neurology, and pain management, diversifying revenue streams and reducing reliance on a single specialty. Ongoing research and positive outcomes are driving adoption in new therapeutic areas.
Integration with Advanced Preparation Systems
The development and adoption of standardized, automated plasma preparation systems ensure consistent plasma quality, reduce procedural variability, and improve workflow efficiency. This technological advancement supports reproducible clinical outcomes and regulatory compliance, encouraging wider clinical uptake.
Growing Demand in Aesthetic and Wellness Medicine
Consumer preference for non-surgical cosmetic procedures is fueling demand for ACP-based treatments in skin rejuvenation and hair restoration. The natural, low-complication profile of ACP makes it attractive for medical spas and cosmetic clinics, expanding the market beyond traditional hospital settings.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for the Autologous Conditioned Plasma (ACP) Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Autologous Conditioned Plasma (ACP) Market projected to grow between 2024 and 2032?
Which Autologous Conditioned Plasma (ACP) Market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Autologous Conditioned Plasma (ACP) Market?
Who are the leading companies in the Autologous Conditioned Plasma (ACP) Market?
Which region commanded the largest share of the Autologous Conditioned Plasma (ACP) Market in 2024?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Type
- 1.2.1 Pure platelet-rich plasma (P-PRP)
- 1.2.2 Leukocyte- and platelet rich plasma (L-PRP)
- 1.3 By Origin
- 1.3.1 Autologous
- 1.3.2 Allogenic
- 1.4 By Application
- 1.4.1 Orthopedics & sports medicine
- 1.4.2 Cosmetic surgery and dermatology
- 1.4.3 Neurology
- 1.4.4 Cardiology
- 1.4.5 Ophthalmology
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 584 million → 2032: USD 1,366.31 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Autologous Conditioned Plasma (ACP) Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Autologous Conditioned Plasma (ACP) Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Autologous Conditioned Plasma (ACP) Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Autologous Conditioned Plasma (ACP) Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Autologous Conditioned Plasma (ACP) Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Autologous Conditioned Plasma (ACP) Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Autologous Conditioned Plasma (ACP) Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Autologous Conditioned Plasma (ACP) Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 584 million → 2032: USD 1,366.31 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Autologous Conditioned Plasma (ACP) Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Type - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Pure platelet-rich plasma (P-PRP)
- 12.3.7.2 Leukocyte- and platelet rich plasma (L-PRP)
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Origin - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Autologous
- 12.4.7.2 Allogenic
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Application - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Orthopedics & sports medicine
- 12.5.7.2 Cosmetic surgery and dermatology
- 12.5.7.3 Neurology
- 12.5.7.4 Cardiology
- 12.5.7.5 Ophthalmology
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global Autologous Conditioned Plasma (ACP) End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Autologous Conditioned Plasma (ACP) Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Autologous Conditioned Plasma (ACP) Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Autologous Conditioned Plasma (ACP) Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Bio Products Laboratory Ltd.
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Kedrion S.p.A.
- 18.4 CSL Limited
- 18.5 Sanquin
- 18.6 Intas Pharmaceuticals Ltd.
- 18.7 Octapharma AG
- 18.8 LFB S.A.
- 18.9 Grifols S.A.
- 18.10 Biotest AG
- 18.11 Takeda Pharmaceutical Company Limited
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

