
Market Overview:
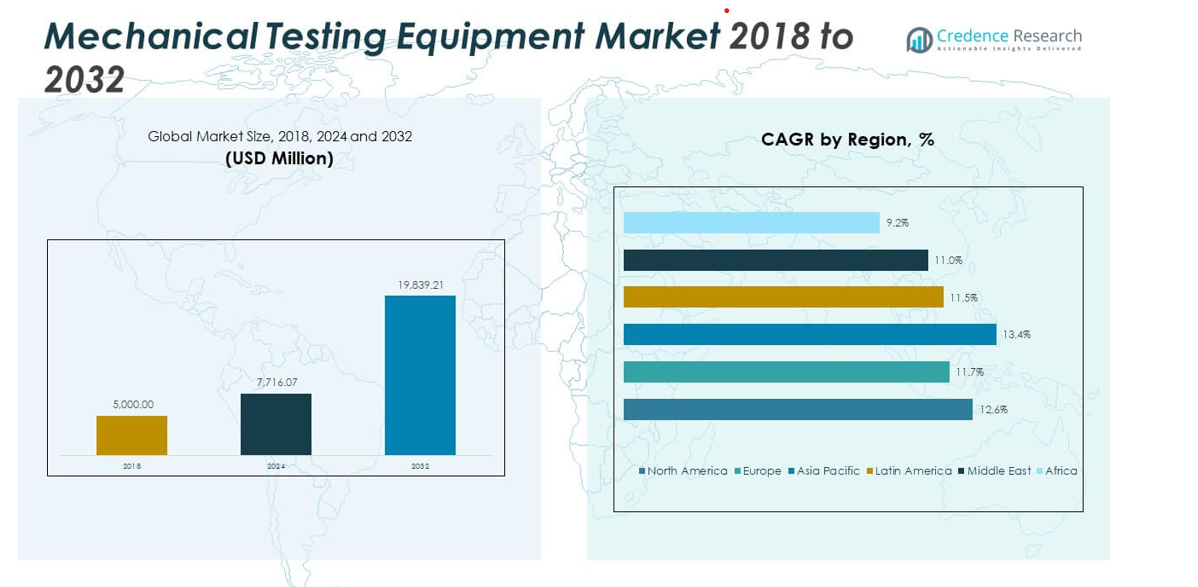
The Mechanical Testing Equipment Market size was valued at USD 5,000.00 million in 2018 to USD 7,716.07 million in 2024 and is anticipated to reach USD 19,839.21 million by 2032, at a CAGR of 12.57% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Mechanical Testing Equipment Market Size 2024 | USD 7,716.07 million |
| Mechanical Testing Equipment Market, CAGR | 12.57% |
| Mechanical Testing Equipment Market Size 2032 | USD 19,839.21 million |
Growth in this market is driven by rising quality assurance requirements across manufacturing, automotive, and aerospace sectors. Industries demand advanced testing solutions to ensure safety, durability, and compliance with international standards. Continuous material innovation involving composites, polymers, and alloys fuels adoption of modern testing systems. Automation, sensor integration, and digital data tracking further enhance precision, enabling faster validation and streamlined production control across testing applications.
Regionally, North America and Europe dominate due to strong industrial bases, strict safety regulations, and ongoing R&D investments. Asia Pacific emerges as the fastest-growing region supported by rapid industrialization and expanding automotive and electronics manufacturing in China, India, and Japan. Latin America, the Middle East, and Africa display steady progress through infrastructure growth, new industrial setups, and adoption of modern testing practices
Market Insights:
- The Mechanical Testing Equipment Market was valued at USD 5,000.00 million in 2018, USD 7,716.07 million in 2024, and is anticipated to reach USD 19,839.21 million by 2032, growing at a CAGR of 12.57%.
- North America (22.4%), Europe (22.3%), and Asia Pacific (45.4%) together capture the majority share due to advanced industrial infrastructure, strong R&D focus, and established regulatory frameworks supporting precision testing.
- Asia Pacific remains the fastest-growing region with 45.4% share, driven by accelerating manufacturing activity, infrastructure growth, and increased investments in testing automation and material innovation.
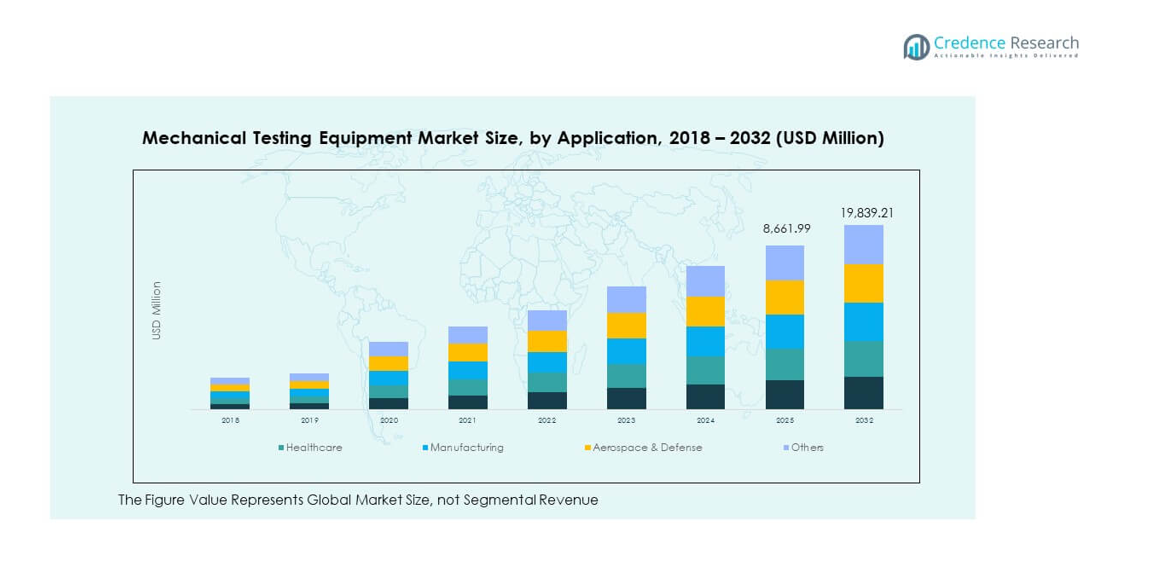
- The manufacturing segment holds approximately 35% share of the Mechanical Testing Equipment Market, supported by its vital role in process validation, quality assurance, and component certification across diverse industries.
- The aerospace & defense segment accounts for around 25% share, propelled by high demand for lightweight materials, safety testing, and compliance verification within aircraft and defense equipment production.
Market Drivers
Rising Demand for Material Validation Across Safety-Critical Industries
The Mechanical Testing Equipment Market expands through rising focus on material validation and safety assurance. Industries such as automotive, aerospace, and energy adopt advanced testing systems to ensure compliance with global quality standards. Manufacturers integrate tensile, fatigue, and hardness testing to confirm durability before product deployment. It supports improved reliability and performance in end-use applications. Governments enforce stricter regulations on material safety and product lifecycle testing. This encourages firms to invest in precision instruments. Continuous innovation in automation and data analytics improves efficiency in test processes. Demand rises further from manufacturers producing advanced alloys, polymers, and composites.
- For example, GS Engineering provides comprehensive vehicle durability and validation testing using advanced sensor arrays, proprietary software and extensive real-time data acquisition. It conducts both static and dynamic tests to support automotive and aerospace manufacturers, following international standards such as ISO, SAE and NATO.
Expanding Use of Advanced Materials Across Manufacturing and Engineering Sectors
Growing utilization of composite and hybrid materials drives market penetration. These materials require precise mechanical characterization for tensile strength, impact resistance, and fatigue life. It encourages manufacturers to invest in technologically advanced test equipment with high accuracy. Aerospace and defense projects rely on structural integrity validation under extreme conditions. Automotive industries test lighter components to meet emission reduction targets. Construction and infrastructure sectors also adopt these systems for quality control in concrete and steel testing. Manufacturers develop high-speed universal testing machines for multiple load profiles. Continuous material innovation supports new product development and enhances quality consistency.
Technological Advancements in Automation, Sensing, and Data Integration
Integration of automation and digital control systems enhances test accuracy and reproducibility. The shift toward smart laboratories accelerates demand for connected testing solutions. IoT-enabled sensors capture real-time stress, strain, and deformation data. Artificial intelligence supports predictive maintenance and error detection during testing. It helps reduce manual supervision and operational downtime. Robotics-based test benches improve throughput across high-volume industrial plants. Digital dashboards allow engineers to compare performance trends across test cycles. Rising adoption of Industry 4.0 technologies strengthens investment in intelligent and adaptive test systems.
Stringent Regulatory Standards and Quality Certification Mandates
Manufacturers comply with international testing standards to secure product certifications and market access. The Mechanical Testing Equipment Market benefits from policies enforcing material traceability and performance benchmarking. Aerospace and automotive suppliers must meet ISO, ASTM, and DIN standards before large-scale production. Compliance tests ensure end-user safety and minimize liability risks. Testing equipment plays a vital role in obtaining type approvals and structural certifications. National laboratories upgrade facilities to meet advanced calibration needs. Industry collaborations promote knowledge sharing and uniform testing protocols. Growing emphasis on sustainable and safe products fuels continuous adoption of precision testing instruments.
- For instance, SGS provides ISO/IEC 17025-accredited mechanical testing services that comply with international standards such as ISO, ASTM, and DIN. The company supports automotive and aerospace manufacturers with certification testing, ensuring material traceability and product safety across global supply chains.
Market Trends
Adoption of Digital Testing Platforms and Real-Time Analytics
Digital transformation reshapes traditional testing environments across multiple sectors. Testing systems now include cloud-based data storage and automated result interpretation. Engineers analyze material behavior through real-time dashboards and AI-assisted insights. It improves decision-making speed and reliability. Automated data logging minimizes human errors and enhances audit transparency. Cloud-based systems also allow remote test monitoring. The trend supports traceability and compliance for global manufacturers. Integration with digital twins supports simulation-driven development and faster material validation.
Growing Popularity of Non-Destructive Testing and Hybrid Methods
Manufacturers increasingly favor non-destructive testing (NDT) to preserve sample integrity. NDT techniques such as ultrasonic, X-ray, and magnetic particle testing offer fast diagnostics. It enables early fault detection without structural damage. Industries such as aerospace, oil and gas, and nuclear energy lead adoption due to strict safety needs. Hybrid systems that combine destructive and non-destructive testing improve testing precision. Portable and automated NDT devices gain traction for field operations. Integration with robotics ensures accessibility in difficult environments. This shift toward hybrid validation methods defines modern testing frameworks.
Integration of Automation and Robotics in Testing Workflows
Automation revolutionizes test workflows by reducing manual intervention. Robotic systems deliver consistent loading conditions and accurate specimen alignment. Automated grips and load frames shorten testing cycles in production lines. It improves throughput and repeatability across industrial plants. Smart robotics support adaptive control during stress testing and deformation analysis. Automated calibration minimizes downtime and ensures long-term stability. Firms adopt robotic manipulators for high-frequency fatigue and wear testing. This trend strengthens efficiency and aligns with industrial digitalization goals.
- For example, MTS Systems Corporation supplies test and simulation systems that cover tensile, compression, durability and fatigue testing of metals, plastics, ceramics and composites for automotive, aerospace and industrial applications.
Shift Toward Sustainability and Eco-Friendly Testing Systems
Manufacturers adopt energy-efficient and recyclable testing solutions to reduce operational footprint. The Mechanical Testing Equipment Market moves toward green design and reduced waste generation. Test laboratories replace hydraulic systems with electromechanical drives for cleaner operation. It supports sustainability targets across global industries. Developers integrate low-power sensors and digital controls to cut energy use. Environmentally responsible testing promotes material reuse and life-cycle assessment. Laboratories seek certification under green building norms. Sustainable practices gain importance in government-funded infrastructure and automotive R&D programs.
- For example, Shimadzu Corporation develops electromechanical testing machines that operate without hydraulic oil, reducing environmental impact and maintenance needs. These systems support tensile, compression, and bending tests while promoting cleaner, energy-efficient testing in automotive and manufacturing laboratories
Market Challenges Analysis
High Equipment Costs and Complex Calibration Requirements
The high initial cost of precision test machines limits adoption among small and mid-scale manufacturers. Complex calibration procedures demand skilled technicians and frequent maintenance. It creates additional operational expenses and slows production schedules. Sensitive instruments require controlled environments, increasing facility costs. Limited interoperability between legacy and modern systems adds integration challenges. Downtime due to calibration errors impacts productivity levels. Manufacturers face difficulty maintaining uniform standards across global test sites. The need for certified operators further complicates scaling in resource-constrained regions.
Lack of Skilled Workforce and Technical Training Infrastructure
Shortage of trained professionals in material science and testing technology affects performance consistency. The Mechanical Testing Equipment Market experiences a skill gap in system setup, data interpretation, and maintenance. Rapid technological evolution increases the need for continuous training. Universities and training centers lag in providing updated laboratory experience. It limits workforce readiness to handle digital and AI-based testing solutions. Inaccurate data analysis can lead to non-compliance in certification tests. Manufacturers must invest heavily in workforce upskilling. This challenge slows equipment adoption in developing markets with limited technical education access.
Market Opportunities
Rising Industrial Modernization and Infrastructure Growth Across Emerging Regions
Industrial modernization creates strong opportunities for expansion across developing economies. Countries such as India, Vietnam, and Indonesia boost investment in heavy manufacturing, automotive, and aerospace sectors. The Mechanical Testing Equipment Market gains from increased demand for product validation facilities. Governments fund metrology centers and testing laboratories to improve export standards. Local manufacturers adopt modern testing tools to meet international benchmarks. It enhances competitiveness and technology transfer from global players. Growth in infrastructure projects accelerates equipment sales across construction materials and structural applications.
Innovation in Smart Testing and Predictive Maintenance Technologies
Advances in machine learning, IoT, and automation open new prospects for intelligent testing systems. Smart sensors and adaptive algorithms deliver continuous equipment monitoring. It reduces unplanned downtime and optimizes calibration schedules. Predictive maintenance models extend machine life and improve operational efficiency. Real-time feedback systems ensure error-free testing environments. Integration with digital twins supports virtual prototyping and accelerates R&D cycles. Market players focusing on connected ecosystems gain early advantage through service-based revenue streams.
Market Segmentation Analysis:
By Product Type The Mechanical Testing Equipment Market includes a broad range of machines that ensure precision and reliability across diverse testing conditions. Universal Testing Machines (UTM) lead demand due to their ability to perform tensile, compression, and flexural tests on multiple materials. Fatigue Testing Machines are vital for assessing endurance in aerospace, defense, and automotive components. Impact Testing Machines measure toughness and failure thresholds for metals and polymers. Hardness Testers verify surface durability and wear resistance in industrial production lines. Specialized systems such as torsion, creep, and compression testers meet complex testing needs for high-performance materials. It grows stronger through the integration of automation, digital monitoring, and high-precision sensors that improve accuracy and test efficiency.
- For instance, the ZwickRoell Z010 model features a maximum force capacity of 10 kN with load measurement accuracy of ±0.05% and position measurement accuracy of ±0.0115 µm, supporting tensile, compression, and bending tests on various materials. Its test speeds have accuracy of ±0.05%, and the integrated testXpert III software ensures accurate data acquisition.
By Material By material, metals dominate testing requirements owing to their structural role in automotive, aerospace, and heavy engineering sectors. Testing ensures strength, ductility, and fatigue resistance of alloys and metal composites. Polymers and plastics witness steady growth as industries focus on lightweight and sustainable materials. Composites gain attention for their increasing use in wind energy, aviation, and automotive parts. Ceramics and rubber are tested for performance reliability under extreme conditions, particularly in medical and industrial settings. Wood testing maintains niche applications in construction and furniture manufacturing. It reflects a balanced demand pattern across traditional and emerging material categories supported by evolving material standards.
By Application By application, automotive and aerospace sectors hold a significant share driven by the need for safety validation and component reliability. Manufacturers rely on extensive fatigue and tensile testing to meet regulatory standards. The manufacturing segment maintains strong adoption through continuous quality control and production certification. Healthcare industries expand usage in testing surgical instruments, prosthetics, and implant materials to ensure precision and compliance. Defense applications utilize testing to evaluate structural integrity and operational resilience. It benefits from growing cross-sector demand for mechanical validation as industries innovate with advanced materials and production techniques.
- For instance, Instron's tensile testing machines, like the model 5969, support highly accurate mechanical testing with variable speeds from 0.001 to 500 mm/min and high-resolution load cells, widely used in automotive and aerospace sectors to ensure component reliability and safety compliance with precise force and elongation measurements.
Segmentation:
By Product Type:
- Universal Testing Machines (UTM)
- Fatigue Testing Machines
- Impact Testing Machines
- Hardness Testers
- Special Testing Machines
- Torsion Testing Machines
- Creep Testing Machines
- Compression Testing Machines
- Others
By Material:
- Metals
- Polymers / Plastics
- Composites
- Ceramics
- Rubber
- Wood
- Others
By Application:
- Automotive
- Healthcare
- Manufacturing
- Aerospace & Defense
- Others
By Region:
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis:
North America
The North America Mechanical Testing Equipment Market size was valued at USD 1,142.50 million in 2018 to USD 1,729.12 million in 2024 and is anticipated to reach USD 4,436.08 million by 2032, at a CAGR of 12.6% during the forecast period. It holds around 22.4% of the global share, driven by high investments in aerospace, defense, and automotive manufacturing. The region benefits from advanced R&D infrastructure and early adoption of precision testing technologies. Major industries rely on mechanical testing for product certification and compliance with strict quality regulations. The U.S. dominates due to the presence of leading manufacturers and strong government standards for safety and reliability. Canada and Mexico contribute through expanding industrial bases and growing export-oriented manufacturing. Technological upgrades in digital testing, automation, and AI-driven analytics enhance the competitive landscape. It maintains its leadership through constant innovation and strong institutional support for material research and product validation.
Europe
The Europe Mechanical Testing Equipment Market size was valued at USD 1,232.50 million in 2018 to USD 1,823.10 million in 2024 and is anticipated to reach USD 4,409.32 million by 2032, at a CAGR of 11.7%. Europe commands around 22.3% market share with strong industrial and regulatory ecosystems. Countries such as Germany, France, and the U.K. lead in material testing innovation for automotive, aerospace, and industrial machinery. It benefits from high-quality manufacturing standards, supported by stringent ISO and EN compliance norms. The region shows strong adoption of automation and sustainability-focused testing systems. Technological collaborations between testing laboratories and universities drive continuous product refinement. Expansion of electric vehicle and renewable energy sectors creates new testing requirements for advanced composites and light alloys. Europe’s mature industrial base ensures steady growth supported by modernization of existing testing infrastructure.
Asia Pacific
The Asia Pacific Mechanical Testing Equipment Market size was valued at USD 2,070.00 million in 2018 to USD 3,278.14 million in 2024 and is anticipated to reach USD 8,953.45 million by 2032, at a CAGR of 13.4%. It dominates the global market with a share of 45.4%, driven by rapid industrialization, infrastructure growth, and manufacturing expansion in China, Japan, India, and South Korea. High demand from automotive, electronics, and aerospace manufacturing boosts equipment deployment. The region benefits from government investments in material research and product certification programs. Emerging economies build advanced laboratories to support international quality standards. It witnesses growing integration of automated and AI-enabled testing systems across production sites. Rising exports of industrial components require enhanced reliability validation. Expanding regional supply chains further strengthen Asia Pacific’s position as the fastest-growing hub for testing solutions.
Latin America
The Latin America Mechanical Testing Equipment Market size was valued at USD 310.00 million in 2018 to USD 473.69 million in 2024 and is anticipated to reach USD 1,128.26 million by 2032, at a CAGR of 11.5%. It accounts for 5.7% of the global market share, with Brazil and Mexico leading growth. Industrial modernization in automotive, construction, and mining sectors supports demand for reliable material testing systems. Regional manufacturers focus on improving export quality and structural integrity in critical components. Government investments in research centers encourage testing standardization across industries. The market gains traction from expanding infrastructure projects requiring mechanical validation for concrete, metals, and composites. It benefits from growing collaborations with international equipment providers. Continued economic reforms and industrial diversification enhance technology adoption and testing capacity in major economies.
Middle East
The Middle East Mechanical Testing Equipment Market size was valued at USD 170.00 million in 2018 to USD 243.78 million in 2024 and is anticipated to reach USD 557.59 million by 2032, at a CAGR of 11.0%. It contributes 2.8% to global market share, supported by steady growth in oil, gas, and construction industries. Countries such as the UAE, Saudi Arabia, and Turkey drive demand for advanced material testing across large-scale infrastructure and industrial projects. The market benefits from new investments in aerospace and defense manufacturing zones. Testing laboratories expand to meet rising certification needs aligned with international safety standards. It witnesses technological transition toward automated testing systems for metals and polymers. Growing local partnerships with global manufacturers strengthen distribution and service networks. Sustainable construction initiatives further promote adoption of testing equipment across emerging projects.
Africa
The Africa Mechanical Testing Equipment Market size was valued at USD 75.00 million in 2018 to USD 168.24 million in 2024 and is anticipated to reach USD 354.51 million by 2032, at a CAGR of 9.2%. It represents 1.4% of the global market share, showing consistent progress through industrial and infrastructure expansion. South Africa leads with growing adoption in mining, construction, and energy sectors. Egypt and Nigeria witness gradual uptake driven by industrial modernization and foreign investment. The market gains support from government programs to improve product standards and testing capacity. Limited access to high-end technology remains a constraint, but regional collaborations improve knowledge transfer. Local distributors expand their portfolios to meet new industrial testing requirements. It advances through integration of affordable and portable testing solutions suited for small-scale operations and developing industrial clusters.
Key Player Analysis:
- MTS Systems Corporation
- Instron (Illinois Tool Works Inc.)
- Shimadzu Corporation
- ZwickRoell
- AMETEK (Lloyd Instruments)
- Hegewald & Peschke
- ADMET, Inc.
- Tinius Olsen
- Applied Test Systems
- Torontech Group International
- Buehler
- PCE Instruments
- Tokyo Testing Machine Co., Ltd.
- Hung Ta Instrument Co., Ltd.
- Qualitest International
Competitive Analysis:
The competitive landscape within the Mechanical Testing Equipment Market remains intense, driven by large global firms and focused niche players. Key companies such as MTS Systems Corporation, Instron (a subsidiary of Illinois Tool Works), Shimadzu Corporation, ZwickRoell, Hegewald & Peschke Meß‑ und Prüftechnik GmbH and AMETEK, Inc. (Lloyd Instruments) dominate through broad product portfolios and global distribution networks. These players continuously launch new machines, expand service networks and form partnerships to maintain competitive positions. It faces pressure from emerging players offering lower-cost or ultra-specialised test equipment solutions. Manufacturers differentiate through automation, digital data integration and global after-sales support. Strategic mergers and acquisitions accelerate market reach and product innovation. Regional footprint becomes critical as firms seek to capture high-growth markets in Asia Pacific and Latin America. The combination of scale, technological leadership and service excellence sets the competitive bar in this domain.
Recent Developments:
- In February 2025, Waters Corporation launched its ElectroForce Apex 1 instrument, designed for advanced polymer and composite mechanical testing. It features a new motor control system, an automated tuning technology (TuneIQ™), and faster fatigue-testing capability for extended test runs.
- In May 2024, Alpha Technologies introduced the AlphaFlex10™ Tensile Tester, adding destructive physical property testing to its rheology-line portfolio aimed at rubber and elastomer materials. The product integrates with existing software and service networks to support comprehensive material analysis.
Report Coverage:
The research report offers an in-depth analysis based on Product Type, Material and Application. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- Rapid industrial automation and digital transformation will elevate demand for precision mechanical testing systems across global manufacturing hubs.
- Increased adoption of AI-driven analytics will enhance test data accuracy and predictive maintenance for complex material structures.
- Integration of IoT-enabled sensors will improve traceability, quality assurance, and real-time performance tracking in test environments.
- Rising investments in aerospace, automotive, and renewable energy sectors will create new material testing requirements.
- The market will see strong opportunities from sustainable testing systems designed for energy efficiency and low maintenance.
- Expansion of R&D facilities in emerging economies will strengthen regional production and local technology development.
- Collaboration between equipment manufacturers and research institutions will drive innovation in multi-axis and hybrid testing machines.
- Growth in additive manufacturing will push demand for customized testing systems capable of evaluating 3D-printed components.
- Government policies enforcing stricter safety and certification norms will stimulate steady equipment upgrades.
- Cloud-based data management and remote laboratory access will redefine global testing standards and service models.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Stringent Quality and Safety Regulations
Increasingly strict international standards in automotive, aerospace, and manufacturing sectors require advanced mechanical testing equipment to ensure compliance, product safety, and certification, driving steady market growth.
Material Innovation and Adoption of Advanced Composites
The rise of new materials such as composites, polymers, and lightweight alloys in engineering and manufacturing necessitates precise mechanical testing for validation, boosting demand for modern, high-accuracy testing systems.
Automation, Digitalization, and Data Integration
The integration of automation, IoT-enabled sensors, and digital data tracking into testing equipment enhances precision, repeatability, and efficiency, encouraging manufacturers to upgrade to smart, connected testing solutions.
Expansion of Manufacturing and Infrastructure in Emerging Markets
Rapid industrialization and infrastructure development in Asia Pacific and other emerging regions are increasing the need for reliable mechanical testing to support quality assurance in new manufacturing and construction projects.
Growth in Non-Destructive and Hybrid Testing Methods
The shift toward non-destructive and hybrid testing techniques allows for faster, more comprehensive material validation without damaging samples, expanding the scope and frequency of testing across industries.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the projected growth of the Mechanical Testing Equipment Market?
At what Compound Annual Growth Rate is the Mechanical Testing Equipment Market projected to grow between 2024 and 2032?
What drives the market’s growth?
Which region dominates the market?
What are the challenges faced by the market
Who are the leading companies in the Mechanical Testing Equipment Market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Material
- 1.2.1 Metals
- 1.2.2 Polymers / Plastics
- 1.2.3 Composites
- 1.2.4 Ceramics
- 1.2.5 Rubber
- 1.2.6 Wood
- 1.3 By Application
- 1.3.1 Automotive
- 1.3.2 Healthcare
- 1.3.3 Manufacturing
- 1.3.4 Aerospace & Defense
- 1.3.5 Others
- 1.4 By Product Type
- 1.4.1 Universal Testing Machines (UTM)
- 1.4.2 Fatigue Testing Machines
- 1.4.3 Impact Testing Machines
- 1.4.4 Hardness Testers
- 1.4.5 Special Testing Machines
- 1.4.6 Compression Testing Machines
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 7,716.07 million → 2032: USD 19,839.21 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Mechanical Testing Equipment Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Mechanical Testing Equipment Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Mechanical Testing Equipment Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Mechanical Testing Equipment Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Mechanical Testing Equipment Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Mechanical Testing Equipment Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Mechanical Testing Equipment Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Mechanical Testing Equipment Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 7,716.07 million → 2032: USD 19,839.21 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Mechanical Testing Equipment Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Material - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Metals
- 12.3.7.2 Polymers / Plastics
- 12.3.7.3 Composites
- 12.3.7.4 Ceramics
- 12.3.7.5 Rubber
- 12.3.7.6 Wood
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Application - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Automotive
- 12.4.7.2 Healthcare
- 12.4.7.3 Manufacturing
- 12.4.7.4 Aerospace & Defense
- 12.4.7.5 Others
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Product Type - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Universal Testing Machines (UTM)
- 12.5.7.2 Fatigue Testing Machines
- 12.5.7.3 Impact Testing Machines
- 12.5.7.4 Hardness Testers
- 12.5.7.5 Special Testing Machines
- 12.5.7.6 Compression Testing Machines
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global Mechanical Testing Equipment End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Mechanical Testing Equipment Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Mechanical Testing Equipment Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Mechanical Testing Equipment Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 MTS Systems Corporation
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Instron (Illinois Tool Works Inc.)
- 18.4 Shimadzu Corporation
- 18.5 ZwickRoell
- 18.6 AMETEK (Lloyd Instruments)
- 18.7 Hegewald & Peschke
- 18.8 ADMET, Inc.
- 18.9 Tinius Olsen
- 18.10 Applied Test Systems
- 18.11 Torontech Group International
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

