
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
| Medical Device Technologies Market Size 2024 | USD 549,125 Million |
| Medical Device Technologies Market , CAGR | 3.56% |
| Medical Device Technologies Market Size 2032 | USD 726,453.05 Million |
Market Overview
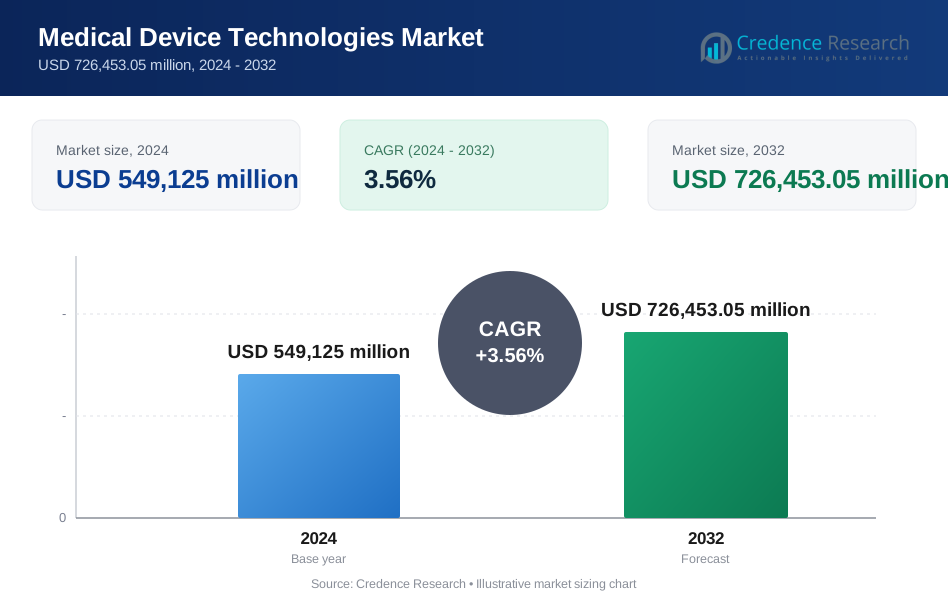
The Medical Device Technologies Market is projected to grow from USD 549,125 million in 2024 to USD 726,453.05 million by 2032, reflecting a compound annual growth rate (CAGR) of 3.56%.
The Medical Device Technologies Market is driven by the increasing prevalence of chronic diseases, rising demand for minimally invasive procedures, and advancements in technology such as AI and IoT integration. The growth is further supported by the aging global population, which demands sophisticated medical solutions. Trends include the development of wearable devices for remote monitoring, enhanced imaging technologies, and the expansion of smart implants. Additionally, the market is experiencing a shift towards personalized medicine, with innovative devices tailored to individual patient needs, improving treatment outcomes and driving market expansion.
The Medical Device Technologies Market is geographically diverse, with key players driving growth across major regions. In North America, companies like Medtronic plc, Johnson & Johnson, and Abbott Laboratories dominate, leveraging advanced technology and extensive distribution networks. In Europe, Siemens Healthineers and GE Healthcare are prominent, focusing on innovative diagnostic imaging and patient monitoring solutions. Asia-Pacific is growing rapidly, with Koninklijke Philips N.V. and Baxter International, Inc. expanding their presence due to increasing healthcare infrastructure and demand. Globally, companies such as Boston Scientific Corporation and Stryker Corporation are influential, offering a wide range of medical devices and contributing to market expansion.
Market Drivers
Rising Demand for Minimally Invasive Procedures
The shift towards minimally invasive procedures is driven by their numerous advantages over traditional surgery, such as reduced recovery times, minimized pain, and lower risk of complications. In 2023, 83% of all plastic surgery procedures were minimally invasive, highlighting the shift towards these techniques. The integration of robotics has led to the development of novel surgical platforms that enhance dexterity and precision, reducing the invasiveness and increasing the efficacy of interventions. These benefits are leading to a heightened demand for specialized medical devices that support such techniques. Additionally, advancements in technology, including robotics, imaging systems, and refined surgical instruments, are enhancing the precision and control of minimally invasive procedures. These technological improvements enable surgeons to perform complex operations with greater accuracy, further fueling the demand for advanced medical devices.
Growing Geriatric Population
The aging global population is significantly impacting the medical device market by increasing the need for medical care and interventions. For instance, the U.S. elderly population (persons aged 65 and above) totaled 60 million in 2023, and personal healthcare spending for this segment was approximately $22,000 per person. As people live longer, there is a rise in chronic diseases and age-related conditions, which drives the demand for diagnostic, treatment, and monitoring devices tailored to older adults. Additionally, there is a strong focus on enabling elderly individuals to maintain independence for as long as possible. Medical devices that assist with mobility, monitor vital signs, and manage chronic conditions are becoming essential to support independent living and improve the quality of life for the elderly.
Technological Advancements in Medical Devices
Technological advancements are revolutionizing the medical device sector, particularly through the integration of Artificial Intelligence (AI) and machine learning. AI-powered devices are enhancing diagnostic accuracy, image analysis, and surgical planning, while machine learning algorithms help in personalizing treatment plans and predicting patient outcomes. For instance, AI and machine learning are being integrated into medical devices, enhancing diagnostic accuracy and personalizing treatment plans. The use of AI in breast cancer has enabled mammograms to be reviewed 30 times faster with almost 100% accuracy. Robotics in surgery has also seen significant advancements, with the FDA approving the first gene therapy for children with Duchenne muscular dystrophy in June 2023, showcasing the potential for improved surgical outcomes and faster recovery times. The rise of connected medical devices and telemedicine further allows for remote monitoring and data collection, which improves chronic disease management and early issue detection.
Focus on Personalized Medicine
The trend towards personalized medicine is driving innovation in medical devices, enabling precision diagnostics and targeted therapies. Advances in diagnostic tools allow for the identification of specific genetic variations or disease markers, which facilitate tailored treatment approaches for individual patients. Minimally invasive biopsy devices are also becoming increasingly important, as they enable the collection of tissue samples for more accurate and personalized diagnosis and treatment planning. This focus on personalized medicine is reshaping how medical devices are designed and utilized to better meet the needs of patients.
Market Trends
Advances in Minimally Invasive Surgery and AI Integration
The medical device technologies market is experiencing significant growth driven by the shift towards minimally invasive procedures and the integration of Artificial Intelligence (AI) and Machine Learning (ML). For instance, the adoption of minimally invasive and robotic-assisted surgery (RAS) systems has surged by 18% in the last year alone, with enhanced precision and 3D visualization contributing to a 30% reduction in patient recovery times and a 25% decrease in overall surgical risks. Minimally invasive and robotic-assisted surgery (RAS) systems are gaining traction due to their advantages, including enhanced precision, 3D visualization, and improved ergonomics for surgeons. These systems enable more precise and controlled operations, reducing patient recovery times and overall surgical risks. Concurrently, the incorporation of AI and ML into medical devices is transforming the industry by providing advanced functionalities. AI-powered diagnostic tools facilitate faster and more accurate disease detection, while AI-driven image analysis enhances surgical planning. Furthermore, AI-assisted decision support within robotic surgery systems is improving surgical outcomes and operational efficiency, highlighting the growing trend of integrating cutting-edge technologies to elevate surgical practices and patient care.
Growth of Telemedicine, Personalized Medicine, and Emerging Markets
The expansion of telemedicine and remote patient monitoring is revolutionizing healthcare by enabling real-time patient surveillance and remote consultations. The Growth of Telemedicine, Personalized Medicine, and Emerging Markets is evident as telemedicine services have experienced a 300% increase in usage, leading to a 40% reduction in hospital readmission rates. Personalized medicine is on the rise, with biosensors collecting over 2 terabytes of patient data daily, enabling tailored treatment plans. This trend facilitates early intervention, enhances chronic disease management, and contributes to reduced hospital readmission rates. Additionally, advancements in medical devices are supporting a shift towards personalized medicine. Biosensors and diagnostic tools now gather detailed patient data, allowing for individualized treatment plans and targeted therapies tailored to specific needs. The Internet of Medical Things (IoMT) is also enhancing the connectivity of medical devices with healthcare IT systems, promoting centralized monitoring and data-driven decision-making. Moreover, the rising popularity of wearable medical devices, such as smartwatches and fitness trackers, empowers patients to actively manage their health. 3D printing technology is enabling the creation of customized implants and surgical models, offering patient-specific solutions. Emphasizing cybersecurity is crucial as the reliance on connected devices grows, prompting manufacturers to enhance security measures to protect patient data. Lastly, the medical device market is expanding in emerging economies like China and India, driven by increased disposable incomes, healthcare awareness, and supportive government initiatives, positioning these regions as key growth areas in the global market.
Market Challenges Analysis
High Costs, Regulatory Hurdles, and Reimbursement Challenges
The medical device technologies market faces significant obstacles related to high costs, stringent regulatory requirements, and reimbursement challenges. Developing and bringing new medical devices to market is a costly and time-consuming endeavor. The extensive regulatory framework necessitates rigorous clinical trials and compliance with detailed standards, which can delay innovation and limit the timely availability of potentially life-saving technologies. Additionally, the reimbursement landscape poses a challenge for the adoption of new devices. Hospitals and healthcare providers often grapple with the complexities of securing favorable reimbursement rates from insurance companies, which can discourage the adoption of innovative medical technologies. These hurdles not only strain financial resources but also potentially hinder the pace of technological advancements and the broader dissemination of cutting-edge medical solutions.
Cybersecurity Threats, Data Privacy Issues, and Skilled Workforce Shortages
As the reliance on connected medical devices increases, cybersecurity threats and data privacy issues become critical concerns. Connected devices are vulnerable to cyberattacks, which can compromise patient data or disrupt essential functionalities, highlighting the need for robust cybersecurity measures. Similarly, managing and safeguarding patient data privacy has become increasingly complex with the rise of telemedicine and connected devices, necessitating stringent data security protocols and clear patient consent processes. Additionally, the growing complexity of medical devices underscores the need for a skilled workforce trained in their operation and maintenance. However, a shortage of qualified technicians and healthcare professionals poses a challenge to effectively managing these advanced technologies. Integration of new devices with existing hospital IT systems also presents difficulties, requiring significant investment and standardized data formats for seamless interoperability. These challenges collectively impact the efficiency and effectiveness of medical device technologies, emphasizing the need for comprehensive strategies to address these issues effectively.
Market Segmentation Analysis:
By Device Type:
The Medical Device Technologies Market is diverse, encompassing a range of device types catering to various healthcare needs. In Vitro Diagnostic (IVD) Devices lead the market, driven by their essential role in disease detection and monitoring, offering advancements in accuracy and speed. Cardiology Devices follow closely, with innovations in diagnostic and therapeutic tools enhancing cardiac care and management. Diagnostic Imaging Devices, including MRI, CT, and ultrasound, are critical for detailed internal examinations, supporting accurate diagnosis and treatment planning. Orthopedic Devices and Ophthalmology Devices address musculoskeletal and eye-related conditions, respectively, with ongoing advancements in technology improving patient outcomes. Endoscopy Devices provide minimally invasive diagnostic solutions, while Diabetes Care Devices and Wound Management Devices offer specialized care for chronic conditions. Kidney/Dialysis Devices and Anesthesia and Respiratory Care Devices are crucial for managing critical health issues, ensuring effective treatment and patient management. Collectively, these segments reflect a broad spectrum of applications and technological advancements shaping the medical device landscape.
By End-user:
The end-user segments of the Medical Device Technologies Market include Academics & Research, Hospitals, Clinics, Diagnostic Centers, Ambulatory Surgical Centers, and others. Hospitals dominate as the primary end-user, driven by their extensive need for diverse medical devices to support comprehensive patient care and complex procedures. Clinics and Diagnostic Centers are significant users, particularly for devices related to routine diagnostics and outpatient care. Ambulatory Surgical Centers are growing in prominence due to their focus on same-day surgical procedures and minimally invasive techniques. Academics & Research institutions contribute by utilizing advanced devices for clinical studies and research, driving innovation in medical technology. The "Others" category includes various specialized settings and facilities that also contribute to the demand for medical devices. Each end-user segment plays a crucial role in driving the adoption and utilization of medical devices, reflecting the diverse applications and needs within the healthcare ecosystem.
Segments:
Based on Device Type:
- In Vitro Diagnostic (IVD) Devices
- Cardiology Devices
- Diagnostic Imaging Devices
- Orthopedic Devices
- Ophthalmology Devices
- Endoscopy Devices
- Diabetes Care Devices
- Wound Management Devices
- Kidney/Dialysis Devices
- Anesthesia and Respiratory Care Devices
- Others
Based on End-user:
- Academics & Research
- Hospitals
- Clinics
- Diagnostic Centers
- Ambulatory Surgical Centers
- Others
Based on the Geography:
- North America
- The U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- The U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis
North America
North America stands as the dominant force in this market, commanding approximately 40% of the global share. This leadership position is primarily driven by the United States, which boasts a robust healthcare system, significant research and development investments, and a high adoption rate of advanced medical technologies. The region's market is characterized by the presence of major medical device manufacturers, a strong focus on innovation, and a healthcare system that readily embraces new technologies. Additionally, favorable reimbursement policies and a growing elderly population contribute to the sustained demand for sophisticated medical devices.
Europe
Europe holds the second-largest market share at around 30%, with Germany, the United Kingdom, and France leading the region's medical device sector. The European market is distinguished by its stringent regulatory standards, particularly the Medical Device Regulation (MDR), which ensures high-quality and safe medical devices. This regulatory environment, while challenging for manufacturers, fosters innovation and maintains consumer trust. The region's aging population and increasing prevalence of chronic diseases drive the demand for advanced medical technologies. European countries also demonstrate a strong commitment to healthcare digitization, propelling the growth of connected medical devices and telemedicine solutions.
Key Player Analysis
- Abbott Laboratories
- Boston Scientific Corporation
- Baxter International, Inc.
- Medtronic plc
- Cardinal Health Inc.
- F. Hoffmann-La Roche Ltd.
- GE Healthcare
- Johnson & Johnson
- Siemens Healthineers
- Smith & Nephew plc
- Stryker Corporation
- Koninklijke Philips N.V.
Competitive Analysis
The Medical Device Technologies Market is highly competitive, featuring leading players with extensive portfolios and global reach. Medtronic plc and Johnson & Johnson are dominant forces, known for their broad range of innovative devices, from cardiology to diabetes care. Abbott Laboratories and Boston Scientific Corporation excel in advanced diagnostic and interventional technologies, driving significant advancements in patient care. GE Healthcare and Siemens Healthineers lead in diagnostic imaging and monitoring solutions, leveraging their technological expertise and research capabilities. Baxter International, Inc. and Stryker Corporation are key players in critical care and orthopedic devices, respectively, with a focus on enhancing patient outcomes and operational efficiency. Koninklijke Philips N.V. stands out with its integrated health technologies and emphasis on digital health solutions. Competitive strategies among these players include continuous innovation, strategic partnerships, and expansion into emerging markets, ensuring they stay at the forefront of the evolving medical device landscape.
Recent Developments
- In March 2024, Stryker Corporation introduced a novel, innovative product, LIFEPAK CR2 automated external defibrillator (AED), to improve cardiac care and enhance patient outcomes.
- In January 2024, Accelus launched a linesider modular-cortical system that can be used for spinal implant surgeries. This implant is expected to be used by the surgeons to support the spine during surgeries.
Market Concentration & Characteristics
The Medical Device Technologies Market exhibits moderate to high concentration, characterized by the presence of several leading players with substantial market shares. Major companies such as Medtronic plc, Johnson & Johnson, and Abbott Laboratories dominate the landscape due to their extensive product portfolios and significant investments in research and development. This concentration results in a competitive environment where innovation and technological advancements are critical. The market is distinguished by rapid technological evolution, with a focus on integrating advanced features such as artificial intelligence and connectivity into medical devices. Companies invest heavily in developing cutting-edge technologies to enhance patient outcomes and operational efficiency. Additionally, regulatory compliance and reimbursement policies play a crucial role in shaping market dynamics. While dominant players lead in market share, there is room for niche players to thrive by addressing specialized needs and emerging trends. Overall, the market is characterized by intense competition and a continuous push towards technological innovation.
Report Coverage
The research report offers an in-depth analysis based on Device Type, End-user and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The market is projected to grow significantly, driven by increasing demand for advanced medical technologies and innovations.
- Advancements in wearable medical devices will enhance patient monitoring and health management.
- The integration of artificial intelligence and machine learning will further improve diagnostic accuracy and treatment personalization.
- Telemedicine and remote monitoring technologies will expand, offering more accessible healthcare solutions.
- There will be a rise in demand for minimally invasive surgical devices, driven by their benefits in patient recovery and precision.
- Growth in emerging markets will provide new opportunities, as these regions invest in healthcare infrastructure and technology.
- Increased focus on personalized medicine will drive the development of tailored medical devices and targeted therapies.
- The adoption of 3D printing technology will advance, enabling customized implants and prosthetics.
- Cybersecurity measures will become more critical to protect patient data and ensure device safety.
- Sustainability initiatives will gain importance, with efforts to reduce environmental impact through eco-friendly device design and disposal practices.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Shift Toward Minimally Invasive Procedures
Minimally invasive techniques offer reduced recovery times, less pain, and lower complication risks compared to traditional surgery. This has led to increased adoption of specialized devices and robotics that support such procedures, fueling market growth.
Aging Global Population
The rising number of elderly individuals worldwide is increasing the prevalence of chronic and age-related diseases, driving demand for diagnostic, monitoring, and therapeutic devices tailored to older adults and supporting independent living.
Technological Advancements and AI Integration
Rapid innovation in medical devices, including the integration of artificial intelligence, machine learning, and IoT, is enhancing diagnostic accuracy, surgical precision, and personalized treatment, making advanced care more accessible and effective.
Expansion of Telemedicine and Remote Monitoring
The surge in telemedicine and wearable devices enables real-time patient monitoring and remote consultations, improving chronic disease management and reducing hospital readmissions, thereby increasing the need for connected medical devices.
Growth in Emerging Markets
Rising healthcare investments, increasing disposable incomes, and supportive government initiatives in emerging economies such as China and India are expanding access to advanced medical technologies and driving overall market expansion.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Medical Device Technologies Market?
What factors are driving the growth of the Medical Device Technologies Market?
What are the key segments within the Medical Device Technologies Market?
What are some challenges faced by the Medical Device Technologies Market?
Who are the major players in the Medical Device Technologies Market?
Which segment is leading the market share?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By End-user
- 1.2.1 Hospitals
- 1.2.2 Clinics
- 1.2.3 Diagnostic Centers
- 1.2.4 Ambulatory Surgical Centers
- 1.2.5 Academics & Research
- 1.2.6 Others
- 1.3 By Device Type
- 1.3.1 In Vitro Diagnostic (IVD) Devices
- 1.3.2 Cardiology Devices
- 1.3.3 Diagnostic Imaging Devices
- 1.3.4 Orthopedic Devices
- 1.3.5 Ophthalmology Devices
- 1.3.6 Endoscopy Devices
- 1.3.7 Diabetes Care Devices
- 1.3.8 Wound Management Devices
- 1.3.9 Kidney/Dialysis Devices
- 1.3.10 Anesthesia and Respiratory Care Devices
- 1.3.11 Others
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 549,125 million → 2032: USD 726,453.05 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Medical Device Technologies Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Medical Device Technologies Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Medical Device Technologies Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Medical Device Technologies Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Medical Device Technologies Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Medical Device Technologies Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Medical Device Technologies Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Medical Device Technologies Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 549,125 million → 2032: USD 726,453.05 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Medical Device Technologies Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By End-user - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Hospitals
- 12.3.7.2 Clinics
- 12.3.7.3 Diagnostic Centers
- 12.3.7.4 Ambulatory Surgical Centers
- 12.3.7.5 Academics & Research
- 12.3.7.6 Others
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Device Type - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 In Vitro Diagnostic (IVD) Devices
- 12.4.7.2 Cardiology Devices
- 12.4.7.3 Diagnostic Imaging Devices
- 12.4.7.4 Orthopedic Devices
- 12.4.7.5 Ophthalmology Devices
- 12.4.7.6 Endoscopy Devices
- 12.4.7.7 Diabetes Care Devices
- 12.4.7.8 Wound Management Devices
- 12.4.7.9 Kidney/Dialysis Devices
- 12.4.7.10 Anesthesia and Respiratory Care Devices
- 12.4.7.11 Others
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 Segment Growth Comparison
- 12.6 Segment Attractiveness and Priority Matrix
Chapter 13 Global Medical Device Technologies End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Medical Device Technologies Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Medical Device Technologies Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Medical Device Technologies Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Medtronic plc
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Johnson & Johnson
- 18.4 Abbott Laboratories
- 18.5 Boston Scientific Corporation
- 18.6 GE Healthcare
- 18.7 Siemens Healthineers
- 18.8 Baxter International, Inc.
- 18.9 Stryker Corporation
- 18.10 Koninklijke Philips N.V.
- 18.11 F. Hoffmann-La Roche Ltd.
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

