
Metal Electrical Conduit Market Overview:
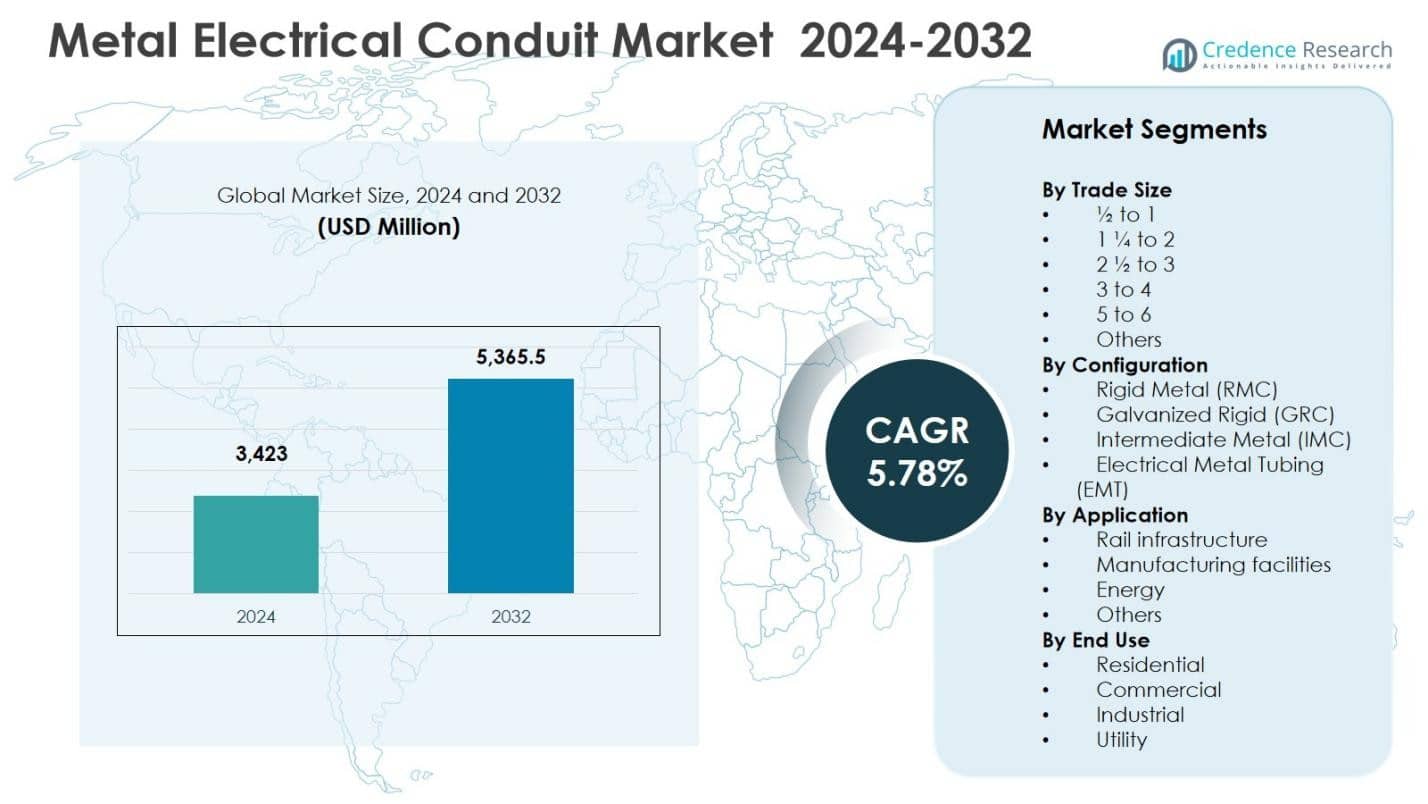
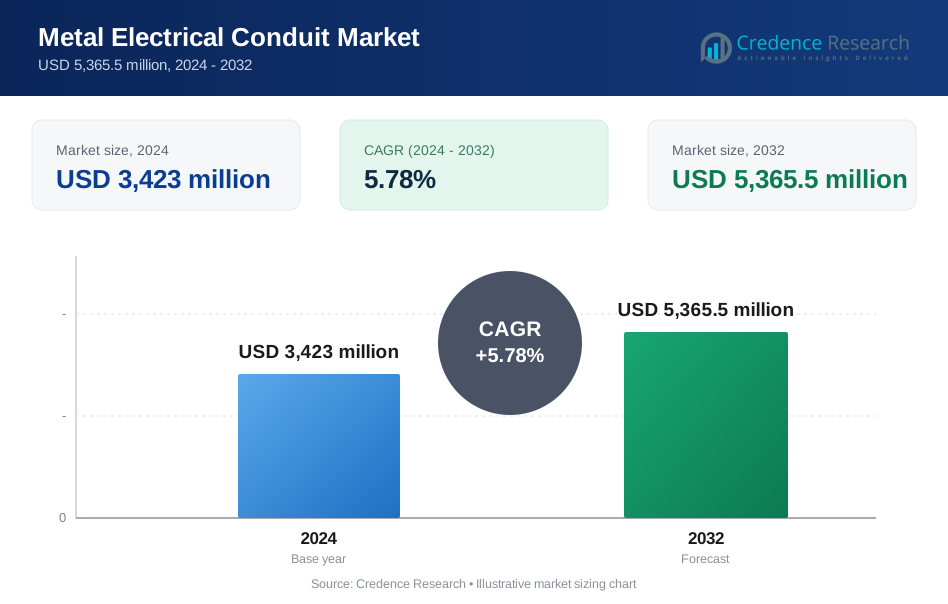
Metal Electrical Conduit Market size was valued at USD 3,423 million in 2024 and is anticipated to reach USD 5,365.5 million by 2032, at a CAGR of 5.78% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Metal Electrical Conduit Market Size 2024 | USD 3,423 million |
| Metal Electrical Conduit Market, CAGR | 5.78% |
| Metal Electrical Conduit Market Size 2032 | USD 5,365.5 million |
Metal Electrical Conduit Market Insights
- Market growth is primarily driven by rising infrastructure investments, industrial automation, and stricter electrical safety and fire protection regulations, with the manufacturing facilities application segment holding a dominant 31.7% share in 2024 due to heavy-duty wiring protection needs.
- Key market trends include increasing adoption of Electrical Metal Tubing, which accounted for a 38.9% share in 2024, along with growing use of recyclable and long-life conduit systems aligned with sustainability-focused construction practices.
- Market structure is defined by established players emphasizing certified products, wide configuration offerings, and regional supply strength, while competition from non-metallic conduits and raw material price volatility act as notable restraints.
- Regionally, North America led with a 32.4% share in 2024, followed by Asia Pacific at 29.8% driven by rapid urbanization, and Europe with 26.1% supported by strong regulatory enforcement and industrial modernization.
Metal Electrical Conduit Market Segmentation Analysis:
By Trade Size:
In the Metal Electrical Conduit Market, the 1¼ to 2 trade size segment dominated with a 34.6% market share in 2024, driven by its widespread use across commercial buildings, industrial facilities, and infrastructure projects. This trade size offers an optimal balance between mechanical strength and installation flexibility, making it suitable for power distribution, control wiring, and safety-critical applications. Strong demand from manufacturing plants, data centers, and public infrastructure upgrades continues to support adoption. Additionally, compatibility with standard fittings and cost efficiency compared to larger diameters further reinforce its dominance within the trade size segmentation.
- For instance, Allied Tube & Conduit supplies 1-1/2 inch EMT conduit, featuring a 10-foot length with thin-wall steel construction and E-Z Pull interior coating for smooth wire pulling in office ceilings and exposed spaces.
By Configuration:
By configuration, Electrical Metal Tubing (EMT) held the leading position with a 38.9% market share in 2024 due to its lightweight structure, ease of bending, and lower installation costs. EMT is extensively used in commercial construction and light industrial environments where corrosion resistance and rapid installation are essential. Growth is driven by rising investments in commercial real estate, renovation of office spaces, and expanding urban infrastructure. Its compliance with electrical safety codes and suitability for concealed wiring applications further strengthen EMT’s preference over rigid and intermediate conduit configurations.
- For instance, Atkore's Allied Tube & Conduit provided EZ-Pull EMT with Flo-Coat galvanizing for office buildings and big-box retail spaces. The product's smooth interior coating facilitated easier conductor pulling in drop ceilings and exposed walls, supporting efficient wiring in healthcare facilities and distribution centers like Amazon.
By Application:
Within applications, manufacturing facilities accounted for the largest share at 31.7% in 2024, supported by increasing automation, equipment electrification, and stringent safety standards. Metal electrical conduits provide superior mechanical protection and fire resistance, making them essential in heavy-duty industrial environments. Expansion of automotive, electronics, and process manufacturing plants has accelerated demand for reliable wiring protection systems. Additionally, ongoing modernization of factories and integration of smart manufacturing technologies continue to drive conduit usage, positioning manufacturing facilities as the dominant application segment in the Metal Electrical Conduit Market.
Key Growth Drivers
Expansion of Construction and Infrastructure Projects
The Metal Electrical Conduit Market benefits significantly from rising investments in commercial, industrial, and public infrastructure development. Rapid urbanization, expansion of transportation networks, and large-scale projects such as rail corridors, airports, and industrial parks are increasing demand for reliable electrical protection systems. Metal conduits are widely adopted due to their high mechanical strength, long operational life, and compliance with stringent safety standards. Government initiatives supporting infrastructure modernization and industrial development further strengthen demand, particularly in projects where durability, fire resistance, and regulatory compliance are critical requirements.
- For instance, Atkore International supplies steel and PVC-coated conduits for healthcare facilities, ensuring safe electricity distribution in patient treatment spaces through robust protection against impacts.
Increasing Focus on Electrical Safety and Fire Protection
Heightened awareness of electrical safety and stricter enforcement of building and fire codes are key drivers of the Metal Electrical Conduit Market. Metal conduits offer superior resistance to heat, impact, and fire compared to alternative materials, making them essential in high-risk installations. Regulatory mandates across manufacturing, energy, and transportation sectors continue to encourage adoption. In addition, growing concerns around workplace safety, insurance liabilities, and operational reliability push end users to invest in robust conduit systems that ensure long-term protection and compliance with national and international safety standards.
- For instance, Zekelman Industries applies premium zinc coatings via hot-dip galvanization on rigid steel conduit, passing UL salt spray and humidity tests to resist corrosion and meet building safety standards in industrial settings.
Industrial Automation and Energy Infrastructure Expansion
The increasing adoption of industrial automation and the expansion of energy infrastructure strongly support market growth. Modern manufacturing facilities rely on automated equipment, robotics, and advanced control systems that require secure and durable cable management solutions. Metal electrical conduits provide enhanced load-bearing capacity, electromagnetic shielding, and resistance to harsh operating conditions. Similarly, investments in power generation, renewable energy projects, and grid upgrades drive demand for metal conduits capable of supporting complex and high-capacity electrical networks, reinforcing their importance across industrial and energy applications.
Key Trends & Opportunities
Growth of Smart Buildings and Commercial Electrification
The rapid adoption of smart buildings is creating significant opportunities within the Metal Electrical Conduit Market. Advanced building automation, IoT integration, and energy-efficient electrical systems require structured and secure wiring solutions. Metal conduits support high-density cabling while ensuring compliance with safety regulations in commercial spaces such as offices, hospitals, and data centers. The growing installation of electric vehicle charging infrastructure and intelligent lighting systems further increases demand, encouraging manufacturers to develop conduit solutions tailored for smart and connected building environments.
- For instance, Rigid Metal Conduit (RMC) provides maximum mechanical protection in high-traffic EV charging areas like public lots, with thick steel walls guarding against impacts while serving as a grounding conductor.
Rising Demand for Sustainable and Long-Life Electrical Systems
Sustainability-driven construction practices are emerging as a key trend shaping market opportunities. Metal electrical conduits, particularly those made from steel and aluminum, are recyclable and offer extended service life, aligning with green building objectives. Developers and facility operators increasingly prioritize materials that reduce lifecycle costs and maintenance requirements. As environmental regulations and sustainability certifications gain importance, metal conduits are positioned as a preferred solution, enabling manufacturers to strengthen their value proposition through durability, recyclability, and long-term performance benefits.
- For instance, Nucor Tubular Products, via Republic Conduit, produces steel tubing with clean American manufacturing using electric arc furnaces that lower carbon emissions compared to global peers.
Key Challenges
Volatility in Raw Material Prices
Fluctuating prices of steel and aluminum present a major challenge for the Metal Electrical Conduit Market. Raw material cost volatility directly affects manufacturing costs, pricing strategies, and profit margins. Sudden price increases can disrupt supply chains, delay projects, and reduce demand in cost-sensitive construction and industrial sectors. Smaller manufacturers face greater exposure due to limited procurement flexibility. Managing cost pressures while maintaining competitive pricing and consistent product quality remains a critical concern for market participants.
Competition from Non-Metallic Conduit Alternatives
Increasing adoption of non-metallic conduits poses a competitive challenge for the Metal Electrical Conduit Market. Materials such as PVC and HDPE offer advantages including lower initial costs, corrosion resistance, and easier installation, making them attractive in residential and light commercial applications. In regions with less stringent safety requirements, these alternatives often replace metal conduits. This competition compels metal conduit manufacturers to emphasize performance, safety compliance, and durability while investing in innovation and application-specific solutions to maintain market relevance.
Regional Analysis
North America
North America accounted for a 32.4% market share in 2024 in the Metal Electrical Conduit Market, supported by strong demand from commercial construction, industrial facilities, and energy infrastructure upgrades. The region benefits from stringent electrical safety and fire protection codes that mandate the use of metal conduits in critical applications. Ongoing investments in data centers, manufacturing automation, and transportation infrastructure further drive adoption. Replacement of aging electrical systems across the United States and Canada also contributes to steady demand, while growing deployment of electric vehicle charging networks reinforces the need for durable and code-compliant conduit systems.
Europe
Europe captured a 26.1% market share in 2024, driven by strict regulatory frameworks governing electrical safety, fire resistance, and sustainability. Demand is strong across industrial manufacturing, rail infrastructure, and commercial renovation projects. Countries such as Germany, the United Kingdom, and France continue to invest in factory modernization and energy-efficient buildings, supporting conduit installations. The region’s emphasis on recyclable materials and long-life electrical systems further supports metal conduit usage. In addition, infrastructure refurbishment and expansion of renewable energy facilities contribute to consistent demand across Western and Northern Europe.
Asia Pacific
Asia Pacific held a 29.8% market share in 2024, making it the fastest-growing regional market for metal electrical conduits. Rapid urbanization, large-scale infrastructure development, and expansion of manufacturing hubs across China, India, Japan, and Southeast Asia drive demand. Increasing investments in rail networks, industrial parks, power generation, and smart city projects significantly boost conduit installations. Rising enforcement of electrical safety standards in commercial and industrial buildings further accelerates adoption. Cost-effective manufacturing and high construction activity levels position Asia Pacific as a key growth engine for the global market.
Latin America
Latin America accounted for a 6.7% market share in 2024, supported by gradual growth in industrial construction, energy projects, and urban infrastructure development. Countries such as Brazil and Mexico are witnessing increased investments in manufacturing facilities, power distribution networks, and transportation infrastructure. Metal electrical conduits are gaining preference in industrial and public projects due to their durability and safety performance. While budget constraints limit adoption in some residential applications, ongoing modernization of electrical systems and rising regulatory awareness continue to support stable growth across the region.
Middle East & Africa
The Middle East & Africa region represented a 5.0% market share in 2024, driven by infrastructure expansion, energy projects, and large commercial developments. Strong demand emerges from the Gulf countries due to investments in airports, rail systems, industrial zones, and smart city initiatives. Metal electrical conduits are widely used in harsh environments where heat resistance and mechanical strength are critical. In Africa, gradual electrification projects and industrial development support moderate demand growth. Government-led infrastructure spending remains the primary driver across the region.
Metal Electrical Conduit Market Segmentations:
By Trade Size
- ½ to 1
- 1 ¼ to 2
- 2 ½ to 3
- 3 to 4
- 5 to 6
- Others
By Configuration
- Rigid Metal (RMC)
- Galvanized Rigid (GRC)
- Intermediate Metal (IMC)
- Electrical Metal Tubing (EMT)
By Application
- Rail infrastructure
- Manufacturing facilities
- Energy
- Others
By End Use
- Residential
- Commercial
- Industrial
- Utility
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
Competitive landscape analysis of the Metal Electrical Conduit Market highlights the presence of established global manufacturers such as Atkore, Schneider Electric, Legrand, HellermannTyton, Anamet Electrical, American Conduit, Techno Flex, Flexa, Nucor Tubular Products, and Gibson Stainless & Specialty. The market is characterized by a strong focus on product durability, regulatory compliance, and broad distribution networks. Leading players compete by expanding manufacturing capacity, strengthening regional supply chains, and offering a wide range of conduit configurations to address diverse industrial, commercial, and infrastructure applications. Strategic investments in corrosion-resistant materials, prefabricated conduit systems, and installation-friendly designs enhance differentiation. Companies also emphasize certifications and compliance with international safety standards to secure large-scale projects. Regional players remain competitive by leveraging cost efficiency and localized distribution. Overall, innovation in product performance, strategic partnerships, and geographic expansion remain central to sustaining market positioning.
Key Player Analysis
- Techno Flex
- Schneider Electric
- Gibson Stainless & Specialty
- Anamet Electrical
- HellermannTyton
- Nucor Tubular Products
- Flexa
- Atkore
- Legrand
- American Conduit
Recent Developments
- In April 2025, TE Connectivity completed its acquisition of Richards Manufacturing Co., strengthening its product portfolio and position in the electrical infrastructure and utility grid products sector.
- In October 2024, Caparo Middle East inaugurated a fully integrated manufacturing plant in Dammam, Saudi Arabia, in collaboration with Engineer Sinan Ali Ahmed Bukamseen to produce electrical conduits.
- In November 2024, ArcelorMittal and China Oriental Group announced a joint venture to manufacture electric steel in China, strengthening their position in the Asian market for electrical applications.
Report Coverage
The research report offers an in-depth analysis based on Trade Size, Configuration, Application, End Use and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The market will continue to benefit from sustained growth in commercial and industrial construction activities.
- Increasing enforcement of electrical safety and fire protection regulations will strengthen long-term demand.
- Expansion of manufacturing automation will drive consistent adoption of durable conduit systems.
- Investments in rail, metro, and transportation infrastructure will support steady market expansion.
- Growth of renewable energy and power grid modernization will create new application opportunities.
- Rising deployment of electric vehicle charging infrastructure will increase conduit installations.
- Demand for recyclable and long-life materials will reinforce preference for metal conduits.
- Product innovation focused on easier installation and corrosion resistance will shape competition.
- Emerging economies will witness faster adoption due to urbanization and infrastructure spending.
- Strategic capacity expansion and regional supply chain strengthening will remain a priority for manufacturers.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for the Metal Electrical Conduit Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Metal Electrical Conduit Market projected to grow between 2024 and 2032?
Which Metal Electrical Conduit Market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Metal Electrical Conduit Market?
Who are the leading companies in the Metal Electrical Conduit Market?
Which region commanded the largest share of the Metal Electrical Conduit Market in 2024?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 3,423 million → 2032: USD 5,365.5 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Metal Electrical Conduit Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Metal Electrical Conduit Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Metal Electrical Conduit Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Metal Electrical Conduit Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Metal Electrical Conduit Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Metal Electrical Conduit Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Metal Electrical Conduit Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Metal Electrical Conduit Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 3,423 million → 2032: USD 5,365.5 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Metal Electrical Conduit Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 Segment Growth Comparison
- 12.4 Segment Attractiveness and Priority Matrix
Chapter 13 Global Metal Electrical Conduit Geographic Market Outlook, 2024-2032
- 13.1 Regional Market Size and Share, 2024
- 13.2 Regional Market Forecast, 2024-2032
- 13.3 Regional Pricing, Production and Demand Differences
- 13.4 North America
- 13.4.1 United States
- 13.4.2 Canada
- 13.4.3 Mexico
- 13.5 Europe
- 13.5.1 Germany
- 13.5.2 France
- 13.5.3 Italy
- 13.5.4 United Kingdom
- 13.5.5 Spain
- 13.5.6 Poland
- 13.5.7 Russia
- 13.5.8 Netherlands
- 13.5.9 Belgium
- 13.5.10 Sweden
- 13.5.11 Denmark
- 13.5.12 Norway
- 13.5.13 Rest of Europe
- 13.6 Asia Pacific
- 13.6.1 China
- 13.6.2 India
- 13.6.3 Japan
- 13.6.4 South Korea
- 13.6.5 Thailand
- 13.6.6 Indonesia
- 13.6.7 Vietnam
- 13.6.8 Malaysia
- 13.6.9 Australia
- 13.6.10 Rest of Asia Pacific
- 13.7 Latin America
- 13.7.1 Brazil
- 13.7.2 Argentina
- 13.7.3 Colombia
- 13.7.4 Chile
- 13.7.5 Rest of Latin America
- 13.8 Middle East
- 13.8.1 Saudi Arabia
- 13.8.2 United Arab Emirates
- 13.8.3 Turkey
- 13.8.4 Israel
- 13.8.5 Iran
- 13.8.6 Rest of the Middle East
- 13.9 Africa
- 13.9.1 South Africa
- 13.9.2 Egypt
- 13.9.3 Nigeria
- 13.9.4 Morocco
- 13.9.5 Rest of Africa
- 13.10 Regional Investment, Policy and Supply Chain Differences
- 13.11 Regional Competitive Landscape
- 13.12 Geographic Growth Hotspots
Chapter 14 Global Metal Electrical Conduit Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2024-2032
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 Global Metal Electrical Conduit Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2024
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2024-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Leading Market Participants – Standard Profile Structure
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

