
Market Overview:
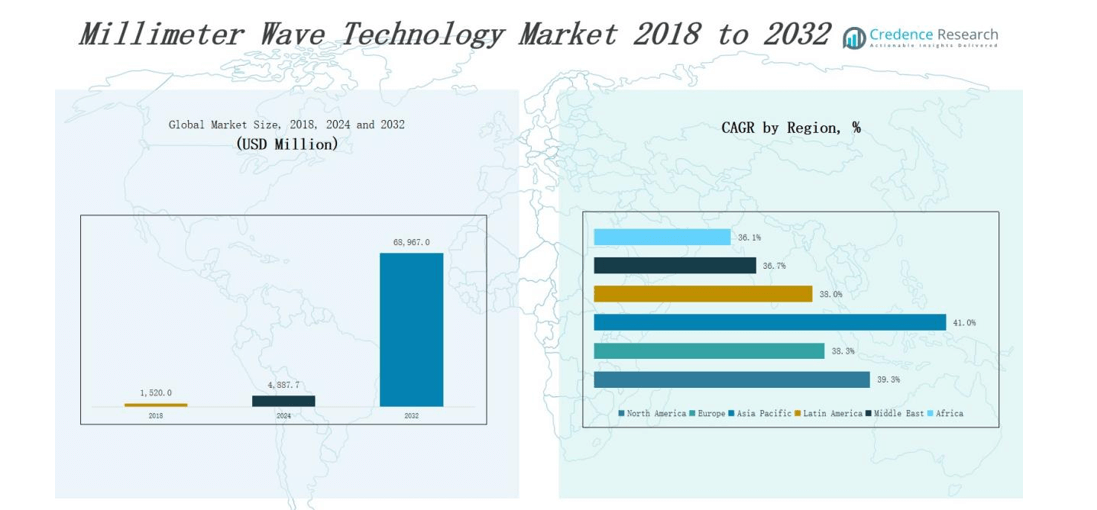
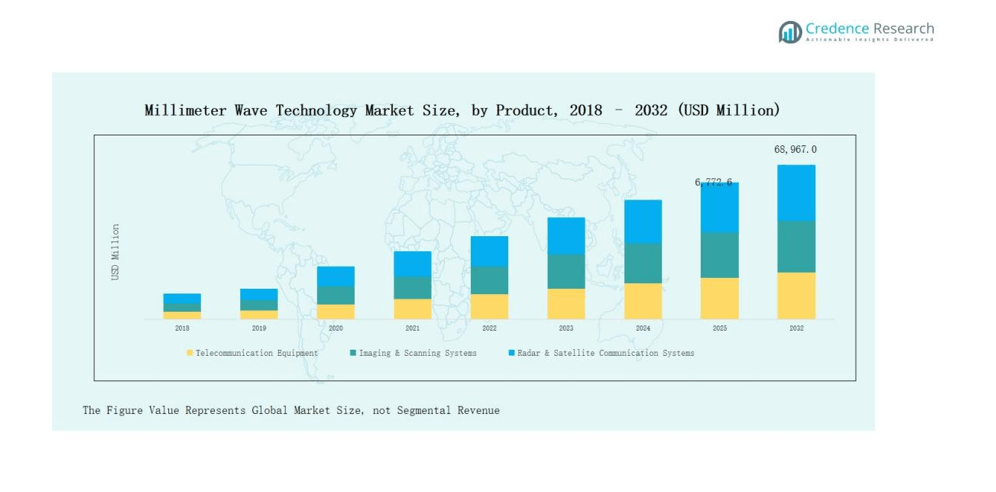
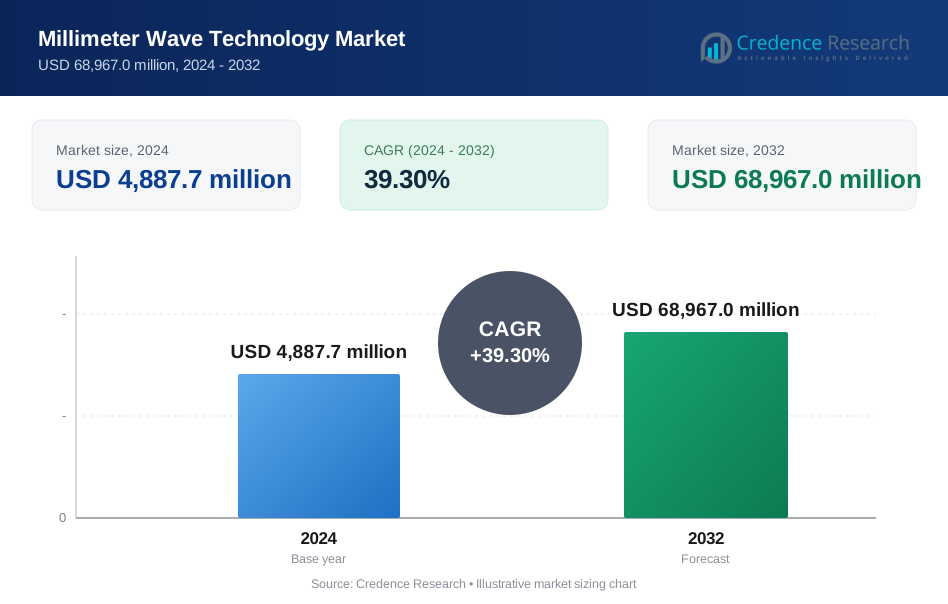
Millimeter Wave Technology Market size was valued at USD 1,520.0 million in 2018 to USD 4,887.7 million in 2024 and is anticipated to reach USD 68,967.0 million by 2032, at a CAGR of 39.3% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Millimeter Wave Technology Market Size 2024 | USD 4,887.7 million |
| Millimeter Wave Technology Market, CAGR | 3.93% |
| Millimeter Wave Technology Market Size 2032 | USD 68,967.0 million |
The millimeter wave technology market is shaped by leading players such as Aviat Networks, BridgeWave Communications, E-Band Communications, Farran Technology, Keysight Technologies, LightPointe Communications, Millitech, NEC Corporation, QuinStar Technology, Eravant, Siklu Communication, and Trex Enterprises. These companies focus on advancing 5G infrastructure, high-capacity backhaul, radar systems, and imaging solutions to strengthen their market presence. Asia Pacific leads the global market with a 41.0% share, supported by large-scale 5G rollouts, rapid urbanization, and significant investments in smart cities, telecommunications, and automotive radar applications, ensuring its position as the dominant regional hub.
Market Insights
- The Millimeter Wave Technology Market grew from USD 1,520.0 million in 2018 to USD 4,887.7 million in 2024 and is expected to reach USD 68,967.0 million by 2032.
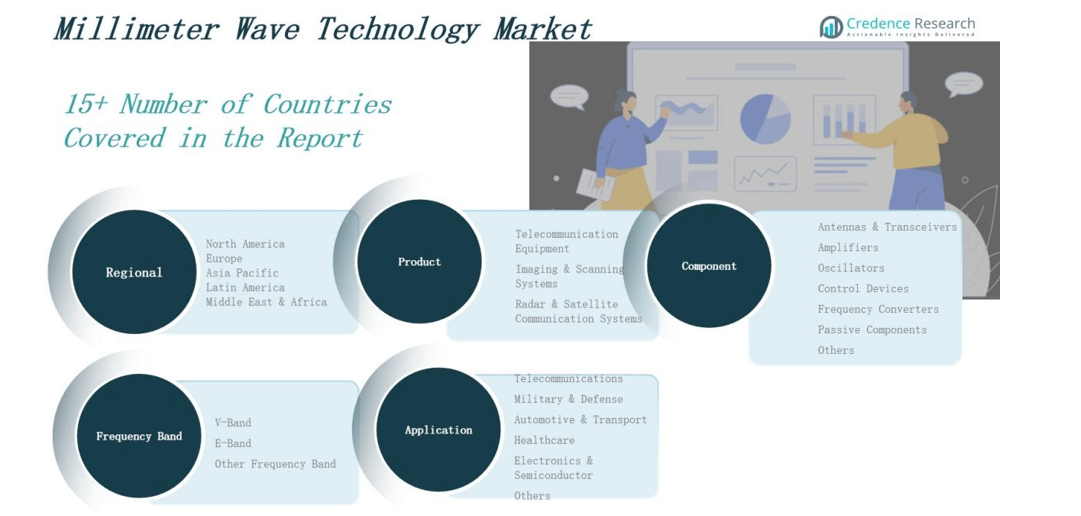
- Telecommunication equipment dominates with a 52% share, driven by rapid 5G deployment, demand for high-bandwidth services, and expansion of advanced wireless infrastructure worldwide.
- Antennas and transceivers lead the component segment with a 34% share, supported by their rising use in base stations, wireless backhaul, and high-frequency communication systems.
- The E-Band segment holds the largest share at 48%, boosted by its ability to deliver multi-gigabit data transfer for telecom backhaul and enterprise-level connectivity solutions.
- Asia Pacific leads the market with a 41.0% share, fueled by rapid urbanization, massive 5G rollout projects, strong smart city investments, and growing automotive radar adoption.
Market Segment Insights
By Product
Telecommunication equipment dominates the millimeter wave technology market with a 52% share. The segment’s growth is driven by rapid 5G deployment, demand for high-bandwidth services, and expansion of advanced wireless infrastructure. Imaging and scanning systems follow, supported by adoption in healthcare diagnostics and security screening, while radar and satellite communication systems gain traction in aerospace, defense, and navigation applications.
- For instance, Verizon’s 5G Ultra Wideband service in the U.S. leverages millimeter wave spectrum to deliver multi‑gigabit speeds in dense urban areas.
By Component
Antennas and transceivers lead the market with a 34% share. Their dominance reflects rising use in base stations, wireless backhaul, and high-frequency communication networks. Amplifiers and oscillators contribute significantly due to their role in enhancing signal strength and stability, while control devices, frequency converters, and passive components address niche requirements in industrial, defense, and healthcare applications.
- For instance, Nokia’s AirScale antenna solutions are deployed in 5G base stations to deliver enhanced coverage and low-latency connectivity.
By Frequency Band
The E-Band segment holds the largest share at 48%, driven by its capacity to support multi-gigabit data transfer for telecom backhaul and enterprise connectivity. The V-Band follows, with strong adoption in urban small-cell networks and indoor communications. Other frequency bands remain vital for defense, automotive radar, and experimental research, offering flexibility for specialized use cases across industries.
Market Overview
5G Deployment and Telecom Expansion
The widespread rollout of 5G networks is a primary driver for the millimeter wave technology market. High-frequency bands enable faster data transfer, low latency, and improved connectivity, making them essential for next-generation communication. Telecom operators are investing heavily in infrastructure upgrades, including small cells and backhaul solutions, to enhance urban network performance. Governments worldwide are releasing spectrum allocations, further boosting adoption. Rising demand for ultra-reliable connectivity in sectors such as smart cities, IoT applications, and autonomous systems reinforces the growth trajectory.
- For instance, Vodafone Idea expanded its 5G network to Jaipur using Ericsson’s energy-efficient radios and AI-powered self-organizing network technology to improve urban connectivity while reducing operational complexity.
Rising Defense and Security Applications
Defense modernization programs are accelerating the adoption of millimeter wave technology for advanced radar, surveillance, and communication systems. Militaries are increasingly using high-frequency bands to improve target detection, secure communications, and battlefield awareness. Imaging and scanning applications also benefit homeland security agencies, which employ millimeter wave scanners for airport screening and perimeter monitoring. With geopolitical tensions driving defense budgets upward, investments in sophisticated communication and surveillance infrastructure continue to rise, positioning the segment as a key growth engine for the market.
- For instance, Boeing's AN/APG-78 Longbow Ka-band fire-control radar uses millimeter waves to track up to 128 targets simultaneously and engage 16 targets within 30 seconds, significantly improving battlefield targeting and situational awareness.
Growing Healthcare and Industrial Use Cases
Healthcare and industrial sectors are witnessing strong adoption of millimeter wave technology for imaging, diagnostics, and non-invasive scanning solutions. Hospitals use it for high-resolution body scanners, while industries deploy it for material characterization, quality inspection, and robotics. The technology’s precision and non-ionizing radiation make it safer for medical diagnostics and industrial inspection compared to alternatives. Rising investment in advanced imaging tools and automation in industries such as manufacturing, aerospace, and pharmaceuticals ensures continuous demand. These factors highlight healthcare and industrial applications as strong contributors to market growth.
Key Trends & Opportunities
Integration with IoT and Smart Devices
The integration of millimeter wave technology with IoT platforms is emerging as a major trend. High-speed, short-range communication supports seamless connectivity for autonomous vehicles, smart wearables, and connected home devices. As IoT ecosystems expand, demand for reliable low-latency networks grows. This creates opportunities for vendors to introduce compact, energy-efficient chipsets and modules. The convergence of IoT and millimeter wave applications will transform industries, enabling new possibilities in telemedicine, logistics automation, and predictive maintenance, driving market opportunities for technology providers.
- For instance, the mmPlug module developed by researchers can be easily connected to the antenna port of any IoT device, enabling it to operate in the millimeter wave band without modifying the device's existing circuitry or firmware.
Advancements in Automotive Radar Systems
Automotive radar is a rapidly growing application, offering strong opportunities for the millimeter wave technology market. Automakers are adopting 77 GHz and higher-band radars for collision avoidance, adaptive cruise control, and autonomous driving. Rising emphasis on road safety regulations and consumer preference for advanced driver assistance systems (ADAS) boost demand. Suppliers are innovating with high-resolution radar sensors that deliver real-time environment mapping. As autonomous vehicle development accelerates, millimeter wave radar is positioned as a critical enabler, creating long-term opportunities across global automotive markets.
- For instance, Infineon offers scalable 77/79 GHz radar chipsets that support applications from short-range parking assistance to long-range autonomous driving functions, enabling precise real-time environment mapping and sensor fusion integration.
Key Challenges
High Infrastructure and Deployment Costs
The deployment of millimeter wave networks requires significant capital investment in base stations, antennas, and supporting infrastructure. Short transmission ranges necessitate dense small-cell installations, increasing rollout costs. For developing economies, high upfront expenditure limits adoption despite the technology’s benefits. Even in developed markets, telecom operators face challenges in balancing investment against return on investment. Cost-effective deployment strategies and infrastructure-sharing models are essential to overcome this barrier, as financial constraints remain one of the major hurdles to widespread adoption.
Limited Propagation and Coverage Issues
Millimeter wave signals face challenges such as high atmospheric absorption, poor penetration through obstacles, and limited coverage range. These factors make the technology less suitable for rural or large-scale outdoor deployments without dense infrastructure support. Weather conditions, including rain and humidity, further affect performance. Such propagation issues restrict seamless connectivity, especially in areas lacking advanced telecom infrastructure. Vendors and operators must invest in innovative solutions such as beamforming, repeaters, and hybrid communication systems to mitigate these limitations and ensure reliable performance.
Regulatory and Spectrum Allocation Barriers
Regulatory frameworks and spectrum allocation policies vary significantly across regions, slowing market growth. In some countries, delayed spectrum auctions and restrictive licensing procedures limit adoption of millimeter wave technologies. Inconsistent global standards complicate interoperability for vendors, creating barriers for large-scale deployments. Moreover, competing demands for spectrum between telecom, defense, and satellite industries add to complexity. Overcoming these regulatory challenges requires coordinated efforts from policymakers, standardization bodies, and industry stakeholders to ensure harmonized allocation and drive broader adoption.
Regional Analysis
North America
North America holds the largest share of the millimeter wave technology market at 39.3%. The region benefits from early 5G adoption, strong telecom infrastructure, and significant investments by major operators in small-cell deployment. High demand from defense, healthcare, and automotive sectors further accelerates growth. Market size has expanded from USD 636.9 million in 2018 to USD 2,026.4 million in 2024, and it is projected to reach USD 28,554.3 million by 2032. Continuous regulatory support and strong R&D activity ensure North America remains a leader throughout the forecast period.
Europe
Europe accounts for 38.3% of the market, driven by rapid digitalization and expanding 5G coverage. Countries like Germany, the UK, and France lead in adoption, while Eastern Europe shows emerging potential. Market revenue grew from USD 377.0 million in 2018 to USD 1,162.2 million in 2024, with forecasts of USD 15,431.6 million by 2032. Strong emphasis on industrial automation, defense modernization, and connected transport systems supports regional growth. Harmonized spectrum policies and EU-backed funding programs further enhance Europe’s role as a significant contributor to the global market.
Asia Pacific
Asia Pacific represents 41.0% of the global share, making it the fastest-growing region. China, Japan, South Korea, and India are major growth engines due to rapid urbanization and massive 5G rollout projects. Market value increased from USD 349.6 million in 2018 to USD 1,177.2 million in 2024, with expectations to reach USD 18,374.9 million by 2032. High consumer demand for advanced smartphones, growing smart city projects, and large-scale manufacturing adoption drive growth. Government-led spectrum allocation and investments in telecom and automotive radar systems strengthen Asia Pacific’s leadership in the market.
Latin America
Latin America contributes 38.0% to the market, supported by increasing telecom investments and expanding connectivity programs. Brazil and Mexico lead adoption, while smaller economies gradually integrate millimeter wave technology into telecom and defense applications. The market expanded from USD 92.7 million in 2018 to USD 295.2 million in 2024, with projections of USD 3,853.9 million by 2032. Rising demand for advanced communication systems and regulatory support for spectrum allocation provide long-term opportunities. However, slower infrastructure development compared to developed regions remains a key restraint.
Middle East
The Middle East holds 36.7% share, driven by adoption in smart cities, defense projects, and telecom modernization. GCC countries, particularly Saudi Arabia and the UAE, lead in 5G infrastructure rollouts and security investments. Market revenue grew from USD 41.0 million in 2018 to USD 120.2 million in 2024, with projections of USD 1,455.6 million by 2032. The region’s focus on high-speed connectivity and diversified economic development fuels adoption. However, reliance on government-led initiatives makes the pace of growth uneven across different Middle Eastern countries.
Africa
Africa represents 36.1% of the market, with gradual growth fueled by telecom expansion and rising demand for digital connectivity. South Africa, Nigeria, and Egypt are primary adopters, while other countries remain in early development stages. The market increased from USD 22.8 million in 2018 to USD 106.6 million in 2024, and it is expected to reach USD 1,296.8 million by 2032. Growing investments in mobile broadband and healthcare imaging systems are improving adoption rates. However, infrastructure gaps and limited spectrum allocation remain major challenges for widespread market penetration.
Market Segmentations:
By Product
- Telecommunication Equipment
- Imaging & Scanning Systems
- Radar & Satellite Communication Systems
By Component
- Antennas & Transceivers
- Amplifiers
- Oscillators
- Control Devices
- Frequency Converters
- Passive Components
- Others
By Frequency Band
- V-Band
- E-Band
- Other Frequency Bands
By Application
- Telecommunications
- Military & Defense
- Automotive & Transport
- Healthcare
- Electronics & Semiconductor
- Others
By Region
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
The competitive landscape of the millimeter wave technology market is defined by intense rivalry among global and regional players focusing on innovation, strategic partnerships, and expansion across telecom, defense, and industrial sectors. Key companies such as Aviat Networks, BridgeWave Communications, Keysight Technologies, NEC Corporation, Siklu Communication, and Trex Enterprises emphasize product advancements in antennas, transceivers, and high-capacity backhaul solutions to capture market share. Vendors are actively investing in research and development to enhance performance, reduce costs, and address challenges related to limited propagation and high deployment expenses. Strategic mergers, acquisitions, and collaborations with telecom operators and defense organizations further strengthen their positions. Emerging players are entering with niche solutions targeting healthcare imaging, automotive radar, and smart city applications. With Asia Pacific leading the market, companies are increasingly prioritizing this region for expansion due to strong 5G infrastructure growth and rising demand for advanced connectivity, making competition more dynamic and innovation-driven.
Key Players
- Aviat Networks, Inc.
- BridgeWave Communications
- E-Band Communications, LLC
- Farran Technology
- Keysight Technologies
- LightPointe Communications, Inc.
- Millitech, Inc.
- NEC Corporation
- QuinStar Technology, Inc.
- Eravant
- Siklu Communication Ltd.
- Trex Enterprises Corporation
Recent Developments
- l In August 2023, Siklu (now part of Ceragon Networks) introduced the MultiHaul™ TG T261 terminal unit, its smallest point-to-multipoint 60 GHz millimeter wave product.
- In December 2023, Eravant (formerly SAGE Millimeter Inc.) received a patent (US No. 11,804,681) for its Uni-Guide™ waveguide connector, designed to simplify mmWave component integration while reducing cost and design complexity.
- In March 2025, Maury Microwave acquired millimeter-wave and sub-THz load-pull IP from Vertigo Technologies, expanding its testing capabilities up to 1.1 THz.
- In February 2025, Ceragon launched new mmWave backhaul products at MWC 2025, including EtherHaul 8020FX, IP-100E, IP-50GP, and IP-50EXA, strengthening high-capacity wireless transport solutions.
Market Concentration & Characteristics
The Millimeter Wave Technology Market demonstrates moderate to high concentration, with a mix of established players and emerging innovators driving competition. It is characterized by rapid technological advancements, strong dependence on spectrum availability, and high capital requirements for infrastructure development. Leading companies such as Aviat Networks, Keysight Technologies, NEC Corporation, and Siklu Communication focus on expanding their product portfolios to address applications in telecommunications, defense, automotive, and healthcare. It shows strong growth potential due to 5G deployment and demand for high-capacity data transfer, though challenges like limited propagation and deployment costs persist. The market emphasizes innovation in antennas, transceivers, and radar systems, with vendors prioritizing energy efficiency and miniaturization. Strategic collaborations, regulatory support for spectrum allocation, and increasing adoption in smart cities further define its characteristics. With Asia Pacific leading in adoption and North America maintaining strong presence, it reflects a dynamic and innovation-driven competitive structure supported by sustained investments.
Report Coverage
The research report offers an in-depth analysis based on Produt, Application, Frequency Band, Component and Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Demand for 5G infrastructure will continue to drive widespread adoption of millimeter wave technology.
- Telecom operators will expand small-cell deployments to support dense urban connectivity.
- Defense and aerospace sectors will increase adoption for advanced radar and secure communication systems.
- Automotive manufacturers will integrate millimeter wave radar for ADAS and autonomous driving.
- Healthcare providers will adopt imaging solutions for non-invasive diagnostics and patient monitoring.
- Industrial sectors will utilize the technology for automation, robotics, and quality inspection.
- Vendors will prioritize energy-efficient and miniaturized components for broader applications.
- Spectrum allocation and regulatory harmonization will influence market penetration across regions.
- Strategic partnerships between telecom providers and equipment manufacturers will strengthen competitive positions.
- Asia Pacific will remain the primary growth hub due to large-scale smart city and telecom investments.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Millimeter Wave Technology Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Millimeter Wave Technology Market projected to grow between 2025 and 2032?
Which Millimeter Wave Technology Market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Millimeter Wave Technology Market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue) (Volume Where Applicable)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Millimeter Wave Technology Scope – Segments & Subsegments Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 Industry Classification & Applicable Codes
- 1.5 Currency, Measurement Units & Valuation Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Millimeter Wave Technology Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 4,887.7 million → 2032: USD 68,967.0 million)
- 2.1.2 Volume & Revenue – Global Totals (Volume Where Applicable)
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Millimeter Wave Technology Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024 (Volume Where Applicable)
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Millimeter Wave Technology Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Millimeter Wave Technology Market Position in the Broader Industry Value Chain
- 3.1.2 Demand Structure & Purchasing Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Millimeter Wave Technology Market Drivers
- 3.3 Millimeter Wave Technology Market Restraints & Challenges
- 3.4 Millimeter Wave Technology Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Millimeter Wave Technology Value Chain Analysis
- 3.6.1 Upstream – Key Inputs, Resources & Suppliers
- 3.6.1.1 Key Input/Resource 1
- 3.6.1.2 Key Input/Resource 2
- 3.6.1.3 Key Input/Resource 3
- 3.6.2 Midstream – Core Operations & Value Creation
- 3.6.2.1 Operating Model & Process Overview
- 3.6.2.2 Key Operating Locations & Capabilities by Company
- 3.6.3 Downstream – Market Channels & End Users
- 3.6.3.1 Direct Sales & Customer Engagement Channels
- 3.6.3.2 Indirect Sales, Intermediaries & Partner Channels
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Key Inputs, Resources & Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Millimeter Wave Technology Supply Chain Analysis
- 3.8.1 Critical Input & Resource Availability Risk Assessment
- 3.8.2 Supplier & Operational Concentration Risk (Geographic Exposure)
- 3.8.3 Supply & Service Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Millimeter Wave Technology category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Millimeter Wave Technology Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Market Size × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute Revenue Growth Through 2032
- 4.3 Incremental Demand Opportunity
- 4.3.1 By Region – Incremental Demand Through 2032
- 4.3.2 Segment – Incremental Demand
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Priority Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Priority market opportunity scorecards reflect the geographic scope and strategic relevance of the study. Listed markets are indicative and may be adapted to the industry.
Chapter 5. Millimeter Wave Technology Cross-Border Trade & Market Access Analysis
- 5.1 International Trade & Cross-Border Activity Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024) (Volume Where Applicable)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024) (Volume Where Applicable)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Category 1 (Applicable Classification Code)
- 5.2.2 Category 2 (Applicable Classification Code)
- 5.2.3 Category 3 (Applicable Classification Code)
- 5.2.4 Category 4 (Applicable Classification Code)
- 5.2.5 Category 5 (Applicable Classification Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Category 1 (Applicable Classification Code)
- 5.3.2 Category 2 (Applicable Classification Code)
- 5.3.3 Category 3 (Applicable Classification Code)
- 5.3.4 Category 4 (Applicable Classification Code)
- 5.3.5 Category 5 (Applicable Classification Code)
- 5.4 Cross-Border Pricing & Transaction Benchmarks
- 5.4.1 Export Pricing – Segment & Country
- 5.4.2 Import Pricing – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Cross-Border Trade & Delivery Routes
- 5.5.1 Cross-Border Trade/Delivery Route 1
- 5.5.2 Cross-Border Trade/Delivery Route 2
- 5.5.3 Cross-Border Trade/Delivery Route 3
- 5.5.4 Cross-Border Trade/Delivery Route 4
- 5.5.5 Cross-Border Trade/Delivery Route 5
- 5.6 Trade Policy & Market Access Impact Assessment
- 5.6.1 Tariff & Non-Tariff Barriers
- 5.6.2 Regional Trade & Economic Integration Frameworks
- 5.6.3 Bilateral & Multilateral Trade Agreements
- 5.6.4 Cross-Border Operating, Licensing & Localization Requirements
Note: This chapter applies where cross-border trade or delivery is relevant to Millimeter Wave Technology. Goods, services, and digital offerings are assessed using applicable classifications and transaction measures. Import-export volumes, trade balances, and route analyses are included only where meaningful to the market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Millimeter Wave Technology Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Leading, Mid-Sized & Emerging Player Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Millimeter Wave Technology Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company (Volume Where Applicable)
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 Company Market Share by Key Segment
- 6.2.6 Company Market Share by Customer Group
- 6.3 Operating Scale, Capacity & Infrastructure Analysis
- 6.3.1 Global Operating Scale & Supply Capacity
- 6.3.2 Resource Utilization & Operating Efficiency
- 6.3.3 Output, Service Delivery & Activity Metrics
- 6.3.4 Operating Footprint & Infrastructure Map
- 6.3.5 Planned Operational & Capacity Expansion
- 6.4 Millimeter Wave Technology Competitive Benchmarking Matrix
- 6.4.1 Revenue, Growth, Profitability & Operating Metric Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Millimeter Wave Technology (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Products, Services & Solutions in Millimeter Wave Technology
- 6.5.3 Operational & Infrastructure Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Millimeter Wave Technology Market – By Sales & Delivery Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032) (Volume Where Applicable)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share (Volume Where Applicable)
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region (Volume Where Applicable)
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Sales & Delivery Channel
- 8.2.2 By Competitive Positioning & Price Tier
Chapter 9. North America Millimeter Wave Technology Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Millimeter Wave Technology Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Millimeter Wave Technology Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Millimeter Wave Technology Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Millimeter Wave Technology Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Millimeter Wave Technology Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Millimeter Wave Technology Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Supply, Output & Operating Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Demand, Adoption & Usage Assumptions
- Appendix F – Pricing & Revenue Metric Reference Tables
- Appendix G – Company Operations & Infrastructure Database
- Appendix H – Cross-Border Trade & Activity Data Tables (Where Applicable)
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
