
Market Overview
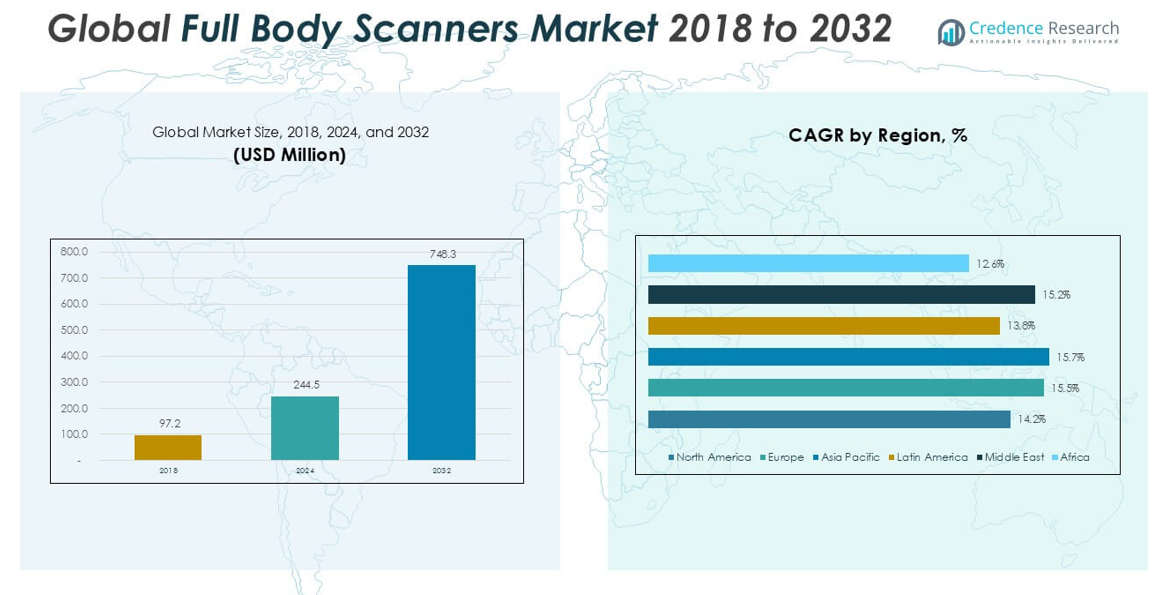
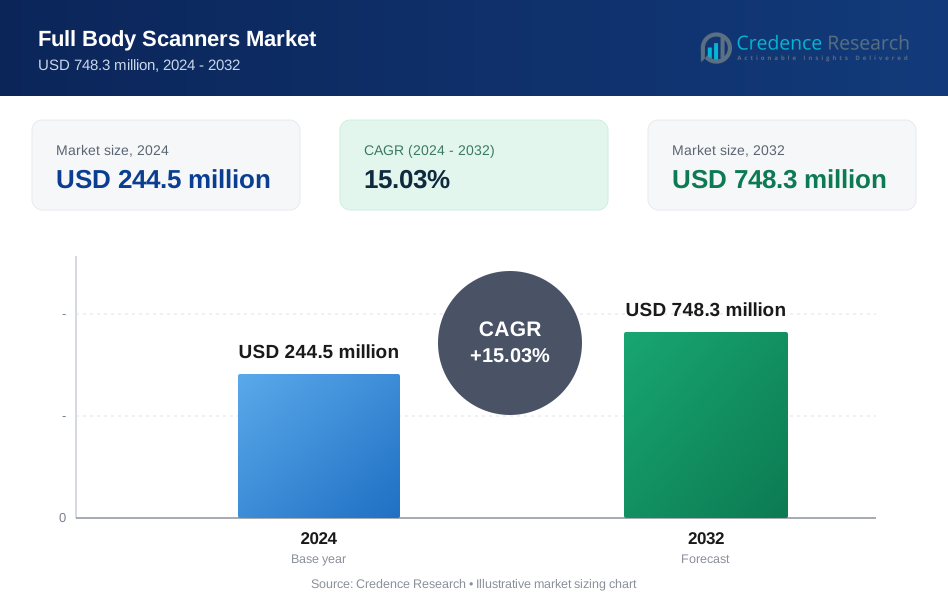
The Global Full Body Scanners Market is projected to grow from USD 244.5 million in 2024 to an estimated USD 748.3 million by 2032, with a compound annual growth rate (CAGR) of 15.03% from 2025 to 2032.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Full Body Scanners Market Size 2024 | USD 244.5 million |
| Full Body Scanners Market, CAGR | 15.03% |
| Full Body Scanners Market Size 2032 | USD 748.3 million |
Key drivers fueling the full body scanners market include heightened global security concerns, especially at airports and borders, and the growing need for non-invasive, efficient screening methods. Technological trends such as the integration of artificial intelligence (AI) and machine learning in scanner systems are enhancing accuracy and reducing false alarms. Additionally, regulatory support and funding for security infrastructure upgrades are boosting market penetration across various sectors. The rising adoption of millimeter wave and backscatter X-ray technologies is also shaping product innovation and performance enhancement.
Geographically, North America holds a dominant position in the full body scanners market due to its early adoption of security technologies and robust investments in transportation and border security infrastructure. Europe follows closely, driven by stringent aviation security protocols. Meanwhile, the Asia-Pacific region is expected to witness the fastest growth, propelled by increasing airport construction and urban security initiatives in emerging economies like China and India. Key players operating in the global market include Smiths Detection, L3Harris Technologies, Leidos Holdings, Rapiscan Systems, and Rohde & Schwarz.
Market Insights
- The Global Full Body Scanners Market is expected to grow from USD 244.5 million in 2024 to USD 748.3 million by 2032, at a CAGR of 15.03% from 2025 to 2032.
- Increasing global security threats are accelerating the demand for advanced, non-invasive screening technologies across public and transportation sectors.
- Integration of AI and machine learning in scanners is improving detection accuracy and reducing operational inefficiencies.
- Government funding and regulatory support for security infrastructure upgrades are fueling product adoption worldwide.
- High initial investment and operational costs are limiting adoption in budget-constrained regions and smaller facilities.
- Privacy concerns and regulatory restrictions on imaging technology continue to pose challenges to widespread deployment.
- North America leads the market, while Asia Pacific is projected to witness the fastest growth due to infrastructure development in emerging economies.
Market Drivers
Rising Demand for Enhanced Security Across Transportation Hubs
Governments and private operators are investing heavily in advanced security infrastructure to address evolving threats in public transportation. The Global Full Body Scanners Market benefits directly from stringent screening protocols at airports, rail stations, and seaports. Full body scanners offer a non-intrusive method for detecting concealed objects, making them an essential tool in high-traffic locations. With increasing air travel and cargo movement, airport authorities are prioritizing faster and more effective screening solutions. Regulatory mandates in regions such as North America and Europe require the use of advanced imaging systems, which supports market growth. It continues to gain traction due to the balance it offers between passenger convenience and threat detection.
- For instance, airport authorities in North America and Europe have rolled out thousands of full body scanners in recent years; by 2025, the commercial airport segment alone will account for installations in more than 300 major international airports globally, with leading security equipment providers like Smiths Detection and Rapiscan Systems supporting these rollouts.
Technological Advancements Improving Accuracy and Efficiency
Manufacturers are integrating AI and machine learning to improve the performance of full body scanners. These technologies reduce false positives and enable quicker, more accurate identification of potential threats. The market is witnessing a shift from conventional detection systems to millimeter wave and backscatter X-ray technologies, which provide detailed imaging with reduced privacy concerns. It also supports real-time threat analysis and enhances decision-making capabilities for security personnel. Compact and mobile scanner models are gaining popularity in smaller transit points and event venues. The Global Full Body Scanners Market benefits from these innovations by offering flexible solutions suited for a variety of environments.
- For instance, as of early 2025, leading global manufacturers have introduced over 100 models of AI-enabled, millimeter-wave and backscatter X-ray full body scanners to the market, with rapid adoption in both fixed and portable configurations to meet evolving airport and rail station security requirements
Increasing Investments in Urban and Critical Infrastructure Security
Full body scanners are becoming integral to security frameworks in government buildings, prisons, and commercial complexes. Rising geopolitical tensions and domestic threats have led to increased security budgets in several countries. Authorities are deploying full body scanners to prevent the entry of weapons, contraband, or explosives into secure zones. It serves a growing need for rapid and reliable screening without creating bottlenecks in high-flow environments. The market is responding with scalable products that can be deployed in permanent or temporary settings. The Global Full Body Scanners Market continues to evolve to meet infrastructure-specific security demands.
Growing Focus on Passenger Experience and Operational Efficiency
Security solutions must deliver both safety and speed, especially in travel and event industries. Full body scanners minimize physical pat-downs, reducing discomfort and wait times for individuals. Operators value systems that deliver fast throughput while maintaining high detection standards. It supports smoother passenger flow and reduces overall operational costs for security teams. The demand for user-friendly interfaces and automated threat recognition has increased among public and private users. The Global Full Body Scanners Market aligns with these expectations by offering systems that meet security needs without disrupting service delivery.
Market Trends
Adoption of AI-Powered Threat Detection Enhancing Screening Accuracy
Security providers are integrating artificial intelligence into full body scanner systems to improve accuracy and threat recognition. AI-powered analytics help reduce false alarms and improve the identification of concealed weapons or prohibited items. These systems can process large volumes of scans rapidly, which supports better throughput in busy environments. It enables real-time image interpretation, assisting security staff in making faster and more confident decisions. The Global Full Body Scanners Market is benefiting from this trend as stakeholders seek smarter, more adaptive detection capabilities. AI integration is becoming a standard expectation in new procurement contracts.
- For instance, according to industry analysis, U.S. airports screened over 858 million passengers in 2023 using body scanners-these screenings resulted in the detection of 6,737 firearms at checkpoints, with AI-powered systems playing a key role in automating threat recognition and streamlining large-scale scan processing
Shift Toward Privacy-Respecting Imaging Technologies
Growing public concern over personal privacy is shaping the design of next-generation full body scanners. Manufacturers are introducing systems that use generic, non-identifiable avatars instead of detailed body images. These innovations allow effective threat detection without revealing anatomical features. It addresses regulatory requirements and public resistance, especially in Europe and North America. The Global Full Body Scanners Market is responding to privacy-driven regulations by aligning product development with ethical and legal standards. This shift strengthens acceptance and broadens the scope for scanner use in civilian environments.
- For instance, the U.S. Transportation Security Administration deployed nearly 630 units with privacy software-such as automated target recognition (ATR)-across more than 150 airports, with future procurement restricted to privacy-enhanced systems that display only generic avatar figures on screens rather than anatomical images
Expansion of Security Applications Beyond Airports
Full body scanners are increasingly being deployed in sectors outside traditional aviation settings. High-security venues such as correctional facilities, stadiums, data centers, and border checkpoints are implementing these systems to manage growing security risks. Demand is rising from government and commercial users seeking rapid screening for large groups. It reflects a broader understanding that full body scanners can serve diverse environments beyond airports. The Global Full Body Scanners Market is growing in scope, with manufacturers tailoring products to suit the needs of non-aviation sectors. Portable and modular units are supporting this trend by enabling flexible deployment.
Growing Emphasis on Contactless and Automated Solutions
The shift toward contactless technologies has accelerated in public security infrastructure. Full body scanners that offer touch-free screening have gained preference in post-pandemic environments. Automated detection and alert systems reduce human error and require minimal operator interaction. It improves user experience while maintaining high security standards. The Global Full Body Scanners Market is aligning with these expectations by offering solutions that reduce physical intervention and streamline operations. This trend is expected to define procurement strategies for both government and private buyers in the coming years.
Market Challenges
High Initial Costs and Budget Constraints Limiting Widespread Adoption
The high cost of full body scanners poses a major challenge for widespread deployment, particularly in developing regions and smaller transportation hubs. Procurement, installation, and maintenance demand significant capital investment, which many public institutions and private operators find difficult to allocate. Budget limitations restrict the ability to upgrade existing security systems or expand coverage to non-traditional areas. The Global Full Body Scanners Market faces hurdles in reaching price-sensitive customers despite its proven effectiveness. It must address cost-efficiency through modular systems and scalable deployment options. Financial constraints continue to slow market penetration in low- and middle-income countries.
- For instance, according to a U.S. Government Accountability Office (GAO) report, the Transportation Security Administration purchased over 900 advanced imaging technology scanners between 2008 and 2021, but unit and installation costs ranged from 130,000 to 180,000 USD per machine, making it difficult for smaller airports and institutions to justify widespread adoption.
Public Concerns Over Privacy and Health Impact Adoption Rates
Concerns about individual privacy and potential health risks from radiation-based scanners remain persistent across various regions. Although manufacturers have introduced privacy-enhancing features, skepticism regarding image storage and misuse lingers among travelers and advocacy groups. In some jurisdictions, regulatory frameworks restrict or delay the use of certain scanner technologies. It creates operational uncertainty and increases compliance costs for market participants. The Global Full Body Scanners Market must work within strict regulatory boundaries while building public trust through transparency and safer technologies. Public resistance can limit acceptance and delay deployments, particularly in regions with strong data protection laws.
Market Opportunities
Expansion into Non-Aviation Sectors Creating New Revenue Streams
The growing need for high-level security in venues beyond airports presents a significant opportunity for market expansion. Full body scanners are gaining traction in government buildings, correctional facilities, stadiums, and corporate campuses. These locations require fast, reliable screening solutions to manage large crowds and sensitive environments. The Global Full Body Scanners Market can capitalize on this shift by offering compact and mobile units tailored for varied infrastructure. It allows vendors to diversify their client base and reduce reliance on the aviation sector. Broader application in urban security planning enhances the market’s long-term growth potential.
Technological Advancements Enabling Product Differentiation and Adoption
Advances in artificial intelligence, automation, and privacy-respecting imaging are opening new avenues for product innovation. These technologies improve detection speed and accuracy while addressing user concerns around privacy and efficiency. Buyers seek intelligent systems that require minimal human oversight and adapt to changing threat landscapes. The Global Full Body Scanners Market stands to gain from investments in AI-driven software and user-centric design. It can drive adoption by offering customized solutions for different operational needs. Continuous innovation positions suppliers to meet demand from both government and private sectors seeking future-ready security infrastructure.
Market Segmentation Analysis
By Product
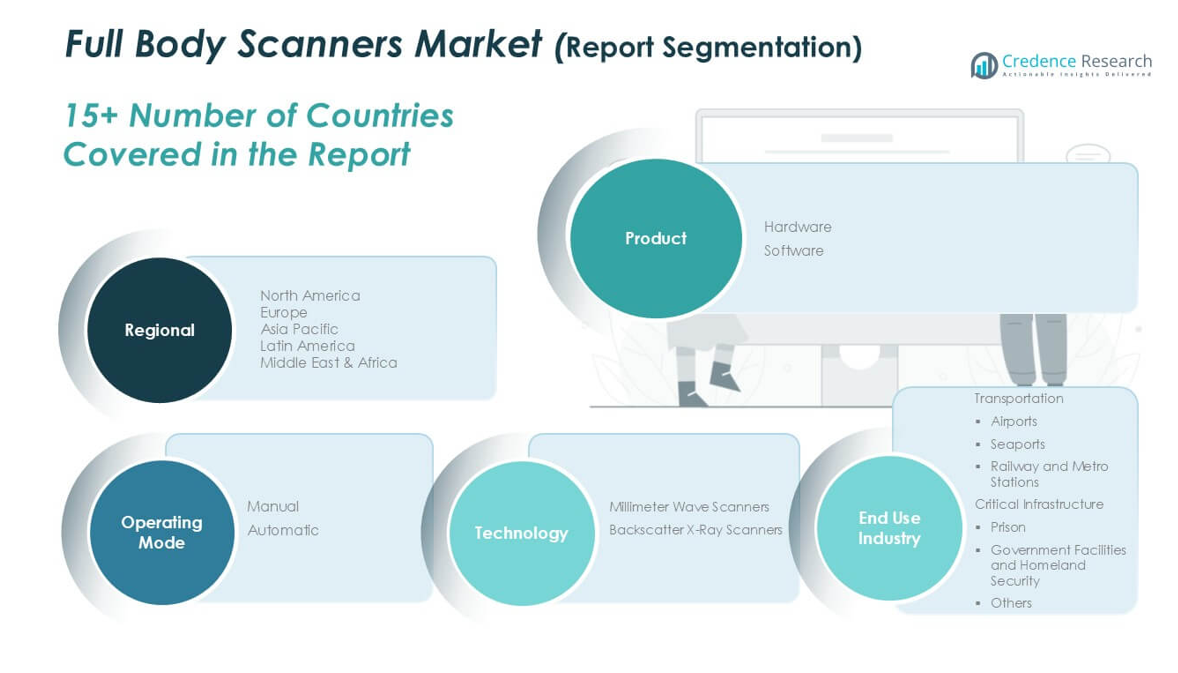
The Global Full Body Scanners Market is segmented into hardware and software components. Hardware accounts for a larger revenue share due to the high cost and critical role of physical scanning units in threat detection. These include millimeter wave and X-ray imaging systems installed at security checkpoints. Software plays a growing role, particularly in enhancing scanner functionality through real-time image analysis, threat detection algorithms, and data integration. It supports operators in decision-making and enables remote monitoring. The increasing demand for AI-enabled software solutions is expected to drive the software segment at a faster pace over the forecast period.
- For instance, according to Novartis’ 2023 annual report, their flagship immunomodulator drug Fingolimod (sold as Gilenya) generated $2.1 billion in global sales in 2023,highlighting the dominant market position of immunomodulators among MS therapies.
By Operating Mode
The market is divided into manual and automatic operating modes. Manual systems involve operator intervention for image interpretation and threat identification, making them more suitable for low-traffic areas. Automatic systems, however, are gaining preference due to their ability to process high volumes with minimal human input. It supports faster throughput and standardizes detection accuracy across environments. The shift toward automation is driven by the need for operational efficiency, especially in airports and busy public venues. The automatic segment is expected to grow at a robust pace due to continuous technology upgrades.
- For instance, data from the IQVIA Institute show that the global market for oral MS drugs grew to $12.4 billion in revenues in 2022, with a five-year CAGR of nearly 11,000 million USD added to this segment since 2018, underlining the rapid adoption of oral therapies.
By Technology
Millimeter wave scanners and backscatter X-ray scanners form the primary technology segments. Millimeter wave scanners hold a major share due to their non-ionizing radiation and higher acceptance in public spaces. They offer fast scanning and improved privacy, making them ideal for passenger screening. Backscatter X-ray scanners provide detailed imaging and are used where high-resolution threat detection is essential. The Global Full Body Scanners Market sees growing demand for millimeter wave technology driven by evolving safety and compliance standards. It is expected to remain dominant due to its favorable safety profile and regulatory support.
By End User Industry
Key end-user industries include transportation and critical infrastructure. Within transportation, airports represent the largest segment, followed by seaports and railway stations. These hubs prioritize full body scanners to meet international security mandates and passenger screening requirements. Critical infrastructure applications include prisons, government facilities, and homeland security operations. These settings rely on full body scanners for preventing contraband and maintaining controlled access. It supports consistent threat detection in high-risk environments. The market continues to grow in both segments due to increased security funding and risk mitigation initiatives.
Segments
Based on Product
- Hardware
- Software
Based on Operating Mode
- Manual
- Automatic
Based on Technology
- Millimeter Wave Scanners
- Backscatter X-Ray Scanners
Based on End User Industry
- Transportation
- Airports
- Seaports
- Railway and Metro Stations
- Critical Infrastructure
- Prison
- Government Facilities and Homeland Security
- Others
Based on Region
- North America
- U.S.
- Canada
- Mexico
- Europe
- UK
- France
- Germany
- Italy
- Spain
- Russia
- Belgium
- Netherlands
- Austria
- Sweden
- Poland
- Denmark
- Switzerland
- Rest of Europe
- Asia Pacific
- China
- Japan
- South Korea
- India
- Australia
- Thailand
- Indonesia
- Vietnam
- Malaysia
- Philippines
- Taiwan
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Peru
- Chile
- Colombia
- Rest of Latin America
- Middle East
- UAE
- KSA
- Israel
- Turkey
- Iran
- Rest of Middle East
- Africa
- Egypt
- Nigeria
- Algeria
- Morocco
- Rest of Africa
Regional Analysis
North America Fidget Toys Market
North America held a market size of USD 52.96 million in 2024 and is projected to reach USD 153.02 million by 2032, growing at a CAGR of 14.2%. The region accounted for approximately 21.3% of the global market share in 2024. The rising demand for stress-relief tools among students and working professionals is fueling growth. Retail expansion through e-commerce platforms and the popularity of innovative designs are increasing product visibility. The Fidget Toys Market in North America benefits from high consumer spending on wellness and recreational items. It continues to expand in the United States and Canada due to increased awareness of sensory development products.
Europe Fidget Toys Market
Europe’s market was valued at USD 65.64 million in 2024 and is expected to reach USD 208.17 million by 2032, registering a CAGR of 15.5%. The region contributed 26.4% to the global market share in 2024. Growth is driven by the adoption of fidget toys in educational institutions and growing awareness around mental health. Countries such as Germany, the UK, and France lead in consumption, supported by product innovation and favorable retail channels. The Fidget Toys Market in Europe is further supported by wellness trends and increasing demand for ADHD-friendly products. It is witnessing rising popularity in both children’s toys and adult stress-relief segments.
Asia Pacific Fidget Toys Market
Asia Pacific led the global market with a value of USD 76.83 million in 2024 and is forecasted to reach USD 246.93 million by 2032, growing at a CAGR of 15.7%. Holding a 30.9% market share in 2024, it is the largest regional contributor. Increasing disposable incomes, rising parental awareness, and a high youth population support strong demand across China, India, and Japan. The Fidget Toys Market in Asia Pacific benefits from local manufacturing and online sales channels. It is rapidly expanding due to increasing attention to child development and concentration tools. Schools and therapy centers are emerging as key end users.
Latin America Fidget Toys Market
Latin America recorded a market size of USD 23.99 million in 2024, projected to grow to USD 67.34 million by 2032 at a CAGR of 13.8%. The region contributed approximately 9.7% to the global market share in 2024. Brazil and Mexico are the primary growth engines due to rising middle-class consumption and growing interest in behavioral aids. The Fidget Toys Market in Latin America is gaining traction in retail stores and through social media promotions. It faces challenges from pricing sensitivity, but local brands are entering the market with affordable alternatives. The sector shows strong potential in educational and healthcare institutions.
Middle East Fidget Toys Market
The Middle East market stood at USD 15.62 million in 2024 and is forecasted to reach USD 48.26 million by 2032, with a CAGR of 15.2%. It accounted for 6.3% of the global market share in 2024. The market is expanding in the UAE and Saudi Arabia due to increased retail access and growing parental interest in developmental toys. The Fidget Toys Market in the Middle East benefits from rising health consciousness and attention to child mental well-being. It is supported by rising demand for non-digital toys that promote focus and motor skills. Schools and therapy centers are integrating these tools for cognitive support.
Africa Fidget Toys Market
Africa’s market value was USD 9.50 million in 2024 and is expected to reach USD 24.54 million by 2032, growing at a CAGR of 12.6%. The region held a 3.8% share of the global market in 2024. South Africa and Nigeria are witnessing moderate growth supported by an emerging middle class and awareness initiatives. The Fidget Toys Market in Africa is at an early growth stage but shows promise in urban areas. It is gradually gaining attention through school supply programs and NGO-driven campaigns focused on children with learning disabilities. Market development depends on affordability, local distribution, and education-based adoption.
Key players
- Smiths Detection
- Leidos Security Detection & Automation
- LINEV Systems
- OD Security
- TEK 84 Inc.
- Westminster International Ltd.
- Iscon Imaging
- Millivision Technologies
- Nuctech Company Limited
- Brijot Imaging Systems, Inc
Competitive Analysis
The Global Full Body Scanners Market is highly competitive with both multinational corporations and specialized technology firms actively shaping its dynamics. Companies like Smiths Detection and Leidos lead with extensive product portfolios and strong financial backing. Emerging players such as TEK 84 Inc. and Iscon Imaging focus on innovation and niche applications to gain market traction. The market sees continuous investments in AI-driven scanning systems and privacy-compliant imaging solutions. It offers opportunities for firms that can meet regulatory standards while delivering scalable and cost-effective technologies. Regional players compete by offering customized solutions for local infrastructure and security needs. The competitive landscape is defined by rapid technological advancements and a clear emphasis on public safety and operational efficiency.
Recent Developments
- In March 2025, Smiths Detection formed an AI integration alliance with Deepnoid (South Korea) to advance threat detection capabilities.
- In February 2025, Leidos Security Detection & Automation partnered with SeeTrue to integrate AI-powered threat-detection algorithms into its ClearScan CT platforms.
Market Concentration and Characteristics
The Global Full Body Scanners Market exhibits moderate to high market concentration, with a few established players dominating global sales through government contracts and airport security deals. Companies such as Smiths Detection, Leidos, and Nuctech hold significant shares due to their technological capabilities and global presence. It is characterized by high entry barriers, including stringent regulatory approvals, capital-intensive product development, and the need for advanced imaging expertise. The market favors firms that can offer reliable, privacy-compliant, and efficient scanning solutions tailored to diverse security settings. Technological innovation, strong customer support, and adherence to safety standards are critical factors influencing competitiveness. The presence of niche players introducing specialized systems contributes to product variety and regional diversification.
Report Coverage
The research report offers an in-depth analysis based on Product, Operating Mode, Technology, End User Industry and Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Governments will continue to expand full body scanner installations in high-footfall areas such as stadiums, metro stations, and event venues. This expansion will support broader public security objectives beyond traditional aviation applications.
- AI-driven threat detection will become standard, improving screening speed and accuracy while minimizing human error. Systems will leverage machine learning to analyze complex patterns and reduce false alarms.
- Post-pandemic hygiene awareness will drive demand for touch-free scanning systems. Users will prefer devices that offer fast, accurate screening with minimal physical interaction.
- Emerging economies in Asia Pacific, Latin America, and the Middle East will invest in security infrastructure, driving new opportunities. Local governments will focus on enhancing border control and critical facility protection.
- Manufacturers will prioritize scanners with privacy-respecting imaging modes to align with evolving global data protection laws. Public acceptance will improve with non-intrusive, anonymous display features.
- Private sector demand will grow, especially in data centers, corporate offices, and manufacturing sites requiring strict access control. The shift will diversify revenue beyond government contracts.
- Compact, easy-to-deploy scanners will gain popularity for temporary events, mobile security checkpoints, and emergency response setups. These units will meet the need for rapid deployment in dynamic settings.
- Countries will move toward harmonized safety and performance regulations for full body scanners. Standardization will ease international procurement and increase cross-border equipment compatibility.
- New generations of millimeter wave and backscatter X-ray systems will offer enhanced resolution, faster processing, and reduced energy usage. This innovation will improve threat detection while lowering operational costs.
- Vendors will engage in partnerships with governments and security agencies to co-develop customized scanning solutions. These collaborations will shape long-term procurement pipelines and ensure technology relevance.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Heightened Global Security Concerns
Increasing threats at airports, borders, and public venues are prompting governments and private operators to invest in advanced full body scanners, making them essential for non-intrusive, efficient screening.
Technological Advancements in AI and Imaging
Integration of artificial intelligence and machine learning in scanner systems is enhancing detection accuracy, reducing false alarms, and enabling real-time threat analysis, which drives adoption across high-traffic environments.
Regulatory Support and Security Infrastructure Funding
Government mandates and funding for security upgrades, especially in North America and Europe, are accelerating the deployment of full body scanners in transportation and critical infrastructure sectors.
Expansion into Non-Aviation Sectors
The adoption of full body scanners is expanding beyond airports to include prisons, government buildings, stadiums, and corporate campuses, opening new revenue streams and diversifying market growth.
Focus on Privacy-Respecting and Contactless Solutions
Growing public concern over privacy and post-pandemic hygiene awareness are driving demand for scanners with privacy-enhancing features and touch-free operation, increasing acceptance and deployment in civilian environments.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the market size of the Global Full Body Scanners Market in 2023 and its forecast for 2032?
Which technologies are most commonly used in full body scanners?
Which regions are leading in the adoption of full body scanners?
Who are the major players in the Global Full Body Scanners Market?
Who are the major players in this market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Product
- 1.2.1 Hardware
- 1.2.2 Software
- 1.3 By Technology
- 1.3.1 Millimeter Wave Scanners
- 1.3.2 Backscatter X-Ray Scanners
- 1.4 By Operating Mode
- 1.4.1 Manual
- 1.4.2 Automatic
- 1.5 By End User Industry
- 1.5.1 Airports
- 1.5.2 Seaports
- 1.5.3 Railway and Metro Stations
- 1.5.4 Prison
- 1.5.5 Government Facilities and Homeland Security
- 1.5.6 Others
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 244.5 million → 2032: USD 748.3 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Full Body Scanners Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Full Body Scanners Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Full Body Scanners Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Full Body Scanners Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Full Body Scanners Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Full Body Scanners Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Data Protection, AI and Cybersecurity Compliance
- 9.8 Upcoming Policy Changes and Market Implications
Chapter 10 Global Full Body Scanners Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Full Body Scanners Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 244.5 million → 2032: USD 748.3 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Full Body Scanners Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Product - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Hardware
- 12.3.7.2 Software
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Technology - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Millimeter Wave Scanners
- 12.4.7.2 Backscatter X-Ray Scanners
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Operating Mode - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Manual
- 12.5.7.2 Automatic
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 By End User Industry - Market Size and Forecast, 2024-2032
- 12.6.1 Segment Definition and Scope
- 12.6.2 Historical Market Size
- 12.6.3 Revenue Forecast, 2024-2032
- 12.6.4 Volume Forecast, 2024-2032
- 12.6.5 Base-Year Market Share, 2024
- 12.6.6 Segment CAGR and Growth Drivers
- 12.6.7 Subsegment Market Size and Forecast
- 12.6.7.1 Airports
- 12.6.7.2 Seaports
- 12.6.7.3 Railway and Metro Stations
- 12.6.7.4 Prison
- 12.6.7.5 Government Facilities and Homeland Security
- 12.6.7.6 Others
- 12.6.8 Subsegment Pricing and Adoption Trends
- 12.6.9 Leading Suppliers and Competition
- 12.6.10 Regional Demand and Opportunities
- 12.7 Segment Growth Comparison
- 12.8 Segment Attractiveness and Priority Matrix
Chapter 13 Global Full Body Scanners End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Full Body Scanners Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Full Body Scanners Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Full Body Scanners Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Smiths Detection
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Leidos Security Detection & Automation
- 18.4 L3Harris Technologies
- 18.5 Rapiscan Systems
- 18.6 Rohde & Schwarz
- 18.7 Nuctech Company Limited
- 18.8 TEK 84 Inc.
- 18.9 Iscon Imaging
- 18.10 Millivision Technologies
- 18.11 OD Security
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

