
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
| Mobile Application Stores Market Size 2024 | USD 235,650.8 million |
| Mobile Application Stores Market, CAGR | 20.7% |
| Mobile Application Stores Market Size 2032 | USD 1,061,517.3 million |
Market Overview
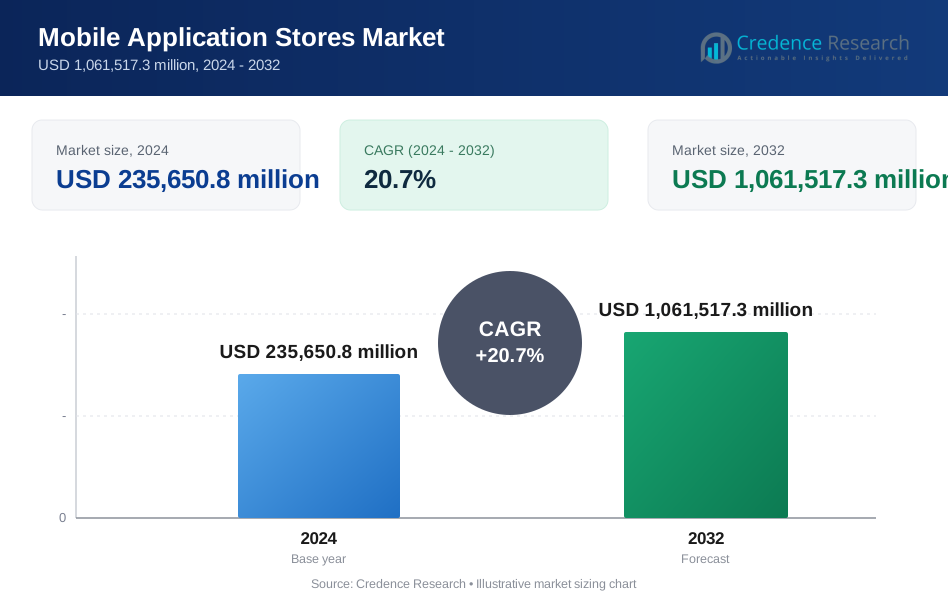
The Mobile Application Stores Market is projected to grow from USD 235,650.8 million in 2024 to USD 1,061,517.3 million by 2032, reflecting a compound annual growth rate (CAGR) of 20.7% during the forecast period, 2024-2032.
The Mobile Application Stores Market is driven by increasing smartphone penetration, the growing demand for mobile apps, and the shift towards digitalization in various industries. The rising use of mobile devices for both personal and business activities has led to an expansion of mobile application stores, providing a broad platform for developers and consumers. Additionally, the introduction of advanced technologies like 5G, AI, and machine learning enhances app functionality, further boosting market growth. Trends such as subscription-based models, in-app purchases, and freemium offerings are increasingly popular, offering developers steady revenue streams. Moreover, the growing popularity of gaming, entertainment, and e-commerce apps is contributing significantly to market expansion. App stores are also adapting to the demand for regionalized content and localized payment options to cater to diverse global markets. As app stores continue to evolve, the focus on improving user experience, personalized recommendations, and security will drive future growth in this competitive landscape.
The Mobile Application Stores Market exhibits significant growth across all regions, with North America holding the largest market share due to high smartphone penetration and strong demand for apps. Europe follows closely, driven by stringent data privacy regulations and a robust digital ecosystem. The Asia-Pacific region is experiencing the highest growth, fueled by rapid smartphone adoption, particularly in India, China, and Southeast Asia, and an increasing demand for mobile gaming and e-commerce apps. Latin America and the Middle East & Africa are also expanding, with rising smartphone use and mobile-first strategies. Key players in these regions include global giants like Apple, Google, Amazon, and Huawei, alongside regional players such as Samsung and Aptoide, each focusing on localized content and regional user preferences to capture market share.
Market Insights
- The Mobile Application Stores Market is projected to grow from USD 235,650.8 million in 2024 to USD 1,061,517.3 million by 2032, with a CAGR of 20.7%.
- Increasing smartphone penetration globally, especially in emerging markets, is driving the demand for mobile applications.
- Technological advancements like 5G, AI, and machine learning enhance app functionality, boosting market growth.
- Subscription-based models, in-app purchases, and freemium offerings are gaining popularity, providing steady revenue streams for developers.
- The growing demand for gaming, entertainment, and e-commerce apps is significantly contributing to market expansion.
- Regionalized content and localized payment options are becoming essential for app stores to cater to global markets.
- North America leads the market with a 30% share in 2024, followed by Europe at 25%, Asia-Pacific at 20%, Latin America at 12%, and the Middle East & Africa at 13%.
Market Drivers
Increasing Smartphone Penetration
One of the primary drivers of the Mobile Application Stores Market is the increasing penetration of smartphones globally. With smartphones becoming more affordable and accessible, the number of users has surged, particularly in emerging markets. This growth in smartphone adoption has led to a corresponding increase in demand for mobile applications, which are primarily accessed through app stores. For instance, Apple App Store and Google Play Store have seen significant growth in app downloads as smartphones become central to daily activities, including communication, entertainment, and e-commerce, fueling the expansion of app stores.
Technological Advancements and 5G Connectivity
Technological advancements, especially the rollout of 5G networks, are driving the growth of mobile application stores. With the enhanced speed and low latency of 5G, users can experience faster and more efficient app performance, which is critical for data-intensive applications such as gaming, augmented reality (AR), and virtual reality (VR). For instance, the Google Play Store offers a wide range of advanced and feature-rich apps that benefit from the capabilities of 5G, further fueling the app store ecosystem. Moreover, the integration of AI and machine learning in mobile apps offers personalized experiences, attracting more users to download and engage with apps, contributing to overall market growth.
Rising Demand for Mobile Gaming and Entertainment Apps
Mobile gaming and entertainment apps have become increasingly popular, significantly driving the Mobile Application Stores Market. The gaming sector, in particular, is one of the largest contributors, with millions of users worldwide downloading gaming apps. For instance, platforms like Apple Arcade and Google Play Games offer a wide variety of gaming apps, driving consumer interest and expanding the market. The availability of free-to-play games with in-app purchases and the rise of subscription-based models for entertainment services, such as music streaming and video on demand, have further fueled market growth. As consumer interest in mobile-based entertainment continues to rise, app stores become the key distribution platform for these apps.
Shift Towards Digitalization and E-Commerce
The ongoing digital transformation across industries has also contributed to the growth of the Mobile Application Stores Market. As businesses increasingly move to digital platforms, the demand for business and productivity apps has surged. For instance, e-commerce platforms like Amazon and mobile banking apps such as Paytm are experiencing significant growth, driven by the convenience they offer consumers. The expansion of these services through app stores, combined with the growing reliance on mobile devices for shopping, banking, and other services, is one of the key drivers propelling the market forward.
Market Trends
Subscription-Based Models and In-App Purchases
One of the key trends in the Mobile Application Stores Market is the growing adoption of subscription-based models and in-app purchases. Many app developers are shifting from one-time purchase models to recurring subscription services, offering users continuous access to content and services. This model is particularly prominent in areas such as gaming, streaming, and productivity apps, where users pay for ongoing features, updates, or exclusive content. For instance, Netflix uses a subscription-based model to offer continuous access to streaming content. In-app purchases also continue to dominate mobile gaming, providing a steady revenue stream for developers. These trends not only enhance app profitability but also contribute to increased consumer engagement and loyalty.
Freemium Offerings and Increased App Monetization
Freemium offerings, where apps are offered for free with the option to purchase premium features, are becoming increasingly popular in the mobile application store ecosystem. This model allows users to try apps before committing financially, reducing barriers to entry and increasing user acquisition. For instance, Spotify offers a freemium model where users can access the app for free and choose to pay for premium features. Once users are engaged, developers can convert them into paying customers through premium features, upgrades, or ad-free experiences. This approach has proven effective in mobile gaming, social media, and health apps, leading to higher revenue generation and better market penetration.
Regionalization and Localization of Apps
The trend of regionalization and localization of mobile apps is on the rise, driven by the need to cater to diverse global markets. App stores are focusing on offering region-specific content, languages, and payment methods to enhance the user experience. For instance, Alibaba localizes its app offerings to match cultural preferences and provide tailored solutions in different regions. By localizing apps to match cultural preferences and offering tailored solutions, developers are able to engage a broader audience. This trend is particularly important in emerging markets, where localized services can drive higher adoption rates and ensure the success of mobile applications.
Focus on Enhanced Security and Privacy
As mobile app usage grows, the demand for enhanced security and privacy features continues to rise. Users are becoming more aware of the risks associated with data privacy breaches, making it imperative for app developers and stores to prioritize secure transactions and data protection. For instance, WhatsApp has incorporated robust security measures such as two-factor authentication and end-to-end encryption to ensure user data is protected. This trend reflects the industry's commitment to maintaining trust while addressing regulatory challenges related to privacy laws and data protection.
Market Challenges Analysis
Intense Competition and Market Saturation
A major challenge in the Mobile Application Stores Market is the intense competition and market saturation. With millions of apps available on platforms like the Apple App Store and Google Play, developers face significant difficulty in distinguishing their products and attracting users. The sheer volume of apps, combined with limited visibility on app stores, makes it challenging for new entrants to achieve substantial market share. Moreover, app store algorithms often prioritize popular or heavily funded apps, leaving smaller developers with limited opportunities to gain exposure. This fierce competition leads to increased marketing expenses for developers and reduced profit margins, especially for those without the resources to drive user acquisition and retention. Additionally, the market’s saturation can lead to user fatigue, where consumers are overwhelmed by the number of available options and are less likely to download new apps. As a result, developers must innovate and continuously improve user experience to stand out, adding further pressure to succeed in a highly competitive environment.
Regulatory and Compliance Challenges
The regulatory environment surrounding mobile applications is another significant challenge that developers and app store operators must navigate. As governments worldwide increasingly focus on data privacy and security, app stores are under heightened scrutiny to ensure that applications comply with stringent privacy laws such as the GDPR in Europe or the CCPA in California. Developers must also adhere to various content moderation and intellectual property regulations, which can vary greatly across different regions. Failure to comply with these regulations can lead to fines, legal disputes, or even removal from app stores. Furthermore, as countries introduce new regulations regarding digital payments, in-app purchases, and user consent, developers face additional complexity in adapting their apps to meet these legal requirements. These challenges not only increase operational costs but also create uncertainty for developers who must continuously adjust their apps to stay compliant, making it harder for smaller businesses to compete against larger companies with dedicated legal and compliance teams. The evolving nature of these regulations requires constant vigilance and flexibility, further complicating the development and distribution processes.
Market Opportunities
One of the key opportunities in the Mobile Application Stores Market lies in the expansion of emerging markets. With rapid smartphone adoption and increased internet penetration in regions such as Asia-Pacific, Latin America, and Africa, mobile app usage is experiencing exponential growth. This trend provides app developers with the opportunity to target new audiences and tailor their offerings to meet the specific needs of these markets. By localizing apps for regional languages, preferences, and payment systems, developers can significantly increase their reach. Moreover, the growing middle class in these regions is driving demand for digital entertainment, e-commerce, and mobile banking apps, creating a fertile ground for app store growth. As emerging markets continue to mature, there will be a surge in mobile app demand, offering developers new revenue streams and opportunities for expansion.
Another opportunity in the Mobile Application Stores Market is the integration of new technologies and services into mobile apps. As technologies such as 5G, augmented reality (AR), virtual reality (VR), and artificial intelligence (AI) continue to evolve, they present significant opportunities for developers to create innovative, feature-rich applications. These advancements enable the development of immersive experiences, smarter app functionalities, and personalized user experiences, which can differentiate apps in the crowded marketplace. Additionally, the rise of subscription-based services, in-app purchases, and ad-supported models presents opportunities for app monetization, helping developers achieve higher revenue streams. As app stores adapt to these technological trends, they can offer developers and users an increasingly sophisticated platform, fostering continued market growth. By leveraging these technologies, developers can meet the evolving expectations of consumers, creating apps that are more engaging and capable of generating greater user retention.
Market Segmentation Analysis:
By Platform
The Mobile Application Stores Market is segmented by platform, primarily focusing on Android and iOS. Android dominates the market due to its wide adoption across a variety of devices and regions. iOS, with its premium user base and higher spending power, also holds a significant share. The competition between these platforms drives innovation in app development and distribution.
By App Category
The market is also segmented by app category, with key segments including gaming, social networking, entertainment, productivity, and e-commerce. Gaming apps continue to lead in revenue generation, driven by in-app purchases and subscriptions. Social networking and entertainment apps are also growing rapidly, offering platforms for streaming and interactive engagement, thereby diversifying app store offerings.
By End User
The Mobile Application Stores Market is segmented by end-user, which includes individual consumers, businesses, and government entities. Individual consumers remain the largest segment, utilizing mobile apps for entertainment, productivity, and communication. The growing adoption of mobile apps in businesses for e-commerce and enterprise solutions is driving demand in the commercial segment.
Segments:
Based on Platform
- iOS
- Android
- Windows
- Others
Based on App Category
- Gaming
- Entertainment
- Education
- Health & Fitness
- Travel
- Utilities
- Others
Revenue Model
- Paid Apps
- In-App Purchases
- Subscription
- Advertising
Based on End-User
- Individual
- Enterprise
Based on the Geography:
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis
North America
In 2024, North America is expected to hold the largest share of the Mobile Application Stores Market, accounting for 30% of the global market. This dominance is driven by the region’s high smartphone penetration, advanced technological infrastructure, and strong demand for mobile applications across various sectors such as entertainment, e-commerce, and productivity. The United States, in particular, is home to major app store platforms like Google Play and the Apple App Store, which significantly contribute to the region's market share. Additionally, the increasing adoption of digital payment systems and subscription-based models within mobile apps supports sustained growth.
Europe
Europe is projected to hold a market share of around 25% in 2024, driven by a robust smartphone market and the increasing popularity of mobile applications for services like gaming, mobile banking, and entertainment. With diverse regulations such as the GDPR influencing data privacy and security, the region is seeing a growing demand for secure and compliant app stores. The rise of e-commerce, along with the growing need for productivity and health-related apps, further supports the expansion of mobile app stores in Europe. Strong economic performance in regions like Western Europe, particularly the UK and Germany, continues to drive the market's growth in this region.
Asia-Pacific
The Asia-Pacific region is expected to experience the highest growth rate in the Mobile Application Stores Market, with a projected market share of 20% in 2024. This is primarily driven by the rapid increase in smartphone penetration, particularly in countries like India, China, and Southeast Asian nations. With a young, tech-savvy population and growing internet connectivity, Asia-Pacific presents significant opportunities for mobile app developers. Furthermore, the rising demand for mobile gaming, social networking, and e-commerce apps fuels the growth of app stores in this region. The increasing disposable income in countries like China and India also contributes to the accelerated adoption of paid apps and in-app purchases.
Latin America
In Latin America, the Mobile Application Stores Market is projected to hold a share of 12% in 2024. The region is experiencing rapid smartphone adoption, particularly in Brazil, Mexico, and Argentina, which is driving the demand for mobile applications. Although mobile app store revenue in Latin America is relatively lower compared to other regions, the increasing focus on e-commerce, online banking, and mobile gaming presents significant growth opportunities. The rise of mobile-first strategies in Latin American countries is anticipated to further propel the market in the coming years.
Middle East and Africa
The Middle East and Africa (MEA) region is expected to account for 13% of the global Mobile Application Stores Market share in 2024. Growth is largely attributed to increasing smartphone penetration and a young, digitally connected population. Countries like the UAE, Saudi Arabia, and South Africa are seeing higher mobile app engagement, particularly in sectors like e-commerce, mobile payments, and entertainment. The demand for mobile applications tailored to the unique needs of regional markets, including language localization and payment methods, offers substantial opportunities for app developers and stores in MEA.
Key Player Analysis
- SlideME
- Aptoide
- Microsoft Store
- Google Play Store
- Amazon Appstore
- Huawei AppGallery
- Samsung Galaxy Store
- GetJar
- Opera Mobile Store
- Apple App Store
Competitive Analysis
The Mobile Application Stores Market is highly competitive, with leading platforms such as Apple App Store, Google Play Store, Amazon Appstore, Samsung Galaxy Store, Huawei AppGallery, Microsoft Store, Aptoide, GetJar, Opera Mobile Store, and SlideME dominating the landscape. These platforms compete on multiple fronts, including user base size, app offerings, and geographic reach. Apple and Google dominate the market, with the largest share driven by their vast user bases and diverse app categories. However, regional players like Samsung Galaxy Store and Huawei AppGallery are gaining traction by focusing on localized content and exclusive app offerings. For instance, Amazon Appstore and Microsoft Store cater to specific niches, such as Kindle devices and Windows-based applications, respectively. Amazon Appstore and Microsoft Store cater to specific niches, such as Kindle devices and Windows-based applications, respectively. Smaller players like Aptoide, GetJar, and SlideME offer alternative distribution models, attracting developers seeking more flexible app store policies. The competition is intensifying as each platform strives to innovate and differentiate itself in a rapidly evolving market.
Recent Developments
- In December 2024, Epic Games partnered with Telefónica to preinstall the Epic Games Store on new Android phones, including Samsung devices, across the UK, Spain, Germany, and Latin America. This collaboration aimed to challenge Google's app store dominance by providing users with alternative app distribution channels.
- In February 2025, PhonePe officially launched its mobile app marketplace, Indus Appstore, aiming to compete with the Google Play Store and Apple's App Store. This initiative is part of a broader strategy to provide an alternative platform for app distribution in India, emphasizing local development and user preferences
- In January 2025, Epic Games announced plans to introduce 19 third-party games on its Android app globally and 16 games on its iOS app in the European Union. This initiative sought to bypass fees from Google Play and Apple's App Store, offering developers a more competitive platform.
- In January 2025, Digital Turbine's EVP of Global Partnerships, Matt Tubergen, highlighted the impending shift from an Apple and Google duopoly to a more open app store landscape. This change is expected to empower mobile carriers and alternative app stores, providing developers with better revenue opportunities and consumers with a broader selection of apps.
Market Concentration & Characteristics
The Mobile Application Stores Market is characterized by a moderately concentrated structure, with a few dominant players capturing the largest market share. Leading platforms such as the Apple App Store, Google Play Store, and Amazon Appstore account for the majority of global app distribution. These platforms maintain significant control over app availability, visibility, and monetization models, influencing the dynamics of the market. Despite the dominance of these major players, there is room for regional players like Samsung Galaxy Store and Huawei AppGallery, which are gaining traction by focusing on localized content and exclusive offerings. The market also features a growing number of smaller app stores, such as Aptoide and GetJar, offering alternative distribution methods and appealing to developers seeking more flexible policies. This diversity in market participants fosters competition and innovation, driving continuous improvements in user experience, app security, and platform functionality.
Report Coverage
The research report offers an in-depth analysis based on Platform, App Category, Model, End-User and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The mobile market demonstrates significant strength as we enter 2025, with the recovering mobile gaming market adding to the rapid growth seen in non-gaming.
- Increased smartphone penetration in emerging markets will drive demand for mobile apps, boosting app store growth.
- The introduction of 5G networks will enhance app performance, particularly for gaming, AR, and VR applications.
- Subscription-based models and in-app purchases will remain significant revenue drivers for app stores.
- Regional players will continue to capture market share by offering localized content and payment options.
- App stores will focus on improving user experience through personalized recommendations and seamless interfaces.
- Growing demand for gaming, entertainment, and e-commerce apps will further accelerate market growth.
- Competition among leading platforms will intensify, driving innovation and new features in app distribution.
- Increased regulatory scrutiny on data privacy and security will shape app store operations, ensuring compliance.
- The rise of cross-platform app development will enhance app accessibility, leading to more diverse app offerings.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Increasing Smartphone Penetration
The widespread adoption of smartphones, especially in emerging markets, is expanding the user base for mobile application stores, driving higher app downloads and revenue opportunities for developers and platforms.
Technological Advancements and 5G Connectivity
The rollout of 5G networks and integration of AI and machine learning are enabling more sophisticated, data-intensive apps, enhancing user experiences and encouraging greater app store engagement.
Growth in Mobile Gaming and Entertainment
Mobile gaming and entertainment apps are among the most downloaded and monetized categories, with in-app purchases and subscriptions fueling significant revenue growth for app stores.
Shift Toward Digitalization and E-Commerce
Businesses and consumers are increasingly relying on mobile apps for shopping, banking, and productivity, boosting demand for app stores as the primary distribution channel for these digital services.
Regionalization and Localization of Content
App stores are adapting to diverse global markets by offering localized content, languages, and payment options, which increases adoption rates and expands their reach in regions with unique cultural and regulatory requirements.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Mobile Application Stores Market?
What factors are driving the growth of the Mobile Application Stores Market?
What are the key segments within the Mobile Application Stores Market?
What are some challenges faced by the Mobile Application Stores Market?
Who are the major players in the Mobile Application Stores Market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By End-User
- 1.2.1 Individual
- 1.2.2 Enterprise
- 1.3 By Platform
- 1.3.1 iOS
- 1.3.2 Android
- 1.3.3 Windows
- 1.3.4 Others
- 1.4 By App Category
- 1.4.1 Gaming
- 1.4.2 Entertainment
- 1.4.3 Education
- 1.4.4 Health & Fitness
- 1.4.5 Travel
- 1.4.6 Utilities
- 1.4.7 Others
- 1.5 By Revenue Model
- 1.5.1 Paid Apps
- 1.5.2 In-App Purchases
- 1.5.3 Subscription
- 1.5.4 Advertising
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 235,650.8 million → 2032: USD 1,061,517.3 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Mobile Application Stores Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Mobile Application Stores Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Mobile Application Stores Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Mobile Application Stores Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Mobile Application Stores Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Mobile Application Stores Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Data Protection, AI and Cybersecurity Compliance
- 9.8 Upcoming Policy Changes and Market Implications
Chapter 10 Global Mobile Application Stores Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Mobile Application Stores Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 235,650.8 million → 2032: USD 1,061,517.3 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Mobile Application Stores Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By End-User - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Individual
- 12.3.7.2 Enterprise
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Platform - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 iOS
- 12.4.7.2 Android
- 12.4.7.3 Windows
- 12.4.7.4 Others
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By App Category - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Gaming
- 12.5.7.2 Entertainment
- 12.5.7.3 Education
- 12.5.7.4 Health & Fitness
- 12.5.7.5 Travel
- 12.5.7.6 Utilities
- 12.5.7.7 Others
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 By Revenue Model - Market Size and Forecast, 2024-2032
- 12.6.1 Segment Definition and Scope
- 12.6.2 Historical Market Size
- 12.6.3 Revenue Forecast, 2024-2032
- 12.6.4 Volume Forecast, 2024-2032
- 12.6.5 Base-Year Market Share, 2024
- 12.6.6 Segment CAGR and Growth Drivers
- 12.6.7 Subsegment Market Size and Forecast
- 12.6.7.1 Paid Apps
- 12.6.7.2 In-App Purchases
- 12.6.7.3 Subscription
- 12.6.7.4 Advertising
- 12.6.8 Subsegment Pricing and Adoption Trends
- 12.6.9 Leading Suppliers and Competition
- 12.6.10 Regional Demand and Opportunities
- 12.7 Segment Growth Comparison
- 12.8 Segment Attractiveness and Priority Matrix
Chapter 13 Global Mobile Application Stores End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Mobile Application Stores Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Mobile Application Stores Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Mobile Application Stores Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Apple
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Google
- 18.4 Amazon
- 18.5 Huawei
- 18.6 Samsung
- 18.7 Microsoft
- 18.8 Aptoide
- 18.9 GetJar
- 18.10 Opera
- 18.11 SlideME
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

