
Market Overview:
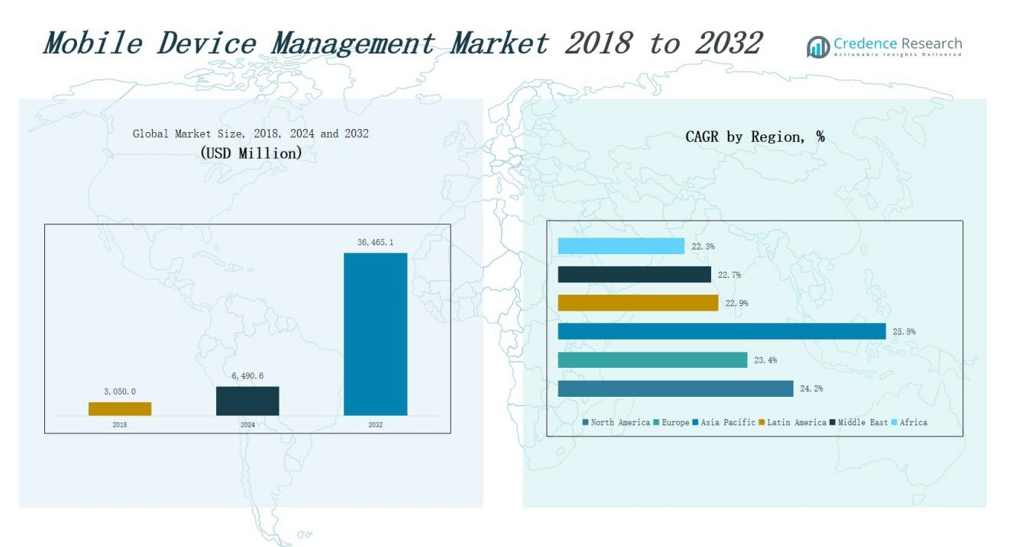
Mobile Device Management Market size was valued at USD 3,050.0 million in 2018 to USD 6,490.6 million in 2024 and is anticipated to reach USD 36,465.1 million by 2032, at a CAGR of 24.2% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Mobile Device Management Market Size 2024 | USD 6,490.6 million |
| Mobile Device Management Market, CAGR | 24.2% |
| Mobile Device Management Market Size 2032 | USD 36,465.1 million |
The Mobile Device Management Market is shaped by leading players such as Microsoft Corporation, IBM Corporation, VMware, Cisco Systems, SAP SE, Citrix Systems, Broadcom, Zoho Corp., Ivanti, SOTI Inc., Kaspersky Labs, Micro Focus, and SolarWinds Worldwide, LLC. These companies compete through cloud-based platforms, advanced security features, and unified endpoint management capabilities, while also expanding managed services and leveraging AI-driven analytics to strengthen offerings. Strategic partnerships, acquisitions, and regional expansions remain central to sustaining market presence. Geographically, North America dominates with 34% market share in 2024, driven by robust IT infrastructure, rapid BYOD adoption, and stringent compliance regulations.
Market Insights
- The Mobile Device Management Market grew from USD 3,050.0 million in 2018 to USD 6,490.6 million in 2024 and is projected to reach USD 36,465.1 million by 2032.
- The software segment dominates with 61% share, led by security management at 24%, while managed services hold the largest portion of the services segment at 15%.
- By device type, smartphones lead with 52% share, followed by laptops at 27%, tablets at 14%, and other devices such as rugged handhelds and wearables at 7%.
- Deployment is led by cloud solutions with 68% share, driven by scalability and cost-efficiency, while on-premise models retain 32% share, favored by highly regulated industries.
- Regionally, North America leads with 34% share in 2024, followed by Europe at 27% and Asia Pacific at 28%, making Asia Pacific the fastest-growing market.
Market Segment Insights
By Solution
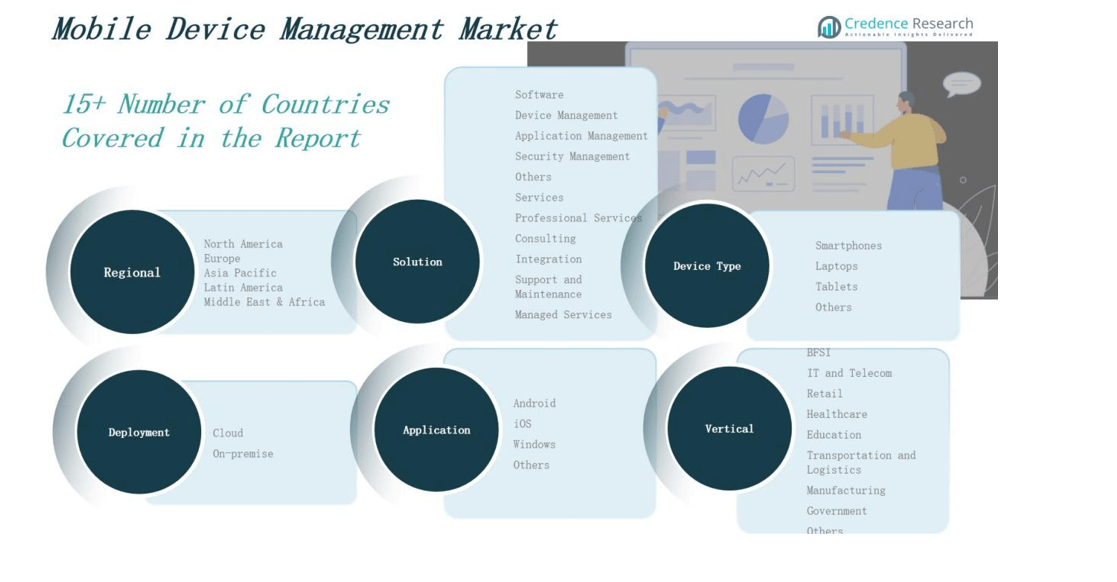
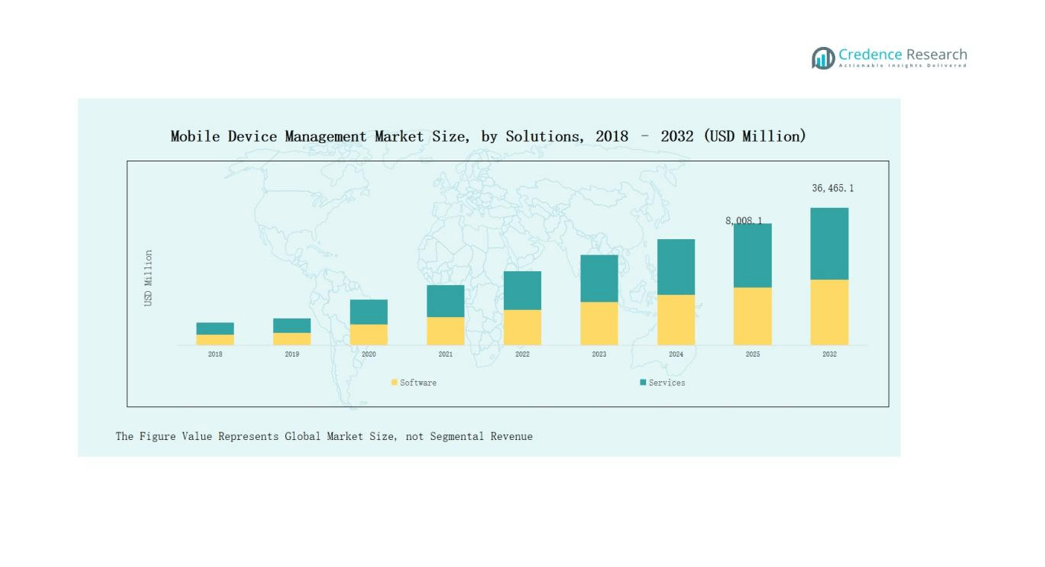
The software segment dominates the mobile device management market with a 61% share, driven by rising adoption of advanced device, OS, and security management solutions. Within this category, security management leads with 24% share, supported by growing concerns around data breaches, compliance needs, and endpoint protection. The services segment accounts for 39%, with managed services holding the largest share at 15%, as enterprises prefer outsourcing MDM operations to reduce costs and enhance scalability.
- For instance, VMware Workspace ONE has been adopted by Delta Air Lines to manage 80,000 mobile devices used across flight operations and ground staff, ensuring strict compliance and data security.
By Device Type
The smartphones segment leads the market with a 52% share, fueled by their widespread use across industries, rising BYOD adoption, and enterprise mobility initiatives. Laptops hold 27% share, supported by the increasing remote workforce and reliance on hybrid work models that require secure access to corporate systems. Tablets capture 14% share, driven by usage in retail, education, and healthcare for mobility-focused operations. Other devices, including rugged handhelds and wearables, represent 7% but show growth potential with expanding use in logistics and industrial applications.
- For example, DHL uses Zebra Technologies’ rugged handhelds across warehouses to improve real-time inventory tracking and last-mile visibility.
By Deployment
The cloud-based deployment segment dominates with 68% share, propelled by its scalability, cost efficiency, and ability to support remote device management for distributed workforces. Enterprises adopt cloud solutions to simplify upgrades, improve compliance management, and integrate with other SaaS platforms. The on-premise segment holds 32% share, largely preferred by organizations in regulated industries such as BFSI and government where data security, control, and compliance requirements remain critical. While cloud continues to expand, hybrid models are gaining traction as firms balance flexibility and regulatory obligations.
Market Overview
Rising Adoption of BYOD Policies
The growing adoption of Bring Your Own Device (BYOD) policies across enterprises is a major driver for the mobile device management market. Companies enable employees to use personal devices for work, which improves flexibility but increases data security risks. MDM solutions address these concerns by offering centralized control, secure access, and compliance management. Organizations invest in robust device and application security frameworks to mitigate data loss and cyber threats. This trend ensures steady demand for scalable, cloud-based MDM platforms across industries.
Increasing Cybersecurity Threats and Compliance Needs
Rising cyberattacks and stringent regulatory frameworks are fueling demand for advanced MDM solutions. Enterprises face mounting risks from data breaches, phishing, and malware targeting mobile endpoints. Compliance requirements such as GDPR, HIPAA, and PCI-DSS further push organizations to adopt MDM tools for data encryption, access control, and monitoring. MDM systems enable real-time detection of suspicious activity, ensuring both operational continuity and regulatory adherence. The rising cost of breaches makes proactive device and application security a top priority for IT leaders worldwide.
- For instance, ManageEngine’s Mobile Device Manager Plus enables Vodafone Qatar to securely manage over 2,500 POS devices across retail stores, helping maintain robust endpoint security and compliance with organizational policies.
Growing Remote and Hybrid Workforces
The global shift toward remote and hybrid work models has significantly increased the need for mobile device management solutions. Employees rely on smartphones, laptops, and tablets to access corporate systems from dispersed locations. MDM platforms enable secure connectivity, device monitoring, and application management across networks, ensuring productivity without compromising data security. Enterprises are prioritizing cloud-based deployments to achieve scalability, seamless integration, and support for remote IT operations. This workforce transformation ensures continuous market expansion, particularly in highly digitized sectors like IT, BFSI, and healthcare.
- For instance, Microsoft Intune, used by companies like United Airlines, allows centralized management of employee devices, enabling secure access to Office 365 applications from personal smartphones and laptops.
Key Trends & Opportunities
Integration with Unified Endpoint Management (UEM)
A key trend shaping the market is the convergence of MDM with Unified Endpoint Management platforms. Enterprises prefer single frameworks that manage smartphones, laptops, desktops, and IoT devices through centralized policies. Vendors are enhancing solutions with AI-driven analytics, automation, and zero-trust security features. This integration improves efficiency, reduces IT overheads, and enhances user experiences. The growing demand for unified solutions presents significant opportunities for vendors offering scalable, cross-platform endpoint management with advanced security and compliance capabilities.
- For instance, VMware Workspace ONE applies AI-based risk analytics for continuous authentication, reducing the likelihood of credential misuse in hybrid work environments.
Expansion of Cloud-Based Solutions in SMEs
The rising adoption of cloud-based MDM solutions by small and medium-sized enterprises represents a major opportunity. SMEs seek cost-efficient, scalable solutions to manage employee devices without heavy infrastructure investments. Cloud models provide remote accessibility, simplified deployment, and automatic updates, making them ideal for resource-constrained organizations. Vendors focusing on flexible pricing models, SaaS offerings, and integration with productivity tools are well-positioned to capture this segment. The SME-driven demand ensures continuous growth, particularly in emerging markets with rapid digital transformation.
- For instance, ManageEngine Mobile Device Manager Plus offers affordable cloud-based device tracking and remote troubleshooting, making it a popular choice for small businesses.
Key Challenges
High Implementation and Operational Costs
One of the biggest challenges for MDM adoption is the high cost of deployment and management. Comprehensive MDM solutions require investments in licensing, integration, training, and ongoing maintenance. For SMEs and cost-sensitive organizations, these expenses often act as barriers. The need for specialized IT expertise further increases operational costs. While cloud-based models reduce upfront investment, large-scale rollouts still demand significant capital. Vendors must offer flexible pricing structures and modular solutions to overcome this constraint and broaden adoption.
Complexity of Multi-Device and Multi-OS Environments
The growing diversity of devices and operating systems in enterprises makes MDM implementation complex. Companies must manage smartphones, tablets, laptops, and IoT devices running on different OS platforms such as Android, iOS, and Windows. Ensuring compatibility, consistent policy enforcement, and seamless integration across this ecosystem is challenging. Frequent OS updates and fragmented device models further complicate management. Enterprises require adaptive and scalable MDM solutions, but achieving uniform security and performance across heterogeneous environments remains a persistent barrier.
Employee Privacy and User Resistance
Concerns around employee privacy and user resistance continue to hinder MDM adoption. Employees often view MDM tools as intrusive since they involve monitoring personal devices used in BYOD setups. Organizations must balance security needs with user autonomy, ensuring policies do not compromise personal data. Overly restrictive controls can reduce employee satisfaction and productivity, leading to reluctance in adopting MDM programs. Addressing these concerns through transparent policies, containerization, and user education is critical to overcoming resistance and ensuring acceptance.
Regional Analysis
North America
North America holds the largest share of the mobile device management market with 34% in 2024, supported by strong enterprise mobility adoption and advanced IT infrastructure. The region’s market expanded from USD 1,180.4 million in 2018 to USD 2,483.3 million in 2024, and it is projected to reach USD 13,930.7 million by 2032 at a CAGR of 24.2%. The U.S. drives this growth with high investments in cloud platforms, stringent compliance regulations, and rapid BYOD adoption. Demand from healthcare, BFSI, and IT services accelerates adoption of scalable cloud-based MDM platforms.
Europe
Europe represents 27% of the global market in 2024, with growth driven by strict data protection laws, digital transformation initiatives, and enterprise security priorities. The market grew from USD 850.0 million in 2018 to USD 1,742.6 million in 2024 and is expected to reach USD 9,278.6 million by 2032, registering a CAGR of 23.4%. Countries such as Germany, the UK, and France lead adoption due to GDPR compliance requirements and growing IT modernization programs. Increased reliance on remote work and secure collaboration tools continues to support market expansion across the region.
Asia Pacific
Asia Pacific is the fastest-growing region with a 28% share in 2024, reflecting strong enterprise mobility adoption, rapid digitization, and cloud transformation. The regional market expanded from USD 655.1 million in 2018 to USD 1,464.6 million in 2024 and is projected to hit USD 9,161.2 million by 2032, recording a CAGR of 25.8%. China, India, Japan, and South Korea drive demand with large mobile user bases, government digital initiatives, and increasing SME adoption of cloud-based solutions. Expanding IT outsourcing and the growth of e-commerce also fuel MDM investments in the region.
Latin America
Latin America accounts for 6% of the global market in 2024, with adoption supported by the modernization of IT systems and rising mobile penetration. The market grew from USD 165.6 million in 2018 to USD 348.5 million in 2024 and is forecasted to reach USD 1,793.4 million by 2032, registering a CAGR of 22.9%. Brazil and Mexico lead adoption due to increased demand for cloud-based platforms and enterprise mobility management in banking, retail, and telecom. Rising data security concerns and growing digital ecosystems further stimulate market expansion in the region.
Middle East
The Middle East represents 3% of the global market in 2024, with growth driven by smart city projects, enterprise digitalization, and strong demand for secure mobile solutions in BFSI and government sectors. The market expanded from USD 123.5 million in 2018 to USD 247.3 million in 2024 and is projected to reach USD 1,261.9 million by 2032, achieving a CAGR of 22.7%. GCC countries lead adoption with strong investments in IT security and cloud infrastructure, while Israel and Turkey show rising demand for advanced endpoint management solutions across enterprises.
Africa
Africa accounts for 2% of the global market in 2024, with increasing adoption supported by expanding telecom networks and enterprise digital initiatives. The market rose from USD 75.3 million in 2018 to USD 204.5 million in 2024 and is expected to reach USD 1,039.4 million by 2032, at a CAGR of 22.3%. South Africa drives regional demand due to its growing corporate sector and investments in IT security. Broader adoption in Nigeria, Egypt, and other markets is driven by rising mobile workforce expansion and cloud adoption, though infrastructural gaps remain a challenge.
Market Segmentations:
Software
- Device Management
- Operating System Management
- Security Management
- Others
Services
- Professional Services
- Consulting
- Integration
- Support and Maintenance
- Managed Services
By Device Type
- Smartphones
- Laptops
- Tablets
- Others
By Deployment
- Cloud
- On-Premise
By Operating System
- Android
- iOS
- Windows
- Others
By Vertical
- BFSI
- IT and Telecom
- Retail
- Healthcare
- Transportation and Logistics
- Manufacturing
- Government
- Others
By Region
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
The competitive landscape of the mobile device management market is characterized by strong rivalry among global technology providers offering software and services for secure mobility. Leading companies such as Microsoft Corporation, IBM Corporation, VMware, Cisco Systems, and SAP SE dominate with extensive product portfolios, cloud expertise, and integrated endpoint management solutions. These firms focus on expanding managed services, enhancing security features, and integrating artificial intelligence for predictive threat management. Emerging players including SOTI Inc., Zoho Corp., and Ivanti strengthen market competition by targeting small and medium enterprises with flexible, cost-effective platforms. Strategic partnerships, acquisitions, and product innovations remain core growth strategies to expand customer bases and improve service delivery. Vendors increasingly emphasize compliance readiness and cross-platform management to address enterprise mobility challenges. The market reflects moderate-to-high concentration, with established leaders capturing significant revenue share, while niche providers leverage agility and specialization to secure opportunities in growing regional and vertical markets.
Key Players
- Broadcom, Inc.
- Cisco Systems
- Citrix Systems
- IBM Corporation
- Ivanti
- Kaspersky Labs
- Micro Focus
- Microsoft Corporation
- SAP SE
- SolarWinds Worldwide, LLC.
- SOTI Inc.
- VMware, Inc.
- Zoho Corp. Pvt. Ltd.
Recent Developments
- In March 2025, Jamf acquired Identity Automation to strengthen its endpoint management portfolio and add role-based access control features. This move enhanced Jamf’s position in delivering advanced Apple-focused mobile device management solutions.
- In September 2023, TeamViewer partnered with Ivanti to integrate Ivanti Neurons for MDM into TeamViewer’s Remote Monitoring and Management platform. This collaboration provides businesses with a combined view and management of both desktop and mobile IT assets with enhanced security and compliance.
- In 2025, JumpCloud acquired VaultOne, a privileged access management provider, to expand its MDM and IAM capabilities. The deal supported JumpCloud’s strategy to integrate device management with identity and access solutions.
- In August 2025, Moki announced a strategic collaboration with Kyocera. This partnership helps organizations manage rugged Kyocera mobile devices more efficiently by integrating cloud‑based Moki MDM solutions.
Market Concentration & Characteristics
The Mobile Device Management Market demonstrates moderate-to-high concentration, with a few global technology leaders holding significant market share. It is defined by intense competition, rapid technological evolution, and a strong emphasis on security-driven innovation. Established vendors such as Microsoft, IBM, VMware, Cisco, and SAP lead with comprehensive portfolios and global reach, while mid-sized firms and niche players focus on agility, customization, and cost-efficient solutions to address specific enterprise needs. The market is characterized by rising demand for cloud-based platforms, unified endpoint management, and compliance-ready solutions tailored to hybrid workforces. It reflects a balance between large enterprises adopting integrated systems and small to medium-sized businesses seeking scalable and affordable models. It continues to evolve through partnerships, mergers, and strategic expansions aimed at enhancing service capabilities and extending regional presence. Growing cybersecurity threats, data privacy regulations, and mobile workforce expansion sustain the competitive dynamics and drive innovation across the industry.
Report Coverage
The research report offers an in-depth analysis based on Solution, Device Type, Deployment, Operating System, Vertical and Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Demand for cloud-based MDM platforms will increase with expanding remote and hybrid workforces.
- Integration of artificial intelligence will strengthen predictive security and device analytics.
- Unified endpoint management adoption will accelerate to simplify multi-device and multi-OS environments.
- SMEs will drive growth by adopting cost-efficient SaaS-based mobile device management solutions.
- Data privacy regulations will continue to shape MDM features and compliance-driven investments.
- Healthcare, BFSI, and government sectors will remain key adopters due to security priorities.
- Managed services will expand as enterprises outsource device management to reduce complexity.
- Growing adoption of IoT devices will create new opportunities for advanced MDM solutions.
- Vendors will focus on partnerships and acquisitions to expand global reach and portfolios.
- User-friendly policies and transparent frameworks will improve employee acceptance of MDM programs.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Rising Adoption of BYOD Policies
The increasing implementation of Bring Your Own Device (BYOD) policies in enterprises is driving demand for mobile device management solutions, as organizations seek to secure and manage employee-owned devices accessing corporate data and applications.
Increasing Cybersecurity Threats and Compliance Needs
Escalating cyberattacks and stringent regulatory requirements such as GDPR and HIPAA are pushing organizations to adopt advanced MDM solutions for data encryption, access control, and compliance management, ensuring both security and regulatory adherence.
Growth of Remote and Hybrid Workforces
The shift towards remote and hybrid work models has heightened the need for scalable, cloud-based MDM platforms that enable secure device management and connectivity for distributed employees, supporting productivity without compromising security.
Expansion of Cloud-Based Solutions in SMEs
Small and medium-sized enterprises are increasingly adopting cloud-based MDM solutions due to their cost efficiency, scalability, and ease of deployment, enabling resource-constrained organizations to manage devices without heavy infrastructure investments.
Integration with Unified Endpoint Management (UEM)
The convergence of MDM with Unified Endpoint Management platforms is creating opportunities for vendors, as enterprises seek centralized frameworks to manage diverse device types and operating systems, improving efficiency and reducing IT complexity.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the projected market size of the Global Mobile Device Management (MDM) Market in 2023 and 2032?
What factors are driving the growth of the MDM market?
How does MDM enhance data security for enterprises?
Which regions are expected to lead the MDM market growth?
Who are the major players in the MDM market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Solution
- 1.2.1 Device Management
- 1.2.2 Operating System Management
- 1.2.3 Security Management
- 1.2.4 Others
- 1.3 By Vertical
- 1.3.1 BFSI
- 1.3.2 IT and Telecom
- 1.3.3 Retail
- 1.3.4 Healthcare
- 1.3.5 Transportation and Logistics
- 1.3.6 Manufacturing
- 1.3.7 Government
- 1.3.8 Others
- 1.4 By Deployment
- 1.4.1 Cloud
- 1.4.2 On-Premise
- 1.5 By Device Type
- 1.5.1 Smartphones
- 1.5.2 Laptops
- 1.5.3 Tablets
- 1.5.4 Others
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 6,490.6 million → 2032: USD 36,465.1 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Mobile Device Management Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Mobile Device Management Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Mobile Device Management Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Mobile Device Management Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Mobile Device Management Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Mobile Device Management Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Data Protection, AI and Cybersecurity Compliance
- 9.8 Upcoming Policy Changes and Market Implications
Chapter 10 Global Mobile Device Management Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Mobile Device Management Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 6,490.6 million → 2032: USD 36,465.1 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Mobile Device Management Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Solution - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Device Management
- 12.3.7.2 Operating System Management
- 12.3.7.3 Security Management
- 12.3.7.4 Others
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Vertical - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 BFSI
- 12.4.7.2 IT and Telecom
- 12.4.7.3 Retail
- 12.4.7.4 Healthcare
- 12.4.7.5 Transportation and Logistics
- 12.4.7.6 Manufacturing
- 12.4.7.7 Government
- 12.4.7.8 Others
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Deployment - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Cloud
- 12.5.7.2 On-Premise
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 By Device Type - Market Size and Forecast, 2024-2032
- 12.6.1 Segment Definition and Scope
- 12.6.2 Historical Market Size
- 12.6.3 Revenue Forecast, 2024-2032
- 12.6.4 Volume Forecast, 2024-2032
- 12.6.5 Base-Year Market Share, 2024
- 12.6.6 Segment CAGR and Growth Drivers
- 12.6.7 Subsegment Market Size and Forecast
- 12.6.7.1 Smartphones
- 12.6.7.2 Laptops
- 12.6.7.3 Tablets
- 12.6.7.4 Others
- 12.6.8 Subsegment Pricing and Adoption Trends
- 12.6.9 Leading Suppliers and Competition
- 12.6.10 Regional Demand and Opportunities
- 12.7 Segment Growth Comparison
- 12.8 Segment Attractiveness and Priority Matrix
Chapter 13 Global Mobile Device Management End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Mobile Device Management Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Mobile Device Management Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Mobile Device Management Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Microsoft Corporation
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 IBM Corporation
- 18.4 VMware, Inc.
- 18.5 Cisco Systems
- 18.6 SAP SE
- 18.7 Citrix Systems
- 18.8 Broadcom, Inc.
- 18.9 Zoho Corp. Pvt. Ltd.
- 18.10 Ivanti
- 18.11 SOTI Inc.
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

