
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Mobile Payment Technologies Market Size 2024 | USD 1668.7 Million |
| Mobile Payment Technologies Market, CAGR | 4.7% |
| Mobile Payment Technologies Market Size 2032 | USD 2409.63 Million |
Market Overview:
The Mobile Payment Technologies Market is projected to grow from USD 1668.7 million in 2024 to an estimated USD 2409.63 million by 2032, with a compound annual growth rate (CAGR) of 4.7% from 2024 to 2032.
The growth of the mobile payment technologies market is fueled by several key factors. First, the increasing penetration of smartphones and the widespread availability of high-speed internet have made mobile payment solutions more accessible to a broader consumer base. This has enabled individuals to make transactions easily from their devices, contributing to the rise of mobile payments globally. In addition, the ongoing shift towards cashless economies plays a significant role in market expansion, with governments and financial institutions actively promoting digital payment methods to enhance transaction efficiency and reduce dependence on physical currency. Technological innovations, such as Near Field Communication (NFC), biometric authentication, and blockchain technology, have also bolstered the security and efficiency of mobile payments, further driving consumer confidence and adoption. Lastly, the integration of mobile payment options with e-commerce platforms, ride-sharing services, and food delivery apps has improved consumer convenience, making mobile payments an attractive choice for users across various industries.
The mobile payment technologies market demonstrates significant regional differences in adoption and growth. North America holds a substantial market share, largely due to high smartphone penetration, advanced digital infrastructure, and the widespread acceptance of contactless payment methods. In the Asia-Pacific region, countries like China and India are experiencing rapid growth in mobile payment adoption. In India, for example, the introduction of the Unified Payments Interface (UPI) has revolutionized digital transactions, making mobile payments more accessible and user-friendly. The region has seen millions of transactions processed daily, indicating a strong consumer preference for mobile payment solutions. Europe, particularly in countries like the UK, Germany, and France, is witnessing steady growth in the adoption of mobile payments, driven by supportive government initiatives and established financial institutions offering digital payment solutions. Meanwhile, in the rest of the world, regions such as Latin America, the Middle East, and Africa are experiencing increasing mobile payment adoption, fueled by rising smartphone usage and efforts to improve financial inclusion through digital platforms.
Market Insights:
- The mobile payment technologies market is projected to grow steadily from USD 1,668.7 million in 2024 to USD 2,409.63 million by 2032, with a CAGR of 4.7%.
- Increased smartphone penetration and improved internet accessibility are major factors driving the growth of mobile payment solutions globally.
- The shift towards cashless societies, supported by governments and financial institutions, is accelerating the adoption of mobile payments.
- Innovations like NFC, biometric authentication, and blockchain technology are enhancing security and user experience, boosting consumer confidence.
- The integration of mobile payments with e-commerce platforms, ride-sharing services, and food delivery apps is significantly increasing market demand.
- Security concerns and the risk of cyberattacks remain key challenges, requiring continuous advancements in encryption and fraud detection.
- Developing regions still face infrastructure challenges, limiting mobile payment adoption due to poor internet connectivity and limited digital infrastructure.
Market Drivers:
Technological Advancements and Innovation
The mobile payment technologies market is significantly driven by continuous technological innovations and advancements. For instance, Near Field Communication (NFC) has become a cornerstone of contactless payments, enabling quick and secure transactions with just a tap. This technology has been widely adopted by platforms like Apple Pay and Google Pay, which use tokenization to replace sensitive card details with encrypted tokens, reducing fraud risks. Biometric authentication, including fingerprint scanning and facial recognition, enhances transaction security and helps mitigate fraud, further boosting consumer confidence in mobile payment platforms. Additionally, blockchain technology is being increasingly adopted to ensure transparency and security in financial transactions, thereby fueling the adoption of mobile payment systems across various industries.
Widespread Smartphone Penetration and Internet Accessibility
The global increase in smartphone usage and the expansion of internet infrastructure have significantly contributed to the growth of mobile payment technologies. With billions of people around the world owning smartphones and gaining access to high-speed internet, mobile payments have become a convenient and accessible solution for everyday transactions. Consumers can now make secure payments directly from their smartphones, removing the need to carry physical currency or credit cards. This widespread smartphone penetration, coupled with the growing availability of 4G and 5G networks, has made mobile payments a preferred choice for individuals seeking seamless and efficient financial transactions. For example, platforms like WeChat Pay and Alipay dominate markets in Asia due to their seamless integration with everyday services such as e-commerce and transportation.
Shift Towards Cashless Societies
A significant driver of the mobile payment technologies market is the global shift toward cashless economies. Governments and financial institutions across the world are actively encouraging digital payment methods to reduce cash usage, improve financial tracking, and curb the risks associated with handling physical currency. The convenience, security, and efficiency offered by mobile payments are central to this transition, as they allow for instantaneous and secure transactions without the need for physical cash. In many countries, initiatives such as digital currencies, cashless payment systems, and mobile wallet solutions are being integrated into the broader financial ecosystem, further promoting the adoption of mobile payment technologies.
Technological Innovations
Advancements in technology continue to drive the sophistication of mobile payment platforms. The integration of artificial intelligence (AI) and machine learning is enhancing fraud detection and personalized user experiences. AI-powered algorithms analyze transaction patterns to identify anomalies, bolstering security measures. Additionally, the development of virtual point-of-sale (vPOS) systems is transforming retail transactions by enabling businesses to process payments through cloud-based platforms, reducing the need for traditional hardware and offering greater flexibility. These innovations contribute to more secure, efficient, and user-friendly mobile payment experiences.
Market Trends:
Emerging Payment Solutions
The mobile payment landscape is evolving with the integration of diverse payment methods, enhancing user convenience and accessibility. In regions like Latin America, alternative payment solutions such as boleto bancário in Brazil and OXXO in Mexico enable consumers to complete online purchases without traditional bank accounts or credit cards. These methods provide unique barcodes or payment slips that can be paid at various locations, broadening the inclusivity of mobile payment systems. Similarly, direct carrier billing allows users to charge purchases directly to their mobile phone bills, simplifying transactions for those without access to conventional banking services. This approach is particularly effective in areas with significant unbanked populations, offering a bridge to digital commerce.
Regulatory Developments
Regulatory initiatives are playing a pivotal role in shaping the mobile payments ecosystem. For instance, India is actively pushing for the Financial Action Task Force (FATF) to ease compliance requirements for cross-border payments made via its Unified Payments Interface (UPI). The government is advocating for relaxed compliance requirements to encourage broader adoption of UPI among Indians traveling abroad, positioning it as a competitive alternative to established networks like Visa and Mastercard. Such regulatory efforts are instrumental in promoting interoperability and expanding the global reach of mobile payment systems.
Integration with E-commerce and Service Platforms
The seamless integration of mobile payment technologies with e-commerce platforms and service-based applications has also played a crucial role in driving market growth. With the rise of online shopping, food delivery apps, and ride-sharing platforms, consumers now expect a smooth, secure, and quick payment experience. For instance, platforms like Starbucks have successfully merged mobile payments with loyalty programs through their app, enabling users to pay conveniently while earning rewards. Mobile payment solutions have been seamlessly embedded into these digital services, enabling users to make purchases, pay for services, and transfer money with just a few taps on their smartphones. This convenience, along with the growth of the digital economy, has made mobile payment technologies a necessary component of everyday life, contributing to their widespread adoption across various sectors.
Consumer Behavior Shifts
Consumer preferences are increasingly favoring mobile payment solutions due to their convenience and efficiency. This trend is fueled by the widespread adoption of smartphones, enhanced security features such as encryption and biometric authentication, and changing consumer behaviors, especially those accelerated by the COVID-19 pandemic. As consumers become more comfortable with mobile transactions, businesses are adapting by integrating mobile payment options to meet evolving customer expectations.
Market Challenges Analysis:
Security and Fraud Concerns
One of the key challenges faced by the mobile payment technologies market is the risk of security breaches and fraud. As mobile payments increase, so does the potential for cyberattacks and fraudulent activities. For instance, in February 2025, a hacker exploited vulnerabilities in Bybit's Ethereum cold wallet, stealing a record $1.4 billion, highlighting the risks associated with insufficient security measures. Hackers target vulnerable payment systems and consumer data, compromising the integrity of mobile payment platforms. While encryption and biometric authentication methods have improved security, the constant evolution of cyber threats means that mobile payment providers must continuously enhance their security measures to protect user data and maintain consumer trust. Any breach in security can have significant financial and reputational consequences for businesses in the market.
Lack of Infrastructure in Developing Regions
In many developing regions, limited access to reliable internet and mobile network infrastructure presents a significant barrier to the widespread adoption of mobile payment technologies. While smartphone penetration is on the rise globally, areas with underdeveloped telecommunications networks face challenges in supporting secure and fast mobile payment systems. This digital divide hampers the ability of consumers in these regions to fully participate in the mobile payment ecosystem, slowing down market growth. Without strong internet connectivity, users cannot make seamless and efficient transactions, limiting the potential for mobile payments in these areas.
Regulatory and Compliance Challenges
The complex regulatory landscape around mobile payments presents another hurdle. Governments worldwide have different rules and regulations governing digital payments, including issues related to data privacy, cross-border payments, and consumer protection. This lack of standardization can complicate the expansion of mobile payment systems, especially for companies aiming to operate in multiple countries. Navigating these regulations can be time-consuming and costly, creating compliance challenges that hinder the growth of mobile payment technologies. Additionally, regulatory uncertainty can deter new entrants from investing in the market, further slowing down innovation.
Consumer Reluctance and Adoption Rates
Despite the convenience and efficiency offered by mobile payments, some consumers remain hesitant to adopt these technologies due to concerns over privacy, security, and the unfamiliarity of digital wallets. Older demographics, in particular, may find it challenging to trust or navigate mobile payment platforms. Additionally, in certain regions, there is still a cultural preference for cash transactions, making it difficult to shift consumers away from traditional payment methods. Overcoming this reluctance and fostering greater consumer confidence remains a key challenge for the market.
Market Opportunities:
The mobile payment technologies market presents significant opportunities for growth in emerging markets, where the adoption of digital payments is rapidly increasing. As smartphone penetration continues to rise in regions such as Asia-Pacific, Latin America, and Africa, mobile payments are becoming more accessible to a broader demographic, including previously underserved populations. The expansion of 4G and 5G networks, coupled with the growing availability of affordable smartphones, presents an opportunity to drive mobile payment adoption in these regions. Furthermore, governments are implementing initiatives to enhance financial inclusion, providing a favorable environment for mobile payment solutions to thrive. Companies can capitalize on these trends by developing localized mobile payment solutions that cater to the specific needs and preferences of consumers in emerging markets, driving growth in untapped areas.
Another key opportunity lies in the development of innovative payment solutions and strategic partnerships. As consumer expectations evolve, there is increasing demand for seamless and secure payment experiences. By leveraging technologies such as biometrics, artificial intelligence, and blockchain, companies can create more secure, efficient, and personalized mobile payment systems. Additionally, partnerships between mobile payment providers and financial institutions, retail businesses, and e-commerce platforms offer opportunities to integrate mobile payments into a broader range of services. This can help to increase the adoption of mobile payments by making them more convenient and widely accepted across various industries. Furthermore, the growing popularity of contactless payments and the rise of digital currencies open new avenues for innovation, allowing businesses to capitalize on emerging trends in the mobile payment ecosystem.
Market Segmentation Analysis:
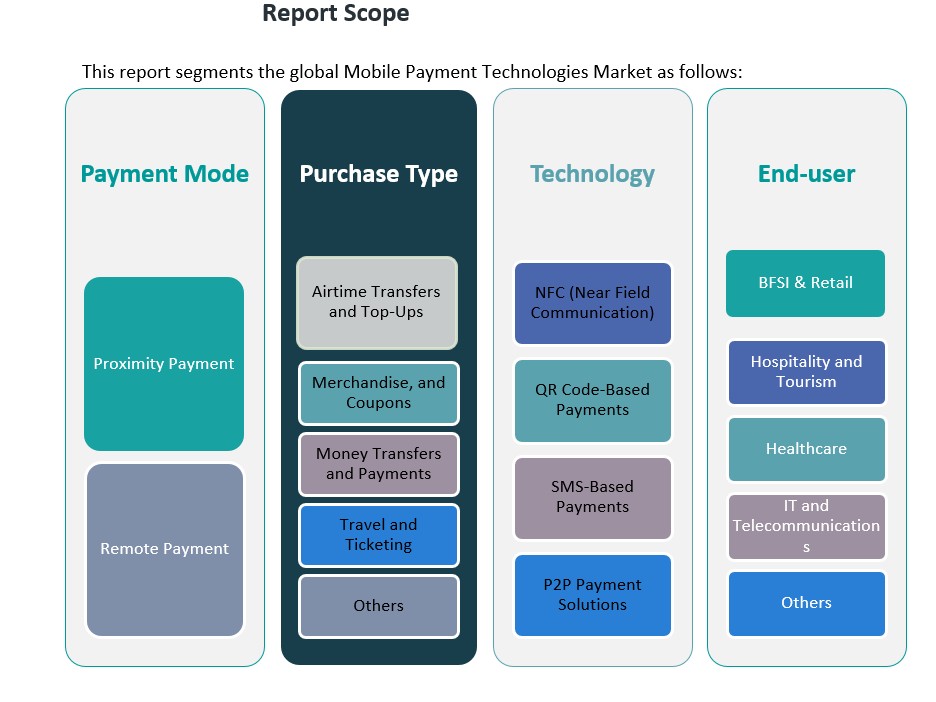
The mobile payment technologies market is segmented into several categories, each reflecting distinct aspects of consumer preferences, usage patterns, and technological advancements.
Payment Mode Segments are divided into Proximity Payment and Remote Payment. Proximity Payment, which involves contactless payments using Near Field Communication (NFC) technology, is growing rapidly due to its convenience in retail and transportation. On the other hand, Remote Payments, which are typically used for online transactions, are seeing substantial growth, particularly in e-commerce and digital services.
Purchase Type Segments include Airtime Transfers and Top-Ups, Merchandise and Coupons, Money Transfers and Payments, Travel and Ticketing, and Others. Money Transfers and Payments represent a significant share, driven by the increasing adoption of digital wallets for cross-border remittances and domestic transactions. Travel and Ticketing is another high-growth segment, with more consumers opting for mobile solutions for booking and payments.
End-user Segments encompass BFSI & Retail, Hospitality and Tourism, Healthcare, IT and Telecommunications, and Others. The BFSI and Retail sectors are the largest contributors, as mobile payment adoption enhances the efficiency and security of transactions. In Healthcare, mobile payments are gaining traction for insurance and medical bill payments, while IT and Telecommunications are integrating mobile payment solutions into their service offerings.
Technology Segments include NFC, QR Code-Based Payments, SMS-Based Payments, and P2P Payment Solutions. NFC remains the dominant technology in proximity payments, while QR Code-Based Payments and P2P Payment Solutions are growing in popularity, especially in regions with high smartphone penetration and a need for cost-effective solutions.
Segmentation:
By Payment Mode Segments:
- Proximity Payment
- Remote Payment
By Purchase Type Segments:
- Airtime Transfers and Top-Ups
- Merchandise and Coupons
- Money Transfers and Payments
- Travel and Ticketing
- Others
By End-user Segments:
- BFSI & Retail
- Hospitality and Tourism
- Healthcare
- IT and Telecommunications
- Others
By Technology Segments:
- NFC (Near Field Communication)
- QR Code-Based Payments
- SMS-Based Payments
- P2P Payment Solutions
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis:
The mobile payment technologies market demonstrates significant regional variations, with each region experiencing unique growth dynamics driven by factors such as smartphone penetration, technological infrastructure, and consumer behavior. The following provides an in-depth analysis of the market across key regions: North America, Asia-Pacific, Europe, and the Rest of the World.
North America
North America holds a dominant share of the global mobile payment technologies market, accounting for approximately 30% of the market in 2023. The region’s strong technological infrastructure, high smartphone penetration, and advanced financial systems contribute to its leadership position. Consumers in North America are increasingly adopting contactless payment methods, such as mobile wallets and NFC-based payment systems, due to their convenience and speed. Additionally, the presence of leading digital payment providers such as Apple Pay, Google Pay, and Samsung Pay has accelerated market growth in the region. The integration of mobile payments with e-commerce platforms and retail businesses further enhances the adoption rate, making mobile payments an essential part of the digital transaction ecosystem.
Asia-Pacific
The Asia-Pacific region is witnessing the fastest growth in the mobile payment technologies market, this region is expected to capture around 45% of the global market share by 2025. The widespread use of smartphones, coupled with the region's rapidly developing digital infrastructure, has fueled the expansion of mobile payments, particularly in countries like China, India, and Japan. China leads the region with mobile payment solutions like Alipay and WeChat Pay, which have revolutionized digital payments in the country. India's adoption of the Unified Payments Interface (UPI) has also contributed to the growing mobile payment ecosystem, making mobile transactions more accessible to the masses. The government’s push towards cashless economies and financial inclusion in these markets further accelerates the growth of mobile payments in Asia-Pacific.
Europe
Europe holds around 20% of the global market share in mobile payment technologies. The adoption of mobile payments in Europe is driven by the presence of established financial institutions, a robust regulatory environment, and growing consumer preference for digital wallets. Countries like the UK, Germany, and France have seen significant growth in mobile payment adoption, facilitated by the rise of contactless payments and the increasing use of mobile wallets. However, the growth rate in Europe is somewhat slower compared to North America and Asia-Pacific, as traditional banking methods remain highly entrenched in many countries. Nevertheless, the continued shift toward cashless payments and advancements in mobile payment technologies provide significant opportunities for growth in the region.
Rest of the World
The Rest of the World, which includes regions such as Latin America, the Middle East, and Africa, is experiencing steady growth in mobile payment adoption, accounting for around 5% of the global market share. In Latin America, countries like Brazil and Mexico have seen the rise of alternative mobile payment solutions, such as boleto bancário and OXXO, which allow consumers to make payments without the need for traditional bank accounts. In Africa, mobile payment solutions like M-Pesa in Kenya have played a pivotal role in promoting financial inclusion by enabling millions of unbanked individuals to access mobile banking services. The growing smartphone usage, internet penetration, and the increasing number of digital payment solutions are expected to drive mobile payment adoption across these regions in the coming years.
Key Player Analysis:
-
Google (Alphabet Inc.)
- Alibaba Group Holdings Limited
- American Express Company
- MoneyGram International
- PayPal Holdings Inc.
Competitive Analysis:
The mobile payment technologies market is highly competitive, with several key players vying for market share through innovation and strategic partnerships. Major players such as Apple Pay, Google Pay, Samsung Pay, and PayPal dominate the market, leveraging their established brand presence and customer trust to drive adoption of mobile payment solutions. These companies continue to enhance their offerings through advancements in security, such as biometric authentication and encryption technologies, to meet growing consumer concerns about data protection. Additionally, fintech companies and emerging startups are disrupting the market by introducing localized payment solutions tailored to specific regional needs. For example, Alipay and WeChat Pay lead in China, while UPI has gained significant traction in India. To remain competitive, companies are increasingly focusing on expanding their ecosystems by partnering with retailers, banks, and tech firms to improve mobile payment integration and offer seamless user experiences across multiple platforms and services.
Recent Developments:
- In January 2025, Google announced its partnership with the Saudi Central Bank (SAMA) to launch Google Pay in Saudi Arabia. This initiative aligns with Saudi Vision 2030 to enhance the digital payments ecosystem and reduce cash dependency.
- In March 2025, Alphabet Inc. confirmed its acquisition of cybersecurity startup Wiz for $32 billion, marking its largest acquisition to date. This move strengthens Alphabet’s focus on cloud security and digital payments.
- In March 2025, Ant International (an Alibaba affiliate) partnered with LankaPay to introduce Alipay+ in Sri Lanka. Over 400,000 merchants can now accept cross-border mobile payments from tourists via 14 international e-wallets linked to Alipay+.
- In February, 2025, AmEx partnered with Alipay to enable cardholders to link their cards to Alipay’s wallet for seamless payments across China.
Market Concentration & Characteristics:
The mobile payment technologies market exhibits a moderate to high level of concentration, with several large players commanding significant market share. Key companies such as Apple Pay, Google Pay, Samsung Pay, and PayPal dominate the landscape, benefiting from their extensive customer bases, brand recognition, and advanced technological capabilities. These players are focused on enhancing user experience through continuous innovation in security, user interface design, and cross-platform integration. The market is characterized by rapid technological advancements, particularly in areas like biometric authentication, Near Field Communication (NFC), and blockchain. This innovation-driven environment fosters a competitive dynamic, where established players are constantly evolving to meet consumer demands for faster, more secure, and more convenient mobile payment solutions. Additionally, regional players such as Alipay and WeChat Pay in Asia, and UPI in India, further contribute to market fragmentation, creating a diverse competitive landscape across different geographical regions.
Report Coverage:
The research report offers an in-depth analysis based on Payment Mode Segments, Purchase Type Segments, End-user Segments and Technology Segments. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- The mobile payment market is expected to experience continued rapid growth in the coming years.
- Increased smartphone adoption and improved internet connectivity will boost market penetration in emerging regions.
- Contactless payment technologies, particularly NFC, will see wider use across various industries, including retail and transportation.
- The integration of AI and machine learning will improve fraud detection and enhance the personalization of payment experiences.
- Evolving regulatory frameworks will support smoother cross-border transactions and enhance consumer protection.
- Blockchain technology will become increasingly relevant, offering more secure and transparent payment solutions.
- Strategic partnerships between fintech companies and traditional financial institutions will create more integrated digital payment ecosystems.
- Mobile payments will be increasingly integrated into wearable devices, driving adoption in consumer electronics.
- The rise of digital currencies and central bank digital currencies (CBDCs) will shape the future of mobile payment options.
- Growing consumer demand for seamless and omnichannel payment experiences will continue to drive innovation across platforms.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Technological Advancements and Innovation
Continuous innovation in mobile payment technologies, such as NFC, biometric authentication, and blockchain, is making transactions more secure and efficient, thereby increasing consumer trust and adoption rates.
Widespread Smartphone Penetration and Internet Accessibility
The rapid increase in smartphone ownership and the expansion of high-speed internet access globally have made mobile payment solutions more accessible, enabling a larger population to participate in digital transactions.
Shift Towards Cashless Societies
Government and financial institution initiatives to promote cashless economies are accelerating the adoption of mobile payments, as digital transactions offer greater convenience, security, and efficiency compared to cash.
Integration with E-commerce and Service Platforms
The seamless embedding of mobile payment options into e-commerce, ride-sharing, and food delivery platforms is driving higher usage by offering consumers a convenient and unified payment experience across multiple services.
Regulatory Support and Financial Inclusion Initiatives
Supportive regulatory frameworks and government-led financial inclusion programs, especially in emerging markets, are fostering the adoption of mobile payment technologies by making digital financial services more accessible to underserved populations.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Mobile Payment Technologies Market?
What factors are driving the growth of the Mobile Payment Technologies Market?
What are the key segments within the Mobile Payment Technologies Market?
What are some challenges faced by the Mobile Payment Technologies Market?
Who are the major players in the Mobile Payment Technologies Market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By End-user
- 1.2.1 BFSI & Retail
- 1.2.2 Hospitality and Tourism
- 1.2.3 Healthcare
- 1.2.4 IT and Telecommunications
- 1.2.5 Others
- 1.3 By Technology
- 1.3.1 NFC (Near Field Communication)
- 1.3.2 QR Code-Based Payments
- 1.3.3 SMS-Based Payments
- 1.3.4 P2P Payment Solutions
- 1.4 By Payment Mode
- 1.4.1 Proximity Payment
- 1.4.2 Remote Payment
- 1.5 By Purchase Type
- 1.5.1 Airtime Transfers and Top-Ups
- 1.5.2 Merchandise and Coupons
- 1.5.3 Money Transfers and Payments
- 1.5.4 Travel and Ticketing
- 1.5.5 Others
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 1,668.7 million → 2032: USD 2,409.63 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Mobile Payment Technologies Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Mobile Payment Technologies Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Mobile Payment Technologies Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Mobile Payment Technologies Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Mobile Payment Technologies Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Mobile Payment Technologies Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Data Protection, AI and Cybersecurity Compliance
- 9.8 Upcoming Policy Changes and Market Implications
Chapter 10 Global Mobile Payment Technologies Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Mobile Payment Technologies Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 1,668.7 million → 2032: USD 2,409.63 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Mobile Payment Technologies Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By End-user - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 BFSI & Retail
- 12.3.7.2 Hospitality and Tourism
- 12.3.7.3 Healthcare
- 12.3.7.4 IT and Telecommunications
- 12.3.7.5 Others
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Technology - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 NFC (Near Field Communication)
- 12.4.7.2 QR Code-Based Payments
- 12.4.7.3 SMS-Based Payments
- 12.4.7.4 P2P Payment Solutions
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Payment Mode - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Proximity Payment
- 12.5.7.2 Remote Payment
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 By Purchase Type - Market Size and Forecast, 2024-2032
- 12.6.1 Segment Definition and Scope
- 12.6.2 Historical Market Size
- 12.6.3 Revenue Forecast, 2024-2032
- 12.6.4 Volume Forecast, 2024-2032
- 12.6.5 Base-Year Market Share, 2024
- 12.6.6 Segment CAGR and Growth Drivers
- 12.6.7 Subsegment Market Size and Forecast
- 12.6.7.1 Airtime Transfers and Top-Ups
- 12.6.7.2 Merchandise and Coupons
- 12.6.7.3 Money Transfers and Payments
- 12.6.7.4 Travel and Ticketing
- 12.6.7.5 Others
- 12.6.8 Subsegment Pricing and Adoption Trends
- 12.6.9 Leading Suppliers and Competition
- 12.6.10 Regional Demand and Opportunities
- 12.7 Segment Growth Comparison
- 12.8 Segment Attractiveness and Priority Matrix
Chapter 13 Global Mobile Payment Technologies End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Mobile Payment Technologies Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Mobile Payment Technologies Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Mobile Payment Technologies Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Google (Alphabet Inc.)
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Apple Inc.
- 18.4 Samsung Electronics
- 18.5 PayPal Holdings Inc.
- 18.6 Alibaba Group Holdings Limited
- 18.7 American Express Company
- 18.8 MoneyGram International
- 18.9 Ant Group (Alipay)
- 18.10 WeChat Pay (Tencent)
- 18.11 Square Inc. (Block, Inc.)
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

