
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
| North America Hummus Market Size 2024 | USD 1,519.09 million |
| North America Hummus Market, CAGR | 11.27% |
| North America Hummus Market Size 2032 | USD 3,569.83 million |
Market Overview
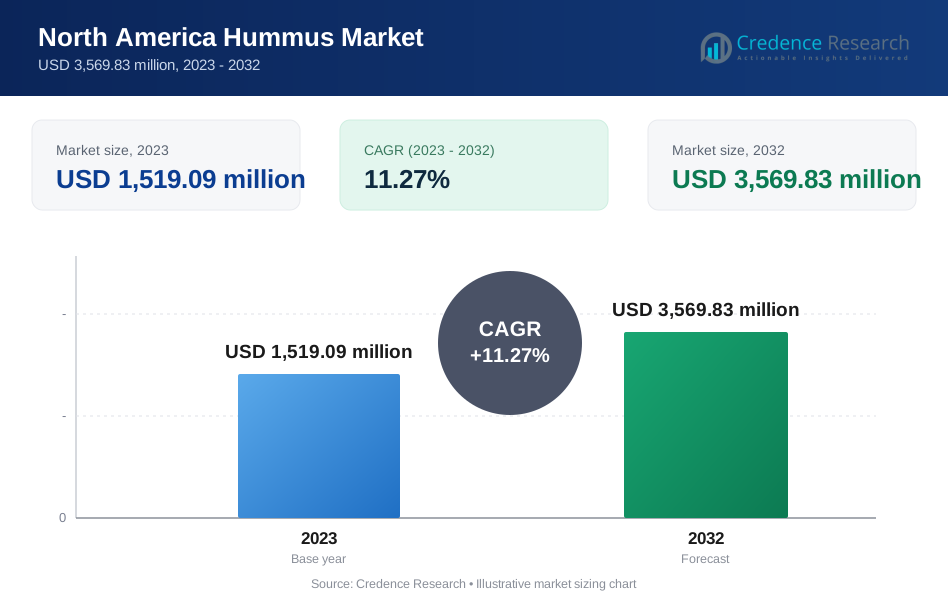
The North America Hummus Market is projected to grow from USD 1,519.09 million in 2023 to an estimated USD 3,569.83 million by 2032, reflecting a robust compound annual growth rate (CAGR) of 11.27% from 2024 to 2032. This growth underscores the increasing consumer demand for healthy and plant-based food products, with hummus gaining traction as a versatile and nutritious dip and spread.
The market is driven by rising health consciousness among consumers, leading to a preference for plant-based proteins and natural ingredients. The growing popularity of Mediterranean and Middle Eastern cuisines in North America has further bolstered hummus consumption. Additionally, manufacturers' focus on clean-label products and convenient packaging solutions aligns with consumer trends, driving market growth. The adoption of hummus as a healthier alternative to traditional spreads and dips also supports its increasing penetration across diverse demographics.
Geographically, the United States dominates the North America hummus market, fueled by widespread awareness of its health benefits and the presence of leading market players. Canada is emerging as a lucrative region, supported by a growing preference for plant-based diets. Key players in the market, such as Sabra Dipping Company, Tribe Mediterranean Foods, and Cedar’s Mediterranean Foods, are investing in product innovation and strategic collaborations to strengthen their market presence and cater to evolving consumer demands.
Market Insights
- The North America Hummus Market is projected to grow from USD 1,519.09 million in 2023 to USD 3,569.83 million by 2032, with a CAGR of 11.27%, driven by rising demand for healthy and plant-based food options.
- Consumers' growing preference for natural ingredients and plant-based proteins significantly drives hummus adoption as a nutritious dip and spread.
- Manufacturers are focusing on innovative flavors and clean-label formulations, enhancing product diversity and catering to varied consumer tastes.
- Market growth is challenged by the availability of other dips and spreads, as well as consumer sensitivity to product pricing.
- The rising influence of Mediterranean and Middle Eastern cuisines in North America has boosted the market demand for hummus as a staple food item.
- The U.S. leads the market, supported by high consumer awareness of health benefits and the strong presence of established brands.
- Canada shows significant growth potential, fueled by a shift towards plant-based diets and increased availability of hummus products across retail channels.
Market Drivers
Increasing Health Awareness and Preference for Plant-Based Foods
The growing health consciousness among North American consumers has significantly fueled the demand for hummus. Recognized as a healthy, nutrient-dense option, hummus aligns with the increasing shift toward plant-based diets. It is rich in plant-based proteins, dietary fiber, and essential vitamins, appealing to health-conscious individuals seeking alternatives to traditional calorie-heavy spreads and dips. For instance, the National Health and Nutrition Examination Survey (NHANES) data indicates that individuals who regularly consume chickpeas or hummus have higher intakes of dietary fiber, polyunsaturated fatty acids, vitamin A, vitamin E, vitamin C, folate, magnesium, potassium, and iron compared to non-consumers. The broader awareness of the benefits of chickpeas as a primary ingredient—including their role in managing cholesterol levels and improving digestive health—has further solidified hummus as a staple in many households. Additionally, the rise of veganism and vegetarianism in North America has expanded the market for hummus as a preferred protein source, supporting its steady adoption across diverse consumer demographics.
Rising Popularityof Mediterranean Cuisine
The growing appreciation for Mediterranean cuisine has been a significant driver of the North America hummus market. Consumers are increasingly exploring global culinary trends, and hummus, as a quintessential Mediterranean food, has gained widespread recognition. The popularity of Mediterranean diet principles, which emphasize healthy fats, legumes, and vegetables, has propelled hummus into the mainstream. For instance, a study published in the Journal of the Academy of Nutrition and Dietetics found that consumers of hummus had higher Healthy Eating Index (HEI) scores, suggesting that hummus consumption is associated with better overall diet quality. This trend is supported by food service providers and restaurants incorporating hummus into their menus, ranging from traditional offerings to innovative pairings. Retailers are also capitalizing on this trend by expanding their range of Mediterranean-inspired ready-to-eat products, further boosting the demand for hummus.
Product Innovation and Diversification
Manufacturers' focus on product innovation has been pivotal in driving the growth of the hummus market in North America. Companies are introducing diverse flavors, including roasted red pepper, garlic, and avocado, to cater to evolving consumer preferences. They are also exploring fusion flavors that combine traditional hummus with popular regional tastes, thereby attracting a wider audience. For instance, in response to consumer demand for variety, companies like Sabra have introduced innovative flavors such as Spicy Harissa and Mediterranean Roasted Garlic, expanding their product lines to include options like Buffalo Hummus and BBQ Hummus, which cater to the adventurous palates of North American consumers. Furthermore, advancements in packaging, such as single-serve portions and resealable containers, have enhanced product convenience and portability. Clean-label initiatives and the inclusion of organic, non-GMO, and gluten-free options are increasingly resonating with health-conscious consumers, further accelerating market growth.
Expansion of Retail and Distribution Channels
The rapid expansion of retail and distribution networks across North America has played a crucial role in increasing hummus accessibility. Supermarkets, hypermarkets, and specialty food stores now dedicate significant shelf space to hummus and related products, reflecting its growing demand. For instance, major retailers like Walmart have collaborated with brands like Fresh Cravings to launch new hummus flavors, making these products more accessible to a broader audience through extensive distribution networks and promotional activities. Additionally, the rise of e-commerce platforms has enabled consumers to conveniently purchase hummus, often benefiting from subscription-based delivery models. Retailers are also leveraging promotional strategies, including discounts and in-store sampling, to boost sales. The penetration of hummus into non-traditional retail spaces, such as convenience stores and vending machines, has further broadened its reach, ensuring that the product appeals to on-the-go consumers and busy professionals.
Market Trends
Growing Popularity of Organic and Clean-Label Products
Consumers in North America are increasingly seeking organic and clean-label hummus options, driven by heightened awareness of food transparency and health implications. For instance, in June 2023, Hope Foods introduced a new range of organic, non-GMO, and plant-based dips with vibrant flavors. This launch not only emphasizes the use of natural ingredients but also highlights their Plastic Neutral certification, showcasing a commitment to environmental responsibility. The inclusion of organic flaxseed oil in these products further enhances their functional benefits, appealing to health-conscious consumers.Products that emphasize natural, non-GMO, and preservative-free ingredients are gaining significant traction. Manufacturers are responding by launching organic-certified and clean-label hummus variants to cater to this growing demand. The clean-label trend aligns with consumers’ expectations for transparency in food production, particularly regarding ingredient sourcing and processing methods. This shift not only enhances brand loyalty but also expands the market's appeal among health-focused demographics.
Innovation in Flavors and Formats
The North America hummus market is witnessing continuous innovation in flavors and product formats designed to cater to diverse taste preferences. In October 2024, Summer Fresh unveiled three new products, including Scorching Dill Pickle Hummus, Honey Jalapeño Hummus, and Spicy Black Bean Dip. These innovative offerings reflect the company's commitment to expanding its hummus and dip range to attract adventurous eaters looking for unique flavor combinations.Additionally, manufacturers are introducing snack-size packs, hummus-based spreads, and meal kits to appeal to convenience-driven consumers. Limited-edition seasonal flavors and fusion products blending traditional hummus with regional or cultural influences are also gaining popularity. These innovations not only enhance product diversity but also help brands differentiate themselves in a competitive market.
Increased Adoption of Sustainable Practices
Sustainability has become a key focus for both consumers and manufacturers in the North America hummus market. Companies are adopting eco-friendly practices such as using recyclable packaging and sourcing chickpeas from sustainable farming initiatives. For example, uBu Foods has designed "Hiker’s Hummus" for outdoor enthusiasts, which does not require refrigeration and weighs half as much as conventional hummus. This innovative approach aligns with their goal to minimize environmental impact while catering to eco-conscious consumers.Furthermore, some brands actively communicate their sustainability efforts through marketing campaigns that resonate strongly with environmentally responsible buyers. By highlighting their commitment to sustainable practices, these companies strengthen their competitive positioning in a market increasingly influenced by consumer demand for environmentally friendly products.
Expansion of Plant-Based Diet Trends
The rise of plant-based diets across North America continues to be a significant trend driving hummus market growth. As consumers increasingly prioritize plant-based alternatives for health, ethical, and environmental reasons, hummus is being embraced as a versatile and protein-rich option. For instance, Sabra has collaborated with Frank's RedHot and Stubb's to launch a new line of flavored hummus products, including Buffalo Hummus, BBQ Hummus, and Sabra Southwest Hummus. This collaboration caters to the growing demand for plant-based and dairy-free options while promoting hummus as an integral part of a balanced diet.This trend is further amplified by partnerships between hummus manufacturers and plant-based food companies that create synergies promoting hummus consumption. Social media influencers and health advocates also play a role in popularizing hummus as a go-to option for plant-based eating, contributing significantly to its growing appeal among diverse consumer segments.
Market Challenges
Competition and Market Saturation
The rapid growth of the North America hummus market has led to increased competition among manufacturers, resulting in market saturation in some regions. Both established brands and new entrants are vying for market share, leading to pricing pressures and reduced profit margins. For instance, major retailers are increasingly introducing private-label hummus products, intensifying the competitive landscape and challenging smaller manufacturers. This situation has led to significant pricing pressures, where brands are forced to lower prices or invest heavily in marketing and promotions to maintain visibility.Moreover, the market's saturation is evident as consumers face a plethora of options, resulting in diluted brand loyalty. As a result, companies are compelled to innovate continuously and diversify their product offerings to attract and retain customers. For example, manufacturers are now introducing a variety of flavors beyond traditional hummus, such as roasted garlic, red pepper, and even dessert-themed options like chocolate hummus, to cater to evolving consumer tastes. This innovation not only helps brands stand out in a crowded market but also addresses the growing demand for unique and diverse food experiences among consumers.Additionally, the increased competition necessitates significant investments in marketing strategies that resonate with health-conscious consumers. Brands are leveraging social media platforms and influencer partnerships to enhance their visibility and engage with their target audience effectively. Overall, the dynamics of competition and market saturation in the North America hummus market underscore the need for brands to be agile and responsive to consumer preferences while navigating the challenges posed by an increasingly crowded marketplace.
Supply Chain and Ingredient Sourcing Challenges
The North America hummus market faces challenges related to supply chain disruptions and the sourcing of high-quality ingredients, particularly chickpeas. Fluctuations in chickpea prices have been noted due to adverse weather conditions and geopolitical factors affecting agricultural production. For example, recent reports indicate that chickpea prices have surged significantly due to supply shortages linked to droughts in key producing regions. This volatility can impact manufacturing costs and product pricing, creating challenges for companies that rely on consistent ingredient availability.Furthermore, as consumer demand shifts towards organic and sustainably sourced ingredients, manufacturers are under pressure to secure reliable suppliers who meet these criteria. The growing emphasis on sustainability is prompting companies to rethink their sourcing strategies and establish partnerships with trusted agricultural producers. This shift not only addresses consumer preferences but also aligns with broader industry trends toward ethical sourcing practices.Additionally, rising transportation costs and supply chain inefficiencies exacerbate these challenges. Manufacturers may face delays or increased costs associated with transporting ingredients from suppliers to production facilities. Such disruptions can affect the overall availability of hummus products in the market, potentially leading to stock shortages or increased retail prices for consumers. Overall, these dynamics illustrate the complex interplay between ingredient sourcing and supply chain management that companies in the North America hummus market must navigate to sustain growth and profitability while meeting consumer expectations for quality and sustainability.
Market Opportunities
Expansion into Untapped Consumer Segments
The North American hummus market presents significant opportunities to target untapped consumer segments, including younger demographics and non-traditional consumers. Brands have successfully leveraged digital marketing strategies and collaborated with social media influencers to create awareness among millennial and Gen Z consumers who prioritize health and convenience. This demographic is particularly responsive to products that align with their values, such as sustainability and nutritional benefits. For instance, the introduction of hummus in school lunch programs has shown promise, as schools increasingly seek healthier snack alternatives. Hummus serves as a nutritious option that appeals to both children and parents, making it an ideal candidate for school menus. Additionally, partnerships with corporate wellness initiatives can enhance visibility among working professionals who are focused on maintaining healthy eating habits in their busy lives. These strategies not only broaden the consumer base but also position hummus as a go-to snack for health-conscious individuals.Increasing awareness campaigns in regions where hummus consumption is relatively low can further expand market reach. By targeting these areas with tailored marketing efforts, brands can educate potential consumers about the benefits of hummus, driving trial and adoption. Overall, tapping into these underrepresented segments through innovative marketing and strategic partnerships can significantly enhance the growth potential of the hummus market in North America.
Integration with Emerging Food Trends
Integrating hummus with emerging food trends opens new avenues for market growth and consumer engagement. Companies are exploring collaborations with meal kit services to include hummus as a versatile ingredient, catering to busy professionals seeking convenient yet nutritious meal options. This integration not only enhances the appeal of meal kits but also positions hummus as an essential pantry staple.Innovative product development is also gaining traction, with brands introducing hummus-infused snacks such as baked chips and pasta sauces. These products highlight the versatility of hummus while catering to trend-savvy consumers eager for unique flavor experiences. For example, ready-to-eat hummus packs are becoming popular among consumers looking for portable, healthy snacks that fit seamlessly into their on-the-go lifestyles.Moreover, aligning hummus with current culinary trends—such as plant-based diets and fusion cuisine—positions it as a desirable product across various food categories. By emphasizing its adaptability, brands can attract a broader audience interested in exploring new culinary experiences. This strategic integration not only enhances the visibility of hummus but also reinforces its status as a must-have item in modern diets, ultimately driving growth within the market.
Market Segmentation Analysis
By Product
The hummus market in North America is segmented by product type, including Classic Latin America Hummus, Roasted Garlic Latin America Hummus, White Bean Latin America Hummus, Black Olive Latin America Hummus, and others. Classic hummus remains the most popular due to its traditional appeal, while flavored variants like roasted garlic and black olive are gaining traction among consumers seeking variety. White bean hummus caters to those looking for alternatives with a lighter texture, reflecting a growing trend toward personalization and diverse tastes.
By Packaging Type
Packaging types for hummus include tubs and cups, jars and bottles, and others. Tubs and cups dominate the market as they are convenient for both individual consumption and sharing. Jars and bottles are increasingly used for premium or artisanal hummus products, appealing to consumers looking for high-quality, long-lasting options. Innovative packaging solutions like resealable containers are further enhancing convenience and reducing food waste.
Segments
Based on product
- Classic Latin America Hummus
- Roasted Garlic Latin America Hummus
- White Bean Latin America Hummus
- Black Olive Latin America Hummus
- Other
Based on Packaging type
- Tubs & Cups
- Jars & Bottles
- Others
Based on Ingredient type
- Chickpeas
- Tahini
- Olive Oil
- Garlic
- Others
Based on Distribution channel
- Supermarkets & Hypermarkets
- Convenience Stores
- Grocery Stores
- Online Retailers
- Others
Based on region
- United States
- Canada
- Mexico
Regional Analysis
United States (70%)
The United States holds the largest market share in the North America hummus market, accounting for approximately 70% of the total market. The dominance of the U.S. can be attributed to high consumer awareness, the widespread popularity of Mediterranean cuisine, and the presence of leading market players such as Sabra Dipping Company. Additionally, the health-conscious population in the U.S. has driven the demand for plant-based and clean-label products, making hummus a popular choice across households and foodservice establishments.
Canada (20%)
Canada accounts for around 20% of the North America hummus market. The growing inclination towards plant-based diets and increasing awareness about the nutritional benefits of hummus have bolstered its demand in the region. Supermarkets and hypermarkets in Canada prominently feature hummus products, and the rise of online retail platforms has further expanded consumer access. The Canadian market is witnessing notable growth, driven by innovative product launches and a rising preference for organic and clean-label options.
Key players
- Bakkavor Group Plc
- Sabra Dipping Company, LLC
- Boar’s Head Brand
- Tribe Mediterranean Foods, Inc.
- SAVENCIA SA
- Abraham's Natural Foods
- Ithaca Hummus
- CEDAR’S MEDITERRANEAN FOODS, INC.
- Lantana Foods
- Haliburton International Foods, Inc.
- Roots Hummus
- Hannah Foods
- Haig’s Delicacies
- Elma Farms
- ESTI FOODS
Competitive Analysis
The North America hummus market is highly competitive, driven by the presence of established brands and emerging players. Companies like Sabra Dipping Company, LLC, and Cedar’s Mediterranean Foods, Inc. dominate the market with extensive product portfolios and robust distribution networks. Innovation in flavors and packaging has become a key differentiator, with players like Ithaca Hummus and Lantana Foods focusing on clean-label and organic options. Smaller brands, including Roots Hummus and Haig’s Delicacies, are leveraging niche marketing strategies to target health-conscious and gourmet consumers. Strategic partnerships and investments in sustainability initiatives further strengthen the competitive landscape.
Recent Developments
- In January 2025, Bakkavor Group Plc reported a strong performance for the full year 2024, with a notable increase in revenue driven by improved volumes and price recovery. The company highlighted its focus on operational efficiencies and strategic progress, which has positioned it well for continued growth in the North American hummus market. Their commitment to quality and innovation is expected to enhance their product offerings in this competitive sector.
- In December 2024, PepsiCo announced its acquisition of Sabra Dipping Company, acquiring the remaining 50% interest from Strauss Group. This move is expected to bolster Sabra's position in the hummus market, allowing for accelerated innovation and product development in response to growing consumer demand for healthier options. Sabra has been a leading brand in the U.S. hummus market, and this acquisition aims to enhance its portfolio further.
- In October 2024, SAVENCIA Fromage & Dairy announced its acquisition of Hope Foods, a brand known for its organic hummus and plant-based dips. This acquisition is part of SAVENCIA's strategy to expand its footprint in the North American hummus market, emphasizing health and nutrition as key drivers of consumer choice.
- In November 2023, Ithaca Hummus announced plans to triple its production capacity with a significant investment in a new production line. This expansion is aimed at meeting the rising demand for fresh, clean-ingredient dips among consumers who prioritize quality and flavor.
- In August 2024, CEDAR’S Mediterranean Foods is set to open a new factory in Massachusetts following a $100 million investment. This facility will double their annual production capacity and enhance their ability to meet growing consumer demands for high-quality hummus products.
- In September 2024, Lantana Foods rebranded its hummus line with new sustainable packaging and introduced unique flavor combinations aimed at health-conscious consumers. The updated packaging reflects the company's commitment to environmental responsibility while appealing to a broader audience seeking innovative food options.
Market Concentration and Characteristics
The North America Hummus Market exhibits a moderately fragmented structure, with a blend of global and regional players contributing to its competitive landscape. Key manufacturers focus on innovative product offerings, including flavor diversification and health-oriented formulations, to cater to the evolving consumer preferences for nutritious and plant-based snacks. The market benefits from high brand loyalty among consumers and the presence of well-established distribution channels, such as supermarkets, hypermarkets, and online platforms, ensuring wide accessibility. Additionally, the growing influence of clean-label and organic trends has led to an emphasis on transparency in ingredient sourcing and labeling, further shaping market dynamics. While large players dominate the market with extensive product portfolios and marketing strategies, smaller regional brands are carving out niches by targeting local tastes and offering artisanal hummus varieties.
Report Coverage
The research report offers an in-depth analysis based on product, Packaging type, Ingredient type, Distribution channel and Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The increasing adoption of plant-based diets will continue to drive hummus consumption, as consumers seek nutritious, protein-rich, and environmentally friendly alternatives to traditional snacks.
- Innovations in flavor profiles, including region-specific and fusion varieties, are expected to attract diverse consumer groups, enhancing market growth.
- The demand for organic and preservative-free hummus is likely to rise as health-conscious consumers prioritize clean-label and sustainably sourced products.
- The growing popularity of e-commerce platforms will facilitate wider access to hummus products, particularly among younger and tech-savvy demographics.
- Fortified hummus products enriched with probiotics, vitamins, and other functional ingredients are anticipated to gain traction as part of the health and wellness trend.
- Local and small-scale manufacturers focusing on authentic and artisanal hummus varieties will increasingly capture niche markets and cater to regional taste preferences.
- Sustainability trends will push manufacturers to adopt eco-friendly and biodegradable packaging, aligning with consumer demands for environmentally conscious products.
- Single-serving, portion-controlled packaging is expected to gain popularity, catering to on-the-go consumers and busy lifestyles.
- Hummus is likely to penetrate non-traditional markets such as schools, hospitals, and workplace cafeterias, driven by its reputation as a healthy snack option.
- Targeted advertising and educational campaigns about the health benefits of hummus will enhance consumer awareness and broaden its market appeal across North America.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the market size of the North America Hummus Market in 2023 and 2032, and what is its CAGR?
What factors are driving the growth of the North America Hummus Market?
How are manufacturers aligning with consumer trends in the hummus market?
Which regions dominate the North America Hummus Market?
What role do key players play in shaping the hummus market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 North America Hummus Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2023; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global North America Hummus Market Snapshot
- 2.1.1 Market Size – Historical (2023) & Forecast (2023-2032) (2023: USD 1,519.09 million → 2032: USD 3,569.83 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 North America Hummus Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2023 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2023
- 2.3.2 Top 10 Players by Volume Share – 2023
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. North America Hummus Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 North America Hummus Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 North America Hummus Market Drivers
- 3.3 North America Hummus Market Restraints & Challenges
- 3.4 North America Hummus Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 North America Hummus Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 North America Hummus Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, North America Hummus category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 North America Hummus Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. North America Hummus Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2023)
- 5.1.2 Global Export Volume by Country (2023)
- 5.1.3 Global Import Value by Country (2023)
- 5.1.4 Global Import Volume by Country (2023)
- 5.1.5 Net Trade Balance by Country (2023)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2023)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the North America Hummus market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 North America Hummus Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2023
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 North America Hummus Market Share Analysis – 2023
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2023)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 North America Hummus Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in North America Hummus (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New North America Hummus Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global North America Hummus Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2023 & 2032)
- 7.1.2 Channel Mix Evolution (2023-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America North America Hummus Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe North America Hummus Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific North America Hummus Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America North America Hummus Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East North America Hummus Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa North America Hummus Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. North America Hummus Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
