
Market Overview
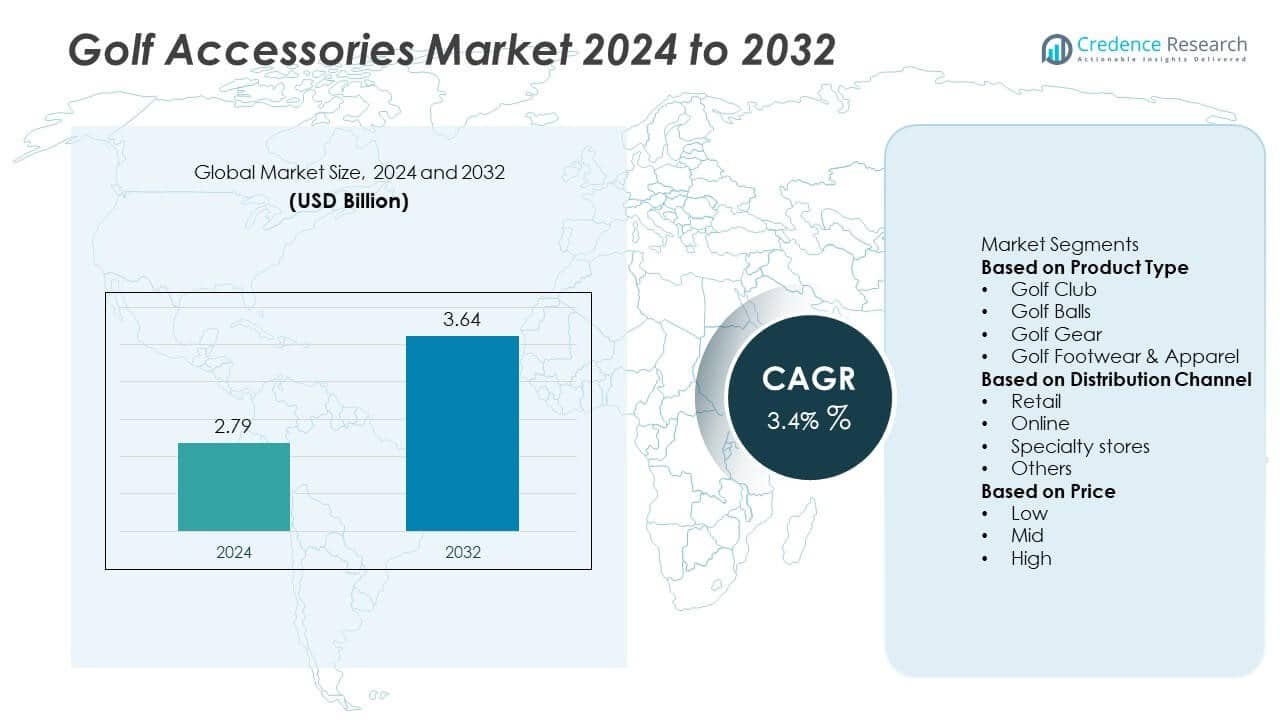
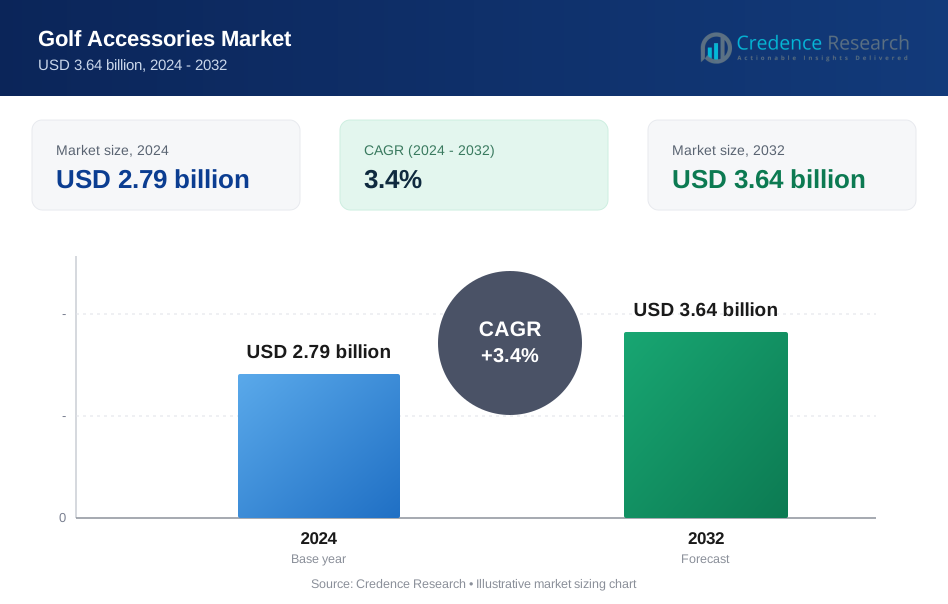
The Golf Accessories Market was valued at USD 2.79 billion in 2024 and is expected to reach USD 3.64 billion by 2032, registering a CAGR of 3.4% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Golf Accessories Market Size 2024 | USD 2.79 Billion |
| Golf Accessories Market, CAGR | 3.4% |
| Golf Accessories Market Size 2032 | USD 3.64 Billion |
The golf accessories market is led by major companies including Bridgestone Corporation, Wilson Sporting Goods, TaylorMade Golf Company, PING Inc., Yonex Co., Ltd., Mizuno Corporation, SRI Sports Limited (Dunlop, Cleveland, Srixon), Callaway Golf Company, Nike, Inc., and Acushnet Holdings Corporation (Titleist). These players dominate through innovation in high-performance golf clubs, advanced materials, and smart wearable technologies. North America emerged as the leading region with a 42% market share in 2024, driven by a strong golfing culture, established tournaments, and premium consumer spending. Europe followed with a 28% share, supported by a well-developed golf infrastructure and rising sustainability trends, while Asia-Pacific rapidly expanded its footprint, accounting for 20% due to growing participation and regional investments in golf development.
Market Insights
- The golf accessories market was valued at USD 2.79 billion in 2024 and is projected to reach USD 3.64 billion by 2032, registering a CAGR of 3.4% during the forecast period.
- Rising participation in golf, expansion of new courses, and increasing adoption of premium golf clubs and apparel are driving market growth.
- Technological advancements such as smart sensors, GPS-based devices, and lightweight materials are shaping market trends and improving player performance.
- The market is moderately consolidated, with major players like Callaway, TaylorMade, Titleist, Bridgestone, and Nike focusing on innovation, sustainability, and global brand collaborations.
- North America held a 42% market share in 2024, followed by Europe with 28% and Asia-Pacific with 20%; by product type, golf clubs accounted for 38%, while the retail channel led with 46% share, reflecting strong consumer preference for in-person purchasing and expert guidance.
Market Segmentation Analysis:
By Product Type
The golf club segment dominated the golf accessories market in 2024, holding over 38% share. This segment leads due to continuous product innovations such as adjustable lofts, lightweight carbon shafts, and advanced swing analysis integration. Premium brands are focusing on high-performance clubs tailored for different skill levels. The increasing popularity of custom-fit clubs and hybrid designs supports wider adoption. Demand from both professional golfers and hobbyists remains strong, driven by growing participation in organized golf tournaments and the development of new golf courses worldwide.
- For instance, PING’s G430 MAX driver incorporates a forged T9S+ face for improved spin consistency, validated through over 8,000 swing simulations during product testing.
By Distribution Channel
The retail segment accounted for the largest share of about 46% in 2024, driven by consumer preference for in-person trials and expert guidance. Retail stores, including golf specialty shops and sports outlets, provide personalized fitting experiences and promotional offers that enhance sales. However, online channels are growing rapidly due to convenience and access to product comparisons. The hybrid retail model combining offline and digital experiences is becoming a key growth driver as brands invest in omnichannel sales strategies to reach broader audiences.
- For instance, Callaway Golf offers custom fitting services utilizing advanced technology like TrackMan launch monitors. These monitors provide precise data on club and ball impact for optimal club recommendations, including adjustments to factors like loft and shaft.
By Price
The mid-price segment led the market with nearly 42% share in 2024, balancing affordability and quality. It appeals to both regular and amateur golfers seeking durable yet cost-effective accessories. Manufacturers are offering mid-range products with advanced materials like titanium and microfiber, enhancing performance without premium costs. The rise in middle-income consumers and increasing golf participation across emerging economies further boosts this segment. Mid-tier product lines also benefit from brand collaborations and promotional campaigns that attract new players transitioning from entry-level to professional-grade equipment.
Key Growth Drivers
Rising Participation in Golf Globally
Growing participation in golf across North America, Europe, and Asia-Pacific is a key market driver. Expanding golf tourism, new course developments, and supportive government initiatives are increasing interest in the sport. Younger players are drawn to golf through televised tournaments and social media exposure. The rising number of training academies and corporate events further supports accessory sales. As the sport gains popularity, demand for essential products like clubs, balls, and apparel continues to grow across both professional and recreational players.
- For instance, Callaway Golf Company reported a 22% increase in its club unit sales volume, reaching over 15 million units sold globally due to strong participation growth. The company also partnered with Topgolf to expand player engagement through 80+ interactive venues that hosted over 25 million visitors in a year, supporting greater awareness and interest in the sport.
Technological Advancements in Golf Equipment
Continuous innovation is transforming the golf accessories landscape. Smart golf clubs, AI-enabled swing analyzers, and GPS tracking devices are enhancing player precision and training effectiveness. Lightweight materials, carbon shafts, and aerodynamic golf balls improve performance and durability. Brands investing in digital and smart product integration appeal strongly to tech-savvy consumers. These developments not only encourage equipment upgrades but also create brand differentiation, driving consistent market expansion through advanced and data-driven solutions.
- For instance, Garmin's Approach S70 smartwatch integrates over 43,000 golf course maps and offers advanced features like Virtual Caddie, which uses historical swing data, wind, and elevation to provide club suggestions and help improve accuracy. It also includes swing tempo analysis for training outcomes.
Expanding Online Retail and Omnichannel Presence
Online retail and hybrid sales models are reshaping the golf accessories industry. E-commerce platforms offer wide accessibility, better pricing, and personalized recommendations, appealing to a diverse customer base. Many brands are now combining physical and digital experiences through omnichannel strategies. Virtual fittings, product visualization tools, and influencer marketing are improving customer engagement. This transformation enables manufacturers to reach new audiences and maintain strong brand visibility across both established and emerging markets.
Key Trends and Opportunities
Sustainability and Eco-Friendly Innovations
Sustainability has become a central trend in the golf accessories market. Companies are developing eco-friendly golf tees, apparel made from recycled materials, and biodegradable packaging. Golf courses are also adopting greener practices, reinforcing consumer interest in sustainable products. This shift enhances brand reputation and aligns with global environmental goals. Manufacturers focusing on green product innovation are well-positioned to attract environmentally conscious golfers and secure long-term competitive advantage.
- For instance, Adidas introduced its Adicross golf line made using 100% recycled polyester and diverted over 25 million plastic bottles from oceans through its “End Plastic Waste” initiative.
Premiumization and Customization Opportunities
Demand for premium and personalized golf accessories is increasing rapidly. Players now prefer customized clubs, tailored shoes, and limited-edition gear to enhance style and performance. Luxury brands are leveraging advanced materials and technology to create exclusive, high-quality designs. The focus on premiumization boosts brand loyalty and profit margins. This trend also appeals to skilled and professional golfers seeking precision, comfort, and individuality in their equipment choices.
- For instance, TaylorMade's MyStealth 2 Plus driver customization program enables golfers to personalize their club with options including nine carbon face colors, six composite ring colors, and several shaft and grip combinations.
Key Challenges
High Cost of Premium Golf Accessories
The elevated cost of high-end golf accessories limits adoption among amateur and casual players. Premium products such as advanced clubs, apparel, and smart devices often require substantial investment. This price barrier is more pronounced in developing regions with lower spending capacity. Balancing performance with affordability remains a major challenge for manufacturers. Expanding mid-range product lines and offering value-based options could help increase accessibility and market reach.
Seasonal and Weather Dependence
The golf accessories market faces seasonal constraints due to its reliance on favorable weather. Sales decline during colder months in major regions like North America and Europe, disrupting annual revenue flow. This cyclical demand pattern complicates production and inventory management. Manufacturers are addressing this by promoting indoor golf simulators and virtual training systems. Expanding into tropical markets and warmer regions also helps maintain steady sales throughout the year.
Regional Analysis
North America
North America dominated the golf accessories market in 2024 with a 42% share, driven by a well-established golfing culture and a high number of professional tournaments. The United States leads the region, supported by extensive golf infrastructure and participation from both professionals and amateurs. Strong consumer spending and technological innovation in smart golf gear also fuel demand. Brands such as Callaway and Titleist continue to expand their presence through advanced product launches and retail partnerships. The rising popularity of indoor golf simulators and youth engagement programs further sustains steady market growth.
Europe
Europe held a 28% share of the global golf accessories market in 2024, supported by strong participation in countries such as the United Kingdom, Germany, and France. The region benefits from historic golf traditions and growing government initiatives to promote outdoor sports. Sustainability-driven consumer behavior has increased demand for eco-friendly apparel and equipment. Major golf events such as the Ryder Cup enhance regional interest, while the expansion of golf resorts supports tourism-linked sales. The growing adoption of digital golf technologies is further strengthening Europe’s position in the global market.
Asia-Pacific
Asia-Pacific accounted for 20% of the market share in 2024, emerging as the fastest-growing region due to rising disposable income and increasing golf participation. Countries like Japan, South Korea, and China are witnessing rapid course development and expanding golf club memberships. Government-backed sports initiatives and growing middle-class interest are boosting accessory sales. Local manufacturers and global brands are also collaborating to launch affordable yet high-quality products. The influence of international tournaments and corporate golf events continues to make the region a vital growth hub for the industry.
Latin America
Latin America captured an 6% share of the global golf accessories market in 2024. Growth is driven by expanding golf tourism and the development of new golf courses in Mexico, Brazil, and Argentina. Regional players are partnering with global brands to introduce premium equipment and apparel. While participation levels remain moderate, increased investments in golf facilities and youth programs are fostering market expansion. Retail stores and online platforms are improving accessibility, and government efforts to promote sports activities are expected to sustain steady growth across the region.
Middle East & Africa
The Middle East & Africa region accounted for 4% of the global market share in 2024, supported by the rising popularity of golf in the UAE, South Africa, and Saudi Arabia. The development of luxury golf resorts and hosting of international tournaments are attracting high-spending tourists. Growing interest among expatriates and regional elites further fuels premium accessory sales. Government investment in sports tourism and urban development projects supports new course openings. Despite climatic challenges, the region continues to gain traction as an emerging golf destination with long-term potential.
Market Segmentations:
By Product Type
- Golf Club
- Golf Balls
- Golf Gear
- Golf Footwear & Apparel
By Distribution Channel
- Retail
- Online
- Specialty stores
- Others
By Price
- Low
- Mid
- High
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
The competitive landscape of the golf accessories market features major players such as Bridgestone Corporation, Wilson Sporting Goods, TaylorMade Golf Company, PING Inc., Yonex Co., Ltd., Mizuno Corporation, SRI Sports Limited (Dunlop, Cleveland, Srixon), Callaway Golf Company, Nike, Inc., and Acushnet Holdings Corporation (Titleist). These companies compete through product innovation, brand recognition, and technological advancements. Leading brands are focusing on lightweight materials, AI-driven swing analytics, and smart golf wearables to enhance player performance. Strategic partnerships with professional golfers and sponsorship of global tournaments strengthen brand visibility. E-commerce expansion and customized product lines are also driving competitiveness. Sustainability initiatives, such as eco-friendly apparel and recyclable packaging, are increasingly shaping corporate strategies. The market remains moderately consolidated, with established brands maintaining dominance through diversified portfolios and strong retail networks, while emerging regional manufacturers focus on affordability and localized designs to capture growing demand.
Key Player Analysis
- Bridgestone Corporation
- Wilson Sporting Goods
- TaylorMade Golf Company
- PING Inc.
- Yonex Co., Ltd.
- Mizuno Corporation
- SRI Sports Limited (Dunlop, Cleveland, Srixon)
- Callaway Golf Company
- Nike, Inc.
- Acushnet Holdings Corporation (Titleist)
Recent Developments
- In January 2025, Callaway announced its 2025 Apparel collection ahead of the PGA Show, highlighting fabric innovation and sustainability.
- In May 2023, the Ladies Professional Golf Association (LPGA) introduced low-cost golf clubs, accessories, and footwear for female beginners and children.
- In January 2023, Callaway Golf, a pioneer in the design, manufacture, and innovation of golf equipment, has unveiled its new Paradym Family of Woods and Irons. crafted for a total performance shift from an unmatched distance, forgiveness, and entirely new product constructions.
Report Coverage
The research report offers an in-depth analysis based on Product Type, Distribution Channel, Price and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Growing youth participation will expand the customer base for golf accessories.
- Integration of AI and smart sensors will enhance gameplay analysis and training accuracy.
- Rising demand for eco-friendly and recycled materials will drive sustainable product launches.
- Expansion of online retail and virtual fitting tools will strengthen digital sales channels.
- Collaborations with professional golfers will boost brand visibility and global outreach.
- Customization of golf clubs, apparel, and footwear will increase consumer loyalty and personalization.
- Development of indoor golf simulators will reduce seasonality and maintain consistent demand.
- Emerging markets in Asia-Pacific and the Middle East will become key growth regions.
- Hybrid and multi-functional accessories will attract both amateur and professional players.
- Increased focus on women’s and youth-specific golf gear will diversify product portfolios and sales.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Golf Accessories market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Golf Accessories market projected to grow between 2025 and 2032?
Which Golf Accessories market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Golf Accessories market?
Who are the leading companies in the Golf Accessories market?
Which region commanded the largest share of the Golf Accessories market in 2024?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue) (Volume Where Applicable)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Golf Accessories Scope – Segments & Subsegments Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 Industry Classification & Applicable Codes
- 1.5 Currency, Measurement Units & Valuation Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Golf Accessories Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 2.79 billion → 2032: USD 3.64 billion)
- 2.1.2 Volume & Revenue – Global Totals (Volume Where Applicable)
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Golf Accessories Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024 (Volume Where Applicable)
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Golf Accessories Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Golf Accessories Market Position in the Broader Industry Value Chain
- 3.1.2 Demand Structure & Purchasing Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Golf Accessories Market Drivers
- 3.3 Golf Accessories Market Restraints & Challenges
- 3.4 Golf Accessories Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Golf Accessories Value Chain Analysis
- 3.6.1 Upstream – Key Inputs, Resources & Suppliers
- 3.6.1.1 Key Input/Resource 1
- 3.6.1.2 Key Input/Resource 2
- 3.6.1.3 Key Input/Resource 3
- 3.6.2 Midstream – Core Operations & Value Creation
- 3.6.2.1 Operating Model & Process Overview
- 3.6.2.2 Key Operating Locations & Capabilities by Company
- 3.6.3 Downstream – Market Channels & End Users
- 3.6.3.1 Direct Sales & Customer Engagement Channels
- 3.6.3.2 Indirect Sales, Intermediaries & Partner Channels
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Key Inputs, Resources & Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Golf Accessories Supply Chain Analysis
- 3.8.1 Critical Input & Resource Availability Risk Assessment
- 3.8.2 Supplier & Operational Concentration Risk (Geographic Exposure)
- 3.8.3 Supply & Service Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Golf Accessories category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Golf Accessories Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Market Size × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute Revenue Growth Through 2032
- 4.3 Incremental Demand Opportunity
- 4.3.1 By Region – Incremental Demand Through 2032
- 4.3.2 Segment – Incremental Demand
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Priority Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Priority market opportunity scorecards reflect the geographic scope and strategic relevance of the study. Listed markets are indicative and may be adapted to the industry.
Chapter 5. Golf Accessories Cross-Border Trade & Market Access Analysis
- 5.1 International Trade & Cross-Border Activity Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024) (Volume Where Applicable)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024) (Volume Where Applicable)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Category 1 (Applicable Classification Code)
- 5.2.2 Category 2 (Applicable Classification Code)
- 5.2.3 Category 3 (Applicable Classification Code)
- 5.2.4 Category 4 (Applicable Classification Code)
- 5.2.5 Category 5 (Applicable Classification Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Category 1 (Applicable Classification Code)
- 5.3.2 Category 2 (Applicable Classification Code)
- 5.3.3 Category 3 (Applicable Classification Code)
- 5.3.4 Category 4 (Applicable Classification Code)
- 5.3.5 Category 5 (Applicable Classification Code)
- 5.4 Cross-Border Pricing & Transaction Benchmarks
- 5.4.1 Export Pricing – Segment & Country
- 5.4.2 Import Pricing – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Cross-Border Trade & Delivery Routes
- 5.5.1 Cross-Border Trade/Delivery Route 1
- 5.5.2 Cross-Border Trade/Delivery Route 2
- 5.5.3 Cross-Border Trade/Delivery Route 3
- 5.5.4 Cross-Border Trade/Delivery Route 4
- 5.5.5 Cross-Border Trade/Delivery Route 5
- 5.6 Trade Policy & Market Access Impact Assessment
- 5.6.1 Tariff & Non-Tariff Barriers
- 5.6.2 Regional Trade & Economic Integration Frameworks
- 5.6.3 Bilateral & Multilateral Trade Agreements
- 5.6.4 Cross-Border Operating, Licensing & Localization Requirements
Note: This chapter applies where cross-border trade or delivery is relevant to Golf Accessories. Goods, services, and digital offerings are assessed using applicable classifications and transaction measures. Import-export volumes, trade balances, and route analyses are included only where meaningful to the market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Golf Accessories Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Leading, Mid-Sized & Emerging Player Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Golf Accessories Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company (Volume Where Applicable)
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 Company Market Share by Key Segment
- 6.2.6 Company Market Share by Customer Group
- 6.3 Operating Scale, Capacity & Infrastructure Analysis
- 6.3.1 Global Operating Scale & Supply Capacity
- 6.3.2 Resource Utilization & Operating Efficiency
- 6.3.3 Output, Service Delivery & Activity Metrics
- 6.3.4 Operating Footprint & Infrastructure Map
- 6.3.5 Planned Operational & Capacity Expansion
- 6.4 Golf Accessories Competitive Benchmarking Matrix
- 6.4.1 Revenue, Growth, Profitability & Operating Metric Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Golf Accessories (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Products, Services & Solutions in Golf Accessories
- 6.5.3 Operational & Infrastructure Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Golf Accessories Market – By Sales & Delivery Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032) (Volume Where Applicable)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share (Volume Where Applicable)
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region (Volume Where Applicable)
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Sales & Delivery Channel
- 8.2.2 By Competitive Positioning & Price Tier
Chapter 9. North America Golf Accessories Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Golf Accessories Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Golf Accessories Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Golf Accessories Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Golf Accessories Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Golf Accessories Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Golf Accessories Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Supply, Output & Operating Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Demand, Adoption & Usage Assumptions
- Appendix F – Pricing & Revenue Metric Reference Tables
- Appendix G – Company Operations & Infrastructure Database
- Appendix H – Cross-Border Trade & Activity Data Tables (Where Applicable)
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
