
Market Overview:
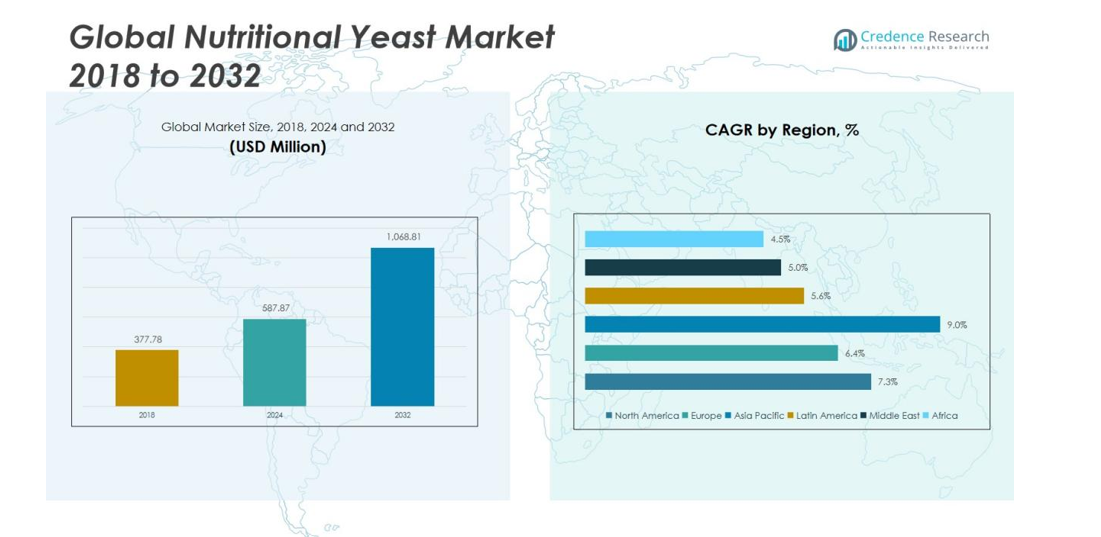
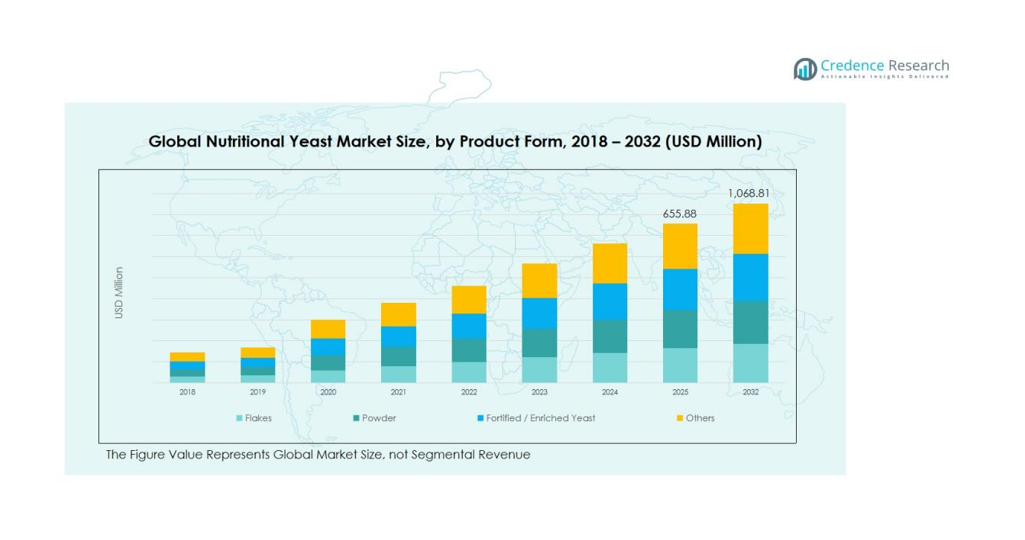
The Global Nutritional Yeast Market size was valued at USD 377.78 million in 2018 to USD 587.87 million in 2024 and is anticipated to reach USD 1,068.81 million by 2032, at a CAGR of 7.23% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Nutritional Yeast Market Size 2024 | USD 587.87 million |
| Nutritional Yeast Market, CAGR | 7.23% |
| Nutritional Yeast Market Size 2032 | USD 1,068.81 million |
Rising demand for clean-label and natural ingredients across the food and beverage sector supports market expansion. Consumers are seeking nutrient-rich, non-GMO, and gluten-free products that promote overall wellness, immunity, and digestive health. Increasing innovation in fortified products and the growing inclusion of nutritional yeast in sports nutrition and dietary supplements further contribute to market growth.
Regionally, North America holds the largest share due to a strong vegan population base and widespread product awareness. Europe follows closely, driven by sustainability-focused consumers and established food processing industries. The Asia Pacific region is expected to record the fastest growth, supported by expanding health-conscious consumer segments and increased adoption of Western dietary trends in China, India, and Japan.
Market Insights:
- The Global Nutritional Yeast Market was valued at USD 377.78 million in 2018, reaching USD 587.87 million in 2024, and is projected to achieve USD 1,068.81 million by 2032, expanding at a CAGR of 7.23% during the forecast period.
- North America leads the market with a 35% share in 2024, supported by a strong vegan population, established food processing infrastructure, and widespread product awareness. Europe follows with a 28% share, driven by sustainability-oriented consumers and strict food labeling standards.
- Asia Pacific accounts for 22% of the market and represents the fastest-growing region, supported by rising disposable incomes, increasing urbanization, and growing adoption of plant-based nutrition across China, Japan, and India.
- By product form, flakes hold the largest share at 46% due to high preference in vegan dishes, snacks, and sauces. Powder accounts for 34% of global volume, supported by growing applications in fortified beverages, supplements, and clean-label seasonings.
- The market’s overall expansion is supported by rising demand for clean-label, non-GMO, and gluten-free food products that promote immunity and digestive health.
Market Drivers:
Rising Adoption of Plant-Based and Vegan Diets
The Global Nutritional Yeast Market is experiencing strong growth due to increasing adoption of plant-based and vegan diets worldwide. Consumers are shifting from animal-based proteins to nutrient-rich alternatives, and nutritional yeast has become a preferred choice for its natural umami flavor and protein content. It serves as an ideal replacement for cheese in vegan dishes while providing essential amino acids and B vitamins. Growing awareness of ethical eating and sustainable food production further boosts its use across retail and foodservice sectors.
- For instance, YESTEIN® yeast protein, derived from fermentation of Baker’s yeast, contains 80% protein and delivers a PDCAAS of 1.0, making it a highly effective vegan protein source supporting muscle recovery and strength enhancement in adults.
Increasing Demand for Fortified and Functional Foods
Demand for fortified and functional foods continues to drive the market’s expansion. Nutritional yeast is rich in vitamins, minerals, and antioxidants that support immunity, energy, and gut health. Food manufacturers are increasingly incorporating it into snacks, dairy alternatives, and beverages to enhance nutritional profiles. Rising consumer interest in health-centric diets and preventive nutrition has made fortified products a mainstream trend, strengthening the market’s overall growth outlook.
- For instance, Bragg Nutritional Yeast Seasoning delivers 630% of the daily B12 requirement per two-tablespoon serving, addressing critical nutrient gaps for consumers following plant-based diets
Expansion of Clean-Label and Non-GMO Product Lines
Growing preference for clean-label and non-GMO foods is another key factor propelling market growth. Consumers seek transparent ingredient lists and naturally derived additives without artificial chemicals or allergens. Nutritional yeast aligns well with these preferences due to its natural fermentation process and minimal processing. It is gaining popularity among manufacturers promoting healthy, traceable, and sustainable ingredients.
Increasing Applications in Dietary Supplements and Sports Nutrition
Expanding applications across dietary supplements and sports nutrition continue to shape market growth. Nutritional yeast provides high-quality protein, B-complex vitamins, and minerals essential for active lifestyles. It supports energy metabolism and recovery, making it valuable for athletes and fitness enthusiasts. Rising awareness of nutritional supplementation, coupled with e-commerce-driven product availability, continues to enhance the market’s penetration across multiple consumer groups.
Market Trends:
Rising Integration of Nutritional Yeast in Functional and Alternative Food Products
The Global Nutritional Yeast Market is witnessing rapid integration of yeast-based ingredients into functional and alternative food categories. It is being used in plant-based cheese, sauces, soups, and bakery formulations for its nutty, savory flavor and high nutritional profile. Food manufacturers are developing innovative formulations that combine nutritional yeast with legumes, grains, and seeds to enhance protein density. Demand from consumers seeking fortified and allergen-free foods has encouraged brands to diversify product portfolios with nutritional yeast-based variants. The rise of flexitarian diets and growing attention to natural protein sources are expanding its appeal across mainstream food categories. The trend aligns with the industry’s focus on delivering both taste and nutrition through clean-label formulations that support wellness and sustainability goals.
- For Instance, NOW Foods' Nutritional Yeast Powder is a fortified, gluten-free, and non-GMO product with a high B-vitamin content, available on the market for some time, not a new release in August 2025.
Technological Advancements and Product Innovation in Nutritional Yeast Production
Ongoing technological advancements in fermentation and drying processes are transforming product quality and application versatility. Manufacturers are investing in improved strains of Saccharomyces cerevisiae to increase nutrient content and flavor consistency. It supports the production of vitamin B12-enriched and low-sodium variants that cater to specific health requirements. The expansion of organic-certified and gluten-free offerings is reinforcing consumer confidence in yeast-derived products. Strategic collaborations between ingredient developers and food companies are accelerating innovation in seasoning blends, ready-to-eat meals, and dietary supplements. Continuous R&D investments and scalable production facilities are expected to enhance cost efficiency and broaden the application base of nutritional yeast across global markets.
- For instance, Angel Yeast completed a new industrial yeast protein production facility at Baiyang Yichang in 2025, achieving a breakthrough that reduces protein extraction time to hours and enables production of 11,000 tons of high-quality yeast protein annually.
Market Challenges Analysis:
High Production Costs and Limited Supply Chain Efficiency
The Global Nutritional Yeast Market faces challenges due to high production and processing costs. Nutritional yeast requires controlled fermentation conditions and specialized equipment, increasing manufacturing expenses. It also depends on reliable sourcing of molasses and other raw materials, which fluctuate in price due to agricultural variability. Limited production capacity in certain regions restricts large-scale supply and impacts pricing stability. It becomes difficult for small and mid-sized manufacturers to maintain cost competitiveness in a market dominated by established players. Supply chain inefficiencies and high logistics costs further limit accessibility in developing economies.
Consumer Awareness Gaps and Market Penetration Barriers
Limited awareness about nutritional yeast among mainstream consumers continues to hinder market penetration. Many consumers remain unfamiliar with its benefits, taste, and culinary applications, particularly in emerging regions. It also faces misconceptions related to yeast allergies and over-processing, affecting adoption in certain markets. Retail visibility remains low compared to traditional protein and supplement products. Manufacturers need targeted marketing strategies and product education to increase acceptance among new consumers. Expanding distribution through online platforms and supermarkets can improve accessibility and encourage trial among health-conscious buyers.
Market Opportunities:
Growing Opportunities in Functional Foods and Nutraceutical Formulations
The Global Nutritional Yeast Market presents strong growth opportunities through its expanding use in functional foods and nutraceutical formulations. Rising consumer focus on preventive health and natural supplementation is creating demand for yeast-based protein and vitamin sources. It serves as a clean, natural ingredient ideal for fortifying snacks, beverages, and ready meals. Manufacturers are introducing vitamin B12-enriched and low-sodium variants to cater to health-conscious consumers. The integration of nutritional yeast into dietary supplements and meal replacements supports the global shift toward personalized nutrition. Expanding applications in gut health and immune-boosting products are expected to strengthen its long-term market potential.
Expansion Across Emerging Economies and E-Commerce Platforms
Emerging economies present vast untapped potential for nutritional yeast manufacturers. Rising disposable income, growing awareness of plant-based nutrition, and increasing vegan populations in Asia-Pacific, Latin America, and the Middle East create new avenues for market entry. It benefits from the rapid expansion of e-commerce and digital health platforms, which enable global access and product visibility. Online retailers are promoting diverse formulations, improving consumer reach and brand recognition. Strategic localization and affordable product lines can help brands penetrate new demographic segments. Strengthened retail infrastructure and digital marketing are expected to accelerate adoption across developing markets.
Market Segmentation Analysis:
By Product Form
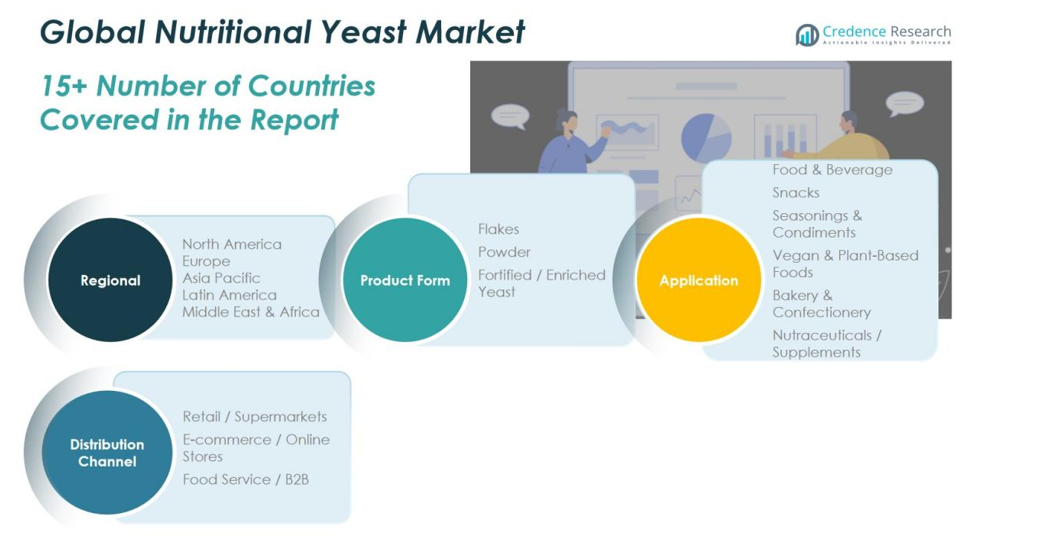
The Global Nutritional Yeast Market is segmented into flakes, powder, and fortified/enriched yeast. Flakes hold the largest share due to their wide use in vegan recipes, snacks, and sauces for their cheesy flavor and easy blending properties. It is preferred by consumers seeking convenient, ready-to-use nutritional toppings. Powder form follows, driven by its application in beverages, soups, and dietary supplements. Fortified or enriched yeast is gaining popularity for its vitamin B12 and mineral content, appealing to health-conscious consumers seeking added nutritional value.
- For instance, NOW Foods offers nutritional yeast powder containing 5 grams of protein per serving, specifically formulated for integration into protein shakes and vegetable juices.
By Application
The market is classified into food and beverage, snacks, seasonings and condiments, vegan and plant-based foods, bakery and confectionery, and nutraceuticals or supplements. Vegan and plant-based foods dominate due to rising adoption of alternative protein sources. It is also witnessing strong demand in snacks and condiments, supported by flavor innovation and functional benefits. The nutraceutical segment is expanding rapidly, driven by growing awareness of preventive health and immunity support.
- For Instance, Good Catch Foods offers plant-based tuna in a 3-ounce (85-gram) pouch, with its "Naked in Water" variety containing 14–17 grams of protein, depending on the product run.
By Distribution Channel
The market is divided into retail/supermarkets, e-commerce/online stores, and food service/B2B. Retail outlets remain the leading channel due to product visibility and consumer trust in established brands. E-commerce is growing quickly due to convenience and a broader product range. Food service distribution is strengthening through increasing adoption of nutritional yeast in commercial kitchens and restaurants.
Segmentations:
By Product Form:
- Flakes
- Powder
- Fortified / Enriched Yeast
By Application:
- Food & Beverage
- Snacks
- Seasonings & Condiments
- Vegan & Plant-Based Foods
- Bakery & Confectionery
- Nutraceuticals / Supplements
By Distribution Channel:
- Retail / Supermarkets
- E-commerce / Online Stores
- Food Service / B2B
By Region:
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis:
North America
The North America Nutritional Yeast Market size was valued at USD 168.16 million in 2018 to USD 259.01 million in 2024 and is anticipated to reach USD 472.19 million by 2032, at a CAGR of 7.3% during the forecast period. The Global Nutritional Yeast Market Market is led by North America, holding a 35% revenue share in 2024. Strong adoption of vegan and plant-based diets drives product demand across the United States and Canada. It benefits from a well-established food processing sector, advanced distribution networks, and consumer preference for fortified foods. Major manufacturers continue to innovate through fortified blends and clean-label offerings. Growing awareness about gut health and nutritional supplementation further strengthens regional sales.
Europe
The Europe Nutritional Yeast Market size was valued at USD 108.13 million in 2018 to USD 162.26 million in 2024 and is anticipated to reach USD 277.90 million by 2032, at a CAGR of 6.4% during the forecast period. Europe accounts for about 28% of the Global Nutritional Yeast Market Market, supported by strong vegan populations and sustainability-driven consumers. It benefits from strict food labeling regulations and demand for non-GMO, allergen-free ingredients. Rising interest in fortified snacks, bakery items, and condiments is fueling product diversification. The UK, Germany, and France lead market growth through active innovation in functional foods. Regional producers are focusing on eco-friendly production and sourcing to align with EU sustainability goals.
Asia Pacific
The Asia Pacific Nutritional Yeast Market size was valued at USD 66.62 million in 2018 to USD 113.15 million in 2024 and is anticipated to reach USD 235.27 million by 2032, at a CAGR of 9.0% during the forecast period. Asia Pacific holds a 22% share of the Global Nutritional Yeast Market Market and is the fastest-growing region. It is driven by a rising middle-class population, urbanization, and growing awareness of plant-based nutrition. Increasing demand for fortified foods and health supplements in China, Japan, and India supports strong market performance. The expanding e-commerce sector and digital health platforms enhance consumer access. Regional manufacturers are investing in scalable production and product localization to meet diverse taste preferences.
Latin America
The Latin America Nutritional Yeast Market size was valued at USD 17.55 million in 2018 to USD 26.96 million in 2024 and is anticipated to reach USD 43.29 million by 2032, at a CAGR of 5.6% during the forecast period. Latin America represents nearly 7% of the Global Nutritional Yeast Market Market, supported by rising health awareness and a gradual shift toward vegetarian food choices. Brazil and Argentina lead demand due to a growing food manufacturing base and expanding retail networks. It is witnessing increased adoption in functional snacks, bakery, and sports nutrition. Local producers are emphasizing affordable fortified products to attract urban consumers. The growth of health-focused retail and organic stores further enhances market visibility.
Middle East
The Middle East Nutritional Yeast Market size was valued at USD 10.71 million in 2018 to USD 15.25 million in 2024 and is anticipated to reach USD 23.45 million by 2032, at a CAGR of 5.0% during the forecast period. The region holds a 5% share of the Global Nutritional Yeast Market Market, supported by increasing demand for fortified and functional food products. The UAE and Saudi Arabia are leading adopters due to rapid dietary transitions and strong retail infrastructure. It benefits from a growing population of health-conscious and vegan consumers. Local distributors are expanding their portfolios to include premium nutritional yeast blends. Rising awareness through online channels and food expos is improving product reach across the region.
Africa
The Africa Nutritional Yeast Market size was valued at USD 6.61 million in 2018 to USD 11.24 million in 2024 and is anticipated to reach USD 16.72 million by 2032, at a CAGR of 4.5% during the forecast period. Africa accounts for nearly 3% of the Global Nutritional Yeast Market Market and shows steady growth due to increasing interest in nutrition and wellness products. South Africa remains the leading market, followed by Egypt and Nigeria. It faces challenges in consumer awareness and distribution, but rising urban incomes support gradual market expansion. Regional producers are focusing on affordable product lines and education-based marketing. Strengthening supply chains and e-commerce penetration are expected to improve long-term growth prospects.
Key Player Analysis:
- Lesaffre Group
- Angel Yeast Co., Ltd.
- AB Mauri (Associated British Foods)
- Red Star Yeast Company
- Ohly GmbH
Competitive Analysis:
The Global Nutritional Yeast Market is characterized by moderate consolidation with key players such as Lesaffre Group, Angel Yeast Co., Ltd., AB Mauri (Associated British Foods), Red Star Yeast Company, and Ohly GmbH dominating global production and innovation. These companies account for a major portion of the total market revenue, driven by strong brand presence and diversified product portfolios. It benefits from strategic partnerships, technological advancements in fermentation, and product enrichment initiatives. Lesaffre Group and Angel Yeast Co., Ltd. focus on expanding fortified and organic-certified product lines, while AB Mauri leverages its extensive distribution network across food and bakery industries. Red Star Yeast Company and Ohly GmbH emphasize clean-label formulations and high-protein nutritional applications. Continuous product innovation and regional expansion remain key competitive strategies enhancing market reach and consumer loyalty.
Recent Developments:
- In October 2025, Gnosis by Lesaffre announced the launch of its new master brand identity “Think like Nature,” which will debut at SupplySide Global 2025 in Las Vegas, focusing on uniting various product brands for health innovation through fermentation.
- In October 2025, Lesaffre and ENGIE Solutions inaugurated a heat recovery unit at Lesaffre’s historic plant in Marcq-en-Barœul, France, to advance their shared carbon reduction goals.
Report Coverage:
The research report offers an in-depth analysis based on Product Form, Application, Distribution Channel and Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- The Global Nutritional Yeast Market is expected to witness strong expansion driven by increasing global demand for plant-based and functional foods.
- It will experience rising adoption in fortified snacks, vegan cheese, and clean-label condiments.
- Manufacturers will focus on organic-certified and vitamin-enriched variants to attract health-conscious consumers.
- Expansion of retail and e-commerce channels will improve global accessibility and brand visibility.
- Technological advances in fermentation will enhance nutrient content and production efficiency.
- Strategic partnerships between food producers and ingredient suppliers will accelerate innovation in new applications.
- Asia Pacific will continue to lead growth due to rising disposable incomes and lifestyle changes.
- North America and Europe will maintain dominance supported by established vegan and sustainable food markets.
- The nutraceutical and dietary supplement sectors will provide high-margin opportunities for yeast-based formulations.
- Growing awareness of nutritional yeast’s benefits for immunity and metabolism will sustain long-term market demand.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the projected growth of the Nutritional Yeast Market?
At what CAGR is the Global Nutritional Yeast Market expected to grow between 2024 and 2032?
What is driving the demand for nutritional yeast?
What are the health benefits of nutritional yeast?
Which regions are leading the nutritional yeast market?
How is the market expanding in Asia and other regions?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue) (Volume Where Applicable)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Nutritional Yeast Scope – Segments & Subsegments Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2018; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 Industry Classification & Applicable Codes
- 1.5 Currency, Measurement Units & Valuation Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Nutritional Yeast Market Snapshot
- 2.1.1 Market Size – Historical (2018) & Forecast (2018-2032) (2018: USD 377.78 million → 2032: USD 1,068.81 million)
- 2.1.2 Volume & Revenue – Global Totals (Volume Where Applicable)
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Nutritional Yeast Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2018 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2018
- 2.3.2 Top 10 Players by Volume Share – 2018 (Volume Where Applicable)
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Nutritional Yeast Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Nutritional Yeast Market Position in the Broader Industry Value Chain
- 3.1.2 Demand Structure & Purchasing Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Nutritional Yeast Market Drivers
- 3.3 Nutritional Yeast Market Restraints & Challenges
- 3.4 Nutritional Yeast Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Nutritional Yeast Value Chain Analysis
- 3.6.1 Upstream – Key Inputs, Resources & Suppliers
- 3.6.1.1 Key Input/Resource 1
- 3.6.1.2 Key Input/Resource 2
- 3.6.1.3 Key Input/Resource 3
- 3.6.2 Midstream – Core Operations & Value Creation
- 3.6.2.1 Operating Model & Process Overview
- 3.6.2.2 Key Operating Locations & Capabilities by Company
- 3.6.3 Downstream – Market Channels & End Users
- 3.6.3.1 Direct Sales & Customer Engagement Channels
- 3.6.3.2 Indirect Sales, Intermediaries & Partner Channels
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Key Inputs, Resources & Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Nutritional Yeast Supply Chain Analysis
- 3.8.1 Critical Input & Resource Availability Risk Assessment
- 3.8.2 Supplier & Operational Concentration Risk (Geographic Exposure)
- 3.8.3 Supply & Service Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Nutritional Yeast category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Nutritional Yeast Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Market Size × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute Revenue Growth Through 2032
- 4.3 Incremental Demand Opportunity
- 4.3.1 By Region – Incremental Demand Through 2032
- 4.3.2 Segment – Incremental Demand
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Priority Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Priority market opportunity scorecards reflect the geographic scope and strategic relevance of the study. Listed markets are indicative and may be adapted to the industry.
Chapter 5. Nutritional Yeast Cross-Border Trade & Market Access Analysis
- 5.1 International Trade & Cross-Border Activity Overview
- 5.1.1 Global Export Value by Country (2018)
- 5.1.2 Global Export Volume by Country (2018) (Volume Where Applicable)
- 5.1.3 Global Import Value by Country (2018)
- 5.1.4 Global Import Volume by Country (2018) (Volume Where Applicable)
- 5.1.5 Net Trade Balance by Country (2018)
- 5.2 Export Analysis – Segment
- 5.2.1 Category 1 (Applicable Classification Code)
- 5.2.2 Category 2 (Applicable Classification Code)
- 5.2.3 Category 3 (Applicable Classification Code)
- 5.2.4 Category 4 (Applicable Classification Code)
- 5.2.5 Category 5 (Applicable Classification Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Category 1 (Applicable Classification Code)
- 5.3.2 Category 2 (Applicable Classification Code)
- 5.3.3 Category 3 (Applicable Classification Code)
- 5.3.4 Category 4 (Applicable Classification Code)
- 5.3.5 Category 5 (Applicable Classification Code)
- 5.4 Cross-Border Pricing & Transaction Benchmarks
- 5.4.1 Export Pricing – Segment & Country
- 5.4.2 Import Pricing – Segment & Source Country
- 5.4.3 Price Trends (2018)
- 5.5 Key Cross-Border Trade & Delivery Routes
- 5.5.1 Cross-Border Trade/Delivery Route 1
- 5.5.2 Cross-Border Trade/Delivery Route 2
- 5.5.3 Cross-Border Trade/Delivery Route 3
- 5.5.4 Cross-Border Trade/Delivery Route 4
- 5.5.5 Cross-Border Trade/Delivery Route 5
- 5.6 Trade Policy & Market Access Impact Assessment
- 5.6.1 Tariff & Non-Tariff Barriers
- 5.6.2 Regional Trade & Economic Integration Frameworks
- 5.6.3 Bilateral & Multilateral Trade Agreements
- 5.6.4 Cross-Border Operating, Licensing & Localization Requirements
Note: This chapter applies where cross-border trade or delivery is relevant to Nutritional Yeast. Goods, services, and digital offerings are assessed using applicable classifications and transaction measures. Import-export volumes, trade balances, and route analyses are included only where meaningful to the market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Nutritional Yeast Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2018
- 6.1.2 Leading, Mid-Sized & Emerging Player Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Nutritional Yeast Market Share Analysis – 2018
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company (Volume Where Applicable)
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2018)
- 6.2.5 Company Market Share by Key Segment
- 6.2.6 Company Market Share by Customer Group
- 6.3 Operating Scale, Capacity & Infrastructure Analysis
- 6.3.1 Global Operating Scale & Supply Capacity
- 6.3.2 Resource Utilization & Operating Efficiency
- 6.3.3 Output, Service Delivery & Activity Metrics
- 6.3.4 Operating Footprint & Infrastructure Map
- 6.3.5 Planned Operational & Capacity Expansion
- 6.4 Nutritional Yeast Competitive Benchmarking Matrix
- 6.4.1 Revenue, Growth, Profitability & Operating Metric Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Nutritional Yeast (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Products, Services & Solutions in Nutritional Yeast
- 6.5.3 Operational & Infrastructure Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Nutritional Yeast Market – By Sales & Delivery Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2018 & 2032) (Volume Where Applicable)
- 7.1.2 Channel Mix Evolution (2018-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share (Volume Where Applicable)
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region (Volume Where Applicable)
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Sales & Delivery Channel
- 8.2.2 By Competitive Positioning & Price Tier
Chapter 9. North America Nutritional Yeast Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Nutritional Yeast Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Nutritional Yeast Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Nutritional Yeast Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Nutritional Yeast Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Nutritional Yeast Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Nutritional Yeast Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Supply, Output & Operating Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Demand, Adoption & Usage Assumptions
- Appendix F – Pricing & Revenue Metric Reference Tables
- Appendix G – Company Operations & Infrastructure Database
- Appendix H – Cross-Border Trade & Activity Data Tables (Where Applicable)
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
