
Personal Care Aid Market Overview:
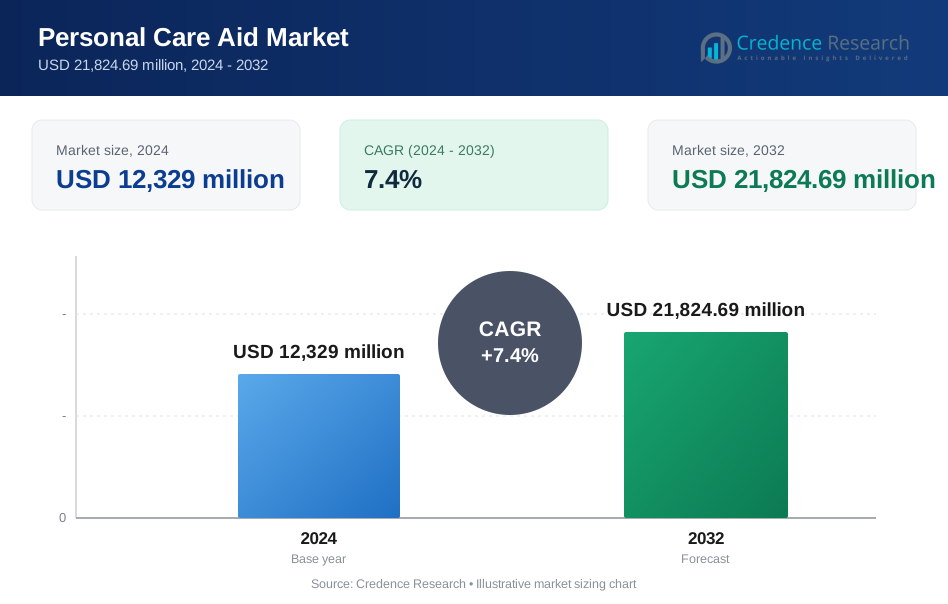
The Personal Care Aid market size was valued at USD 12,329 million in 2024 and is anticipated to reach USD 21,824.69 million by 2032, at a CAGR of 7.4% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Personal Care Aid Market Size 2024 | USD 12,329 million |
| Personal Care Aid Market, CAGR | 7.4% |
| Personal Care Aid Market Size 2032 | USD 21,824.69 million |
Personal Care Aid Market Insights
- Rising awareness of skincare, hygiene, and grooming across all age groups is driving consistent product demand, especially in creams, lotions, and shampoos, which dominate by product segment.
- Consumers increasingly prefer clean-label, organic, and personalized personal care solutions, with e-commerce and influencer-led marketing accelerating product discovery and engagement.
- High competition from global and regional brands creates pricing pressure and brand saturation, while strict regulatory norms across countries increase compliance costs.
- Asia-Pacific leads with a 30% market share, followed by North America at 28% and Europe at 24%, while skincare remains the dominant segment with over 30% share, supported by high demand for moisturizers, serums, and anti-aging products.
Personal Care Aid Market Segmentation Analysis:
By Product Type
Skincare dominates the personal care aid market, holding over 30% revenue share in 2024. Creams and lotions lead this segment, driven by rising demand for daily moisturization and anti-aging formulations. Serums and face masks gain traction due to their targeted benefits and premium positioning. Body care products also see strong adoption, especially soaps and shower gels, fueled by hygiene awareness and fragrance-based choices. In hair care, shampoos hold the largest share, supported by high consumption frequency and expanding dandruff, anti-hair fall, and color-protection lines. Oral care maintains steady growth with toothpaste as the top-selling product, aided by whitening and herbal variants.
- For instance, L'Oréal’s Revitalift Laser X3 cream includes 3% Pro-Xylane and hyaluronic acid, enhancing visible skin firmness and hydration.
By Skin Type
Normal skin leads the personal care aid market by skin type, accounting for over 35% market share. This segment benefits from universal product compatibility and broader availability across categories. Dry skin follows closely, driven by demand for deep hydration products, particularly during winter months and in arid regions. Sensitive skin segment is expanding steadily, influenced by increasing skin conditions and preference for mild, dermatologist-tested formulations. Combination skin products show consistent demand due to tailored offerings that address varied skin needs. Brands invest in labelling and R&D to create differentiated solutions for each skin category, boosting consumer confidence.
- For instance, Cetaphil Gentle Skin Cleanser is clinically proven to maintain pH balance and has been trusted for over 75 years with over 40 million bottles sold annually.
By Consumer Orientation
Women represent the largest consumer base in the personal care aid market, contributing more than 60% of the overall market share. This dominance stems from higher spending on skincare, cosmetics, and hair care essentials. Men’s segment records fast-paced growth, propelled by increasing grooming awareness and specialized offerings in beard care, fragrances, and anti-aging products. The kids’ segment sees consistent demand, especially for tear-free, gentle products across body, hair, and oral care, backed by parental concerns for safety and dermatological certification. Gender-specific branding, influencer marketing, and expanding retail presence continue to shape demand trends in all consumer groups.
Key Growth Drivers
Rising Health and Grooming Awareness Among Consumers
The global rise in health, hygiene, and grooming awareness continues to fuel demand in the personal care aid market. Consumers, especially in urban regions, increasingly prioritize skincare, haircare, and oral hygiene routines as part of their daily wellness regimen. Social media platforms, beauty influencers, and wellness blogs have made personal care trends highly visible and aspirational, pushing younger consumers to invest more in products like serums, masks, and grooming essentials. Men’s grooming is also gaining traction, with growing acceptance of skincare and beard care routines. Additionally, changing lifestyle patterns, rising disposable income, and demand for anti-aging and pollution-protection products further contribute to market expansion. As self-care becomes more mainstream, brands are witnessing higher product uptake across categories.
- For instance, Unilever’s Dove Real Beauty campaign generated 787 million impressions across digital platforms in 2025, strengthening brand visibility.
Expansion of E-commerce and Direct-to-Consumer (DTC) Channels
The shift toward online shopping and DTC channels is a significant driver in the personal care aid market. Consumers increasingly prefer digital platforms due to convenience, wider product availability, price comparison, and access to reviews. Major brands and startups alike are investing in omnichannel strategies, enhancing customer experience with personalized recommendations and seamless logistics. E-commerce enables deeper market penetration, especially in tier-2 and tier-3 cities, where brick-and-mortar stores may be limited. Subscription models, influencer-driven campaigns, and exclusive online launches create urgency and loyalty among buyers. The growth of beauty tech, AI-based skin diagnostics, and virtual try-on features further drive consumer engagement and product discovery in the online space, contributing to robust sales growth across demographics.
- For instance, Sephora’s Virtual Artist continues to be a key engagement feature, boosting digital discovery across thousands of products.
Increased Focus on Clean, Sustainable, and Natural Products
Demand for clean-label, organic, and sustainable personal care products is on the rise. Consumers are actively scrutinizing ingredient lists, seeking products free from parabens, sulfates, and synthetic fragrances. This shift is driven by growing health consciousness, concerns over skin sensitivity, and a broader push toward environmental sustainability. Brands offering cruelty-free, vegan, biodegradable, and plastic-free packaging are gaining favor. Natural oils, herbal extracts, and plant-based actives are increasingly used in formulations across skincare, haircare, and oral care. Regulatory support for safer ingredients and eco-friendly labeling further reinforces this movement. The clean beauty segment, once niche, has now become mainstream, with both premium and mass-market players launching green product lines to capture eco-aware consumers.
Key Trends & Opportunities
Personalization and Technological Integration in Product Development
Technological innovation and data-driven personalization are transforming the personal care aid landscape. Consumers now demand tailored solutions based on skin type, tone, hair condition, or specific concerns. Brands leverage AI, skin analysis tools, and genetic profiling to offer hyper-personalized product recommendations. Smart devices like facial cleansing brushes, hair analyzers, and app-linked diagnostic tools enhance user experience and product efficacy. Customizable formulations where users select ingredients based on individual needs are gaining popularity. This trend opens opportunities for niche players and DTC brands to differentiate in a crowded market. It also supports premiumization, as personalized products command higher pricing and build long-term consumer loyalty.
- For instance, L’Oréal’s Perso device uses AI to formulate personalized skincare blends in real time based on skin condition data captured by the user.
Growth in Men’s Grooming and Gender-Neutral Products
Men’s grooming is evolving rapidly, no longer limited to basic hygiene products. Demand for face cleansers, anti-aging creams, beard oils, and fragrances has grown, fueled by shifting cultural norms and expanding marketing efforts. Influencer campaigns and sports endorsements have played a role in normalizing skincare for men. At the same time, the market is witnessing rising demand for gender-neutral products that appeal to all users regardless of identity. These products often emphasize skin type or function over targeted gender marketing. This inclusive approach attracts Gen Z and younger millennials, who value diversity, expression, and authenticity in brand messaging offering significant room for future growth.
Key Challenges
Intense Market Competition and Brand Saturation
The personal care aid market faces intense competition due to the presence of numerous global, regional, and DTC brands. New entrants frequently disrupt the market with aggressive pricing, influencer campaigns, and niche positioning. Established brands struggle to maintain loyalty amid changing consumer preferences and product overload. The constant influx of new products-especially in skincare and cosmetics-can lead to consumer fatigue and higher churn rates. Price wars and imitation products also dilute value perception. To maintain share, brands must continually innovate, invest in marketing, and differentiate on performance, sustainability, or personalization, which increases operational complexity and cost.
Regulatory and Compliance Barriers Across Regions
Navigating regulatory frameworks poses a challenge for companies operating in multiple markets. Different regions have varied standards for permissible ingredients, labeling, testing, and environmental claims. For instance, while certain preservatives or chemicals are acceptable in the U.S., they may be banned in the EU or require disclosure in Asia. Complying with safety, allergen, and organic certification standards adds time and cost to product development. Misinformation and rising consumer activism have also forced brands to invest more in transparency and traceability. Non-compliance can lead to fines, product recalls, or brand reputation damage, making regulatory agility a critical concern in cross-border operations.
Regional Analysis
North America
North America holds a market share of over 28% in 2024, driven by high consumer spending on skincare, haircare, and grooming products. The U.S. leads the region with a strong preference for premium, anti-aging, and clean-label formulations. Personalization, e-commerce, and brand loyalty programs support sustained demand. Growth in men's grooming and gender-neutral categories adds further momentum. Canada contributes with rising demand for natural and organic products. Brands leverage digital tools and influencer-led marketing to target niche segments. High disposable income and awareness of product safety regulations reinforce North America's dominant position in the global market.
Europe
Europe accounts for approximately 24% of the global personal care aid market, supported by a mature beauty and wellness culture. Countries like Germany, France, and the UK drive regional sales with strong demand for organic and dermatologically tested products. Regulatory emphasis on clean and sustainable formulations pushes innovation in eco-friendly packaging and green ingredients. Growth in male grooming, aging population skincare, and functional cosmetics drives product diversification. The region also sees steady uptake in DTC and e-commerce models. Local brands maintain strong footholds, while global companies cater to evolving ethical and environmental consumer values.
Asia-Pacific
Asia-Pacific leads in growth rate and captures nearly 30% of the global market share in 2024. Rapid urbanization, rising disposable income, and beauty-conscious millennials drive product uptake across categories. China, Japan, South Korea, and India dominate the region with increasing demand for skincare, haircare, and cosmetics. K-beauty and J-beauty trends heavily influence product development globally. E-commerce penetration, social media engagement, and innovation in formulations support rapid growth. Personalization, SPF-infused skincare, and herbal products are in high demand. Local and global brands invest heavily in R&D and marketing to gain a competitive edge in this dynamic market.
Latin America
Latin America holds about 8% of the global personal care aid market, with Brazil and Mexico as key contributors. The market benefits from rising awareness of skincare and hygiene, along with expanding retail and online channels. Fragrances, body care, and hair care dominate regional preferences. Economic fluctuations pose challenges, but premiumization and clean-label trends are gaining attention. Consumer interest in plant-based, herbal, and dermatologist-recommended products is rising. Beauty routines influenced by cultural factors drive demand for region-specific product lines. Local players and multinationals compete by offering affordable innovations tailored to the middle-income population.
Middle East & Africa (MEA)
The MEA region contributes roughly 5% to the global personal care aid market. Demand is led by countries such as the UAE, Saudi Arabia, and South Africa, where consumers increasingly adopt global beauty and grooming standards. Fragrances, skincare, and halal-certified cosmetics dominate sales. Urbanization, tourism, and the influence of Western beauty standards are key drivers. Product preferences lean toward luxury, natural, and sensitive-skin-friendly items. Regional brands focus on local climate needs and religious compliance, while international players invest in expanding retail partnerships and e-commerce infrastructure to tap into growing consumer segments.
Personal Care Aid Market Segmentations:
By Product Type:
- Skincare
- Creams and Lotions
- Serums
- Face Packs or Masks
- Cleansers
- Other Skincare Products
- Body Care
- Soaps
- Shower Gels
- Creams
- Oils
- Hair Care
- Shampoos
- Conditioners
- Hair Dyes
- Hair Oils
- Other Haircare Products
- Oral Care
- Toothpaste
- Mouthwash
- Tooth Powder
- Cosmetics
- Facial Products
- Eye Products
- Lip Products
- Nail Products
- Fragrances and Deodorants
By Skin Type:
- Dry Skin
- Normal Skin
- Sensitive Skin
- Combination Skin
By Consumer Orientation:
- Women
- Men
- Kids
By Distribution Channel:
- Modern Trade
- Departmental Stores
- Convenience Stores
- Specialty Stores
- Mono Brand Store
- Online Retailers
- Direct to Consumer
- Third-party to Consumer
- Other Sales Channel
By Geography:
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
The personal care aid market features intense competition with a mix of global conglomerates and niche regional players. Leading companies such as Procter & Gamble, LVMH, Estée Lauder, and Johnson & Johnson dominate through broad product portfolios, strong brand equity, and global distribution networks. These firms consistently invest in R&D, marketing, and product innovation to maintain consumer engagement and expand market share. Emerging players and DTC brands focus on clean-label, organic, and personalized offerings to capture younger demographics. Digital channels, influencer partnerships, and subscription models are key strategies to build customer loyalty. Mergers, acquisitions, and collaborations also shape the competitive dynamics, enabling market leaders to expand into untapped segments or geographies. Product differentiation, pricing strategies, and sustainable practices continue to drive brand positioning. Regional firms gain traction by addressing local skin types, cultural preferences, and ingredient familiarity. Overall, the landscape remains highly dynamic, with innovation and responsiveness being critical for long-term growth.
Key Player Analysis
- Revlon Inc.
- Johnson and Johnson
- Mary Kay Cosmetics
- Coty Inc.
- LVMH (Moët Hennessy - Louis Vuitton)
- Estee Lauder Companies Inc.
- Kao Corporation
- MAC Cosmetics
- Procter and Gamble Co.
- Clarins Group
- Chanel S.A.
- Laverana GmbH and Co. KG
Recent Developments
- In April 2024, Naples Soap Company received the 'Visual Impact Award' from NJPEC for its custom gift box, the Birthday Box, featuring natural, fruity-scented skin care products and festive birthday-themed items.
- In April 2024, Kroger, the fourth largest retailer in the United States, started exclusively carrying MCoBeauty in its United States locations. MCoBeauty, a new beauty brand, is marketed as an affordable alternative to popular brands like Sephora. Its bright packaging and affordable prices have gained popularity on TikTok, with its Flawless Glow Luminous Skin Filter and Super Glow Bronzing Drops being popular choices.
- In November 2023, Kiehl's partnered with Instacart to deliver same-day skincare and hair care products across the United States. The partnership, which began in Canada, allows customers to receive Kiehl's products in as little as an hour.
Report Coverage
The research report offers an in-depth analysis based on Product Type, Skin Type, Consumer Orientation, Distribution Channel and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Demand for clean, natural, and chemical-free personal care products will continue to rise.
- Skincare and haircare segments will see higher adoption driven by wellness and anti-aging needs.
- E-commerce and direct-to-consumer models will expand further across urban and semi-urban markets.
- Men’s grooming products will gain strong traction with broader product ranges and targeted marketing.
- Brands will invest more in personalized and AI-driven skincare and diagnostics tools.
- Sustainable packaging and ethical sourcing will become essential for brand differentiation.
- Emerging markets in Asia-Pacific and Latin America will offer strong growth opportunities.
- Technological advancements in product formulation will enhance performance and consumer appeal.
- Cross-border regulatory alignment and certifications will influence global expansion strategies.
- Competitive intensity will increase with continued entry of niche, purpose-driven startups.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Rising Health and Grooming Awareness
Increasing consumer focus on skincare, hygiene, and grooming routines - amplified by social media and influencer culture - is driving demand for a wide range of personal care aid products, especially in urban areas and among younger demographics.
Expansion of E-commerce and DTC Channels
The shift to online shopping and direct-to-consumer models provides consumers with greater convenience, product variety, and access to personalized recommendations, accelerating market penetration in both developed and emerging regions.
Demand for Clean, Sustainable, and Natural Products
Consumers are increasingly seeking products with clean-label, organic, and eco-friendly formulations, prompting brands to innovate with natural ingredients, cruelty-free claims, and sustainable packaging to capture environmentally conscious buyers.
Personalization and Technological Integration
Advancements in AI, skin diagnostics, and customizable formulations are enabling brands to offer tailored solutions for individual skin and hair needs, enhancing consumer engagement and supporting premium pricing strategies.
Growth in Men’s Grooming and Gender-Neutral Products
Changing cultural norms and targeted marketing are expanding the men’s grooming segment and driving demand for gender-neutral products, opening new avenues for growth and product innovation.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for the Personal care aid market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Personal care aid market projected to grow between 2024 and 2032?
Which Personal care aid market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Personal care aid market?
Who are the leading companies in the Personal care aid market?
Which region commanded the largest share of the Personal care aid market in 2024?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Skin Type
- 1.2.1 Dry Skin
- 1.2.2 Normal Skin
- 1.2.3 Sensitive Skin
- 1.2.4 Combination Skin
- 1.3 By Product Type
- 1.3.1 Skincare (Creams and Lotions, Serums, Face Packs or Masks, Cleansers, Other Skincare Products)
- 1.3.2 Body Care (Soaps, Shower Gels, Creams, Oils)
- 1.3.3 Hair Care (Shampoos, Conditioners, Hair Dyes, Hair Oils, Other Haircare Products)
- 1.3.4 Oral Care (Toothpaste, Mouthwash, Tooth Powder)
- 1.3.5 Cosmetics (Facial Products, Eye Products, Lip Products, Nail Products)
- 1.3.6 Fragrances and Deodorants
- 1.4 By Consumer Orientation
- 1.4.1 Women
- 1.4.2 Men
- 1.4.3 Kids
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 12,329 million → 2032: USD 21,824.69 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Personal Care Aid Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Personal Care Aid Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Personal Care Aid Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Personal Care Aid Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Personal Care Aid Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Personal Care Aid Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Personal Care Aid Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Personal Care Aid Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 12,329 million → 2032: USD 21,824.69 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Personal Care Aid Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Skin Type - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Dry Skin
- 12.3.7.2 Normal Skin
- 12.3.7.3 Sensitive Skin
- 12.3.7.4 Combination Skin
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Product Type - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Skincare (Creams and Lotions, Serums, Face Packs or Masks, Cleansers, Other Skincare Products)
- 12.4.7.2 Body Care (Soaps, Shower Gels, Creams, Oils)
- 12.4.7.3 Hair Care (Shampoos, Conditioners, Hair Dyes, Hair Oils, Other Haircare Products)
- 12.4.7.4 Oral Care (Toothpaste, Mouthwash, Tooth Powder)
- 12.4.7.5 Cosmetics (Facial Products, Eye Products, Lip Products, Nail Products)
- 12.4.7.6 Fragrances and Deodorants
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Consumer Orientation - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Women
- 12.5.7.2 Men
- 12.5.7.3 Kids
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global Personal Care Aid Geographic Market Outlook, 2024-2032
- 13.1 Regional Market Size and Share, 2024
- 13.2 Regional Market Forecast, 2024-2032
- 13.3 Regional Pricing, Production and Demand Differences
- 13.4 North America
- 13.4.1 United States
- 13.4.2 Canada
- 13.4.3 Mexico
- 13.5 Europe
- 13.5.1 Germany
- 13.5.2 France
- 13.5.3 Italy
- 13.5.4 United Kingdom
- 13.5.5 Spain
- 13.5.6 Poland
- 13.5.7 Russia
- 13.5.8 Netherlands
- 13.5.9 Belgium
- 13.5.10 Sweden
- 13.5.11 Denmark
- 13.5.12 Norway
- 13.5.13 Rest of Europe
- 13.6 Asia Pacific
- 13.6.1 China
- 13.6.2 India
- 13.6.3 Japan
- 13.6.4 South Korea
- 13.6.5 Thailand
- 13.6.6 Indonesia
- 13.6.7 Vietnam
- 13.6.8 Malaysia
- 13.6.9 Australia
- 13.6.10 Rest of Asia Pacific
- 13.7 Latin America
- 13.7.1 Brazil
- 13.7.2 Argentina
- 13.7.3 Colombia
- 13.7.4 Chile
- 13.7.5 Rest of Latin America
- 13.8 Middle East
- 13.8.1 Saudi Arabia
- 13.8.2 United Arab Emirates
- 13.8.3 Turkey
- 13.8.4 Israel
- 13.8.5 Iran
- 13.8.6 Rest of the Middle East
- 13.9 Africa
- 13.9.1 South Africa
- 13.9.2 Egypt
- 13.9.3 Nigeria
- 13.9.4 Morocco
- 13.9.5 Rest of Africa
- 13.10 Regional Investment, Policy and Supply Chain Differences
- 13.11 Regional Competitive Landscape
- 13.12 Geographic Growth Hotspots
Chapter 14 Global Personal Care Aid Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2024-2032
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 Global Personal Care Aid Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2024
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2024-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Procter & Gamble Co.
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 LVMH (Moët Hennessy - Louis Vuitton)
- 17.4 Estée Lauder Companies Inc.
- 17.5 Johnson & Johnson
- 17.6 Revlon Inc.
- 17.7 Coty Inc.
- 17.8 Kao Corporation
- 17.9 Clarins Group
- 17.10 Chanel S.A.
- 17.11 Mary Kay Cosmetics
- 17.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

