
Market Overview
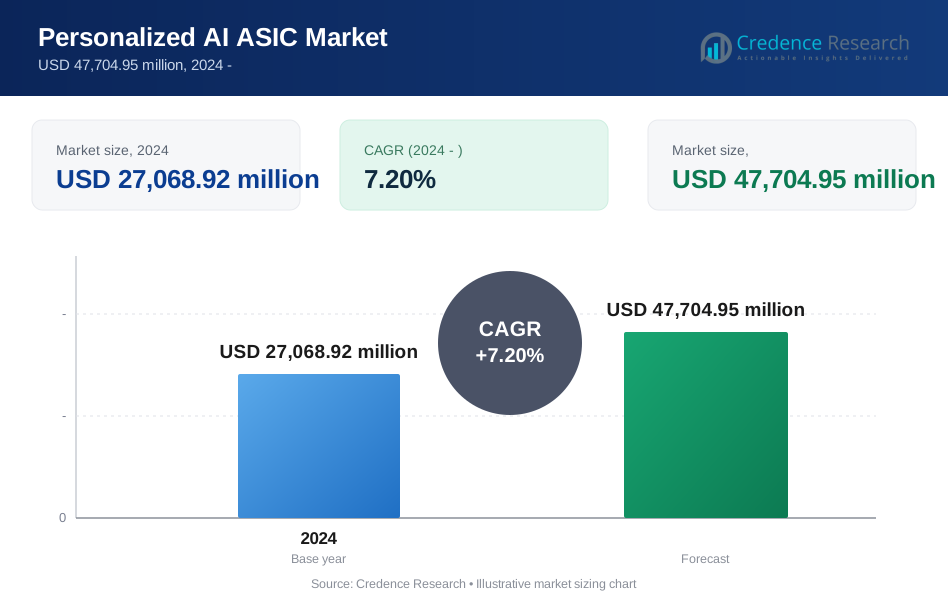
The Personalized AI ASIC Market size was valued at USD 16,143.32 million in 2018 to USD 27,068.92 million in 2024 and is anticipated to reach USD 47,704.95 million by 2032, at a CAGR of 7.20% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2024 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Personalized AI ASIC Market Size 2024 | USD 27,068.92 Million |
| Personalized AI ASIC Market, CAGR | 7.20% |
| Personalized AI ASIC Market Size 2032 | USD 47,704.95 Million |
The Personalized AI ASIC Market is driven by rising demand for energy-efficient, application-specific processors tailored for edge computing, healthcare diagnostics, and autonomous systems. Growing adoption of AI-powered wearables, smart devices, and real-time data processing accelerates the need for custom chip architectures. Trends include integration of neuromorphic computing, increasing use of 5nm and 3nm fabrication technologies, and collaboration between semiconductor firms and AI startups to enhance chip design. The shift toward personalized, low-latency AI applications across industries supports the rapid evolution of AI ASICs, enabling higher inference speeds, improved security, and optimized performance for specific workloads.
The Personalized AI ASIC Market spans key regions including North America, Europe, Asia Pacific, Latin America, the Middle East, and Africa. Asia Pacific holds the largest share, driven by high-tech manufacturing in China, Japan, and South Korea. North America leads in innovation and R&D, while Europe emphasizes energy-efficient AI hardware. Latin America, the Middle East, and Africa show emerging growth. Major players include Qualcomm, Intel, NVIDIA, Apple, Samsung Electronics, AMD, MediaTek, Huawei, Broadcom, and Socionext, competing through custom design, AI integration, and edge computing advancements.
Market Insights
- The Personalized AI ASIC Market was valued at USD 16,143.32 million in 2018, reached USD 27,068.92 million in 2024, and is projected to hit USD 47,704.95 million by 2032, growing at a CAGR of 7.20%.
- Rising demand for edge computing, real-time processing, and application-specific hardware drives market expansion across healthcare, automotive, and smart device sectors.
- Integration of neuromorphic computing and advanced 5nm and 3nm fabrication technologies enables smaller, faster, and more energy-efficient AI ASICs.
- North America holds over 33% share with strong R&D investment and major players like Intel and Qualcomm accelerating product development.
- Asia Pacific leads the market with a 37% share, driven by manufacturing strength in China, Japan, and South Korea and large-scale deployment of AI-powered devices.
- Europe accounts for 20% of market share, focusing on green computing, sovereign chip design, and AI privacy compliance in industrial and telecom sectors.
- Challenges include high development costs, long design cycles, and limited post-fabrication flexibility, which can hinder broader adoption in fast-evolving AI environments.

Market Drivers
Rising Demand for Edge AI and Custom Workloads
The Personalized AI ASIC Market is propelled by growing demand for edge computing devices that require low-latency, high-efficiency processing tailored to specific applications. It addresses the limitations of general-purpose processors in handling diverse AI tasks with speed and energy optimization. Industries such as healthcare, automotive, and smart devices increasingly rely on application-specific chips to enhance real-time decision-making and performance. This demand fuels continuous development of domain-specific architectures with optimized power consumption and minimal memory overhead.
For instance, Apple’s Neural Engine, integrated into its A-series chips, accelerates AI tasks like image recognition and augmented reality on mobile devices with exceptional energy efficiency, enabling real-time capabilities without cloud dependence.
Proliferation of Smart Devices and Wearable Technology
The expansion of smart consumer electronics, fitness trackers, and medical wearables has intensified the need for personalized AI chips that offer compactness, efficiency, and privacy. The Personalized AI ASIC Market responds by enabling on-device intelligence that reduces reliance on cloud-based data processing. It supports continuous health monitoring, gesture recognition, and real-time feedback in portable formats. Consumer preference for fast, adaptive devices with personalized features pushes companies to integrate AI ASICs into mainstream electronics.
For instance, NVIDIA's Jetson platform powers edge AI applications in healthcare and robotics, handling complex AI workloads in real time to deliver tailored user experiences.
Advancements in Semiconductor Fabrication and Design
Progress in semiconductor technology, such as 5nm and emerging 3nm nodes, supports the development of compact, high-performance AI ASICs. These fabrication advances reduce chip size while boosting processing speed and power efficiency. The Personalized AI ASIC Market benefits from this miniaturization trend, which allows embedding AI capabilities in devices with stringent space and energy constraints. It enables chipmakers to experiment with innovative architectures, including neuromorphic and low-voltage designs tailored for specific inference models.
Increasing Investments and Collaborative Ecosystems
Growing investments by tech giants, venture capital firms, and semiconductor manufacturers are accelerating innovation in AI ASICs. Startups and established players form strategic partnerships to co-develop chip designs optimized for targeted AI functions. The Personalized AI ASIC Market gains traction from this ecosystem, which blends hardware engineering expertise with algorithmic efficiency. It encourages rapid prototyping, validation, and deployment of new chipsets that support intelligent automation, personalized user experiences, and scalable edge solutions.
Market Trends
Integration of Neuromorphic and Brain-Inspired Architectures
The Personalized AI ASIC Market is witnessing strong momentum from the adoption of neuromorphic designs that mimic human brain functionality. These architectures improve energy efficiency and parallel processing for real-time AI tasks. They allow low-power inference and learning at the edge without relying on external data centers. Companies are embedding spiking neural networks into ASICs to support continuous learning. It addresses dynamic applications in robotics, AR/VR, and smart vision systems requiring adaptive intelligence and contextual awareness.
For instance, researchers in the Human Brain Project collaborating with Intel demonstrated that a neuromorphic system based on 32 Loihi chips delivers 2 to 3 times lower energy consumption than conventional AI models on tasks involving temporal data processing, such as understanding story context and object relationships.
Shift Toward Hyper-Personalization Across Consumer Applications
Demand for real-time customization in smart devices, voice assistants, and healthcare diagnostics is driving trends in user-centric chip design. The Personalized AI ASIC Market aligns with this by offering hardware tailored to specific user profiles and behavioral patterns. It enables secure, device-level processing of personal data without latency or privacy risks. Manufacturers integrate biometric authentication, contextual decision-making, and predictive analytics directly into ASICs. This trend supports AI-driven personalization at scale across home automation, mobile, and wellness devices.
For instance, Nest's smart thermostats use AI ASICs to learn user behavior and preferences for heating and cooling, enabling real-time adaptive climate control that improves comfort and energy efficiency.
Expansion of Edge AI and Federated Learning Models
Edge AI is reshaping the deployment of AI workloads by reducing dependency on centralized data processing. The Personalized AI ASIC Market supports this shift by providing ultra-low-power chips designed for localized inference. Trends also highlight the integration of federated learning frameworks into ASIC designs, allowing devices to collaboratively train AI models without sharing raw data. It strengthens data privacy, reduces bandwidth costs, and ensures consistent model updates in IoT, smart city, and industrial automation ecosystems.
AI Chip Design Customization Enabled by EDA Tools and IP Cores
The rise of advanced electronic design automation (EDA) tools and reusable intellectual property (IP) blocks is fueling faster, modular AI ASIC development. Companies leverage these platforms to iterate custom chip layouts for specific algorithms or devices. The Personalized AI ASIC Market benefits from this trend, which accelerates time-to-market while optimizing cost and performance. It supports the creation of domain-specific hardware tailored to applications in imaging, speech recognition, cybersecurity, and personalized computing environments.
Market Challenges Analysis
High Development Costs and Complex Design Cycles
The Personalized AI ASIC Market faces significant challenges due to the high upfront investment required for custom chip development. Designing ASICs for personalized AI applications involves lengthy verification, specialized fabrication processes, and expensive EDA tool usage. Smaller companies struggle to compete with established players due to limited access to capital and talent. It limits innovation and delays product launches. Iterative design cycles and the need for extensive hardware-software co-optimization further increase time-to-market and resource requirements.
Limited Flexibility and Rapid Technological Obsolescence
ASICs, by nature, offer limited post-fabrication flexibility, making them less adaptable to evolving AI models or algorithmic updates. The Personalized AI ASIC Market contends with risks associated with rapid advancements in AI software that may outpace hardware capabilities. It creates challenges in ensuring compatibility, scalability, and long-term usability. Any changes in AI workloads often require redesigning chips entirely. This inflexibility increases lifecycle costs and may hinder adoption in fast-changing sectors such as autonomous systems and consumer electronics.
Market Opportunities
Rising Adoption in Healthcare, Wearables, and Assistive Technologies
The growing demand for intelligent, low-power hardware in healthcare diagnostics, fitness tracking, and assistive devices presents a strong opportunity for the Personalized AI ASIC Market. Devices that require continuous monitoring and real-time analytics benefit from application-specific chipsets. It enables accurate processing of biometric data, personalized insights, and secure on-device computing. Use cases in hearing aids, glucose monitors, and mental health tools continue to expand. Companies can capitalize on this trend by designing ASICs tailored to medical-grade precision and user-specific needs.
Growing Demand for Secure and Private On-Device AI Processing
Escalating privacy concerns and data protection regulations are pushing industries toward decentralized AI architectures. The Personalized AI ASIC Market stands to gain from demand for secure, on-device processing that eliminates cloud dependency. It supports AI workloads that require confidentiality, such as facial recognition, personalized recommendations, and voice authentication. Organizations seek ASICs that balance high-speed inference with hardware-level encryption and privacy controls. This opens avenues in sectors such as finance, defense, and enterprise-grade consumer electronics where secure personalization is essential.
Market Segmentation Analysis:
By Product Type
The Personalized AI ASIC Market segments into Personalized AI Training ASICs, Personalized AI Inference ASICs, and Edge AI ASICs. Training ASICs support high-performance computing for model development and are primarily used in data centers. Inference ASICs enable fast, energy-efficient decision-making for real-time applications. Edge AI ASICs focus on localized processing in devices such as wearables and embedded systems. It continues to see rising demand for edge-capable solutions due to privacy, latency, and connectivity advantages.
For instance, edge AI ASICs focus on processing at the device level to enhance privacy and reduce latency, a trend driven by demand for edge-capable solutions in wearables and embedded systems that rely on localized data handling without cloud dependency.
By Application
The Personalized AI ASIC Market divides into Consumer Electronics, Healthcare & Medical Devices, Automotive (ADAS, In-Car Assistants), Telecommunications & Networking, Retail & Marketing Personalization, and Smart Home & IoT Devices. Consumer electronics lead adoption with demand for personalized features in smartphones and wearables. Healthcare devices integrate AI ASICs for diagnostics and continuous monitoring. The automotive sector deploys these chips in advanced driver assistance and cabin intelligence systems. It also finds strong use cases in telecom for traffic optimization and in retail for AI-driven customer engagement.
For instance, BMW employs AI ASICs embedded in predictive maintenance algorithms to monitor battery health and brake systems, enabling proactive servicing and improved vehicle reliability.

Segments
Based on Product Type
- Personalized AI Training ASICs
- Personalized AI Inference ASICs
- Edge AI ASICs
Based on Application
- Consumer Electronics
- Healthcare & Medical Devices
- Automotive (ADAS, In-Car Assistants)
- Telecommunications & Networking
- Retail & Marketing Personalization
- Smart Home & IoT Devices
Based on Region
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis
North America
The North America Personalized AI ASIC Market size was valued at USD 4,798.34 million in 2018 to USD 7,923.04 million in 2024 and is anticipated to reach USD 14,020.44 million by 2032, at a CAGR of 7.3% during the forecast period. North America holds the largest market share at over 33%, driven by strong adoption of AI technologies in the U.S. and Canada. It benefits from robust investment in semiconductor R&D, edge computing infrastructure, and personalized healthcare solutions. Companies focus on integrating ASICs into smart devices, autonomous systems, and cloud platforms. Presence of major players like Intel, NVIDIA, and Qualcomm accelerates innovation and commercialization. Regulatory frameworks also support AI deployment across industries including automotive, defense, and consumer electronics.
Europe
The Europe Personalized AI ASIC Market size was valued at USD 2,956.16 million in 2018 to USD 4,680.02 million in 2024 and is anticipated to reach USD 7,484.56 million by 2032, at a CAGR of 5.9% during the forecast period. Europe accounts for approximately 20% of the global market share, driven by growing demand for AI hardware in industrial automation, healthcare, and telecommunications. It sees strong momentum in countries like Germany, France, and the UK, which invest in sovereign AI infrastructure. Initiatives around digital sovereignty and green computing influence custom chip adoption. European players collaborate with research institutes to build energy-efficient AI ASICs tailored for edge and embedded systems. The market is expanding with increasing focus on data privacy and on-device learning.
Asia Pacific
The Asia Pacific Personalized AI ASIC Market size was valued at USD 6,913.12 million in 2018 to USD 12,028.59 million in 2024 and is anticipated to reach USD 22,517.16 million by 2032, at a CAGR of 8.0% during the forecast period. Asia Pacific dominates the global market with over 37% share, fueled by massive investments in AI, IoT, and 5G infrastructure. China, Japan, South Korea, and India lead in AI chip innovation and production capacity. It benefits from high-volume consumer electronics manufacturing and government-backed AI policies. Regional players focus on localized ASICs for smartphones, robotics, and smart cities. The presence of major foundries and design houses supports rapid prototyping and volume deployment. Demand continues to grow across healthcare, retail, and automotive applications.
Latin America
The Latin America Personalized AI ASIC Market size was valued at USD 746.31 million in 2018 to USD 1,235.50 million in 2024 and is anticipated to reach USD 1,921.69 million by 2032, at a CAGR of 5.5% during the forecast period. Latin America holds a modest share of about 6% of the global market. It shows steady growth driven by increasing digitalization and adoption of AI in sectors such as healthcare, retail, and transportation. Countries like Brazil and Mexico invest in smart infrastructure and AI-enabled devices. It focuses on edge AI ASICs for cost-effective deployments in resource-constrained environments. Local demand is growing for real-time analytics in urban management and customer personalization.
Middle East
The Middle East Personalized AI ASIC Market size was valued at USD 439.58 million in 2018 to USD 671.95 million in 2024 and is anticipated to reach USD 993.38 million by 2032, at a CAGR of 4.8% during the forecast period. The region contributes around 4% to the global market, supported by AI adoption in sectors like energy, logistics, and defense. It witnesses growth in demand for smart city solutions, driven by national digital transformation agendas. Countries such as UAE and Saudi Arabia integrate personalized AI capabilities in public services and surveillance. Investment in semiconductor design hubs and data centers enhances the regional ecosystem. The market favors inference-focused ASICs with localized processing and low-power performance.
Africa
The Africa Personalized AI ASIC Market size was valued at USD 289.80 million in 2018 to USD 529.82 million in 2024 and is anticipated to reach USD 767.72 million by 2032, at a CAGR of 4.6% during the forecast period. Africa holds the smallest share, contributing nearly 3% to the global market. It experiences gradual adoption of AI ASICs in mobile health, agriculture, and education technologies. It relies on partnerships with global tech firms for chip access and deployment. Edge-based AI solutions are gaining attention for offline use in remote areas. Governments and startups begin to explore personalized applications using affordable AI hardware. Market growth remains constrained by infrastructure and funding limitations.
Key Player Analysis
- MediaTek
- Socionext
- Intel
- Huawei
- Qualcomm
- Samsung Electronics
- Broadcom
- AMD (Advanced Micro Devices)
- Apple
- NVIDIA
Competitive Analysis
The Personalized AI ASIC Market features intense competition driven by innovation, rapid product cycles, and domain-specific design strategies. Key players such as Apple, Intel, NVIDIA, Qualcomm, and Samsung Electronics lead with proprietary architectures optimized for edge AI, training, and inference. Companies invest heavily in custom chip development to enhance speed, energy efficiency, and integration with AI ecosystems. The Personalized AI ASIC Market sees startups and fabless firms introducing disruptive solutions focused on low-power and secure on-device computing. Strategic partnerships between semiconductor firms, AI developers, and cloud providers accelerate time-to-market. It remains highly dynamic, with players competing on process node advancements, IP differentiation, and application-specific performance. Emerging competitors from Asia are expanding their presence through vertical integration and government-backed AI initiatives.
Recent Developments
- In February 2025, OpenAI finalized its first custom AI chip design and sent it to TSMC for fabrication, aiming to reduce reliance on third-party GPU suppliers like NVIDIA.
- In June 2025, Qualcomm announced the acquisition of UK-based Alphawave for $2.4 billion to strengthen its AI and high-speed connectivity capabilities for data center applications.
- In June 2025, Astera Labs entered a strategic partnership with Alchip to co-develop high-performance ASIC solutions for rack-scale AI connectivity.
- In January 2025, Nano Labs invested in Weiheng Technology, acquiring a 5% equity stake to support the development of AI-centric edge and compute-storage ASICs in collaboration with DeepSeek.
Market Concentration & Characteristics
The Personalized AI ASIC Market shows moderate to high concentration, with a few dominant players including NVIDIA, Intel, Qualcomm, Apple, and Samsung Electronics leading innovation and volume production. These companies hold strong positions due to advanced fabrication capabilities, proprietary architectures, and integration with AI ecosystems. The market is characterized by high entry barriers, driven by complex design requirements, substantial R&D costs, and access to leading-edge foundries. It favors vertically integrated firms and those with strategic alliances across the AI value chain. The Personalized AI ASIC Market emphasizes customization, energy efficiency, and low-latency performance, making it highly competitive in segments such as edge computing, autonomous systems, and smart medical devices. Players differentiate through specialization in inference or training chips, domain-specific optimization, and scalability across platforms. The pace of technological evolution and rapid product iteration cycles reinforce the need for continuous innovation and design agility to maintain relevance in this dynamic landscape.
Report Coverage
The research report offers an in-depth analysis based on Product Type, Application and Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Demand for application-specific AI chips will rise with increased edge device deployment in healthcare, automotive, and consumer electronics.
- Semiconductor companies will invest in ultra-low-power AI ASICs to support energy-efficient, on-device processing.
- Neuromorphic and brain-inspired architectures will gain traction for real-time adaptive computing.
- 3nm and advanced fabrication technologies will enable higher performance and smaller chip footprints.
- Strategic collaborations between AI startups and chipmakers will accelerate custom ASIC development.
- Integration of AI ASICs into wearables and smart home devices will expand across global markets.
- Security and privacy requirements will drive demand for on-device AI inference chips.
- Cloud providers will offer hybrid models that combine cloud AI with personalized edge ASICs.
- Open-source AI hardware initiatives will foster broader innovation and standardization.
- Government support for AI infrastructure will strengthen domestic ASIC manufacturing in emerging regions.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Personalized AI ASIC Market?
What factors are driving the growth of the Personalized AI ASIC Market?
What are the key segments within the Personalized AI ASIC Market?
What are some challenges faced by the Personalized AI ASIC Market?
Who are the major players in the Personalized AI ASIC Market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Personalized AI ASIC Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to the forecast period)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Personalized AI ASIC Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (the forecast period) (2024: USD 27,068.92 million → forecast year: USD 47,704.95 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Personalized AI ASIC Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs.
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Personalized AI ASIC Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Personalized AI ASIC Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Personalized AI ASIC Market Drivers
- 3.3 Personalized AI ASIC Market Restraints & Challenges
- 3.4 Personalized AI ASIC Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Personalized AI ASIC Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Personalized AI ASIC Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Personalized AI ASIC category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Personalized AI ASIC Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through the forecast period
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through the forecast period
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Personalized AI ASIC Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Personalized AI ASIC market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Personalized AI ASIC Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Personalized AI ASIC Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Personalized AI ASIC Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Personalized AI ASIC (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Personalized AI ASIC Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Personalized AI ASIC Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & )
- 7.1.2 Channel Mix Evolution (the forecast period)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through the forecast period
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Personalized AI ASIC Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Personalized AI ASIC Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Personalized AI ASIC Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Personalized AI ASIC Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Personalized AI ASIC Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Personalized AI ASIC Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Personalized AI ASIC Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
