
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Smart Virtual Personal Assistants Market Size 2024 | USD 3,796.32 million |
| Smart Virtual Personal Assistants Market, CAGR | 26.43% |
| Smart Virtual Personal Assistants Market Size 2032 | USD 24,783.5 million |
Market Overview:
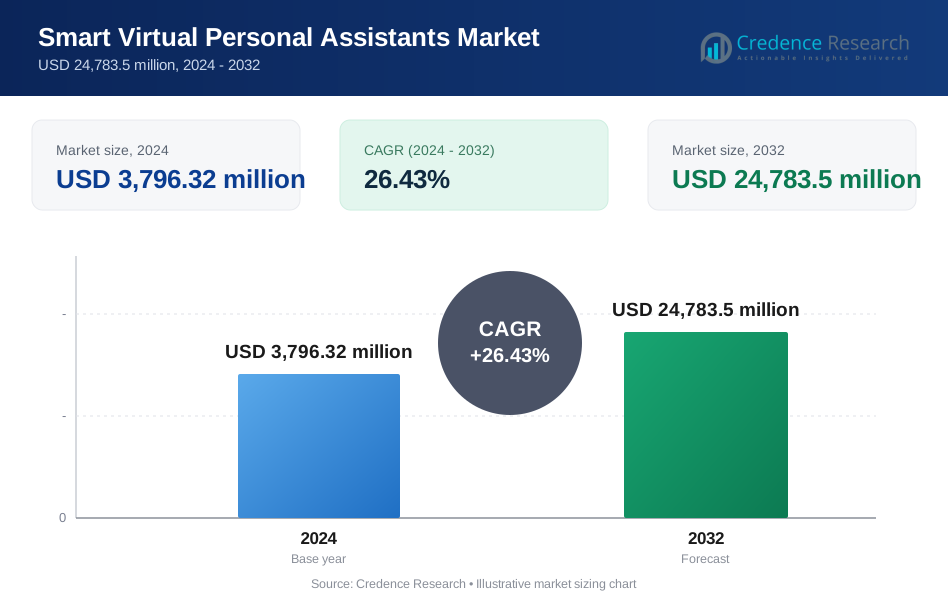
The Smart Virtual Personal Assistants Market is projected to grow from USD 3,796.32 million in 2024 to USD 24,783.5 million by 2032, reflecting a robust compound annual growth rate (CAGR) of 26.43%.
The Smart Virtual Personal Assistants market is driven by the increasing adoption of AI and machine learning technologies, enabling more personalized, intuitive, and efficient user experiences. The growing demand for automation in daily tasks, coupled with advancements in natural language processing and voice recognition, is fueling market growth. Furthermore, the rising popularity of smart devices, including smartphones, wearables, and IoT-enabled gadgets, has amplified the demand for virtual assistants. Consumer preference for hands-free, time-saving solutions is contributing to their widespread use in sectors like retail, healthcare, and customer service. Additionally, the increasing integration of virtual assistants in business operations to enhance productivity and customer engagement is a notable trend. The growing awareness of smart assistant capabilities, along with the expansion of cloud computing and data analytics, is further propelling market evolution. These factors, combined with innovations in voice-controlled devices, are driving the substantial growth forecasted for the market in the coming years.
The Smart Virtual Personal Assistants market exhibits strong geographical diversity, with North America leading at 39% market share in 2024, driven by major players like Amazon and Google. Europe follows with a 30% share, where countries like the UK, Germany, and France are key markets for AI integration in various industries. The Asia-Pacific region, accounting for 20%, is witnessing rapid adoption, particularly in China, Japan, and India, with companies such as Baidu and Yandex making significant strides. The Rest of the World region holds an 11% share, with growing interest in smart assistants across Latin America, the Middle East, and Africa. Key players in these regions, including Apple, Amazon, and Baidu, are intensifying their efforts to expand their market footprint and cater to regional demands in consumer electronics, smart homes, and enterprise applications.
Market Insights:
- The Smart Virtual Personal Assistants market is expected to grow from USD 3,796.32 million in 2024 to USD 24,783.5 million by 2032, with a robust CAGR of 26.43%.
- Advancements in AI and machine learning technologies are driving growth, enabling more personalized and intuitive user experiences through improved voice recognition and natural language processing.
- The rise in smart device adoption, including smartphones, wearables, and IoT gadgets, has fueled the demand for virtual assistants, especially in consumer electronics and smart homes.
- Businesses increasingly adopt virtual assistants to streamline operations, enhance productivity, and improve customer engagement, further contributing to market expansion.
- Privacy and data security concerns pose a significant challenge, with consumers becoming cautious about the collection and usage of personal data by virtual assistants.
- Technical limitations, such as speech recognition accuracy and understanding diverse accents, hinder the full potential of virtual assistants, especially in complex environments.
- The North American market leads with a 39% share in 2024, followed by Europe at 30%, Asia-Pacific at 20%, and the Rest of the World at 11%.
Market Drivers:
Technological Advancements in AI and Machine Learning:
One of the primary drivers of the Smart Virtual Personal Assistants market is the rapid advancement in artificial intelligence (AI) and machine learning technologies. These innovations allow virtual assistants to offer more accurate, personalized, and context-aware interactions. Enhanced natural language processing (NLP) and speech recognition capabilities enable virtual assistants to understand complex queries, execute commands, and deliver relevant responses efficiently. For instance, Apple’s Siri leverages advanced natural language processing and speech recognition to understand complex user queries and execute tasks such as sending messages, setting reminders, and controlling smart devices across iPhones, iPads, and Macs. As AI technology continues to improve, virtual assistants become increasingly valuable to both consumers and businesses, offering improved user experiences and expanding their functionality.
Rising Adoption of Smart Devices and IoT Integration:
The increasing adoption of smart devices, such as smartphones, smart speakers, and IoT-enabled appliances, significantly contributes to the market's growth. As consumers increasingly embrace connected technologies in their homes and workplaces, the demand for virtual assistants integrated into these devices has surged. For example, in October 2023, Amazon Web Services launched its Software Package Catalog, a managed cloud service that allows users to register, monitor, and manage large fleets of IoT devices, providing centralized oversight for connected environments. These assistants allow users to control their devices with voice commands, manage daily tasks, and access information, enhancing convenience and efficiency. The integration of virtual assistants in a wide range of IoT devices fosters seamless automation, making it an essential component of modern digital ecosystems.
Demand for Automation and Productivity Enhancement:
As businesses and consumers strive to improve productivity and efficiency, the demand for automation solutions continues to rise. Smart Virtual Personal Assistants are being increasingly used to streamline administrative tasks, schedule management, and customer support. In the corporate sector, these assistants are employed to automate routine processes, manage emails, and improve workflow efficiency. The ability of virtual assistants to perform repetitive tasks reduces the workload on human employees, allowing them to focus on higher-level strategic activities, thereby enhancing overall productivity.
Consumer Preference for Convenience and Time Savings:
The growing preference for convenience and time-saving solutions among consumers is a significant driver for the Smart Virtual Personal Assistants market. People are increasingly seeking hands-free, voice-controlled alternatives to manage their daily tasks. Whether it’s setting reminders, making appointments, or controlling home environments, virtual assistants provide users with an efficient, streamlined way to interact with technology. As lifestyles become busier, the need for intelligent, responsive, and easy-to-use digital assistants continues to grow, further accelerating market demand.
Market Trends:
Integration with Multi-Device Ecosystems:
A prominent trend in the Smart Virtual Personal Assistants market is their increasing integration with a wide range of devices. Virtual assistants are no longer confined to smartphones or smart speakers; they are now embedded in a variety of devices, including wearables, home appliances, and even vehicles. For instance, Apple’s Siri, powered by Apple Intelligence, is now deeply integrated across iPhone, iPad, and Mac, enabling users to perform actions like sending photos or retrieving articles simply by voice, regardless of which device they’re using. This multi-device ecosystem enables seamless user experiences, where a single voice command can control multiple devices across different platforms. The growing interconnectedness of devices fosters a more integrated and efficient environment, enhancing convenience for consumers and businesses alike.
Enhanced Personalization and Context-Awareness:
Smart Virtual Personal Assistants are becoming more personalized, with advancements in AI enabling them to offer highly contextualized and tailored responses. These assistants can learn user preferences over time and provide increasingly accurate suggestions and actions based on individual habits, locations, and previous interactions. This trend towards deeper personalization is improving the overall user experience, making virtual assistants not only more functional but also more intuitive. Personalization helps users save time and effort by anticipating needs and offering relevant solutions, thus making the assistants more valuable in everyday tasks.
Expansion in Business Applications:
Beyond consumer use, there is a growing trend of Smart Virtual Personal Assistants being integrated into business operations to enhance customer service and internal processes. Virtual assistants are increasingly being deployed in customer support, handling routine inquiries, and improving response times. Businesses are also leveraging virtual assistants for tasks like scheduling meetings, managing emails, and analyzing data, ultimately improving operational efficiency. For instance, Synapse, a UK-based public relations platform, deployed an AI-powered virtual assistant that now manages 70% of routine customer queries, cutting average FAQ response times from 3 hours to under 1 minute and saving about 30% in annual customer service operational costs. This shift highlights the broader acceptance of AI-powered assistants in professional environments, as companies look for innovative ways to streamline operations and improve customer experiences.
Increased Focus on Privacy and Security:
As the adoption of Smart Virtual Personal Assistants grows, there is an increased focus on privacy and data security. Consumers are becoming more aware of the data being collected by these devices, prompting developers to enhance security features. The implementation of end-to-end encryption, strict data protection policies, and transparent privacy practices is becoming a key priority for companies offering virtual assistants. Ensuring that personal information remains secure while providing seamless functionality is crucial to maintaining consumer trust and sustaining long-term market growth.
Market Challenges Analysis:
Privacy and Data Security Concerns:
A major challenge facing the Smart Virtual Personal Assistants market revolves around privacy and data security concerns. These assistants continuously collect data to personalize user experiences, including voice commands, preferences, habits, and behavioral patterns. This extensive data collection poses significant risks related to unauthorized access, data breaches, and potential misuse by third parties. With growing concerns about cyber threats and the mishandling of personal information, consumers are becoming more cautious about adopting these devices, particularly in environments that handle sensitive data. Trust is a critical factor for consumers when deciding to use virtual assistants, especially as their role in personal and business environments expands. For instance, Google Assistant's integration with other Google services increases the risk of extensive user profiling, as the assistant can aggregate data across multiple platforms, amplifying concerns over how personal information is collected and potentially exploited. Companies must invest in robust security protocols, encryption technologies, and transparent data policies to reassure users about the safety of their information. Without addressing these security concerns, the market risks encountering significant resistance, which could hinder widespread adoption.
Technical Limitations and Accuracy Issues:
Another notable challenge in the Smart Virtual Personal Assistants market is the persistent technical limitations, particularly related to speech recognition and natural language processing (NLP). While AI and machine learning technologies have made significant strides in enhancing virtual assistants, they still face hurdles in accurately understanding diverse accents, dialects, and complex speech patterns. Misunderstandings, particularly with non-native speakers or regional variations, can lead to frustrating user experiences. Additionally, virtual assistants struggle to comprehend context in extended conversations, often misinterpreting commands or failing to maintain logical continuity over multiple exchanges. These limitations can diminish the overall utility of virtual assistants, especially in more demanding or business-critical applications. Overcoming these challenges requires continuous advancements in AI algorithms, linguistic models, and contextual awareness. Until these technical issues are resolved, virtual assistants will remain limited in their potential, especially in more complex, professional environments.
Market Opportunities:
The Smart Virtual Personal Assistants market presents several opportunities for growth, particularly as advancements in AI and machine learning continue to evolve. One of the key opportunities lies in the increasing demand for voice-controlled technologies in a variety of industries. Virtual assistants can be integrated into a wide range of devices, from smartphones and smart speakers to wearables, vehicles, and home appliances, offering convenience and efficiency to users. As consumers become more accustomed to hands-free, voice-activated solutions, the market for virtual assistants is expected to expand rapidly. Businesses are also increasingly leveraging virtual assistants to streamline customer service operations, automate administrative tasks, and enhance employee productivity, creating additional opportunities for companies in this space. The ability to offer personalized experiences, coupled with the integration of AI-driven insights, is likely to attract new user segments and enhance the appeal of virtual assistants.
Furthermore, the rise of IoT and smart homes presents another significant opportunity for the Smart Virtual Personal Assistants market. As more households adopt connected devices, the demand for a centralized virtual assistant to manage these devices grows. Virtual assistants can help users control everything from lighting and temperature to security systems and entertainment, all through voice commands. This level of automation appeals to consumers seeking more convenient and efficient ways to manage their homes. Additionally, with the increasing emphasis on data-driven decision-making, virtual assistants can be used to provide real-time analytics and support decision-making in both personal and professional settings. These trends are expected to create new revenue streams, particularly for companies that can integrate their virtual assistants into broader smart ecosystems and provide solutions tailored to specific industries or needs.
Market Segmentation Analysis:
By Application
The Smart Virtual Personal Assistants market is segmented by application into various industries, including education, BFSI (Banking, Financial Services, and Insurance), retail, healthcare, IT & telecom, automotive, consumer electronics, and travel & hospitality. Each sector leverages virtual assistants for tasks like automation, customer service, and improving operational efficiency, driving market growth.
By Product Outlook
The product segment of the Smart Virtual Personal Assistants market includes smart speakers and chatbots. Smart speakers are widely used in homes and businesses for voice-controlled functions, while chatbots are increasingly adopted for customer service and support across multiple industries. Both products cater to the rising demand for efficient, hands-free user interactions.
By Technology
Technological advancements play a significant role in the Smart Virtual Personal Assistants market. Key technologies include text-based, text-to-speech, and automatic speech recognition. Text-based systems enable written interactions, while text-to-speech and automatic speech recognition facilitate more natural, voice-based communication, enhancing user experience and driving the adoption of virtual assistants across various applications.
Segments:
Based on Application
- Education
- BFSI
- Retail
- Healthcare
- IT & Telecom
- Automotive
- Consumer Electronics
- Travel & Hospitality
- Others
Based on Product Outlook
- Smart Speakers
- Chatbots
Based on Technology
- Text-Based
- Text-To-Speech
- Automatic Speech Recognition
Based on the Geography:
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis:
North America
In 2024, North America holds the largest market share in the Smart Virtual Personal Assistants market, accounting for 39% of the global market. The region's dominance is primarily due to the high adoption rate of advanced technologies and the presence of leading companies in the virtual assistant industry, such as Amazon and Google. The increasing demand for voice-controlled devices, such as smart speakers and AI-powered assistants, is driving growth in both consumer and business applications. Additionally, the region's well-developed infrastructure and high disposable income contribute to widespread consumer adoption, while businesses in sectors like healthcare, retail, and BFSI continue to integrate virtual assistants for improved productivity and customer service.
Europe
Europe holds a significant market share of 30% in 2024, supported by the growing adoption of AI and machine learning technologies. The demand for Smart Virtual Personal Assistants in Europe is driven by increasing consumer awareness and the integration of virtual assistants into various industries, including retail, automotive, and healthcare. Countries like the United Kingdom, Germany, and France are leading the charge, with businesses leveraging virtual assistants for customer engagement, automation, and operational efficiency. Moreover, Europe is witnessing rising investments in smart home technologies, further boosting the demand for voice-controlled assistants.
Asia-Pacific
Asia-Pacific (APAC) is expected to hold a 20% share of the market in 2024, making it a rapidly growing region for Smart Virtual Personal Assistants. With the increasing adoption of smartphones and IoT devices, the demand for virtual assistants is steadily rising in countries such as China, Japan, India, and South Korea. The region's vast population and emerging middle class are key drivers of this growth. Additionally, the adoption of virtual assistants in sectors like retail, healthcare, and education is helping boost market penetration. As the region experiences strong economic growth and technology advancements, APAC is poised to become one of the key contributors to the global market.
Rest of the World
The Rest of the World (RoW) region, which includes regions such as Latin America, the Middle East, and Africa, holds a smaller market share of 11% in 2024. Despite the relatively low market share, the region is witnessing increased interest in Smart Virtual Personal Assistants, particularly in sectors such as consumer electronics and healthcare. The growth in internet penetration and the adoption of smartphones is expected to drive demand for virtual assistants. The Middle East, with its strong focus on technological advancements and smart city initiatives, is likely to see significant growth in the coming years.
Key Player Analysis:
- Nuance Communications
- Microsoft Cortana
- Google Assistant
- Yandex Alice
- OpenAI GPT-3
- Baidu DuerOS
- Sony Xperia Assistant
- Amazon Alexa
- Alibaba AliGenie
- IBM Watson Assistant
- Samsung Bixby
- Apple Siri
Competitive Analysis:
The Smart Virtual Personal Assistants market is highly competitive, with leading players such as Apple Siri, Amazon Alexa, Samsung Bixby, Google Assistant, OpenAI GPT-3, Microsoft Cortana, Baidu DuerOS, IBM Watson Assistant, Yandex Alice, Nuance Communications, Sony Xperia Assistant, and Alibaba AliGenie. These companies are at the forefront of driving innovation in AI and machine learning technologies, integrating advanced natural language processing and speech recognition capabilities into their products. Apple and Google dominate the consumer sector with their AI-powered assistants embedded in smartphones and smart speakers, while Amazon leads in the smart home ecosystem. Companies like OpenAI and IBM are pushing the boundaries of conversational AI and enterprise solutions. Meanwhile, Baidu, Yandex, and Alibaba are strengthening their presence in China and other Asian markets. The competition intensifies as these companies continuously upgrade their virtual assistants, enhance personalization features, and expand their presence across various industries, including retail, healthcare, and automotive.
Recent Delopments:
- In April 2025, Nuance rolled out a new AI virtual assistant for healthcare, designed to streamline clinical workflows for clinicians and improve patient-provider interactions.
- In February 2024, Gemini was released as a mobile chatbot, initially titled Assistant with Bard, and began its rollout as the primary assistant on new Android devices.
- In April 2025, Sony released a new software update for the Xperia 1 V, improving security and emergency call functionality.
- On February 26, 2025, Amazon unveiled Alexa+, a major upgrade powered by generative AI. The enhanced assistant offers advanced conversational skills, personalized routines, proactive assistance, and the ability to execute complex tasks such as booking services and managing smart home devices.
Market Concentration & Characteristics:
The Smart Virtual Personal Assistants market is characterized by moderate concentration, with a few dominant players leading the industry, including Amazon, Google, Apple, and Microsoft. These companies hold significant market shares due to their established technology ecosystems, extensive consumer reach, and continuous advancements in AI and machine learning. However, the market is also witnessing the emergence of new players and innovations, particularly from regional companies such as Baidu, Yandex, and Alibaba, which are enhancing competition. The market is driven by factors like increasing smart device adoption, demand for automation, and AI-driven personalization. As a result, companies are focusing on improving speech recognition, natural language processing, and multi-device integration. While established companies lead, there is ample opportunity for newcomers to capture market share, particularly through niche innovations or regional expansions. The market is evolving rapidly, with continuous improvements in AI technology and a growing range of applications.
Report Coverage:
The research report offers an in-depth analysis based on Application, Product Outlook, Technology and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- The demand for voice-controlled virtual assistants will continue to rise as more smart devices become integrated into daily life.
- Advancements in AI and machine learning will lead to more personalized, intuitive, and context-aware user experiences.
- Virtual assistants will increasingly play a critical role in automating both personal and business tasks, improving productivity and efficiency.
- The expansion of IoT ecosystems will drive greater integration of virtual assistants into smart homes and workplaces.
- Consumer preference for hands-free solutions will fuel growth in sectors like retail, healthcare, and automotive.
- Businesses will further integrate virtual assistants into their operations to enhance customer service, support, and engagement.
- Enhanced data analytics and cloud computing will enable virtual assistants to offer more accurate insights and predictions.
- Improved natural language processing and speech recognition technologies will overcome existing limitations in understanding diverse languages and accents.
- Concerns around privacy and data security will lead to the development of more secure and transparent virtual assistant systems.
- Regional markets, particularly in Asia-Pacific and the Middle East, will experience rapid adoption due to growing tech infrastructure and consumer demand.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Smart Virtual Personal Assistants market?
What factors are driving the growth of the Smart Virtual Personal Assistants market?
What are some challenges faced by the Smart Virtual Personal Assistants market?
Who are the major players in the Smart Virtual Personal Assistants market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Smart Virtual Personal Assistants Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Smart Virtual Personal Assistants Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 3,796.32 million → 2032: USD 24,783.5 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Smart Virtual Personal Assistants Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Smart Virtual Personal Assistants Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Smart Virtual Personal Assistants Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Smart Virtual Personal Assistants Market Drivers
- 3.3 Smart Virtual Personal Assistants Market Restraints & Challenges
- 3.4 Smart Virtual Personal Assistants Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Smart Virtual Personal Assistants Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Smart Virtual Personal Assistants Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Smart Virtual Personal Assistants category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Smart Virtual Personal Assistants Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Smart Virtual Personal Assistants Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Smart Virtual Personal Assistants market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Smart Virtual Personal Assistants Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Smart Virtual Personal Assistants Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Smart Virtual Personal Assistants Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Smart Virtual Personal Assistants (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Smart Virtual Personal Assistants Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Smart Virtual Personal Assistants Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Smart Virtual Personal Assistants Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Smart Virtual Personal Assistants Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Smart Virtual Personal Assistants Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Smart Virtual Personal Assistants Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Smart Virtual Personal Assistants Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Smart Virtual Personal Assistants Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Smart Virtual Personal Assistants Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
