
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
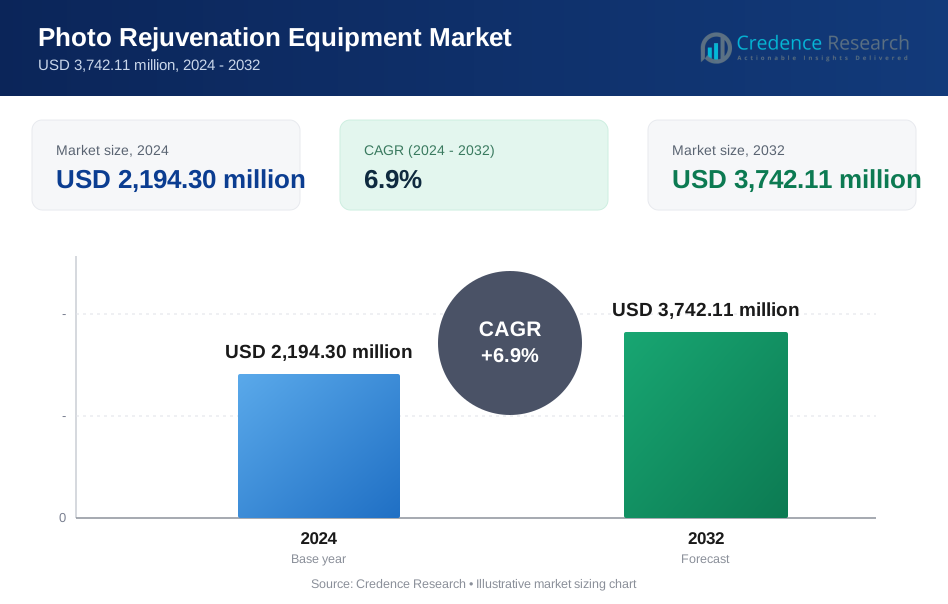
| Photo Rejuvenation Equipment Market Size 2024 | USD 2,194.30 million |
| Photo Rejuvenation Equipment Market, CAGR | 6.9% |
| Photo Rejuvenation Equipment Market Size 2032 | USD 3742.11 million |
Market Overview:
The Photo rejuvenation Equipment Market is projected to grow from USD 2,194.30 million in 2024 to an estimated USD 3742.11 million by 2032, with a compound annual growth rate (CAGR) of 6.9% from 2024 to 2032.
The primary drivers of the photo rejuvenation equipment market include the growing focus on aesthetics, especially among the aging population seeking skin rejuvenation therapies. Additionally, the non-invasive nature of photo rejuvenation procedures, which reduces downtime compared to traditional surgical methods, has fueled their adoption. The rising prevalence of skin-related conditions such as acne, wrinkles, and hyperpigmentation further contribute to the demand for photo rejuvenation treatments. Furthermore, advancements in laser and light-based technologies, such as Intense Pulsed Light (IPL) and fractional lasers, have made procedures more effective and safer, enhancing their popularity among patients and practitioners alike.
Regionally, North America holds a dominant share of the global photo rejuvenation equipment market, attributed to a high concentration of aesthetic treatment centers and a growing number of individuals opting for cosmetic procedures. The market in Europe is also witnessing significant growth, driven by increasing consumer awareness and the presence of well-established healthcare infrastructure. Meanwhile, the Asia Pacific region is anticipated to register the highest growth rate due to rising disposable incomes, increasing adoption of cosmetic treatments, and a growing inclination toward non-invasive procedures in countries like China, India, and Japan. As the market evolves, manufacturers are focusing on innovative product development and strategic partnerships to enhance their competitive edge. The introduction of new technologies and treatment modalities is likely to cater to diverse consumer needs, further stimulating market growth. Additionally, ongoing education about the benefits of non-invasive procedures is expected to increase patient engagement and drive adoption rates. Overall, the future of the photo rejuvenation equipment market looks promising as it adapts to changing consumer preferences and technological advancements. The synergy between aesthetic demand and innovative treatment options will likely sustain its upward trajectory in the coming years.
Market Drivers:
Increasing Demand for Non-Invasive Aesthetic Procedures
One of the key drivers of the photo rejuvenation equipment market is the growing preference for non-invasive cosmetic treatments. As consumers seek effective solutions to rejuvenate their skin without undergoing surgical procedures, photo rejuvenation has gained widespread appeal. The minimal downtime and lower risk compared to traditional surgeries make it an attractive option for individuals looking to improve their appearance with minimal disruption to their daily lives. For instance, A report by the American Society of Plastic Surgeons revealed that non-invasive procedures such as laser skin resurfacing increased by 15% in the last year.
Technological Advancements in Photo rejuvenation Devices
Technological innovations in photo rejuvenation equipment are significantly contributing to the market’s growth. Advancements in laser and light-based technologies, such as Intense Pulsed Light (IPL), fractional lasers, and LED therapy, have improved the efficacy and safety of these treatments. These innovations enable practitioners to offer tailored treatments, enhancing patient outcomes and satisfaction. For instance, the introduction of the Lumenis M22 IPL device has been shown to reduce pigmentation by 80% after just three treatments.As a result, both consumers and healthcare providers are increasingly adopting these advanced devices for a variety of skin concerns, from acne to signs of aging.
Rising Awareness of Aesthetic Treatments
Growing awareness about aesthetic procedures, fueled by media, social platforms, and the increasing acceptance of cosmetic treatments, is driving demand for photo rejuvenation therapies. More individuals are becoming conscious of their skin health and appearance, with a shift towards preventative care. This heightened awareness, along with a desire for youthful and radiant skin, is leading to a surge in the number of people seeking non-invasive treatments like photo rejuvenation. For instance, A survey by RealSelf indicated that 67% of respondents are considering non-invasive aesthetic treatments within the next year.
Expanding Middle-Class Population in Emerging Markets
The expanding middle class in emerging markets is another significant driver for the photo rejuvenation equipment market. As disposable incomes rise in regions like Asia-Pacific and Latin America, more people are investing in skincare and aesthetic treatments. In countries like China, India, and Brazil, the demand for non-invasive cosmetic procedures is increasing rapidly. With access to advanced photo rejuvenation technologies, these regions are becoming key growth areas for the global market. For instance, In China, the number of aesthetic clinics has increased by 20% annually, driven by the growing middle-class population seeking cosmetic treatments.
Market Trends:
Integration of Multi-Technology Platforms
One of the current trends in the photo rejuvenation equipment market is the integration of multiple technologies into a single device. Modern photo rejuvenation devices now combine various technologies such as Intense Pulsed Light (IPL), fractional lasers, and radiofrequency, providing practitioners with versatile tools to address a range of skin concerns. For instance, the SmartXEL CO2 fractional Laser delivers laser energy using a double pulse called SmartPulse, while the Astra RF device uses radiofrequency micro needling to stimulate collagen and elastin. This integration allows for more customized treatments, improving efficacy and patient satisfaction. By offering multiple treatment options in a single platform, these devices not only enhance performance but also increase convenience for both healthcare providers and patients.
Minimally Invasive and Customized Treatments
There is a notable shift toward more personalized and minimally invasive photo rejuvenation procedures. With an increasing demand for individualized treatment plans, professionals are focusing on tailoring treatments based on specific skin types and concerns. This trend is driven by advancements in diagnostic tools, which allow practitioners to better understand skin conditions and deliver more targeted therapies. Minimally invasive options that promise quicker recovery times and reduced discomfort are also gaining popularity among patients who want effective results without extensive downtime. For example, IPL treatments are non-invasive and have minimal side effects, making them a preferred choice for treating skin discoloration and photoaging.
Growing Adoption of Home-Use Devices
Another emerging trend is the growing availability and adoption of at-home photo rejuvenation devices. With rising consumer demand for convenience, several brands are introducing devices designed for personal use. These devices, while not as powerful as those used in professional settings, offer a cost-effective and accessible solution for individuals looking to maintain skin health between professional treatments. The trend towards at-home devices reflects the broader shift in consumer behavior, where individuals seek to incorporate skincare routines into their daily lives. For instance, LED phototherapy devices are becoming popular for at-home use due to their safety and ease of use.
Focus on Safety and FDA Approval
Safety is a critical focus within the photo rejuvenation equipment market, as consumers prioritize effective yet safe treatment options. Manufacturers are increasingly ensuring their products are FDA-approved, a key indicator of safety and reliability. The growing emphasis on regulatory compliance is driven by rising consumer concerns over the side effects of treatments and the desire for results with minimal risk. This trend aligns with the broader industry focus on enhancing the safety and comfort of photo rejuvenation therapies. For example, FDA-approved IPL devices are widely used for their proven safety and efficacy in treating various skin conditions.
Market Challenges Analysis:
High Cost of Advanced Equipment
One of the primary challenges in the photo rejuvenation equipment market is the high cost of advanced devices. The technological complexity and innovation involved in developing effective photo rejuvenation equipment contribute to their premium pricing. These costs can limit access for smaller clinics or practitioners, particularly in emerging markets with lower disposable incomes. Additionally, the high upfront investment required to purchase such equipment may deter potential entrants into the market, impacting overall growth and limiting competition. Regulatory compliance presents another significant challenge. Photo rejuvenation devices must adhere to stringent safety standards, which vary across regions. In many countries, manufacturers must navigate complex approval processes to obtain certifications, such as FDA approval in the U.S. These regulatory requirements can delay product launches and increase operational costs. Moreover, safety concerns related to improper use of these devices or adverse reactions during treatments can deter consumers from opting for photo rejuvenation procedures. Ensuring consistent compliance with evolving regulations and maintaining safety standards are ongoing challenges for market participants.
Consumer Education and Misconceptions
Despite the growing popularity of photo rejuvenation treatments, consumer education remains a challenge. Many potential patients are still unaware of the full range of benefits and possible risks associated with photo rejuvenation. Misconceptions about the efficacy, safety, and costs of treatments may result in hesitation or reluctance to adopt these procedures. Educating consumers about the science behind photo rejuvenation devices, the expected outcomes, and the qualifications of practitioners is essential for addressing these challenges and fostering greater market penetration. The photo rejuvenation equipment market faces intense competition from alternative skin rejuvenation therapies. Surgical procedures, such as facelifts and Botox, as well as other non-invasive treatments like chemical peels and dermal fillers, offer different approaches to achieving youthful skin. This competition could limit the market share of photo rejuvenation devices, particularly if consumers perceive alternative treatments as more effective or less costly. Companies must continuously innovate and differentiate their offerings to maintain a competitive edge in this crowded market.
Market Segmentation Analysis:
By Product
The photo rejuvenation equipment market can be segmented by product type into laser-based devices, intense pulsed light (IPL) devices, and light-emitting diode (LED) devices. Laser-based devices dominate the market due to their advanced precision and efficacy in treating various skin concerns, including wrinkles, acne, and hyperpigmentation. IPL devices are also gaining traction, offering versatility in treating different skin types and conditions. LED devices, while less invasive, are increasingly popular for their ease of use and minimal side effects, making them ideal for home-use applications.
By Modality
The market is further segmented by modality into standalone devices and multi-platform devices. Standalone devices are designed for specific treatments, while multi-platform devices combine various technologies, such as lasers and IPL, offering more flexibility and treatment options in a single unit. The multi-platform modality is witnessing higher demand due to its ability to provide tailored solutions for different skin concerns, attracting both professional and consumer markets.
By End-User
The key end-users in the photo rejuvenation equipment market include dermatology clinics, cosmetic surgery centers, and home users. Dermatology clinics and cosmetic surgery centers dominate the market, as these professional settings are equipped with advanced devices capable of performing a wide range of photo rejuvenation procedures. However, the growing trend of at-home skincare treatments is driving the demand for home-use devices, offering greater accessibility to non-invasive skin rejuvenation solutions.
Segmentations:
By Product
- Laser-based Devices
- Intense Pulsed Light (IPL) Devices
- Light Emitting Diode (LED) Devices
By Modality
- Standalone Devices
- Multi-Platform Devices
By End-User
- Dermatology Clinics
- Cosmetic Surgery Centers
- Home Users
By Region
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis:
North America
North America holds the largest share of the global photo rejuvenation equipment market, accounting for 40% of the market share. The dominance of this region is primarily due to the high demand for aesthetic treatments and the presence of advanced healthcare infrastructure. The U.S. is the key contributor to this market segment, with a growing consumer base seeking non-invasive skin rejuvenation solutions. The increasing popularity of anti-aging treatments and skin care innovations, along with a high concentration of dermatology clinics and cosmetic centers, further drives the growth of the market. Additionally, the adoption of advanced photo rejuvenation technologies, such as fractional lasers and IPL devices, contributes significantly to market expansion.
Europe
Europe holds a 30% market share in the global photo rejuvenation equipment market, with countries like Germany, the U.K., and France leading the demand for advanced aesthetic treatments. The region benefits from a well-established medical aesthetic industry and a high level of awareness regarding skincare. The demand for photo rejuvenation devices is driven by both aging demographics and increased interest in non-invasive aesthetic procedures. Furthermore, the presence of key market players and a growing trend toward preventive skincare solutions bolster the region’s position in the global market.
Asia-Pacific
The Asia-Pacific region is experiencing the fastest growth in the photo rejuvenation equipment market, capturing 20% of the market share. The rapid rise in disposable income, a burgeoning middle class, and increased awareness about aesthetic treatments in countries like China, India, and Japan are driving the market in this region. The demand for skin rejuvenation therapies is further fueled by the growing preference for non-invasive procedures due to their lower costs and minimal downtime. Additionally, an increase in medical tourism and the availability of advanced equipment at competitive prices contribute to the region’s fast-paced growth.
Latin America
Latin America holds a 7% market share, with Brazil and Mexico being the primary contributors. The demand for photo rejuvenation equipment in this region is steadily growing, driven by increasing disposable incomes, changing lifestyles, and rising consumer awareness of skincare and aesthetics. The market in Latin America is characterized by a growing preference for non-invasive aesthetic procedures, with consumers opting for photo rejuvenation therapies as an effective alternative to traditional surgical treatments.
Middle East & Africa
The Middle East and Africa (MEA) region accounts for 3% of the global photo rejuvenation equipment market share. This region is experiencing steady growth due to a rising focus on cosmetic procedures, particularly in countries like the UAE and Saudi Arabia, where a high demand for aesthetic treatments is observed. The market in this region is expected to expand further as disposable incomes rise, and as medical tourism increases, attracting individuals seeking advanced, non-invasive treatments.
Key Player Analysis:
- Lumenis Ltd.
- Candela Corporation
- Syneron Medical Ltd.
- Cutera, Inc.
- Alma Lasers
- Solta Medical
- Photomedex, Inc.
- Sciton, Inc.
- Lutronic Corporation
- Asclepion Laser Technologies
Competitive Analysis:
The photo rejuvenation equipment market is highly competitive, with key players focusing on innovation, product differentiation, and strategic partnerships to maintain their market share. Leading companies such as Lumenis Ltd., Candela Corporation, and Syneron Medical Ltd. continue to drive market growth through the development of advanced technologies, including fractional lasers, IPL systems, and multi-platform devices. For instance, Lumenis invested $1.07 billion in its Aesthetics and Vision businesses following the sale of its Surgical business to Boston Scientific. These companies invest significantly in research and development to improve treatment efficacy, patient safety, and the user experience. Additionally, market players are increasingly adopting mergers, acquisitions, and collaborations to enhance their product portfolios and expand their geographic presence. With growing demand for non-invasive procedures, competition is intensifying, especially in emerging markets where smaller, cost-effective devices are gaining traction. Companies that focus on affordability, safety, and performance are positioned to capitalize on this expanding market.
Recent Developments:
- In August 2024, Lumenis secured U.S. Food and Drug Administration 510(k) clearance for the percutaneous treatment of facial wrinkles in patients with Fitzpatrick Skin Types (FST) I-IV using its Matrix Pro RF micro needling applicator.
- In January 2024, Candela introduced the Nordlys IPL and laser devices, which feature Selective Waveband Technology (SWT) intense pulsed light (IPL), along with two non-ablative fractional lasers (1550 nm and 1940 nm) and an Nd:YAG 1064 nm laser, designed to address a variety of skin concerns.
- In February 2024, Cutera announced the international limited commercial release of AviClear, the first energy-based device FDA-cleared for the long-term treatment of mild, moderate, and severe acne. This device uses a 1726nm laser to target and suppress sebum production.
- In June 2023, Candela received FDA clearance for the Vbeam 595 nm pulsed dye laser, which is considered the gold standard for vascular treatment and port wine stains and hemangiomas in the pediatric population.
Market Concentration & Characteristics:
The photo rejuvenation equipment market exhibits moderate concentration, with a few key players commanding significant market share, such as Lumenis Ltd., Candela Corporation, and Syneron Medical Ltd. These companies dominate through continuous technological advancements, broad product portfolios, and strong brand recognition. However, the market also features a growing number of smaller players, particularly in emerging regions, offering cost-effective solutions that cater to a wider consumer base. The market characteristics are marked by rapid technological innovation, with a focus on improving treatment efficacy, safety, and user experience. Moreover, the increasing demand for non-invasive aesthetic procedures drives market dynamics, prompting both established and new players to compete based on product performance, regulatory compliance, and cost efficiency. As such, companies must balance innovation with affordability to capture and maintain their market positions in a competitive and evolving landscape.
Report Coverage:
The research report offers an in-depth analysis based on product, modality, end-user and region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- The demand for non-invasive aesthetic treatments will continue to rise, driving the adoption of photo rejuvenation devices across various demographics.
- Technological advancements in laser, IPL, and LED technologies will lead to more effective and versatile photo rejuvenation devices, improving treatment outcomes.
- The increasing popularity of at-home photo rejuvenation devices will expand market reach to consumers seeking affordable and convenient options.
- Growing awareness about skin health and anti-aging treatments will fuel the demand for photo rejuvenation procedures, particularly among aging populations.
- Dermatology clinics and cosmetic surgery centers will remain the dominant end-users, but the rise of home-use devices will diversify the market.
- Multi-platform photo rejuvenation devices will gain further traction due to their ability to address multiple skin concerns with a single device.
- Expansion into emerging markets, driven by rising disposable incomes and an increasing middle class, will present new growth opportunities.
- Stringent regulatory standards and increasing safety concerns will prompt manufacturers to prioritize FDA-approved devices and compliance with local regulations.
- The rise of medical tourism will drive the demand for advanced photo rejuvenation treatments in regions like Asia-Pacific and the Middle East.
- Competitive pressure will lead to more collaborations, partnerships, and product innovations, further enhancing market dynamics and customer satisfaction.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the projected growth of the photo rejuvenation equipment market?
What factors are driving the growth of the photo rejuvenation equipment market?
Which region holds the largest market share in photo rejuvenation equipment?
Which region is expected to experience the highest growth in the photo rejuvenation equipment market?
What types of technologies are being used in photo rejuvenation treatments?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Photo Rejuvenation Equipment Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Photo Rejuvenation Equipment Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 2,194.30 million → 2032: USD 3,742.11 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Photo Rejuvenation Equipment Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Photo Rejuvenation Equipment Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Photo Rejuvenation Equipment Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Photo Rejuvenation Equipment Market Drivers
- 3.3 Photo Rejuvenation Equipment Market Restraints & Challenges
- 3.4 Photo Rejuvenation Equipment Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Photo Rejuvenation Equipment Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Photo Rejuvenation Equipment Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Photo Rejuvenation Equipment category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Photo Rejuvenation Equipment Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Photo Rejuvenation Equipment Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Photo Rejuvenation Equipment market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Photo Rejuvenation Equipment Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Photo Rejuvenation Equipment Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Photo Rejuvenation Equipment Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Photo Rejuvenation Equipment (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Photo Rejuvenation Equipment Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Photo Rejuvenation Equipment Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Photo Rejuvenation Equipment Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Photo Rejuvenation Equipment Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Photo Rejuvenation Equipment Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Photo Rejuvenation Equipment Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Photo Rejuvenation Equipment Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Photo Rejuvenation Equipment Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Photo Rejuvenation Equipment Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
