
Market Overview
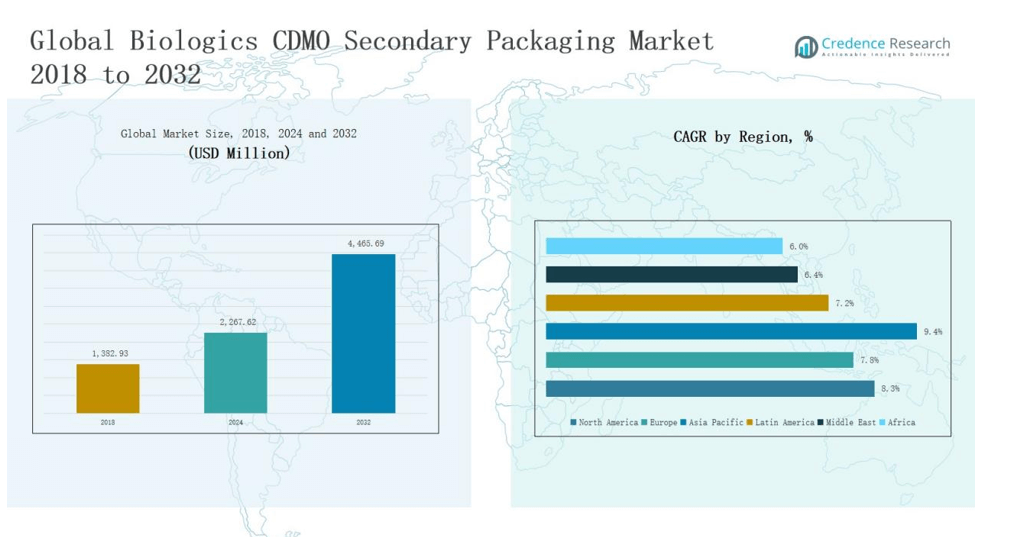
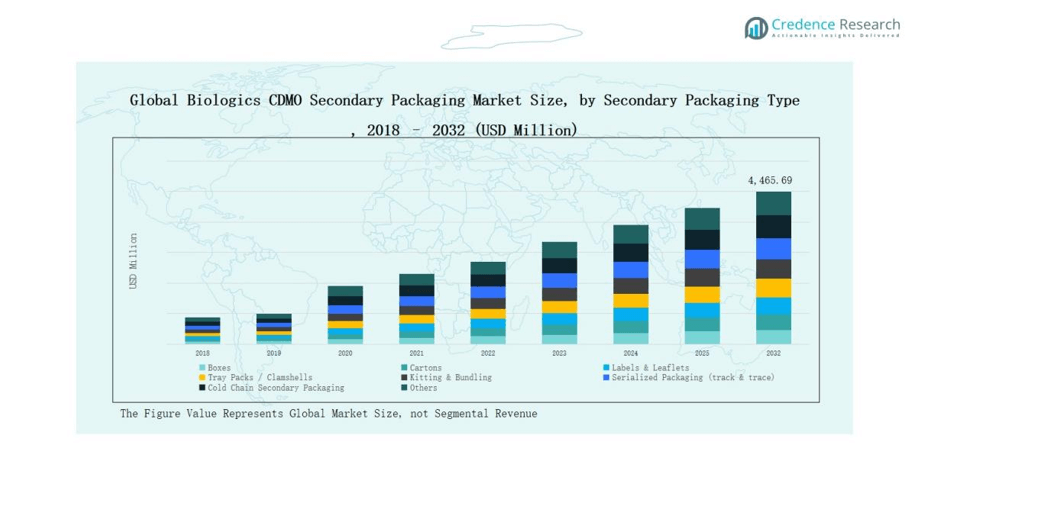
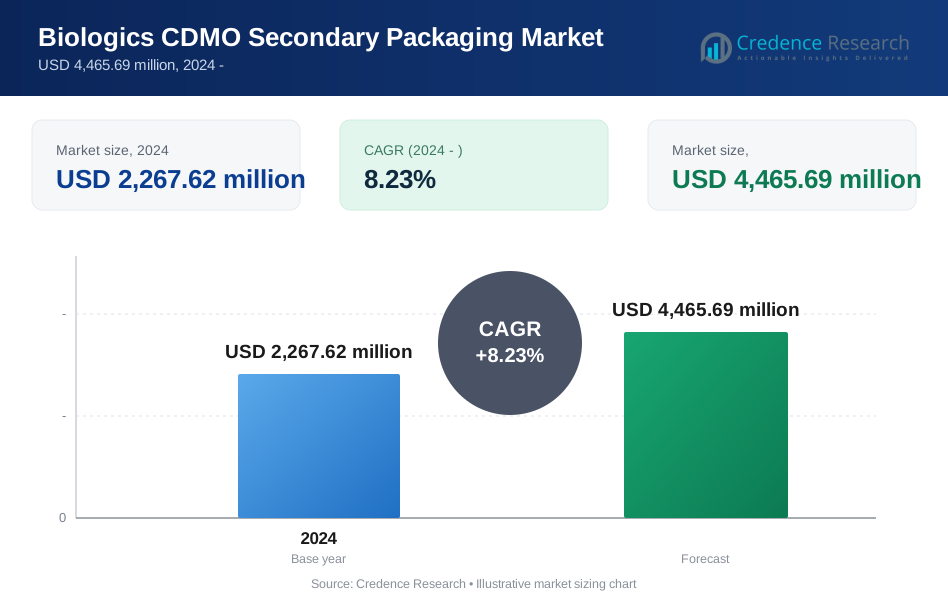
Global Biologics CDMO Secondary Packaging Market size was valued at USD 1,382.93 million in 2018 to USD 2,267.62 million in 2024 and is anticipated to reach USD 4,465.69 million by 2032, at a CAGR of 8.23% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Biologics CDMO Secondary Packaging Market Size 2024 | USD 2,267.62 million |
| Biologics CDMO Secondary Packaging Market, CAGR | 8.23% |
| Biologics CDMO Secondary Packaging Market Size 2032 | USD 4,465.69 million |
The Global Biologics CDMO Secondary Packaging Market is shaped by leading players including WuXi Biologics, FUJIFILM Diosynth, Samsung Biologics, Thermo Fisher Scientific, Catalent, Lonza, PCI Pharma Services, Vetter Pharma, Almac Group, Sharp, and Recipharm. These companies dominate through advanced serialization, cold chain packaging, and patient-centric kitting solutions that align with global compliance standards. Their strategic investments in digital packaging technologies and regional expansions strengthen competitive positioning. North America leads the market with a 37% share in 2024, supported by strong pharmaceutical outsourcing, biologics pipelines, and strict regulatory frameworks, establishing it as the most influential region globally.
Market Insights
- The Global Biologics CDMO Secondary Packaging Market was valued at USD 2,267.62 million in 2024 and is projected to reach USD 4,465.69 million by 2032.
- Boxes lead with 28% share among secondary packaging types, followed by cartons at 18% and labels and leaflets at 14%, reflecting compliance and safety requirements.
- Vials dominate with 32% share in compatible primary packaging, while prefilled syringes (18%) and ampoules (15%) also drive demand through vaccines and self-administration formats.
- North America holds 37% share in 2024, supported by strong outsourcing, R&D, vaccine production, and advanced serialization adoption across biologics supply chains.
- Key players such as WuXi Biologics, FUJIFILM Diosynth, Samsung Biologics, Thermo Fisher, Catalent, Lonza, PCI Pharma Services, Vetter, and Almac Group strengthen market competitiveness.
Market Segment Insights
By Secondary Packaging Type
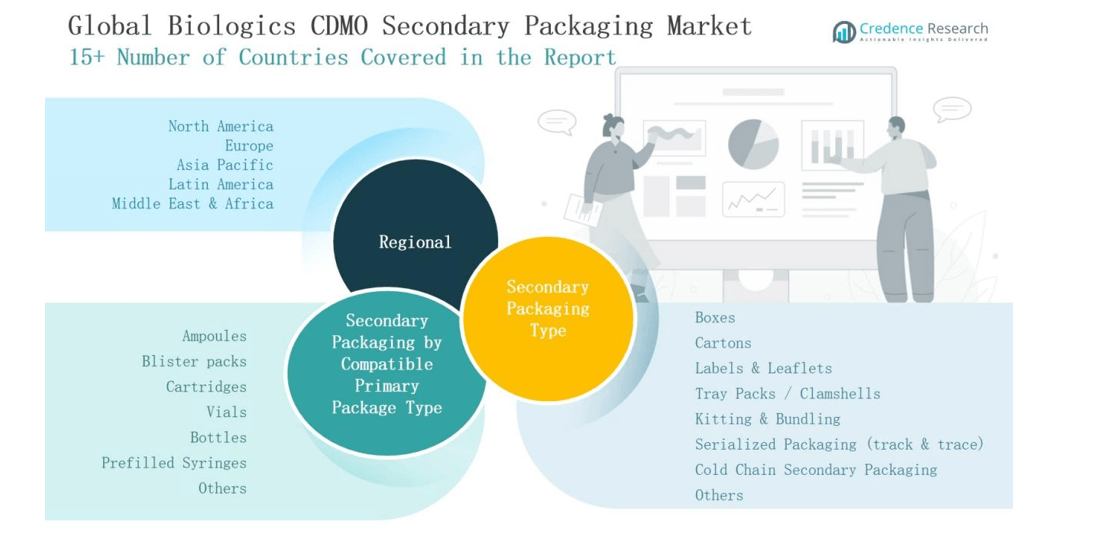
Boxes dominate the Global Biologics CDMO Secondary Packaging Market, holding about 28% share. Their strength lies in broad applicability, cost efficiency, and ability to protect bulk biologics during storage and transport. Cartons follow with 18% share, driven by retail-ready formats and anti-counterfeit features, while labels and leaflets account for 14%, supported by regulatory mandates for patient safety and multilingual compliance. Prefilled syringe kits, serialization, and cold chain packaging continue to expand, reflecting the growing need for patient-centric delivery and stringent traceability.
- For instance, WuXi Biologics expanded its prefilled syringe assembly and secondary packaging capability at its Germany facility to meet rising demand for patient-ready biologics delivery formats.
By Compatible Primary Package Type
Vials lead this segment with a commanding 32% share, fueled by their extensive use in vaccines and monoclonal antibodies. Prefilled syringes hold about 18% share, benefiting from convenience and rising home-care adoption. Ampoules and blister packs remain important with 15% and 12% shares, respectively, while cartridges secure 10% due to the popularity of auto-injectors and pens. Bottles (8%) and other novel formats (5%) play supportive roles, particularly in advanced therapies and clinical trials requiring customized secondary packaging.
- For instance, West Pharmaceutical Services launched NovaPure cartridges specifically designed for auto-injectors and insulin pens, reflecting the increasing demand for cartridge-based delivery in biologics.
Market Overview
Rising Demand for Biologics and Vaccines
The expansion of biologics and vaccine pipelines fuels steady growth in the Global Biologics CDMO Secondary Packaging Market. Increased prevalence of chronic diseases and infectious outbreaks drives large-scale production of injectable therapies. This creates significant demand for reliable packaging solutions such as boxes, vials, and cold chain formats to ensure product integrity. CDMOs play a vital role by offering scalable and compliant secondary packaging tailored for biologics. The segment benefits from heightened pharmaceutical outsourcing trends, ensuring efficient market access.
- For instance, Argonaut Manufacturing Services expanded its Carlsbad facility with a new filling line capable of supporting clinical and commercial packaging of vials, syringes, and cartridges to more than quadruple its existing fill-finish operations.
Regulatory Emphasis on Serialization and Traceability
Global regulations mandating serialization, tamper-evidence, and secure labeling drive rapid adoption of advanced packaging technologies. Biologics CDMOs integrate serialization solutions into cartons, labels, and kitting formats to combat counterfeiting and ensure supply chain transparency. Track-and-trace requirements across North America, Europe, and Asia-Pacific create strong opportunities for CDMOs specializing in compliant packaging. This driver significantly boosts investments in digital packaging infrastructure and software-enabled monitoring, positioning secondary packaging as a critical enabler of regulatory adherence and patient safety.
- For instance, Optel Group launched an integrated software platform that supports multi-level serialization and aggregation for biologics CDMOs, boosting regulatory compliance and supply chain transparency.
Growth of Cold Chain Logistics for Advanced Therapies
The rise of temperature-sensitive biologics, including cell and gene therapies, is expanding demand for cold chain secondary packaging. Specialized formats such as insulated shippers and phase-change packs are essential for maintaining stability during global distribution. CDMOs invest heavily in cryogenic packaging capabilities to meet the needs of clinical trials and commercial supply. As personalized medicines and specialty biologics expand, cold chain solutions create sustained growth. This driver highlights the market’s alignment with evolving therapeutic portfolios and patient-centric delivery models.
Key Trends & Opportunities
Shift Toward Patient-Centric and Home-Care Packaging
Patient convenience is reshaping biologics packaging, creating opportunities for kitting and prefilled syringe bundles. With more biologics designed for self-administration, CDMOs are focusing on secondary packaging that combines drug, device, and instructions in integrated kits. This trend supports adherence, reduces dosing errors, and meets healthcare system goals of decentralizing care. It also opens opportunities for customized formats tailored to patient populations, boosting demand for flexible and innovative packaging solutions.
- For instance, in April 2025, PCI Pharma Services announced the acquisition of Ajinomoto Althea, expanding its flexible biologics manufacturing capabilities to include new facilities for prefilled syringes and cartridges.
Digital Integration and Smart Packaging Solutions
Adoption of digital technologies in secondary packaging is rising, with opportunities in smart labeling, real-time monitoring, and blockchain-based traceability. Biologics CDMOs are exploring smart packages embedded with QR codes, NFC tags, and sensors to track temperature and authenticity. These innovations not only ensure compliance but also enhance patient engagement and supply chain transparency. Growing investments in digital infrastructure create opportunities for CDMOs to differentiate offerings and capture contracts from global biopharma companies.
- For instance, Amcor partnered with digital serialization company Kezzler to offer MaXQ, a solution for embedding unique digital codes into packaging to enable authentication, consumer interaction, and supply chain tracking.
Key Challenges
High Capital Investment Requirements
Developing compliant secondary packaging facilities involves substantial capital outlays in equipment, serialization systems, and cold chain infrastructure. Smaller CDMOs often face entry barriers due to high upfront costs, limiting competitive participation. Continuous upgrades to meet evolving regulatory mandates further strain budgets. These financial demands challenge scalability, particularly for mid-tier CDMOs aiming to expand global reach and serve high-volume biologics programs.
Complex Regulatory Landscape Across Regions
The biologics secondary packaging industry faces highly fragmented regulations, varying across North America, Europe, and emerging markets. Compliance with diverse serialization rules, labeling standards, and cold chain requirements complicates global distribution strategies. CDMOs must maintain constant vigilance and adapt operations to multiple frameworks, raising operational complexity and costs. This challenge can delay time-to-market for biologics, making regulatory adaptability a key competitive necessity.
Supply Chain Disruptions and Material Constraints
Volatility in supply chains, including shortages of specialized packaging materials, creates a major challenge. Rising costs of sustainable cartons, labels, and insulated packaging strain margins for CDMOs. Geopolitical tensions, logistics delays, and energy costs further affect availability and pricing of raw materials. These constraints threaten timely delivery of biologics, especially in cold chain-sensitive shipments, forcing CDMOs to adopt risk-mitigation strategies and diversify supplier networks.
Regional Analysis
North America
North America dominates the Global Biologics CDMO Secondary Packaging Market with a 37% share in 2024. The region’s leadership is driven by strong pharmaceutical outsourcing, advanced biologics pipelines, and strict regulatory compliance requirements. The U.S. remains the largest contributor due to extensive biologics R&D, vaccine production, and adoption of serialization technologies. Canada and Mexico provide supportive growth through expanding manufacturing and logistics capabilities. With a CAGR of 8.3%, the region is expected to nearly double its market size by 2032, supported by growing demand for cold chain and patient-centric packaging solutions.
Europe
Europe holds a 16% share in 2024, supported by a strong pharmaceutical base in Germany, France, and the UK. The region benefits from stringent packaging regulations that drive adoption of serialization, labeling, and anti-counterfeit solutions. Expansion in contract packaging services is further encouraged by a large generics and biosimilars market. Growth is moderate with a CAGR of 7.0%, reflecting a stable but competitive landscape. By 2032, Europe is projected to achieve over USD 750 million in revenue, fueled by continued biologics innovation and outsourcing trends.
Asia Pacific
Asia Pacific is the fastest-growing region, capturing 26% share in 2024 and registering a CAGR of 9.4%. China, Japan, South Korea, and India drive expansion through growing biologics manufacturing, clinical trials, and outsourcing activities. Investments in cold chain infrastructure and serialization compliance are accelerating adoption of advanced packaging solutions. Rising demand for vaccines, cell therapies, and biosimilars enhances the region’s role as a global manufacturing hub. By 2032, Asia Pacific is projected to lead growth momentum, reaching nearly USD 1.5 billion in revenue.
Latin America
Latin America contributes 4% share in 2024, with Brazil and Mexico leading demand. Growth is primarily supported by expanding pharmaceutical manufacturing capacity and increasing adoption of CDMO services. Regulatory modernization and the need for cost-effective packaging drive outsourcing trends across the region. Despite a smaller base, the market shows resilience with a CAGR of 6.5%, expected to reach nearly USD 180 million by 2032. Cold chain packaging for vaccines and biologics is emerging as a key growth driver in this region.
Middle East
The Middle East accounts for 2% share in 2024, with a steady CAGR of 5.3%. Countries such as Saudi Arabia, UAE, and Turkey invest in healthcare infrastructure and biopharmaceutical facilities, creating opportunities for CDMOs. Growth is driven by the adoption of serialization and the expansion of distribution networks for biologics. However, reliance on imports and limited manufacturing scale constrain rapid expansion. By 2032, the market is projected to surpass USD 74 million, supported by increasing government focus on healthcare security.
Africa
Africa holds 1% share in 2024, reflecting its nascent stage in the biologics CDMO secondary packaging market. South Africa and Egypt lead adoption, while the rest of the region is gradually building capacity. The region grows at a CAGR of 4.5%, supported by vaccine programs, donor-funded health initiatives, and rising pharmaceutical investments. Despite challenges such as infrastructure gaps, opportunities lie in cold chain packaging and partnerships with global CDMOs. By 2032, Africa is expected to achieve USD 49 million, highlighting steady but gradual market growth.
Market Segmentations:
By Secondary Packaging Type
- Boxes
- Cartons
- Labels & Leaflets
- Tray Packs / Clamshells
- Kitting & Bundling
- Serialized Packaging (Track & Trace)
- Cold Chain Secondary Packaging
- Others
By Compatible Primary Package Type
- Ampoules
- Blister Packs
- Cartridges
- Vials
- Bottles
- Prefilled Syringes
- Others
By Region
- North America
- U.S.
- Canada
- Mexico
- Europe
- UK
- France
- Germany
- Italy
- Spain
- Russia
- Belgium
- Netherlands
- Austria
- Sweden
- Poland
- Denmark
- Switzerland
- Rest of Europe
- Asia Pacific
- China
- Japan
- South Korea
- India
- Australia
- Thailand
- Indonesia
- Vietnam
- Malaysia
- Philippines
- Taiwan
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Peru
- Chile
- Colombia
- Rest of Latin America
- Middle East
- UAE
- KSA
- Israel
- Turkey
- Iran
- Rest of Middle East
- Africa
- Egypt
- Nigeria
- Algeria
- Morocco
- Rest of Africa
Competitive Landscape
The Global Biologics CDMO Secondary Packaging Market is moderately consolidated, with a mix of global leaders and regional specialists competing on scale, technology, and compliance capabilities. Key players such as WuXi Biologics, FUJIFILM Diosynth, Samsung Biologics, Thermo Fisher Scientific, Catalent, Lonza, and PCI Pharma Services dominate through integrated service portfolios spanning clinical to commercial packaging. Their strengths lie in serialization expertise, cold chain packaging, and advanced kitting solutions, enabling them to meet stringent regulatory and client requirements. Mid-tier firms and regional CDMOs compete by offering cost-effective, flexible, and niche services tailored to emerging markets. Strategic partnerships, expansions in Asia-Pacific, and investments in digital packaging technologies are shaping the competitive dynamics. Growing demand for patient-centric and home-care packaging formats further intensifies rivalry, pushing companies to differentiate through innovation and end-to-end supply chain integration. The market remains dynamic, with M&A activity and infrastructure upgrades reinforcing competitive positioning globally.
Key Players
- WuXi Biologics (Cayman) Inc.
- FUJIFILM Diosynth Biotechnologies U.S.A. Inc.
- Samsung Biologics Co. Ltd.
- Thermo Fisher Scientific Inc.
- Catalent, Inc.
- Lonza Group
- PCI Pharma Services
- Vetter Pharma International GmbH
- Almac Group
- Sharp (part of UDG Healthcare)
- Recipharm AB
- Siegfried Holding AG
- Baxter BioPharma Solutions
Recent Developments
- In March 2025, Syngene International acquired Emergent BioSolutions’ Baltimore biologics facility for US $36.5 million, boosting its bioreactor capacity and supporting biologics secondary packaging needs.
- In March 2024, SMC Ltd. opened a new facility in North Carolina expanding sterile fill-finish capabilities, including secondary packaging services, reinforcing their pharmaceutical services and manufacturing footprint.
- In June 2025, Zydus Lifesciences agreed to acquire Agenus Inc.’s biologics manufacturing facilities in California, marking its entry into the biologics CDMO space with potential expansion into secondary packaging services.
- In April 2025, FUJIFILM Biotechnologies entered a 10-year manufacturing agreement with Regeneron Pharmaceuticals, valued at over USD 3 billion, to expand U.S. biologics production and related packaging demand.
Report Coverage
The research report offers an in-depth analysis based on Secondary Packaging Type, Compatible Primary Package Type and Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Demand for biologics will increase reliance on specialized secondary packaging solutions.
- Serialization and track-and-trace adoption will expand across all major regions.
- Cold chain packaging will grow with rising cell and gene therapy pipelines.
- Patient-centric kits will gain traction as self-administration becomes more common.
- Digital and smart packaging integration will enhance compliance and transparency.
- Sustainability initiatives will drive adoption of recyclable and eco-friendly packaging formats.
- Outsourcing of packaging to CDMOs will deepen as pharma firms streamline operations.
- Regional CDMOs will strengthen positions by offering flexible and cost-efficient services.
- Strategic collaborations and acquisitions will shape market consolidation trends.
- Emerging markets will become important growth hubs for packaging innovation and supply.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Biologics CDMO Secondary Packaging Market?
What are the key segments within the Biologics CDMO Secondary Packaging Market?
What are some challenges faced by the Biologics CDMO Secondary Packaging Market?
Who are the major players in the Biologics CDMO Secondary Packaging Market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Biologics CDMO Secondary Packaging Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to the forecast period)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Biologics CDMO Secondary Packaging Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (the forecast period) (2024: USD 2,267.62 million → forecast year: USD 4,465.69 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Biologics CDMO Secondary Packaging Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs.
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Biologics CDMO Secondary Packaging Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Biologics CDMO Secondary Packaging Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Biologics CDMO Secondary Packaging Market Drivers
- 3.3 Biologics CDMO Secondary Packaging Market Restraints & Challenges
- 3.4 Biologics CDMO Secondary Packaging Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Biologics CDMO Secondary Packaging Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Biologics CDMO Secondary Packaging Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Biologics CDMO Secondary Packaging category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Biologics CDMO Secondary Packaging Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through the forecast period
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through the forecast period
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Biologics CDMO Secondary Packaging Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Biologics CDMO Secondary Packaging market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Biologics CDMO Secondary Packaging Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Biologics CDMO Secondary Packaging Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Biologics CDMO Secondary Packaging Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Biologics CDMO Secondary Packaging (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Biologics CDMO Secondary Packaging Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Biologics CDMO Secondary Packaging Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & )
- 7.1.2 Channel Mix Evolution (the forecast period)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through the forecast period
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Biologics CDMO Secondary Packaging Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Biologics CDMO Secondary Packaging Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Biologics CDMO Secondary Packaging Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Biologics CDMO Secondary Packaging Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Biologics CDMO Secondary Packaging Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Biologics CDMO Secondary Packaging Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Biologics CDMO Secondary Packaging Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
