
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
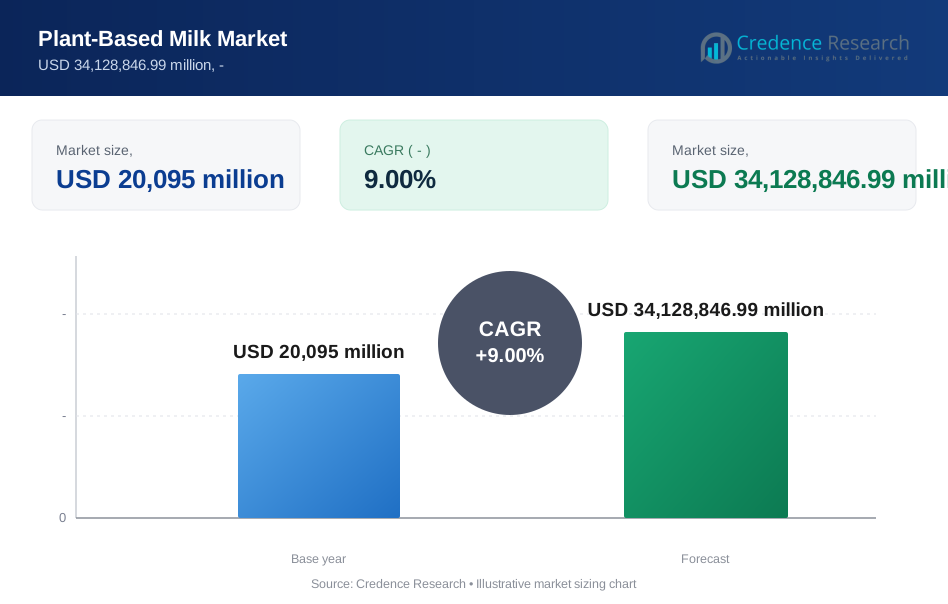
| Plant-Based Milk Market Size 2023 | USD 20,095 million |
| Plant-Based Milk Market , CAGR | 9.00% |
| Plant-Based Milk Market Size 2032 | USD 34,128,846.99 million |
Market Overview
The Plant-Based Milk Market is projected to grow from USD 20,095 million in 2024 to USD 34,128,846.99 million by 2032, reflecting a compound annual growth rate (CAGR) of 9.00%.
The Plant-Based Milk Market is driven by increasing consumer awareness of health and wellness, alongside rising lactose intolerance and dietary restrictions favoring plant-based diets. Innovation in flavors and fortified options continues to attract a broader consumer base. Environmental concerns also play a significant role, as plant-based milks typically require fewer resources and result in lower emissions than dairy products. These factors, combined with expanding retail availability and aggressive marketing strategies, are set to propel market growth.
The global Plant-Based Milk Market showcases significant geographical diversity with North America and Europe leading in terms of consumption due to high consumer awareness and a strong shift towards vegan and lactose-free diets. Asia-Pacific is rapidly growing, fueled by changing dietary habits and increasing health consciousness in countries like China and India. Key players shaping the market include Oatly Inc., Blue Diamond Growers, and Groupe Danone, each contributing through innovative product offerings and extensive distribution networks. These companies are pivotal in driving both regional and global market expansion through strategic partnerships, mergers, and product innovations.
Market Drivers
Health and Wellness Trends Driving Plant-Based Milk Demand
As health consciousness rises, more consumers are discovering lactose intolerance or allergies to dairy products, pushing them towards plant-based milk alternatives. For instance, according to the National Institute of Diabetes and Digestive and Kidney Diseases, approximately 68% of the global population has lactose malabsorption, making lactose-free alternatives highly appealing.These alternatives not only cater to these specific dietary restrictions but also offer significant nutritional benefits. They are typically lower in calories, cholesterol-free, and rich in essential nutrients, unlike traditional dairy milk. Moreover, there's an increasing consumer recognition of the connection between diet and chronic disease prevention, which further amplifies the shift towards plant-based options.
Impact of Veganism and Vegetarianism on Market Growth
The growing popularity of vegan and vegetarian diets significantly boosts the demand for plant-based milk products. For instance, a 2020 statistics shows there are 5% vegans, 20% flexitarian and 11% vegetarians around the globe. Consumers adhering to these dietary preferences are not just eliminating animal products for health reasons but are also driven by lifestyle choices that advocate for minimal animal harm. This cultural shift is creating a robust market for plant-based alternatives, as these consumers seek comprehensive replacements for dairy products, encompassing everything from milk to cheese and yogurt.
Environmental and Ethical Considerations Influence Choices
The production of plant-based milk is generally associated with a lower environmental footprint, which resonates well with eco-conscious consumers. This sustainability aspect, combined with heightened awareness of animal welfare and ethical considerations surrounding the dairy industry, compels more individuals to opt for plant-based milks. These factors are becoming increasingly decisive in consumer purchasing decisions, as they align with a broader trend of environmental responsibility and ethical consumption.
Innovation and Accessibility Expanding Consumer Base
Significant advances in food technology have improved the taste and texture of plant-based milks, making them comparable to dairy milk and appealing to a wider audience. The introduction of a diverse range of products, from almond and soy to oat and coconut milk, addresses various consumer tastes and dietary needs. Furthermore, the increased retail presence of these products in supermarkets and online platforms enhances consumer accessibility, ensuring that plant-based milks are an easy addition to daily routines, thereby supporting continued market growth.
Market Trends
Diversification and Innovation in Plant-Based Milk Products
The Plant-Based Milk Market is witnessing significant diversification as manufacturers extend beyond traditional almond, soy, and oat milk to incorporate novel varieties like pea, cashew, and rice milk. This expansion caters to a broader range of consumer preferences and dietary requirements. For example, the "lactose-free" claim is featured on 12.2% of plant-based milk products sold online globally, even higher than the 11.3% with a "dairy-free" claim. This focus on health benefits aligns with consumer preferences, as 42% of consumers globally say they follow a dairy-free diet for digestive health reasons. Additionally, there is a growing emphasis on fortifying these milks with functional ingredients such as additional nutrients, vitamins, and minerals, enhancing their appeal as healthful alternatives to dairy milk. The innovation doesn't stop at milk alone; the market is also seeing an increase in value-added products like plant-based yogurt, cheese, and ice cream, alongside ready-to-drink flavored and functional beverages. These developments not only meet the diverse tastes and dietary needs of consumers but also bolster the market’s growth by offering more comprehensive plant-based dairy alternatives.
Sustainability and Technological Advancements Driving Market Evolution
Sustainability remains a cornerstone of the Plant-Based Milk industry, with manufacturers adopting eco-friendly packaging and focusing on reducing the water footprint and carbon emissions associated with production. These initiatives reflect a commitment to minimizing environmental impact and aligning with consumer expectations for responsible practices. Moreover, the market is also benefiting from technological advancements that improve production processes, making them more efficient and cost-effective. These technologies are crucial in developing new and innovative plant-based milk products, further stimulating market growth. Additionally, as the market expands globally, companies are increasingly localizing products to suit regional tastes and preferences, ensuring relevance and accessibility in emerging markets where interest in plant-based products is rapidly growing.
Market Challenges Analysis
Supply Chain and Consumer Challenges in the Plant-Based Milk Market
The plant-based milk market faces significant challenges related to raw material availability and cost. Supply chain disruptions often lead to fluctuations in the availability of key plant-based raw materials, impacting production schedules and ultimately affecting pricing structures. For instance, 42% of global consumers say they are restricting their consumption of animal-based products, leading to increased demand for plant-based alternatives. Concurrently, as demand for these products increases, so too do the costs associated with procuring high-quality raw materials, placing upward pressure on final product prices. On the consumer front, taste and preference pose considerable hurdles. Many consumers remain loyal to dairy milk due to taste preferences, and replicating the exact taste and texture of dairy milk in plant-based alternatives is an ongoing challenge. Additionally, building consumer loyalty and strong brand preference is particularly challenging in a market that is not only competitive but also crowded with both new entrants and well-established players.
Regulatory and Competitive Pressures Complicate Market Dynamics
Navigating the regulatory landscape presents another layer of complexity. Plant-based milk producers must contend with stringent labeling regulations and meet industry standards, which can be both time-consuming and costly. The process for obtaining necessary product approvals can also extend product launch timelines, affecting market entry and competitive positioning. Moreover, intense competition in the market leads to price wars and promotional strategies that can erode profit margins. Companies must balance competitive pricing with the need to cover higher production and raw material costs. Additionally, sustainability remains a pressing issue; producers must balance the need for sustainable sourcing and production practices against the imperative to maintain profitability, all while addressing consumer skepticism about the environmental impact of certain production methods. Communicating the nutritional benefits and fortifying plant-based milks to match the nutritional profile of dairy milk also remains a critical task, requiring ongoing consumer education and engagement.
Market Segmentation Analysis:
By Product Type:
The Plant-Based Milk Market is extensively segmented by product types, with soy milk, almond milk, and oat milk leading as the most popular choices among consumers due to their nutritional profiles and widespread availability. Emerging varieties such as coconut, cashew, and rice milk are gaining traction due to unique flavor profiles and dietary benefits, catering to niche consumer preferences. Moreover, innovative products like hemp seed, peanut, and pea milk are emerging in response to consumer demands for diverse nutritional content and hypoallergenic properties. Specialty milks, including hazelnut, macadamia, and other types like spelt and banana milk, are carving out their own spaces in the market by offering distinctive tastes and health benefits. This wide array of options reflects the market's response to increasing consumer demand for variety and personalization in dietary choices.
By Forms:
In terms of form, the Plant-Based Milk Market is primarily divided into liquid and powder segments. The liquid form dominates the market, appreciated for its convenience and similarity to traditional dairy milk, making it a straightforward substitute in both cooking and direct consumption. On the other hand, the powdered form is valued for its longer shelf life and space-efficient packaging, which appeals particularly to consumers with limited storage space or those who prioritize convenience and sustainability. Powdered plant-based milk is also gaining popularity in the commercial sector, especially in the bakery and confectionery industries, due to its ease of use and storage efficiency, positioning it as a versatile ingredient in a variety of culinary applications.
Segments:
Based on Product Type:
- Soy Milk
- Almond Milk
- Coconut Milk
- Cashew Milk
- Hemp Seed Milk
- Rice Milk
- Oat Milk
- Peanut Milk
- Pea Milk
- Hazelnut Milk
- Macadamia Milk
- Other Product Types (Spelt Milk, Banana)
Based on Forms:
- Liquid
- Powder
Based on Categories:
- Organic
- Conventional
Based on Flavors:
- Original/Unflavored
- Flavored
- Chocolate
- Vanilla
- Strawberry
- Coconut
- Mocha
- Berry
- Hazelnut
- Other Flavors
Based on End Uses:
- Infant Formula
- Dairy Products (Milk, Cheese, Yogurt, Butter, Spreads, Ice Cream, Frozen Dessert)
- Bakery and Confectionary
- Milk and Milk-Based Beverages
- Retail Sales
Based on Sales Channels:
- Direct Sales
- Indirect Sales
- Modern Trade
- Convenience Store
- Departmental Store
- Traditional Store
- Specialty Store
- Online Retailers
- Other Sales Channels
Based on the Geography:
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis
North America
North America leads the market with a substantial 40% share, primarily due to its early adoption of plant-based diets and strong presence of innovative food companies. The United States dominates this segment, benefiting from a well-established retail network and a growing consumer base seeking dairy alternatives. The region's market is characterized by a diverse range of plant-based milk options, including almond, soy, oat, and newer varieties like pea and cashew milk. Canada follows suit, with increasing demand driven by health-conscious millennials and a growing vegan population. The North American market also benefits from continuous product innovations, including fortified plant-based milks and flavored varieties, catering to evolving consumer tastes and nutritional needs.
Europe
Europe holds the second-largest market share at 35%, with countries like Germany, the United Kingdom, and Sweden at the forefront of adoption. The European market is driven by strong environmental awareness, animal welfare concerns, and a growing lactose-intolerant population. For instance, sales of plant-based milk and derivatives in Europe were valued at almost 3.9 billion U.S. dollars in 2020, and this figure is expected to reach 6.8 billion U.S. dollars by 2026. The region has seen a significant shift towards oat milk, particularly in Nordic countries, due to its lower environmental impact compared to other plant-based alternatives.
Key Player Analysis
- Freedom Foods Group Ltd
- Earth’s Own Food Company Inc.
- Hain Celestial Group, Inc.
- Goya Foods
- Groupe Danone
- Blue Diamond Growers, Inc.
- Liwayway Holdings Company Limited
- Elden Foods Inc.
- Oatly Inc.
- Kaslink Foods Oy Ltd
- Plenish
- Alpina Foods
- Living Harvest Foods Inc.
- Döhler GmbH
- Nestlé
- Mc Cormick & Co.
- Natura Foods
Competitive Analysis
In the competitive landscape of the Plant-Based Milk Market, leading players such as Oatly Inc., Blue Diamond Growers, and Groupe Danone are actively expanding their market share through innovation and strategic global expansions. Oatly Inc. distinguishes itself with a strong focus on sustainability and a diverse product range that resonates with environmentally conscious consumers. Blue Diamond Growers leverages its expertise in almond-based products to cater to a broad demographic looking for nut-based dairy alternatives, emphasizing quality and nutritional benefits. Groupe Danone, with its extensive portfolio that includes several plant-based brands, capitalizes on its global presence and robust distribution networks to meet consumer demands across various regions. These companies are continuously enhancing their product offerings and engaging in partnerships and acquisitions to broaden their consumer base and strengthen market presence amidst growing competition.
Recent Developments
- In January 2023, Oatly Inc. collaborated with Reitan, the operator of approximately 90 7-Eleven and 300 Pressbyrån convenience stores across Sweden. This strategic expansion facilitated Oatly’s growth and broadened its customer base significantly.
- In July 2022, French food giant Danone launched its first plant-based dairy and baby formula products. This introduction was in response to increasing parental demand for vegetarian and flexitarian dietary options for toddlers, aligning with evolving consumer preferences towards plant-based nutrition.
- In February 2024, Nestlé confirmed the withdrawal of its yellow pea-based milk alternative, Wunda, from the market. The Swiss multinational company informed the Dutch publication Food+Agri that Wunda is no longer available in the Netherlands and has also been removed from international distribution channels.
- In March 2022, Plenish, one of the fastest-growing plant-based drinks brands in the UK, launched a comprehensive brand refresh alongside new premium packaging for its range of plant-based milk, juices, and shots.
Market Concentration & Characteristics
The Plant-Based Milk Market exhibits a moderate to high level of market concentration, with a few major players like Oatly Inc., Blue Diamond Growers, and Groupe Danone dominating the industry. These leading companies command significant market shares due to their established brand reputations, extensive distribution networks, and wide-ranging product portfolios. The market is characterized by intense competition among these key players, who are continually innovating and expanding their product lines to include a variety of flavors and formulations that cater to an expanding consumer base with diverse dietary needs and preferences. Additionally, the market is seeing an influx of smaller, niche players who are introducing unique and specialized products, such as milk from peas and macadamias, further enriching the market dynamics and offering consumers more choices. This blend of large and small companies contributes to the vibrant and competitive nature of the market, driving continuous innovation and improvement across the industry.
Report Coverage
The research report offers an in-depth analysis based on Product Type, Forms, Categories, Flavors, End Uses, Sales Channels and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Plant-based milk consumption is expected to continue its growth trajectory, driven by increasing health awareness and dietary shifts.
- Technological advancements in production processes will enhance the quality and variety of plant-based milk offerings.
- Expansion into emerging markets will accelerate, particularly in Asia and Africa, as consumer awareness and income levels rise.
- Nutritional fortification will become more prevalent, addressing consumer demand for healthier alternatives to dairy milk.
- Sustainability initiatives will intensify, focusing on reducing carbon footprints and improving packaging solutions.
- New product development will cater to niche preferences with unique flavors and plant sources.
- Regulatory frameworks will evolve, potentially simplifying product approvals and labeling requirements.
- Market competition will increase as new entrants join and existing players expand their product lines.
- Consumer education efforts will ramp up, aiming to highlight the benefits and versatility of plant-based milks.
- Strategic partnerships and acquisitions will become key strategies for companies looking to quickly expand their market reach and capabilities.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Health and Wellness Trends
Growing consumer awareness of health, wellness, and dietary restrictions such as lactose intolerance is driving demand for plant-based milk alternatives, which are perceived as healthier and often fortified with essential nutrients.
Rise of Veganism and Flexitarian Diets
The increasing adoption of vegan, vegetarian, and flexitarian diets is fueling demand for plant-based milk as consumers seek to reduce or eliminate animal products for health, ethical, and lifestyle reasons.
Environmental and Ethical Considerations
Plant-based milks have a lower environmental footprint compared to dairy, appealing to eco-conscious consumers who are motivated by sustainability and animal welfare concerns.
Product Innovation and Diversification
Continuous innovation in flavors, fortification, and new plant sources (such as oat, pea, and cashew) is expanding the consumer base by catering to diverse tastes and nutritional needs.
Improved Accessibility and Retail Expansion
Wider availability of plant-based milks in supermarkets, specialty stores, and online platforms is making these products more accessible, supporting market growth across both developed and emerging regions.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Plant-Based Milk Market?
What factors are driving the growth of the Plant-Based Milk Market?
What are the key segments within the Plant-Based Milk Market?
Who are the major players in the Plant-Based Milk Market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Form
- 1.2.1 Liquid
- 1.2.2 Powder
- 1.3 By Flavor
- 1.3.1 Original/Unflavored
- 1.3.2 Chocolate
- 1.3.3 Vanilla
- 1.3.4 Strawberry
- 1.3.5 Other Flavors
- 1.4 By Product Type
- 1.4.1 Soy Milk
- 1.4.2 Almond Milk
- 1.4.3 Oat Milk
- 1.4.4 Coconut Milk
- 1.4.5 Rice Milk
- 1.4.6 Cashew Milk
- 1.5 By Sales Channel
- 1.5.1 Modern Trade
- 1.5.2 Convenience Store
- 1.5.3 Specialty Store
- 1.5.4 Online Retailers
- 1.5.5 Other Sales Channels
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 20,095 million → 2032: USD 34,128,846.99 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Plant-Based Milk Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Plant-Based Milk Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Plant-Based Milk Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Plant-Based Milk Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Plant-Based Milk Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Plant-Based Milk Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Plant-Based Milk Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Plant-Based Milk Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 20,095 million → 2032: USD 34,128,846.99 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Plant-Based Milk Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Form - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Liquid
- 12.3.7.2 Powder
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Flavor - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Original/Unflavored
- 12.4.7.2 Chocolate
- 12.4.7.3 Vanilla
- 12.4.7.4 Strawberry
- 12.4.7.5 Other Flavors
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Product Type - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Soy Milk
- 12.5.7.2 Almond Milk
- 12.5.7.3 Oat Milk
- 12.5.7.4 Coconut Milk
- 12.5.7.5 Rice Milk
- 12.5.7.6 Cashew Milk
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 By Sales Channel - Market Size and Forecast, 2024-2032
- 12.6.1 Segment Definition and Scope
- 12.6.2 Historical Market Size
- 12.6.3 Revenue Forecast, 2024-2032
- 12.6.4 Volume Forecast, 2024-2032
- 12.6.5 Base-Year Market Share, 2024
- 12.6.6 Segment CAGR and Growth Drivers
- 12.6.7 Subsegment Market Size and Forecast
- 12.6.7.1 Modern Trade
- 12.6.7.2 Convenience Store
- 12.6.7.3 Specialty Store
- 12.6.7.4 Online Retailers
- 12.6.7.5 Other Sales Channels
- 12.6.8 Subsegment Pricing and Adoption Trends
- 12.6.9 Leading Suppliers and Competition
- 12.6.10 Regional Demand and Opportunities
- 12.7 Segment Growth Comparison
- 12.8 Segment Attractiveness and Priority Matrix
Chapter 13 Global Plant-Based Milk Geographic Market Outlook, 2024-2032
- 13.1 Regional Market Size and Share, 2024
- 13.2 Regional Market Forecast, 2024-2032
- 13.3 Regional Pricing, Production and Demand Differences
- 13.4 North America
- 13.4.1 United States
- 13.4.2 Canada
- 13.4.3 Mexico
- 13.5 Europe
- 13.5.1 Germany
- 13.5.2 France
- 13.5.3 Italy
- 13.5.4 United Kingdom
- 13.5.5 Spain
- 13.5.6 Poland
- 13.5.7 Russia
- 13.5.8 Netherlands
- 13.5.9 Belgium
- 13.5.10 Sweden
- 13.5.11 Denmark
- 13.5.12 Norway
- 13.5.13 Rest of Europe
- 13.6 Asia Pacific
- 13.6.1 China
- 13.6.2 India
- 13.6.3 Japan
- 13.6.4 South Korea
- 13.6.5 Thailand
- 13.6.6 Indonesia
- 13.6.7 Vietnam
- 13.6.8 Malaysia
- 13.6.9 Australia
- 13.6.10 Rest of Asia Pacific
- 13.7 Latin America
- 13.7.1 Brazil
- 13.7.2 Argentina
- 13.7.3 Colombia
- 13.7.4 Chile
- 13.7.5 Rest of Latin America
- 13.8 Middle East
- 13.8.1 Saudi Arabia
- 13.8.2 United Arab Emirates
- 13.8.3 Turkey
- 13.8.4 Israel
- 13.8.5 Iran
- 13.8.6 Rest of the Middle East
- 13.9 Africa
- 13.9.1 South Africa
- 13.9.2 Egypt
- 13.9.3 Nigeria
- 13.9.4 Morocco
- 13.9.5 Rest of Africa
- 13.10 Regional Investment, Policy and Supply Chain Differences
- 13.11 Regional Competitive Landscape
- 13.12 Geographic Growth Hotspots
Chapter 14 Global Plant-Based Milk Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2024-2032
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 Global Plant-Based Milk Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2024
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2024-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Oatly Inc.
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 Blue Diamond Growers
- 17.4 Groupe Danone
- 17.5 Nestlé
- 17.6 Plenish
- 17.7 Freedom Foods Group Ltd
- 17.8 Earth’s Own Food Company Inc.
- 17.9 Hain Celestial Group, Inc.
- 17.10 Goya Foods
- 17.11 Alpina Foods
- 17.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

