
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
| Plant-Based Protein Beverages Market Size 2024 | USD 1080.3 million |
| Plant-Based Protein Beverages Market, CAGR | 10.1% |
| Plant-Based Protein Beverages Market Size 2032 | USD 2332.61 million |
Market Overview:
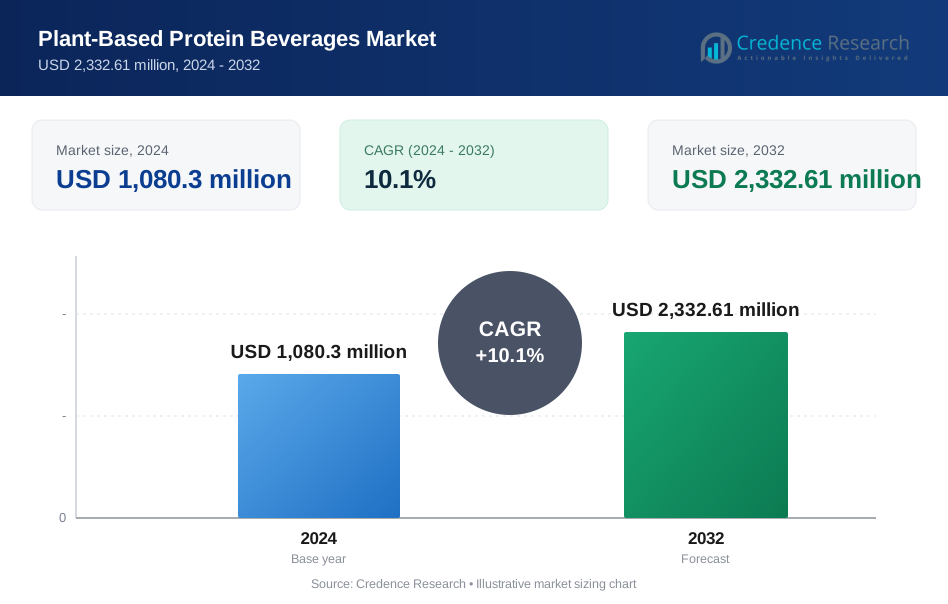
The Plant-Based Protein Beverages Market is projected to grow from USD 1080.3 million in 2024 to an estimated USD 2332.61 million by 2032, with a compound annual growth rate (CAGR) of 10.1% from 2024 to 2032.
Several factors are fueling the expansion of the plant-based protein beverages market. Firstly, rising health-consciousness among consumers, along with the increasing popularity of plant-based diets, has led to a surge in demand for protein-enriched beverages that cater to specific dietary needs, such as vegan, gluten-free, and lactose-free options. Additionally, the growing concerns over animal-based protein consumption, coupled with an increasing number of people adopting plant-based or flexitarian lifestyles, are contributing to market growth. Moreover, product innovations, such as the development of protein beverages with enhanced flavors and functional benefits, further drive consumer interest.
Regionally, North America holds a dominant position in the plant-based protein beverages market, accounting for a substantial share due to the region’s high adoption rate of plant-based diets, along with strong demand for fitness-related products. Europe follows closely, with a growing trend toward veganism and an increasing focus on health and wellness. The Asia Pacific market is also experiencing rapid growth, driven by changing consumer preferences, the rising popularity of plant-based diets in countries such as India and China, and the availability of diverse plant-based protein sources. Latin America and the Middle East & Africa are expected to witness moderate growth during the forecast period.
Market Drivers:
Increasing Health Consciousness:
One of the primary drivers of the plant-based protein beverages market is the growing consumer awareness regarding health and wellness. As more people become conscious of the adverse effects of animal-based products on health, such as cholesterol and saturated fats, there is a shift towards plant-based alternatives. Plant-based protein beverages offer a healthier, lower-fat, and more nutritious option, making them increasingly popular among fitness enthusiasts, athletes, and health-conscious individuals. For instance, a survey conducted by Mintel in 2020 found that 63% of U.S. adults agreed that plant-based proteins are healthier than animal-based proteins.
Rising Popularity of Plant-Based Diets:
The growing adoption of plant-based diets, driven by concerns over sustainability, ethical considerations, and animal welfare, is significantly contributing to market growth. Consumers are increasingly seeking plant-based proteins sourced from peas, rice, hemp, and soy, as they offer comparable benefits to animal proteins without the environmental impact. For example, Beyond Meat, known for its pea protein-based products, has seen a significant rise in consumer demand. This shift toward plant-based lifestyles is expanding the demand for protein beverages made with natural, plant-based ingredients.
Functional and Nutritional Benefits:
Plant-based protein beverages are being favored for their functional and nutritional benefits. They are often enriched with essential vitamins, minerals, and antioxidants that contribute to overall health. This includes aiding in muscle recovery, promoting weight loss, improving digestion, and boosting immunity. For instance, Vega offers a range of plant-based protein shakes that are fortified with vitamins and minerals to support overall health. The demand for such beverages has surged as consumers look for convenient ways to meet their nutritional needs while maintaining a balanced diet.
Product Innovation and Variety:
The innovation and diversification of plant-based protein beverages are key factors driving market growth. Manufacturers are continuously developing new flavors, ingredients, and formulations to cater to a wide range of consumer preferences. For instance, in 2021, Califia Farms introduced a new line of protein oat milk beverages fortified with superfoods like maca and adaptogens like ashwagandha. The introduction of beverages fortified with superfoods, adaptogens, and probiotics has further fueled interest in these products. This broadening of product offerings enhances the appeal of plant-based protein beverages, making them a versatile choice for various dietary preferences and health goals.
Market Trends:
Growing Demand for Clean Label Products:
One of the prominent trends in the plant-based protein beverages market is the increasing demand for clean label products. Consumers are becoming more discerning about the ingredients in their food and beverages, preferring those with transparent, simple, and recognizable ingredients. This trend has prompted manufacturers to create plant-based protein drinks with minimal processing, fewer additives, and no artificial preservatives or sweeteners. For instance, Califia Farms offers a line of almond milk protein beverages that are non-GMO, carrageenan-free, and made with simple ingredients. Clean label offerings are perceived as healthier and more natural, appealing to health-conscious consumers.
Expansion of Plant-Based Flavors:
As the plant-based protein beverages market matures, manufacturers are diversifying their flavor offerings to cater to a wider range of tastes. Traditionally, plant-based proteins were associated with earthy, sometimes unpleasant flavors. However, ongoing innovation in product formulations has led to the development of more palatable, exciting flavor options, such as vanilla, chocolate, berry, and even exotic fruit combinations. For example, Ripple Foods introduced a line of plant-based protein shakes in flavors like vanilla, chocolate, and coffee. This flavor expansion is helping to attract a broader consumer base, including those who may not have initially considered plant-based protein beverages.
Focus on Functional Ingredients:
Another significant trend in the market is the incorporation of functional ingredients into plant-based protein beverages. Consumers are seeking beverages that not only provide protein but also offer additional health benefits. These functional ingredients may include probiotics, adaptogens, antioxidants, and vitamins that support immunity, digestion, and overall wellness. For instance, Garden of Life offers plant-based protein powders that include probiotics and enzymes to aid digestion. This trend reflects the growing preference for nutritionally enhanced beverages that go beyond basic hydration or protein content to provide a more comprehensive health benefit.
Rise of Sustainable Packaging:
Sustainability continues to be a major concern for modern consumers, and this has extended to the packaging of plant-based protein beverages. Eco-conscious consumers are increasingly opting for products that come in recyclable, biodegradable, or sustainably sourced packaging. Manufacturers are responding by investing in environmentally friendly packaging solutions to reduce their carbon footprint and appeal to the growing demographic of environmentally aware buyers. For example, Oatly uses sustainable packaging made from renewable materials for its oat milk products. This trend is expected to continue as consumers place more value on sustainability in their purchasing decisions.
Market Challenges Analysis:
Taste and Texture Challenges:
One of the key challenges faced by the plant-based protein beverages market is the ongoing difficulty in achieving an appealing taste and texture. Plant-based proteins, such as pea, hemp, and rice protein, can sometimes have an earthy or gritty flavor and texture that may not be as palatable to all consumers. Despite advancements in formulation and flavor enhancement, many plant-based proteins beverages still struggle to meet the taste expectations of a broader market. Manufacturers must continuously innovate to overcome these sensory challenges, making plant-based options more attractive to consumers accustomed to traditional dairy-based protein drinks.
High Production Costs:
The production costs associated with plant-based protein beverages are often higher compared to those of traditional dairy-based products. Sourcing high-quality plant proteins, such as pea, soy, or rice, can be expensive, especially in regions where these ingredients are not locally available. Furthermore, the manufacturing process for plant-based protein beverages often requires specialized equipment and more complex formulations, which can increase operational expenses. These elevated costs may be passed on to consumers, potentially limiting price-sensitive consumers’ access to plant-based options.
Limited Consumer Awareness:
Despite the growing popularity of plant-based diets, a significant challenge remains in educating consumers about the benefits and nutritional value of plant-based protein beverages. Many consumers are still unfamiliar with the range of plant-based proteins available or may perceive them as inferior to animal-based proteins in terms of nutritional content. Increased efforts in marketing and consumer education are necessary to bridge this knowledge gap and help consumers make informed decisions about incorporating plant-based protein beverages into their diets.
Regulatory and Labeling Concerns:
Another challenge for the plant-based protein beverages market is the evolving regulatory landscape surrounding plant-based products. Labeling requirements can vary across different regions, making it difficult for manufacturers to ensure compliance with varying regulations. Additionally, some regions have stringent guidelines regarding claims such as "protein-rich" or "vegan," which can limit marketing strategies. Navigating these regulatory complexities is an ongoing challenge for producers aiming to expand their market presence.
Market Segmentation Analysis:
By Product
The plant-based protein beverages market is segmented into various product types, including ready-to-drink (RTD) beverages, powder-based protein drinks, and concentrate-based beverages. RTD beverages dominate the market due to their convenience, allowing consumers to enjoy a protein-packed drink without the need for preparation. Powder-based protein drinks are also popular, especially among fitness enthusiasts and athletes, who prefer to customize their protein intake. Concentrate-based beverages are gaining traction as a more affordable and flexible option.
By Source
Plant-based protein beverages are derived from a variety of plant sources, including soy, pea, rice, hemp, and almond. Among these, pea protein holds a significant share due to its high protein content and digestibility. Soy protein is also widely used, particularly for its complete amino acid profile. Rice, hemp, and almond protein are gaining popularity due to their allergen-free nature and nutritional benefits.
By Distribution Channel
The distribution channels for plant-based protein beverages include supermarkets and hypermarkets, online retail, convenience stores, and health & specialty stores. Supermarkets and hypermarkets are the primary retail channels, offering a wide range of plant-based beverages. The online retail segment is growing rapidly, driven by the increasing popularity of e-commerce and the ability to reach a broader consumer base. Health & specialty stores remain key players for niche products targeting health-conscious consumers.
By Category
The plant-based protein beverages market is categorized into conventional and organic segments. Organic plant-based protein beverages are witnessing increased demand due to consumer preferences for clean-label products and natural ingredients. The conventional category remains dominant due to its affordability and widespread availability.
Segmentations:
By Product
- Ready-to-Drink (RTD) Beverages
- Powder-Based Protein Drinks
- Concentrate-Based Beverages
By Source
- Soy Protein
- Pea Protein
- Rice Protein
- Hemp Protein
- Almond Protein
By Distribution Channel
- Supermarkets and Hypermarkets
- Online Retail
- Convenience Stores
- Health & Specialty Stores
By Category
- Conventional
- Organic
By Region
- North America
- U.S.
- Canada
- Mexico
- Europe
- UK
- France
- Germany
- Italy
- Spain
- Russia
- Belgium
- Netherlands
- Austria
- Sweden
- Poland
- Denmark
- Switzerland
- Rest of Europe
- Asia Pacific
- China
- Japan
- South Korea
- India
- Australia
- Thailand
- Indonesia
- Vietnam
- Malaysia
- Philippines
- Taiwan
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Peru
- Chile
- Colombia
- Rest of Latin America
- Middle East
- UAE
- KSA
- Israel
- Turkey
- Iran
- Rest of Middle East
- Africa
- Egypt
- Nigeria
- Algeria
- Morocco
- Rest of Africa
Regional Analysis:
North America holds the largest market share in the plant-based protein beverages market, accounting for approximately 35%. This region has seen a significant increase in demand for plant-based products, driven by rising health consciousness, environmental concerns, and the adoption of vegan and vegetarian lifestyles. The United States is a key market within North America, with a large population of health-focused consumers and a well-established retail infrastructure supporting the distribution of plant-based beverages. The demand for plant-based protein drinks is particularly high among fitness enthusiasts, athletes, and those following plant-based diets. The growing popularity of these beverages is supported by the availability of a variety of options from both established brands and startups, further solidifying North America's dominance in the market.
Europe follows closely behind, with a market share of approximately 30%. The European market is characterized by a strong preference for plant-based diets, supported by increasing awareness of the health and environmental benefits of plant-based proteins. Countries like the United Kingdom, Germany, and France are at the forefront of this shift, with a high rate of veganism and a growing interest in sustainable food choices. The demand for plant-based protein beverages is driven not only by health-conscious consumers but also by the ethical concerns surrounding animal welfare. Retail chains across Europe are expanding their plant-based offerings, contributing to the region's strong market position. The shift towards clean-label and organic products further supports the growth of plant-based protein beverages in the region.
Asia Pacific is experiencing rapid growth, with a market share of approximately 20%. The rise of plant-based protein beverages in this region is fueled by changing dietary patterns, particularly in countries like China, India, and Japan. As urbanization increases and disposable incomes rise, consumers are becoming more aware of the benefits of plant-based diets, especially in the context of health and wellness. Additionally, the availability of local plant protein sources such as soy, rice, and peas is contributing to the region’s market expansion. The plant-based protein beverage sector in Asia Pacific is also benefitting from the increasing popularity of fitness and wellness trends, further driving demand for protein-enriched drinks.
Latin America holds a market share of approximately 10%, with countries like Brazil witnessing a rise in the adoption of plant-based diets. Although the market is still developing, the demand for plant-based protein beverages is gaining momentum as consumers become more aware of the health benefits and environmental impact of plant-based products. The region’s growing middle class and increasing interest in sustainability are key factors driving this trend.
Middle East & Africa represents a smaller segment, with a market share of about 5%. However, there is a gradual shift towards plant-based options as consumers in urban areas, particularly in the Gulf countries, seek healthier and more sustainable alternatives. Awareness of plant-based diets is increasing, particularly among the younger population, although market penetration remains lower compared to other regions. The growth potential in this region lies in the increasing availability of plant-based protein beverages and rising consumer interest in wellness.
Key Player Analysis:
- Nestlé
- PepsiCo
- Danone
- Unilever
- Orgain
- Ripple Foods
- Oatly
- Blue Diamond Growers
- Hain Celestial Group
- SunOpta
- Vega
Competitive Analysis:
The plant-based protein beverages market is highly competitive, with several key players dominating the landscape. Major companies such as Nestlé, PepsiCo, Danone, and Unilever have established a strong presence by leveraging their extensive distribution networks, brand recognition, and innovative product offerings. These industry giants are focusing on expanding their product portfolios to include a variety of plant-based protein beverages, often incorporating diverse plant sources like pea, soy, and rice to cater to different consumer preferences. Smaller, specialized brands such as Orgain, Ripple Foods, and Oatly have also made significant inroads by offering premium, clean-label, and organic plant-based protein beverages. These companies differentiate themselves through product innovation, emphasizing natural ingredients and sustainability. For example, Orgain has gained popularity for its organic protein shakes, while Ripple Foods has focused on pea protein-based beverages. Additionally, strategic partnerships, acquisitions, and advancements in R&D are key tactics for companies looking to capture market share.
Recent Developments:
- In Nov 2024, Nestlé introduced Orgain Better Whey, their first precision fermentation dairy protein powder that is animal-free and lactose-free.
- In Early 2024, PepsiCo expanded distribution of Muscle Milk Plant Protein Shakes to additional national retailers.
- In June 2024, Danone focus on protein-enriched dairy products and plant-based alternatives, noting that 25% of global consumers are now flexitarians.
- In November 2024, Unilever announced plans to sell The Vegetarian Butcher brand as part of portfolio restructuring.
Market Concentration & Characteristics:
The plant-based protein beverages market is moderately concentrated, with a mix of established multinational corporations and specialized smaller companies. Major players such as Nestlé, PepsiCo, and Danone dominate the market through their extensive distribution channels, strong brand recognition, and diverse product portfolios. These companies are increasingly investing in plant-based innovations to capture the growing demand for health-focused, sustainable alternatives. However, the market also features a significant presence of niche players like Orgain, Ripple Foods, and Oatly, which differentiate themselves through premium, organic, and clean-label offerings. This creates a dynamic competitive environment where both large companies and specialized brands are vying for market share. The market characteristics include a strong emphasis on product diversification, particularly in flavor and nutritional benefits, as well as a focus on sustainability in sourcing and packaging. Overall, innovation and consumer demand for healthier, plant-based beverages are driving market characteristics and competition.
Report Coverage:
The research report offers an in-depth analysis based on Product, Source, Distribution Channel and Category. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- Increasing consumer preference for plant-based diets will continue to drive the growth of plant-based protein beverages.
- There will be a rise in demand for clean-label products, with consumers prioritizing natural, minimally processed ingredients.
- The introduction of new, innovative flavors and formulations will enhance the appeal of plant-based protein beverages to a broader consumer base.
- Growing awareness of the environmental impact of animal-based proteins will further accelerate the shift toward plant-based alternatives.
- The expansion of online retail channels will make plant-based protein beverages more accessible to consumers worldwide.
- Technological advancements in protein extraction and formulation will improve taste, texture, and nutritional profiles, making plant-based beverages more appealing.
- Increasing consumer interest in functional beverages, with added benefits such as probiotics, vitamins, and antioxidants, will create opportunities for growth.
- The popularity of fitness and wellness trends will continue to drive demand for protein-enriched beverages, especially among athletes and health-conscious individuals.
- Rising disposable incomes, particularly in emerging markets, will contribute to the growing adoption of plant-based protein beverages in regions like Asia Pacific and Latin America.
- Sustainability concerns, including eco-friendly packaging, will play an increasingly important role in shaping product offerings and consumer choices.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Plant-Based Protein Beverages Market?
What factors are driving the growth of the Plant-Based Protein Beverages Market?
What are some challenges faced by the Plant-Based Protein Beverages Market?
Who are the major players in the Plant-Based Protein Beverages Market?
Which segment is leading the market share?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue) (Volume Where Applicable)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Plant-Based Protein Beverages Scope – Segments & Subsegments Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 Industry Classification & Applicable Codes
- 1.5 Currency, Measurement Units & Valuation Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Plant-Based Protein Beverages Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 1,080.3 million → 2032: USD 2,332.61 million)
- 2.1.2 Volume & Revenue – Global Totals (Volume Where Applicable)
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Plant-Based Protein Beverages Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024 (Volume Where Applicable)
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Plant-Based Protein Beverages Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Plant-Based Protein Beverages Market Position in the Broader Industry Value Chain
- 3.1.2 Demand Structure & Purchasing Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Plant-Based Protein Beverages Market Drivers
- 3.3 Plant-Based Protein Beverages Market Restraints & Challenges
- 3.4 Plant-Based Protein Beverages Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Plant-Based Protein Beverages Value Chain Analysis
- 3.6.1 Upstream – Key Inputs, Resources & Suppliers
- 3.6.1.1 Key Input/Resource 1
- 3.6.1.2 Key Input/Resource 2
- 3.6.1.3 Key Input/Resource 3
- 3.6.2 Midstream – Core Operations & Value Creation
- 3.6.2.1 Operating Model & Process Overview
- 3.6.2.2 Key Operating Locations & Capabilities by Company
- 3.6.3 Downstream – Market Channels & End Users
- 3.6.3.1 Direct Sales & Customer Engagement Channels
- 3.6.3.2 Indirect Sales, Intermediaries & Partner Channels
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Key Inputs, Resources & Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Plant-Based Protein Beverages Supply Chain Analysis
- 3.8.1 Critical Input & Resource Availability Risk Assessment
- 3.8.2 Supplier & Operational Concentration Risk (Geographic Exposure)
- 3.8.3 Supply & Service Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Plant-Based Protein Beverages category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Plant-Based Protein Beverages Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Market Size × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute Revenue Growth Through 2032
- 4.3 Incremental Demand Opportunity
- 4.3.1 By Region – Incremental Demand Through 2032
- 4.3.2 Segment – Incremental Demand
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Priority Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Priority market opportunity scorecards reflect the geographic scope and strategic relevance of the study. Listed markets are indicative and may be adapted to the industry.
Chapter 5. Plant-Based Protein Beverages Cross-Border Trade & Market Access Analysis
- 5.1 International Trade & Cross-Border Activity Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024) (Volume Where Applicable)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024) (Volume Where Applicable)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Category 1 (Applicable Classification Code)
- 5.2.2 Category 2 (Applicable Classification Code)
- 5.2.3 Category 3 (Applicable Classification Code)
- 5.2.4 Category 4 (Applicable Classification Code)
- 5.2.5 Category 5 (Applicable Classification Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Category 1 (Applicable Classification Code)
- 5.3.2 Category 2 (Applicable Classification Code)
- 5.3.3 Category 3 (Applicable Classification Code)
- 5.3.4 Category 4 (Applicable Classification Code)
- 5.3.5 Category 5 (Applicable Classification Code)
- 5.4 Cross-Border Pricing & Transaction Benchmarks
- 5.4.1 Export Pricing – Segment & Country
- 5.4.2 Import Pricing – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Cross-Border Trade & Delivery Routes
- 5.5.1 Cross-Border Trade/Delivery Route 1
- 5.5.2 Cross-Border Trade/Delivery Route 2
- 5.5.3 Cross-Border Trade/Delivery Route 3
- 5.5.4 Cross-Border Trade/Delivery Route 4
- 5.5.5 Cross-Border Trade/Delivery Route 5
- 5.6 Trade Policy & Market Access Impact Assessment
- 5.6.1 Tariff & Non-Tariff Barriers
- 5.6.2 Regional Trade & Economic Integration Frameworks
- 5.6.3 Bilateral & Multilateral Trade Agreements
- 5.6.4 Cross-Border Operating, Licensing & Localization Requirements
Note: This chapter applies where cross-border trade or delivery is relevant to Plant-Based Protein Beverages. Goods, services, and digital offerings are assessed using applicable classifications and transaction measures. Import-export volumes, trade balances, and route analyses are included only where meaningful to the market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Plant-Based Protein Beverages Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Leading, Mid-Sized & Emerging Player Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Plant-Based Protein Beverages Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company (Volume Where Applicable)
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 Company Market Share by Key Segment
- 6.2.6 Company Market Share by Customer Group
- 6.3 Operating Scale, Capacity & Infrastructure Analysis
- 6.3.1 Global Operating Scale & Supply Capacity
- 6.3.2 Resource Utilization & Operating Efficiency
- 6.3.3 Output, Service Delivery & Activity Metrics
- 6.3.4 Operating Footprint & Infrastructure Map
- 6.3.5 Planned Operational & Capacity Expansion
- 6.4 Plant-Based Protein Beverages Competitive Benchmarking Matrix
- 6.4.1 Revenue, Growth, Profitability & Operating Metric Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Plant-Based Protein Beverages (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Products, Services & Solutions in Plant-Based Protein Beverages
- 6.5.3 Operational & Infrastructure Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Plant-Based Protein Beverages Market – By Sales & Delivery Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032) (Volume Where Applicable)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share (Volume Where Applicable)
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region (Volume Where Applicable)
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Sales & Delivery Channel
- 8.2.2 By Competitive Positioning & Price Tier
Chapter 9. North America Plant-Based Protein Beverages Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Plant-Based Protein Beverages Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Plant-Based Protein Beverages Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Plant-Based Protein Beverages Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Plant-Based Protein Beverages Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Plant-Based Protein Beverages Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Plant-Based Protein Beverages Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Supply, Output & Operating Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Demand, Adoption & Usage Assumptions
- Appendix F – Pricing & Revenue Metric Reference Tables
- Appendix G – Company Operations & Infrastructure Database
- Appendix H – Cross-Border Trade & Activity Data Tables (Where Applicable)
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
