
Market Overview
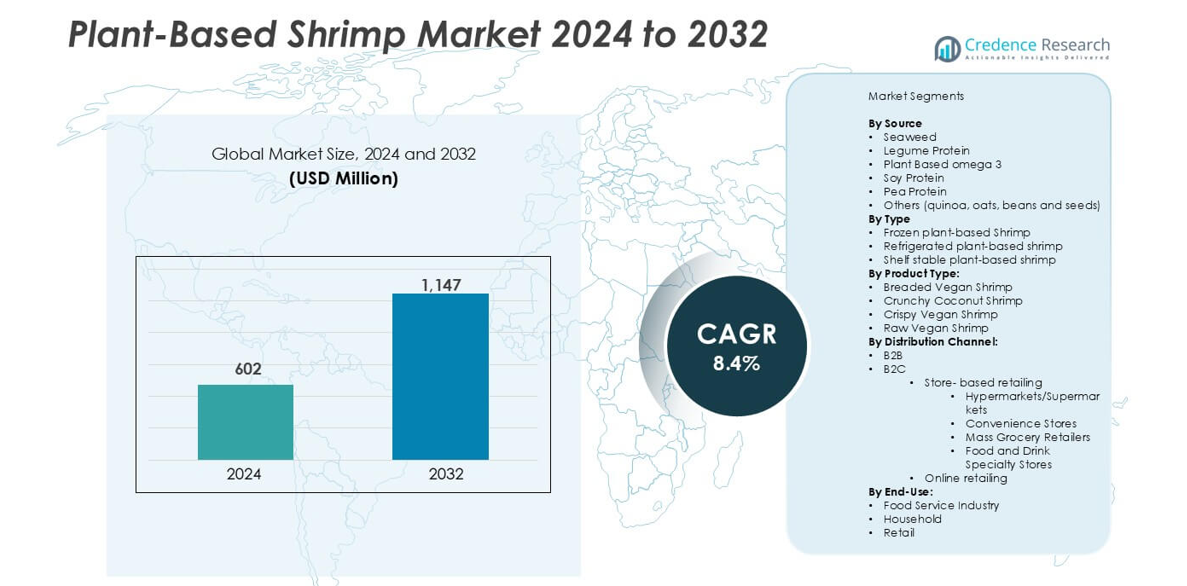
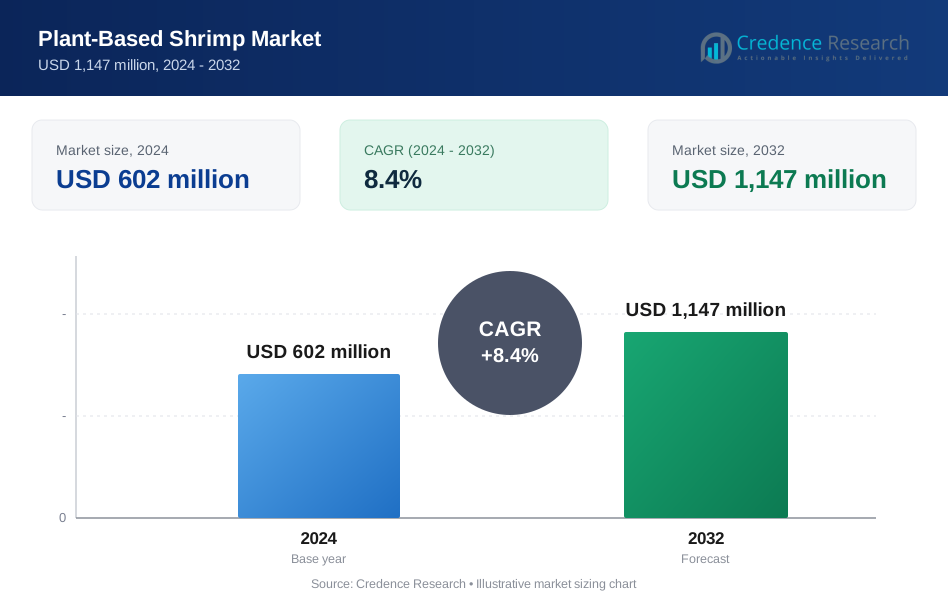
The Plant-Based Shrimp market size was valued at USD 602 million in 2024 and is anticipated to reach USD 1,147 million by 2032, registering a CAGR of 8.4% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Plant-Based Shrimp Market Size 2024 | USD 602 million |
| Plant-Based Shrimp Market, CAGR | 8.4% |
| Plant-Based Shrimp Market Size 2032 | USD 1,147 million |
The plant-based shrimp market is led by companies such as Thai Union, ProExpo, Omarsa, Zhanjiang Guolian, Quoc Viet, Nekkanti Sea Foods, The Liberty Group, Devi Fisheries, Royal Greenland A/S, and Pescanova. These players focus on developing sustainable and high-protein shrimp alternatives using seaweed, soy, and pea protein bases. North America holds the largest regional share of 38%, supported by strong consumer awareness, retail expansion, and advanced R&D capabilities. Europe follows with 30% share, driven by clean-label trends and eco-friendly food regulations, while Asia-Pacific accounts for 24%, benefiting from growing vegan populations and seafood innovation hubs.
Market Insights
- The plant-based shrimp market was valued at USD 602 million in 2024 and is projected to reach USD 1,147 million by 2032, registering a CAGR of 8.4%.
- Rising environmental concerns, overfishing, and demand for sustainable protein sources are driving market growth across foodservice and retail channels.
- Key trends include innovation in seaweed and pea protein formulations, clean-label ingredient development, and expanding vegan seafood portfolios by global brands.
- Major players such as Thai Union, Omarsa, and The Plant-Based Seafood Co. focus on R&D, partnerships, and product differentiation to strengthen market positions.
- North America leads with 38% share, followed by Europe at 30% and Asia-Pacific at 24%; seaweed-based shrimp dominates by source, while frozen plant-based shrimp holds the largest type share globally.
Market Segmentation Analysis:
By Source
Seaweed dominates the plant-based shrimp market with over 34% share in 2024 due to its rich umami flavor and sustainable cultivation. Seaweed-based shrimp analogs replicate authentic taste and texture while offering high nutritional value and low environmental impact. Producers such as New Wave Foods and Sophie's Kitchen utilize seaweed extract and algal proteins to enhance product quality. Rising consumer preference for ocean-friendly and allergen-free seafood alternatives drives the segment growth, supported by innovation in algae-derived proteins and plant-based omega-3 fortification technologies.
- For instance, New Wave Foods developed shrimp alternatives using seaweed extract and mung bean protein in formulations of up to 20 % algae content per batch.
By Type
Frozen plant-based shrimp holds the largest share of about 52% in 2024, owing to its longer shelf life and convenient storage for retail and foodservice channels. Manufacturers focus on improving freezing technology to preserve moisture and texture comparable to real shrimp. Frozen variants are gaining traction across supermarkets and quick-service restaurants due to consistent product quality. Increasing adoption of frozen vegan seafood in global supply chains and e-commerce platforms further supports this segment’s expansion, while refrigerated and shelf-stable types cater to niche urban consumers.
- For instance, several manufacturers maintain internal product temperatures at –18 °C and achieve thaw drip losses under 5 g per 100 g after freezing.
By Product Type
Breaded vegan shrimp leads the product type segment with nearly 45% market share in 2024. Its crunchy coating and ready-to-cook format appeal to flexitarian and fast-food consumers. Companies such as Beleaf and The Plant-Based Seafood Co. invest in advanced breading formulations using pea protein and rice flour to mimic traditional shrimp. The rising demand for quick-preparation plant-based meals and snack-friendly seafood alternatives accelerates this segment’s growth, supported by the launch of innovative coconut- and crispy-style variants targeting global retail and restaurant chains.
Key Growth Drivers
Growing Flexitarian and Vegan Population
The global shift toward plant-forward diets is significantly boosting the demand for vegan seafood alternatives. Flexitarians, who occasionally consume animal products, represent a large share of this growth. They are motivated by health consciousness, animal welfare, and environmental concerns. Plant-based shrimp appeals to this group due to its high protein and low cholesterol content. Major retail chains and quick-service restaurants are expanding vegan menu options to meet this growing consumer base. Marketing campaigns emphasizing “cruelty-free seafood” and “ocean-safe nutrition” are further fueling adoption. This consumer-driven transition is expected to continue strengthening plant-based shrimp sales worldwide.
- For instance, over 40 % of consumers globally identified as flexitarian by 2025, supporting uptake of plant-based shrimp products.
Advancements in Food Technology and Product Innovation
Technological improvements in texture enhancement, extrusion, and flavor replication are transforming the plant-based shrimp market. New formulations use seaweed extracts, pea protein isolates, and fermentation-based oils to deliver the elasticity and mouthfeel of traditional shrimp. Companies like New Wave Foods and OmniFoods are investing heavily in R&D to achieve higher sensory parity and cleaner ingredient lists. These innovations are expanding applications in ready-to-eat, frozen, and restaurant menus. Continuous developments in encapsulated flavor systems and plant-based omega-3 integration further improve product quality. The advancement of scalable production and improved freezing technologies will sustain market competitiveness.
- For instance, New Wave Foods uses seaweed and soy protein in formulations that retain springy texture and protein levels comparable to conventional shrimp.
Rising Demand for Sustainable Seafood Alternatives
The growing awareness of overfishing, ocean pollution, and the carbon footprint of traditional seafood production is driving the adoption of plant-based shrimp. Consumers are increasingly choosing sustainable protein sources that protect marine ecosystems while offering comparable nutrition and flavor. Companies are responding by developing algae- and seaweed-based shrimp that replicate real shrimp texture without environmental harm. Governments and NGOs are also promoting alternative proteins through awareness campaigns and clean-label certifications. As sustainability becomes a key purchase factor, plant-based shrimp manufacturers gain strong traction in retail and foodservice channels, especially across North America and Europe.
Key Trends & Opportunities
Expansion Across Foodservice and Retail Channels
Plant-based shrimp is rapidly expanding into mainstream retail and restaurant networks as global brands partner with alternative seafood producers. Foodservice chains and frozen food brands are adding plant-based shrimp to sushi rolls, tacos, and pasta dishes to attract flexitarian consumers. Retail visibility through supermarkets and online grocery platforms has surged, supported by improved cold chain logistics. Collaborations between manufacturers and food distributors are enhancing availability in North America, Europe, and Asia-Pacific. The ongoing integration of vegan shrimp into diverse cuisines and meal formats presents a major opportunity for sustained market penetration.
- For instance, in March 2021, New Wave Foods announced a partnership with Dot Foods, a major U.S. food redistributor, to distribute its plant-based shrimp. This deal gave New Wave Foods access to thousands of foodservice operations across the country.
Innovation in Ingredient Sourcing and Clean Label Formulations
Manufacturers are shifting toward clean-label, allergen-free, and non-GMO ingredients to meet evolving consumer expectations. Seaweed, mung beans, and chickpeas are emerging as preferred raw materials for their nutritional and sustainability benefits. Companies are also exploring fermentation and enzymatic processing to enhance flavor and texture naturally. The demand for simple ingredient lists and functional nutrients, such as omega-3 fatty acids and fiber, continues to grow. Brands emphasizing transparency and natural sourcing are gaining stronger consumer trust, particularly among health-conscious buyers and premium vegan product lines.
Key Challenges
High Production Costs and Limited Economies of Scale
Despite increasing demand, production costs for plant-based shrimp remain high due to complex formulations and limited manufacturing infrastructure. The use of specialty ingredients such as algal oil and textured proteins raises operational expenses. Scaling production while maintaining quality and sensory appeal poses a challenge for emerging brands. Moreover, limited processing facilities for alternative seafood create supply bottlenecks. Manufacturers must invest in process optimization and ingredient innovation to achieve cost parity with traditional shrimp. Achieving affordability without compromising quality will be crucial for large-scale market penetration.
Consumer Skepticism and Taste Acceptance
Taste and texture remain key barriers to broader adoption of plant-based shrimp. Many consumers still perceive vegan seafood as inferior in flavor or authenticity compared to real shrimp. Overcoming this perception requires continuous R&D to replicate the complex chewiness and oceanic flavor profile of shrimp. Brands are conducting sensory testing and collaborating with chefs to refine formulations. Marketing strategies emphasizing taste parity and environmental benefits are helping shift perceptions, but overcoming ingrained seafood preferences remains a gradual process. Building consumer trust through sampling and education is essential for long-term success.
Regional Analysis
North America
North America dominates the plant-based shrimp market with nearly 38% share in 2024. The region’s strong demand stems from rising vegan seafood adoption and environmental awareness. Consumers are shifting toward sustainable protein options, supported by advanced retail distribution and high purchasing power. Companies like New Wave Foods and The Plant-Based Seafood Co. lead with large-scale retail and foodservice collaborations. Expanding plant-based menus across restaurants and supermarkets in the U.S. and Canada continues to drive steady growth, while ongoing product innovation and marketing around sustainability strengthen market leadership.
Europe
Europe accounts for about 30% of the global market, driven by stringent sustainability regulations and growing flexitarian lifestyles. Consumers in countries such as Germany, the U.K., and the Netherlands increasingly prefer ocean-friendly protein substitutes. The region benefits from advanced R&D and widespread availability of vegan seafood through major retail chains. European manufacturers emphasize non-GMO, allergen-free, and clean-label ingredients. The EU’s focus on reducing seafood imports and supporting alternative proteins further boosts local production. Innovation in flavor development and texture enhancement ensures a strong competitive position for European brands.
Asia-Pacific
Asia-Pacific holds nearly 24% of the market, supported by rapid urbanization, dietary diversification, and seafood dependency. Countries such as China, Japan, and Singapore are witnessing fast adoption of plant-based seafood due to health and sustainability concerns. Local startups and global brands are investing in algae-based shrimp production and distribution partnerships. Government initiatives promoting sustainable aquaculture alternatives further enhance growth prospects. Rising disposable income and growing vegan populations across key economies are fueling demand, especially in frozen and ready-to-eat product segments distributed through online retail and supermarkets.
Latin America
Latin America captures about 5% market share, with Brazil and Mexico leading adoption. The region’s growing awareness of ocean conservation and plant-based diets is driving early market expansion. Local producers are collaborating with global vegan seafood brands to introduce cost-effective shrimp alternatives in supermarkets and restaurants. Increased consumer interest in sustainable food production and plant-based protein innovation is encouraging investment in regional manufacturing. However, limited cold chain infrastructure and price sensitivity currently restrict wider market penetration, though retail presence and foodservice partnerships are steadily increasing.
Middle East & Africa
The Middle East & Africa region holds around 3% of the global share, with gradual growth fueled by rising vegan product availability and international trade partnerships. Countries like the UAE and South Africa are emerging as key markets due to increasing health consciousness and premium food imports. Global players are expanding distribution in the region’s retail and hospitality sectors. The demand for sustainable and halal-certified plant-based seafood options is increasing. Despite infrastructure challenges, expanding awareness campaigns and higher urban consumption levels are creating long-term growth opportunities.
Market Segmentations:
By Source
- Seaweed
- Legume Protein
- Plant Based omega 3
- Soy Protein
- Pea Protein
- Others (quinoa, oats, beans and seeds)
By Type
- Frozen plant-based Shrimp
- Refrigerated plant-based shrimp
- Shelf stable plant-based shrimp
By Product Type:
- Breaded Vegan Shrimp
- Crunchy Coconut Shrimp
- Crispy Vegan Shrimp
- Raw Vegan Shrimp
By Distribution Channel:
- B2B
- B2C
-
- Store- based retailing
- Hypermarkets/Supermarkets
- Convenience Stores
- Mass Grocery Retailers
- Food and Drink Specialty Stores
- Online retailing
- Store- based retailing
By End-Use:
- Food Service Industry
- Household
- Retail
By Geography:
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
The competitive landscape of the plant-based shrimp market is moderately consolidated, with leading players focusing on innovation, sustainability, and global expansion. Companies such as Thai Union, ProExpo, Omarsa, and Zhanjiang Guolian are investing in alternative seafood R&D to reduce reliance on conventional shrimp farming. Emerging plant-based specialists like The Plant-Based Seafood Co. and New Wave Foods are driving product innovation through algae- and pea protein-based formulations that replicate real shrimp texture and flavor. Strategic partnerships with retail and foodservice brands are expanding distribution networks across North America, Europe, and Asia-Pacific. Major seafood producers are diversifying into vegan shrimp to meet growing consumer demand for sustainable and allergen-free options. Continuous advancements in extrusion technology, ingredient sourcing, and clean-label production are intensifying competition, while marketing efforts centered on environmental impact and taste parity further differentiate brands in this evolving global market.
Key Player Analysis
- Thai Union
- ProExpo
- Omarsa
- Zhanjiang Guolian
- Quoc Viet
- Nekkanti Sea Foods
- The Liberty Group
- Devi Fisheries
- Royal Greenland A/S
- Pescanova
Recent Developments
- In July 2024, Big Idea Ventures launched Bayou Best Foods after acquiring intellectual property from New Wave Foods, with plans to bring plant-based shrimp products to market by the end of 2024.
- In January 2024, Steakholder Foods, based in Israel, unveiled the world’s first 3D-printed plant-based shrimp, crafted to closely mimic the texture and appearance of traditional shrimp.
- In July 2023, Thai Union, a Thailand-based food producer, launched plant-based shrimp dumplings and announced plans to expand its branded plant-based offerings across European markets.
- In March 2023, New Wave Foods entered a strategic distribution partnership with Dot Foods to roll out plant-based shrimp made from seaweed and plant proteins across the U.S. foodservice industry.
Report Coverage
The research report offers an in-depth analysis based on Source, Type, Product Type, Distribution Channel, End-Use and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The market will grow steadily as demand for sustainable seafood alternatives increases.
- Advancements in plant protein and algae-based ingredients will enhance product quality.
- Frozen and ready-to-eat formats will gain stronger consumer acceptance worldwide.
- Foodservice chains will expand vegan shrimp offerings on global menus.
- Investment in R&D will improve texture, flavor, and nutritional profiles.
- Clean-label and allergen-free formulations will attract health-conscious consumers.
- Asia-Pacific will emerge as a key production and consumption hub.
- Strategic collaborations between seafood and plant-based companies will accelerate innovation.
- Retail expansion and e-commerce growth will boost product accessibility.
- Regulatory support for sustainable food production will strengthen market adoption
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Growing Flexitarian and Vegan Population
The increasing number of consumers adopting flexitarian and vegan diets is fueling demand for plant-based shrimp, as these groups seek sustainable, high-protein seafood alternatives that align with their health and ethical values.
Advancements in Food Technology and Product Innovation
Improvements in texture, flavor replication, and ingredient sourcing - such as the use of seaweed extracts and pea protein - are making plant-based shrimp more appealing and authentic, driving broader market acceptance and new product launches.
Rising Demand for Sustainable Seafood Alternatives
Concerns over overfishing, ocean pollution, and the environmental impact of traditional shrimp farming are pushing consumers and foodservice providers toward plant-based shrimp, which offers a lower ecological footprint and supports marine conservation.
Expansion Across Foodservice and Retail Channels
Partnerships with major food distributors and increased placement in supermarkets, restaurants, and online platforms are making plant-based shrimp more accessible, accelerating market penetration and consumer trial.
Innovation in Ingredient Sourcing and Clean Label Formulations
The shift toward clean-label, allergen-free, and non-GMO ingredients is attracting health-conscious consumers and those with dietary restrictions, further expanding the market for plant-based shrimp products.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for the Plant-Based Shrimp market, and what is its projected size in 2032?T
At what Compound Annual Growth Rate is the Plant-Based Shrimp market projected to grow between 2025 and 2032?
What factors are driving the growth of the Plant-based shrimp market?
What are some challenges faced by the Plant-based shrimp market?
Who are the major players in the Plant-based shrimp market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Type
- 1.2.1 Frozen plant-based Shrimp
- 1.2.2 Refrigerated plant-based shrimp
- 1.2.3 Shelf stable plant-based shrimp
- 1.3 By Source
- 1.3.1 Seaweed
- 1.3.2 Legume Protein
- 1.3.3 Plant Based omega 3
- 1.3.4 Soy Protein
- 1.3.5 Pea Protein
- 1.3.6 Others (quinoa, oats, beans and seeds)
- 1.4 By Product Type
- 1.4.1 Breaded Vegan Shrimp
- 1.4.2 Crunchy Coconut Shrimp
- 1.4.3 Crispy Vegan Shrimp
- 1.4.4 Raw Vegan Shrimp
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 602 million → 2032: USD 1,147 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Plant-Based Shrimp Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Plant-Based Shrimp Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Plant-Based Shrimp Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Plant-Based Shrimp Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Plant-Based Shrimp Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Plant-Based Shrimp Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Plant-Based Shrimp Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Plant-Based Shrimp Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 602 million → 2032: USD 1,147 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Plant-Based Shrimp Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Type - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Frozen plant-based Shrimp
- 12.3.7.2 Refrigerated plant-based shrimp
- 12.3.7.3 Shelf stable plant-based shrimp
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Source - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Seaweed
- 12.4.7.2 Legume Protein
- 12.4.7.3 Plant Based omega 3
- 12.4.7.4 Soy Protein
- 12.4.7.5 Pea Protein
- 12.4.7.6 Others (quinoa, oats, beans and seeds)
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Product Type - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Breaded Vegan Shrimp
- 12.5.7.2 Crunchy Coconut Shrimp
- 12.5.7.3 Crispy Vegan Shrimp
- 12.5.7.4 Raw Vegan Shrimp
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global Plant-Based Shrimp Geographic Market Outlook, 2024-2032
- 13.1 Regional Market Size and Share, 2024
- 13.2 Regional Market Forecast, 2024-2032
- 13.3 Regional Pricing, Production and Demand Differences
- 13.4 North America
- 13.4.1 United States
- 13.4.2 Canada
- 13.4.3 Mexico
- 13.5 Europe
- 13.5.1 Germany
- 13.5.2 France
- 13.5.3 Italy
- 13.5.4 United Kingdom
- 13.5.5 Spain
- 13.5.6 Poland
- 13.5.7 Russia
- 13.5.8 Netherlands
- 13.5.9 Belgium
- 13.5.10 Sweden
- 13.5.11 Denmark
- 13.5.12 Norway
- 13.5.13 Rest of Europe
- 13.6 Asia Pacific
- 13.6.1 China
- 13.6.2 India
- 13.6.3 Japan
- 13.6.4 South Korea
- 13.6.5 Thailand
- 13.6.6 Indonesia
- 13.6.7 Vietnam
- 13.6.8 Malaysia
- 13.6.9 Australia
- 13.6.10 Rest of Asia Pacific
- 13.7 Latin America
- 13.7.1 Brazil
- 13.7.2 Argentina
- 13.7.3 Colombia
- 13.7.4 Chile
- 13.7.5 Rest of Latin America
- 13.8 Middle East
- 13.8.1 Saudi Arabia
- 13.8.2 United Arab Emirates
- 13.8.3 Turkey
- 13.8.4 Israel
- 13.8.5 Iran
- 13.8.6 Rest of the Middle East
- 13.9 Africa
- 13.9.1 South Africa
- 13.9.2 Egypt
- 13.9.3 Nigeria
- 13.9.4 Morocco
- 13.9.5 Rest of Africa
- 13.10 Regional Investment, Policy and Supply Chain Differences
- 13.11 Regional Competitive Landscape
- 13.12 Geographic Growth Hotspots
Chapter 14 Global Plant-Based Shrimp Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2024-2032
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 Global Plant-Based Shrimp Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2024
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2024-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Thai Union
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 ProExpo
- 17.4 Omarsa
- 17.5 Zhanjiang Guolian
- 17.6 Quoc Viet
- 17.7 Nekkanti Sea Foods
- 17.8 The Liberty Group
- 17.9 Devi Fisheries
- 17.10 Royal Greenland A/S
- 17.11 Pescanova
- 17.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

