
Market Overview
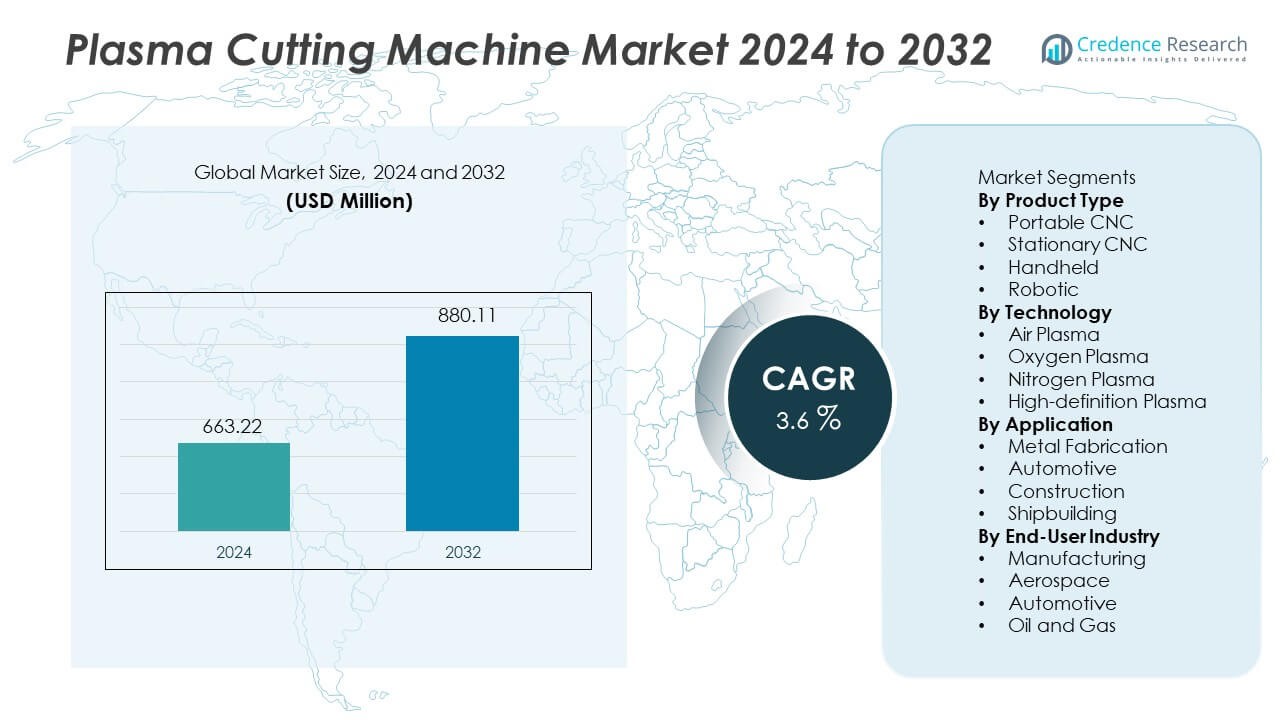
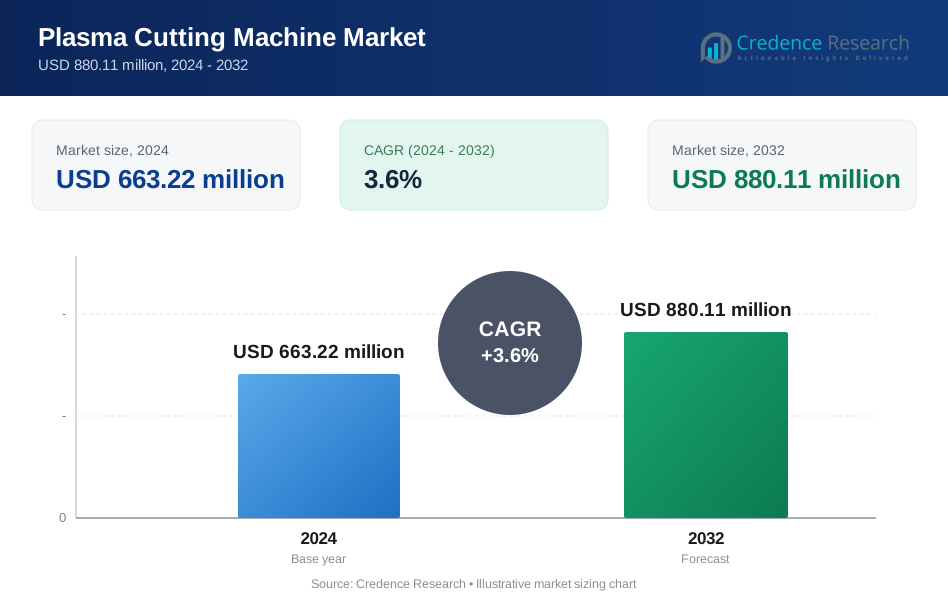
The Plasma Cutting Machine Market was valued at USD 663.22 million in 2024 and is projected to reach USD 880.11 million by 2032, registering a CAGR of 3.6% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Plasma Cutting Machine Market Size 2024 | USD 663.22 Million |
| Plasma Cutting Machine Market, CAGR | 3.6% |
| Plasma Cutting Machine Market Size 2032 | USD 880.11 Million |
Top players in the Plasma Cutting Machine market include Hypertherm Associates, Lincoln Electric, ESAB Corporation, Komatsu, Kjellberg Cutting Technology, Koike Aronson, Messer Cutting Systems, Voortman Steel Machinery, Hornet Cutting Systems, and Shandong Huayuan Welding and Cutting. These companies strengthen their position with CNC platforms, high-definition cutting, and automated solutions that support consistent metal processing across fabrication and construction. Asia Pacific remains the leading regional market with a 38% share, driven by strong industrialization, expanding construction, and growing automotive production across China, Japan, South Korea, and India. North America and Europe continue to invest in advanced systems and automated solutions that improve productivity, precision, and operating efficiency in metal fabrication environments.
Market Insights
- The Plasma Cutting Machine market reached USD 663.22 million in 2024 and is poised to reach USD 880.11 million by 2032 at a CAGR of 3.6% during the forecast period.
- Rising demand for precision metal processing and automation adoption in fabrication units strengthen growth across product types, with Portable CNC holding a 39% share due to flexible use in workshops and onsite applications.
- Market trends highlight increasing use of high-definition plasma and portable systems that support clean cutting, higher productivity, and reduced finishing time across automotive, construction, and machinery sectors.
- Competitive activity centers on technology upgrades, automated CNC integration, gas-efficient torches, and robotics that enhance cutting consistency, while cost sensitivity and competition from fiber lasers remain major restraints for small workshops.
- Asia Pacific leads regional demand with a 38% share, followed by North America at 26% and Europe at 22%, supported by strong metal fabrication bases and steady expansion across construction and industrial applications.
 Market Segmentation Analysis:
By Product Type
Portable CNC systems hold a 39% share in this segment due to rising use in small and mid-scale fabrication units that focus on flexible cutting needs and mobile operations. Portable models support field maintenance and onsite repair work across metals. Stationary CNC machines follow because large plants require continuous accuracy in thick plate cutting. Handheld tools serve repair jobs that need fast set-up in low-volume sites. Robotic cutting expands in automated welding lines where safety and repeat precision remain critical. Demand rises as manufacturers seek faster changeovers and compact footprints to support lean production goals.
- For instance, Hypertherm Associates introduced Powermax45 XP that provides professional grade power and supports reliable cutting of mild steel with superior cut and gouge quality, reducing the need for secondary preparation.
By Technology
Air plasma technology leads this segment with a 42% share due to lower operating cost and the ability to cut mild steel at higher speeds in metal workshops. Oxygen plasma supports stainless and carbon steel cutting where oxide layer removal matters during fabrication. Nitrogen plasma serves aluminum and non-ferrous metals used in transport and machinery components. High-definition plasma grows through precision cutting in automotive and aerospace, supported by cleaner edge quality and tight tolerances. Adoption improves because energy-efficient systems reduce power usage without lowering cut performance in high-duty cycles.
- For instance, Lincoln Electric's Spirit II high-definition plasma platform achieves rapid cutting speeds on common steel thicknesses and provides a consistent kerf width, ensuring high-quality, virtually dross-free cuts with a minimal edge bevel.
By Application
Metal fabrication remains the dominant application with a 47% share due to increasing demand for plate processing, custom metal panels, and structural steel components across industrial clusters. The automotive sector adopts plasma cutting to support chassis parts and body repair in service centers. Construction uses plasma in bridges, heavy frames, and structural beams where fast profile cutting supports project timelines. Shipbuilding requires wider plates and corrosion-resistant processing that benefit from accurate cutting speeds for hull sections. Growth accelerates as fabrication plants expand capacity and seek higher throughput with reduced thermal distortion on thick metals.
Key Growth Drivers
Rising Demand for Precision Metal Processing
Industrial firms seek accurate metal cutting for fabrication. Plasma systems support clean edges on many alloys. Manufacturers invest in advanced controls that lower errors and reduce rework cycles. Growing infrastructure and automotive production raise demand for high throughput operations across many regions. The shift from manual cutting to CNC units accelerates adoption in metal workshops. Companies focus on flexible machines that handle varied thickness without losing speed. Energy-efficient models lower running cost and improve shop margins. These benefits encourage many users to upgrade older equipment in phased steps.
- For instance, ESAB’s Cutmaster 60 marks a tested cutting capacity of 20 mm steel and reaches a maximum severance of 32 mm during continuous operation under certified industrial test conditions.
Automation Adoption Across Production Lines
Modern factories adopt automated plasma for repetitive and complex patterns. Robotic arms guide torches with constant speed for stable quality. Firms use vision systems and improved sensors to monitor cut paths in real time. Automated machine cells reduce manual handling and improve safety in high heat areas. Large workshops deploy integrated software to manage nesting, scheduling, and consumable planning. The link between CAD files and CNC tables lowers setup time for many parts. This change enables faster delivery cycles for fabrication partners that serve construction and vehicles.
- For instance, implementation of robotic plasma cutting cells combines CNC programming (G-code based) with automated torch control to cut complex shapes reliably across multiple metal types while maintaining consistent cut quality.
Expansion of Heavy Engineering and Construction Projects
Global construction growth increases demand for steel beams and structural frames. Plasma systems cut thick plates at high speeds that support project timelines in many sites. Heavy engineering uses the technology for machinery parts and equipment frames. Shipyards depend on plasma for hull sections that need wide panels. National infrastructure plans drive material demand for bridges, rail, and energy facilities. Fabricators require scalable capacity that portable and stationary systems can support. This creates strong orders from mid and large production houses that work under long contracts.
Key Trends and Opportunities
Shift Toward High-Definition and Clean Cutting
High-definition plasma improves edge quality and lowers secondary finishing work. Users seek narrow kerf and reduced slag on premium materials. Adoption grows in aerospace, transport, and heavy machinery that require precision. Vendors develop torches that manage heat input and gas control with better accuracy. This trend opens replacement demand for older models in many regions. Clean cutting reduces grinding time and improves worker safety. The focus on thin sheet quality strengthens adoption in automotive service centers and part suppliers. Technology advances in control systems unlock new precision gains across many metals.
- For instance, Kjellberg’s HiFocus 280i neo achieves an excellent certified cut on mild steel and maintains a narrow kerf in high-definition mode, confirmed through testing under the relevant EN ISO 9013 cut quality classification.
Growth of Portable Systems for Onsite Jobs
Portable CNC machines support field repairs in construction sites and offshore operations. Demand rises for compact tables that handle many thickness levels. Service firms use handheld options for emergency breakdown work. Portable systems reduce transport time and improve productivity during remote work. Mining and energy projects adopt mobile cutting to support field maintenance. The rise of rental services opens new business models for suppliers. Portable machines also support small workshops that lack floor area for large tables. This creates steady growth in entry level systems across developing markets.
- For instance, Miller Electric’s Spectrum 625 X-treme provides robust performance on mild steel up to its rated cutting capacity and uses Auto-Refire control that keeps arc transfer stable during multi-pierce cycles.
Key Challenges
High Initial Investment and Operating Cost
Many users face higher upfront cost for advanced CNC and robotic systems. Small shops find consumables and gas requirements costly during peak loads. Maintenance needs proper training and replacement parts that raise total expense. Energy consumption increases operating bills in long duty cycles. Firms compare plasma against laser options as prices fall for fiber units. The return on investment depends on production volume and material mix. This challenge slows adoption among small fabrication companies that rely on manual options.
Competition from Laser Cutting Technologies
Fiber laser machines provide high precision and minimal heat affected zones. Many industries adopt laser for thin sheet and complex contours. Laser delivers clean edges that lower grinding steps in premium segments. Suppliers of plasma respond with high-definition options to defend market share. Users evaluate cut quality, power needs, and gas usage before selection. Competition pressures pricing and limits margin for mid-range plasma models. This challenge encourages vendors to bundle software, service, and training to stay competitive.
Regional Analysis
North America
North America holds a 26% share driven by widespread adoption of CNC plasma systems across metal fabrication, construction, and automotive repair services. The United States supports demand from machinery workshops that require precision cutting for heavy equipment and custom metal projects. Energy and oil service companies use plasma for pipe sections and field repairs. Replacement of manual units with automated cutting strengthens market expansion. Canada invests in plant upgrades that improve processing efficiency and safety standards. Strong presence of fabrication clusters, robotics integration, and skilled labor encourages suppliers to introduce advanced control technologies across the region.
Europe
Europe accounts for a 22% share, supported by strong industrial bases in Germany, Italy, and France that prioritize clean cutting and accuracy for automotive, machinery, and structural steel applications. Growth in fabricated components for electric vehicles and renewable energy increases demand for efficient cutting systems in the region. EU regulations encourage energy-efficient equipment and low-emission industrial processes, driving interest in advanced torches and optimized gas use. High-definition systems gain traction in aerospace and high-strength steel processing. Vendors expand service networks to support automated cutting in advanced manufacturing clusters.
Asia Pacific
Asia Pacific leads the market with a 38% share due to strong metal fabrication industries in China, Japan, South Korea, and India. Expanding construction projects and rapid industrialization drive investment in CNC plasma equipment for structural steel, machinery parts, and heavy engineering. Automotive production encourages demand for precise cutting of body panels and underbody components. Local manufacturers introduce cost-competitive systems that accelerate adoption among small and mid-scale workshops. Government initiatives for industrial modernization and smart factories support automated processes. Increasing application in shipbuilding and large infrastructure projects strengthens long-term growth across the region.
Latin America
Latin America holds an 8% share led by rising industrial activity in Brazil and Mexico. Metal fabrication companies adopt plasma systems for construction steel, automotive components, and heavy equipment frames. Growing investment in industrial infrastructure and energy projects drives demand for thicker plate processing. Vendors expand distribution channels to serve mid-scale fabrication workshops that seek affordable CNC units. Handheld and portable equipment see rising use in field repairs across mining operations. Gradual modernization of metal workshops encourages demand for automated tables and high-capacity machines, although cost sensitivity and financing barriers remain key factors in adoption.
Middle East and Africa
Middle East and Africa represent a 6% share driven by oil, gas, and construction projects that require metal fabrication for pipelines, platforms, and structural steel. Gulf countries invest in advanced cutting systems for industrial maintenance, offshore structures, and heavy engineering equipment. Ship repair yards in the region rely on plasma cutting for hull plates and corrosion-resistant materials. Africa shows gradual growth supported by infrastructure upgrades and industrial investment in key markets such as South Africa. Demand for portable and handheld systems rises in field jobs, while limited technical skills and capital investment restrain wider adoption.
Market Segmentations:
By Product Type
- Portable CNC
- Stationary CNC
- Handheld
- Robotic
By Technology
- Air Plasma
- Oxygen Plasma
- Nitrogen Plasma
- High-definition Plasma
By Application
- Metal Fabrication
- Automotive
- Construction
- Shipbuilding
By End-User Industry
- Manufacturing
- Aerospace
- Automotive
- Oil and Gas
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
Competitive landscape in the Plasma Cutting Machine market features key players such as Hypertherm Associates, Lincoln Electric, ESAB Corporation, Komatsu, Kjellberg Cutting Technology, Koike Aronson, Messer Cutting Systems, Voortman Steel Machinery, Hornet Cutting Systems, and Shandong Huayuan Welding and Cutting. Leading companies focus on expanding product portfolios with advanced CNC control, high-definition cutting, and gas-efficient systems that strengthen precision and reduce operational cost in high-duty industrial use. Vendors invest in R&D to introduce automated tables, robotics integration, and IoT-based monitoring that support predictive maintenance and improve uptime in fabrication lines. Many suppliers expand global service networks to support after-sales, consumables, and training offerings, especially in Asia Pacific and North America where fabrication growth remains strong. Strategic partnerships, regional distribution agreements, and technology upgrades drive differentiation, while competition from laser cutting encourages plasma vendors to enhance cut quality and efficiency across multiple production settings.
Key Player Analysis
- Hypertherm Associates
- Lincoln Electric
- ESAB Corporation
- Komatsu
- Kjellberg Cutting Technology
- Koike Aronson
- Messer Cutting Systems
- Voortman Steel Machinery
- Hornet Cutting Systems
- Shandong Huayuan Welding and Cutting
Recent Developments
- In September 2025, Machitech expanded its U.S. manufacturing footprint and improved service capabilities by acquiring Victory CNC Plasma Systems, aiming to meet growing domestic demand and enhance product customization.
- In May 2024, Hypertherm Associates introduced the Powermax45 SYNC, featuring an innovative single-piece cartridge system designed to extend consumable life, reduce downtime, and simplify operator training for improved productivity.
- In 2024, Hypertherm launched the XPR460, integrated with advanced X-Definition technology, specifically engineered for cutting thicker metals with faster speeds, enhanced beveling precision, and improved cut quality.
Report Coverage
The research report offers an in-depth analysis based on Product Type, Technology, Application, End-User Industry and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Future demand will rise as industries seek precise metal cutting capabilities.
- CNC systems will gain wider use in fabrication and automotive workshops.
- High-definition technology will expand in aerospace and machinery applications.
- Portable units will grow due to onsite repairs and field maintenance needs.
- Automation and robotics integration will increase for repetitive cutting tasks.
- Energy-efficient designs will support lower operating costs for users.
- Smart controls will improve cut quality and minimize material waste.
- Service providers will expand training and after-sales support in major regions.
- Regional manufacturing growth in Asia Pacific will drive new installations.
- Competition with laser cutting will push vendors to enhance cut performance.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Precision Metal Processing Demand
Manufacturers require accurate, clean cuts for a variety of metals, driving adoption of advanced plasma cutting machines that reduce errors and minimize rework, especially in fabrication and automotive sectors.
Automation and CNC Integration
The shift from manual to automated CNC plasma systems enables higher throughput, repeatability, and safety, supporting growth in industries seeking to streamline production and reduce labor costs.
Expansion of Construction and Heavy Engineering
Large-scale infrastructure and construction projects globally are increasing demand for plasma cutting machines capable of processing thick steel plates and structural components efficiently.
Growth in Portable and Onsite Solutions
Rising need for field maintenance, repairs, and flexible workshop operations is boosting demand for portable CNC and handheld plasma cutting systems, particularly in developing regions and remote job sites.
Technological Advancements in High-Definition Plasma
Continuous improvements in high-definition plasma technology are enabling cleaner cuts, reduced finishing time, and better energy efficiency, encouraging upgrades and new installations across metal fabrication and machinery industries.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for the Plasma Cutting Machine market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Plasma Cutting Machine market projected to grow between 2024 and 2032?
Which Plasma Cutting Machine market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Plasma Cutting Machine market?
Who are the leading companies in the Plasma Cutting Machine market?
Which region commanded the largest share of the Plasma Cutting Machine market in 2024?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Technology
- 1.2.1 Air Plasma
- 1.2.2 Oxygen Plasma
- 1.2.3 Nitrogen Plasma
- 1.2.4 High-definition Plasma
- 1.3 By Application
- 1.3.1 Metal Fabrication
- 1.3.2 Automotive
- 1.3.3 Construction
- 1.3.4 Shipbuilding
- 1.4 By Product Type
- 1.4.1 Portable CNC
- 1.4.2 Stationary CNC
- 1.4.3 Handheld
- 1.4.4 Robotic
- 1.5 By End-User Industry
- 1.5.1 Manufacturing
- 1.5.2 Aerospace
- 1.5.3 Automotive
- 1.5.4 Oil and Gas
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 663.22 million → 2032: USD 880.11 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Plasma Cutting Machine Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Plasma Cutting Machine Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Plasma Cutting Machine Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Plasma Cutting Machine Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Plasma Cutting Machine Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Plasma Cutting Machine Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Plasma Cutting Machine Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Plasma Cutting Machine Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 663.22 million → 2032: USD 880.11 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Plasma Cutting Machine Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Technology - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Air Plasma
- 12.3.7.2 Oxygen Plasma
- 12.3.7.3 Nitrogen Plasma
- 12.3.7.4 High-definition Plasma
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Application - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Metal Fabrication
- 12.4.7.2 Automotive
- 12.4.7.3 Construction
- 12.4.7.4 Shipbuilding
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Product Type - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Portable CNC
- 12.5.7.2 Stationary CNC
- 12.5.7.3 Handheld
- 12.5.7.4 Robotic
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 By End-User Industry - Market Size and Forecast, 2024-2032
- 12.6.1 Segment Definition and Scope
- 12.6.2 Historical Market Size
- 12.6.3 Revenue Forecast, 2024-2032
- 12.6.4 Volume Forecast, 2024-2032
- 12.6.5 Base-Year Market Share, 2024
- 12.6.6 Segment CAGR and Growth Drivers
- 12.6.7 Subsegment Market Size and Forecast
- 12.6.7.1 Manufacturing
- 12.6.7.2 Aerospace
- 12.6.7.3 Automotive
- 12.6.7.4 Oil and Gas
- 12.6.8 Subsegment Pricing and Adoption Trends
- 12.6.9 Leading Suppliers and Competition
- 12.6.10 Regional Demand and Opportunities
- 12.7 Segment Growth Comparison
- 12.8 Segment Attractiveness and Priority Matrix
Chapter 13 Global Plasma Cutting Machine End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Plasma Cutting Machine Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Plasma Cutting Machine Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Plasma Cutting Machine Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Hypertherm Associates
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Lincoln Electric
- 18.4 ESAB Corporation
- 18.5 Komatsu
- 18.6 Kjellberg Cutting Technology
- 18.7 Koike Aronson
- 18.8 Messer Cutting Systems
- 18.9 Voortman Steel Machinery
- 18.10 Hornet Cutting Systems
- 18.11 Shandong Huayuan Welding and Cutting
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

