
Population Health Management Market Overview:
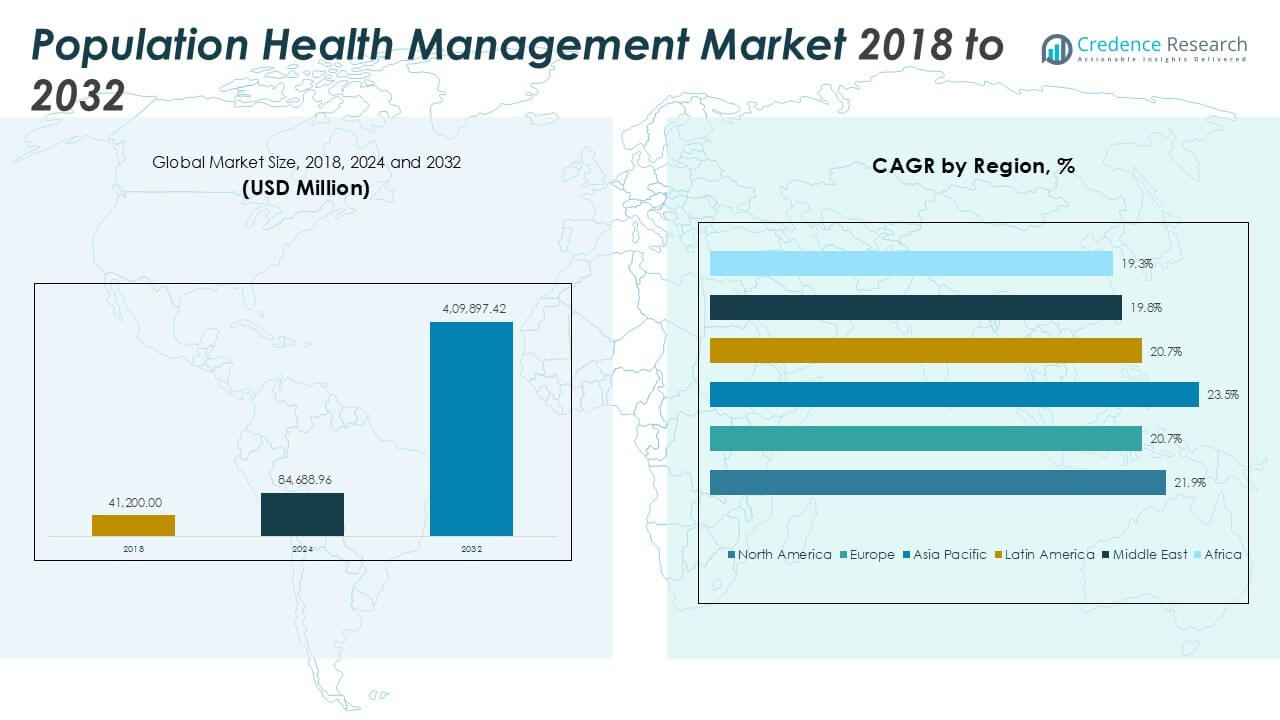
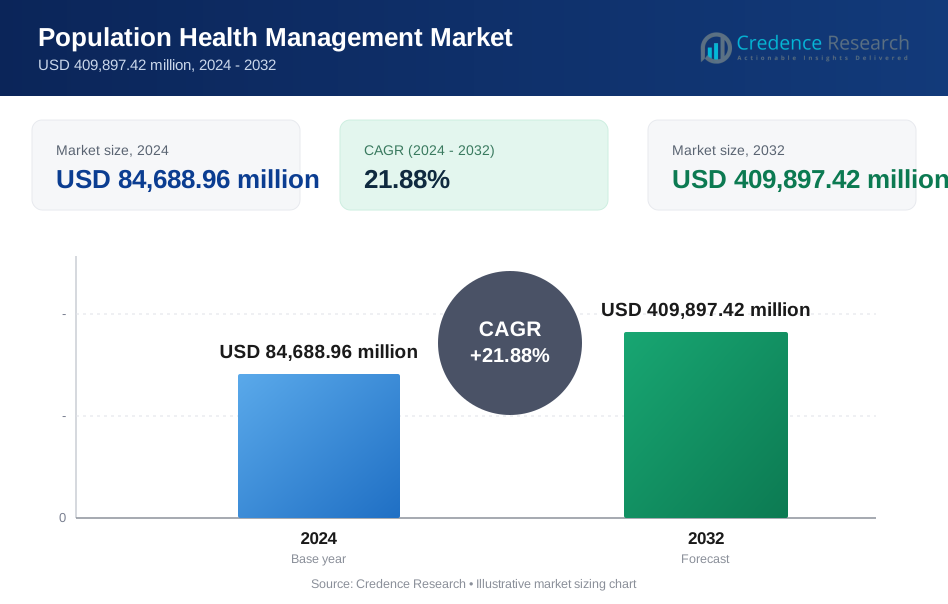
Population Health Management market size was valued at USD 41,200.00 million in 2018, reached USD 84,688.96 million in 2024, and is anticipated to reach USD 409,897.42 million by 2032, at a CAGR of 21.88% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Population Health Management Market Size 2024 | USD 84,688.96 million |
| Population Health Management Market, CAGR | 21.88% |
| Population Health Management Market Size 2032 | USD 409,897.42 million |
Top players in the population health management market include Optum, Oracle, Veradigm LLC, McKesson Corporation, eClinicalWorks, Philips, Athenahealth, and Conifer Health Solutions. These companies dominate the competitive landscape by offering integrated platforms that support care coordination, data analytics, and risk management. They leverage AI, cloud infrastructure, and interoperable systems to enhance efficiency across healthcare settings. In terms of regional performance, North America leads the market with a 45.8% share in 2024, driven by advanced healthcare IT infrastructure, strong regulatory backing, and early adoption of value-based care models. Asia Pacific is the fastest-growing region, propelled by rapid digital health investments and rising chronic disease burdens.
Population Health Management Market Insights
- The Population Health Management market was valued at USD 84,688.96 million in 2024 and is projected to reach USD 409,897.42 million by 2032, growing at a CAGR of 21.88%.
- Growing focus on value-based care models and chronic disease management drives PHM adoption across providers and payers.
- AI-powered predictive analytics, EHR integration, and cloud-based delivery are shaping innovation in the market.
- Key players like Optum, Oracle, McKesson, and Veradigm lead with broad product portfolios and strategic partnerships, while smaller vendors expand through niche solutions.
- North America held the largest regional share at 45.8% in 2024, while Asia Pacific is the fastest-growing region with a 23.5% CAGR; by product, software accounts for over 60% of market share due to demand for integrated data tools.
Population Health Management Market Segmentation Analysis:
By Product
Software dominates the population health management market by product, accounting for over 60% of the total revenue share in 2024. This growth stems from increased adoption of data analytics, care coordination, and risk management platforms across healthcare systems. Hospitals and providers seek integrated solutions that track patient data, optimize treatment paths, and manage chronic conditions. Regulatory mandates and the shift to value-based care models further drive demand for robust software tools. Vendors continue to enhance capabilities in predictive analytics, population stratification, and AI-based insights, making software a critical enabler of outcome-focused healthcare delivery.
- For instance, Cerner deploys population health software used by more than 27,000 healthcare facilities worldwide.
By End-Use Segment
Providers represent the largest end-use segment, holding more than 65% of the market share in 2024. Hospitals, integrated delivery networks (IDNs), and physician groups increasingly rely on population health tools to manage patient cohorts, reduce readmissions, and comply with evolving reimbursement models. The focus on preventive care, chronic disease management, and coordinated service delivery boosts provider adoption. Value-based contracts with payers and CMS quality initiatives encourage data-driven care decisions. Providers are also leveraging real-time dashboards and EHR integration to improve population-level visibility and performance tracking across care settings.
- For instance, Epic Systems supports population health programs across hospital networks serving over 250 million patient records globally.
By Delivery Mode
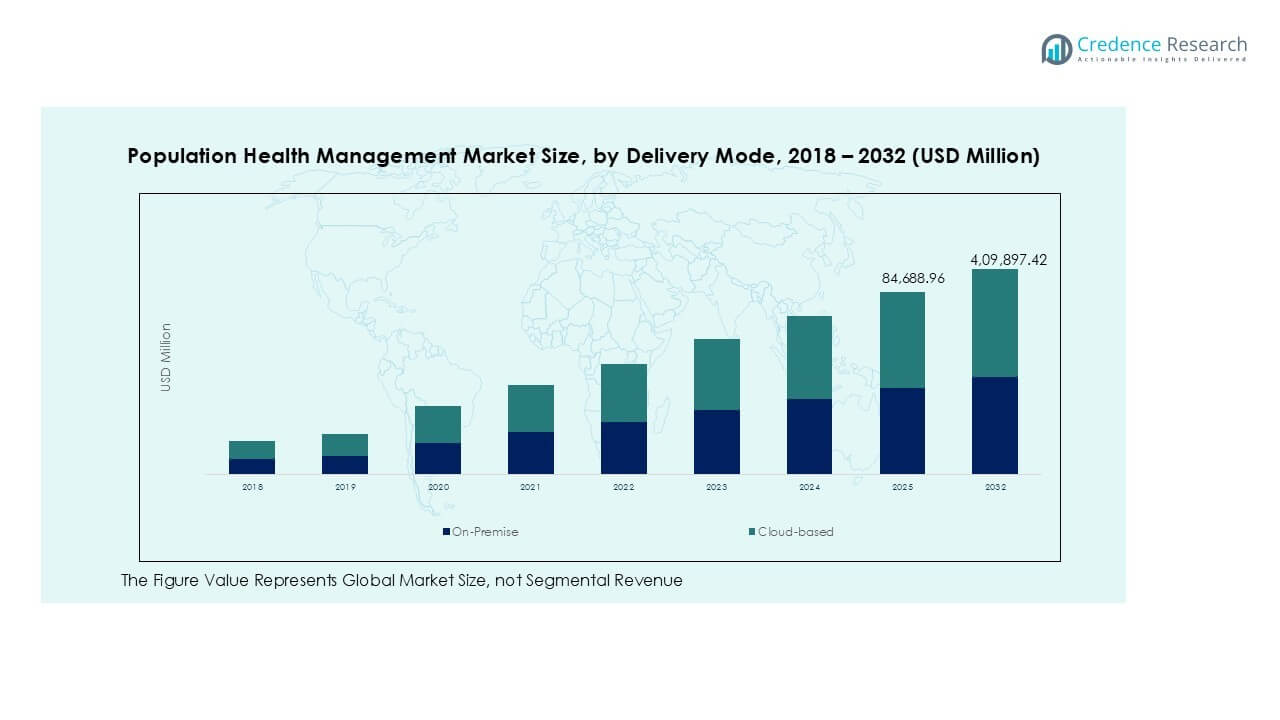
Cloud-based solutions dominate the delivery mode segment with over 70% share in 2024, outpacing on-premise models. The shift toward cloud infrastructure supports faster deployment, scalability, and remote access, especially for multi-site providers and payers. Rising cybersecurity improvements and compliance with HIPAA and GDPR standards have boosted confidence in cloud platforms. Cost savings on IT infrastructure and real-time collaboration across stakeholders also make cloud delivery more attractive. Vendors offering Software-as-a-Service (SaaS) models benefit from recurring revenue streams and flexible subscription-based pricing, enabling wider access across medium and large healthcare organizations.
Population Health Management Market Key Growth Drivers
Shift Toward Value-Based Care Models
The transition from fee-for-service to value-based care models drives sustained growth in the population health management market. Healthcare systems are incentivized to reduce costs while improving patient outcomes. PHM platforms enable providers and payers to monitor population-wide metrics, identify at-risk individuals, and deploy preventive strategies. As governments and private insurers tie reimbursements to quality metrics, stakeholders increasingly invest in population analytics tools. These systems help reduce readmissions, manage chronic diseases, and improve care coordination. With CMS and private payers expanding alternative payment models, PHM tools become critical for navigating bundled payments, shared savings programs, and accountable care organizations (ACOs).
- For instance, United Health Group uses Optum population health platforms to support more than 100,000 physicians in value-based arrangements.
Rising Burden of Chronic Diseases
The increasing prevalence of chronic conditions such as diabetes, heart disease, and respiratory disorders significantly fuels demand for population health tools. These diseases drive the majority of healthcare costs and require continuous, coordinated management. PHM solutions enable segmentation of patients based on risk profiles and help customize care pathways. By tracking real-time health data and care interventions, providers can lower emergency visits and improve long-term outcomes. The aging global population further accelerates this trend, creating demand for proactive chronic care management and remote monitoring tools. Governments and employers are aligning strategies to curb escalating treatment costs and workforce productivity losses.
- For instance, Kaiser Permanente manages chronic disease populations using PHM tools across more than 12 million members.
Government Support and Policy Mandates
Government-led initiatives supporting healthcare IT adoption play a pivotal role in accelerating PHM deployment. In the U.S., programs under the Affordable Care Act, Medicare Shared Savings Program (MSSP), and Medicaid expansion promote preventive care and population-level risk analysis. Internationally, countries are integrating digital health frameworks and pushing interoperability standards. Regulatory mandates on data sharing, clinical reporting, and performance tracking drive investments in analytics platforms. Financial incentives, grants, and subsidies help providers and payers implement PHM technologies across fragmented care ecosystems. As more regions mandate electronic health records (EHR) usage and health information exchanges (HIE), the groundwork strengthens PHM scalability.
Population Health Management Market Key Trends & Opportunities
Integration of Artificial Intelligence and Predictive Analytics
Artificial Intelligence (AI) and machine learning are transforming population health management by enhancing predictive capabilities. AI algorithms help identify high-risk individuals, forecast disease progression, and optimize resource allocation. Predictive models improve decision-making in chronic care, behavioral health, and hospital admissions. With growing access to electronic health records, claims data, and social determinants of health, PHM platforms now offer more accurate insights for targeted interventions. AI-based alerts also support timely outreach for preventive screenings or follow-ups. Vendors that integrate AI-driven care guidance and automation within their offerings are gaining competitive advantages and fostering clinical efficiency at scale.
- For instance, IBM deployed AI-driven population health analytics within its Watson Health portfolio, analyzing over 300 million patient records from claims, EHRs, and social data sources.
Growing Demand for Interoperability and Unified Health Records
As care becomes more distributed across multiple settings, the need for interoperable systems has become urgent. Unified health records across providers, payers, and patients are key to effective PHM. Interoperability enhances data flow and enables real-time insights, care coordination, and patient engagement. The demand for seamless integration with EHRs, claims platforms, and wellness applications creates opportunities for vendors offering robust APIs and standards-based architectures. National efforts such as TEFCA in the U.S. and NHS Digital strategies in the UK support this transition. Organizations that achieve greater data connectivity improve care outcomes while reducing operational silos.
Population Health Management Market Key Challenges
Data Privacy and Regulatory Compliance Issues
Data security remains a critical concern in population health management, given the sensitivity of patient health information. Managing large volumes of data across multiple stakeholders increases the risk of breaches and non-compliance. Strict regulations such as HIPAA, GDPR, and local data residency laws create compliance complexity. Providers and payers must ensure encryption, access controls, and audit trails across cloud and on-premise systems. The rise of third-party integrations and wearables also heightens exposure. Failure to adhere to data protection frameworks can result in hefty penalties, legal liability, and loss of public trust. This makes robust cybersecurity a top priority.
Integration Complexity Across Fragmented IT Systems
One of the biggest challenges in deploying PHM solutions is integrating them with legacy infrastructure and diverse data sources. Healthcare organizations often operate across siloed systems with incompatible formats and outdated interfaces. Aligning EHRs, lab reports, imaging systems, and payer databases into a single PHM platform requires significant investment and time. Interoperability gaps limit real-time data access and hinder seamless care coordination. Smaller practices and rural providers face more barriers due to budget constraints and lack of IT expertise. Without standardized frameworks and unified governance, the full benefits of population health tools remain underutilized.
Population Health Management Market Regional Analysis
North America
North America led the global population health management market with a 2024 revenue of USD 38,778.57 million, accounting for over 45.8% of the total share. The market grew from USD 19,046.76 million in 2018 and is projected to reach USD 187,487.82 million by 2032, expanding at a CAGR of 21.9%. The region benefits from strong healthcare IT infrastructure, early EHR adoption, and favorable policy frameworks like the Affordable Care Act. High provider-payer collaboration and value-based care contracts drive PHM platform deployment across hospitals and accountable care organizations in the U.S. and Canada.
Europe
Europe held the second-largest share in 2024, reaching USD 15,902.27 million or around 18.8% of the global market. The market rose from USD 8,157.60 million in 2018 and is forecasted to hit USD 71,220.77 million by 2032, with a CAGR of 20.7%. Government-backed digital health strategies, aging populations, and chronic disease management initiatives support market growth. Countries like Germany, the UK, and France invest in national EHR rollouts and care coordination systems. The EU’s push for cross-border health data interoperability enhances regional adoption of population-level analytics and preventive care models.
Asia Pacific
Asia Pacific emerged as the fastest-growing region, with a CAGR of 23.5% between 2024 and 2032. The market expanded from USD 9,270.00 million in 2018 to USD 19,973.54 million in 2024, capturing 23.6% of the global market share. It is expected to reach USD 107,516.42 million by 2032. Rapid digital health adoption in China, India, Japan, and Australia fuels the expansion. Government healthcare reforms, growing insurance penetration, and rising chronic disease cases accelerate demand for cloud-based PHM solutions. Regional investments in hospital digitization and AI-powered health platforms drive future scalability.
Latin America
Latin America reached USD 5,199.05 million in 2024, representing approximately 6.1% of the global market. The market grew from USD 2,554.40 million in 2018 and is set to reach USD 23,310.86 million by 2032, growing at a CAGR of 20.7%. Brazil and Mexico lead regional adoption due to public health digitization and insurance modernization efforts. Governments support preventive care and health system efficiency using PHM tools. Despite infrastructure limitations, cloud deployment models and international partnerships enhance scalability. The region benefits from expanding private healthcare providers and increased demand for chronic disease management.
Middle East
The Middle East population health management market stood at USD 2,252.18 million in 2024, holding a 2.7% share. It grew from USD 1,194.80 million in 2018 and is projected to reach USD 9,470.88 million by 2032, posting a CAGR of 19.8%. GCC countries such as Saudi Arabia and the UAE drive demand through large-scale health transformation programs and digital health mandates. Investments in smart hospitals, AI-based care models, and value-based payment systems support the regional outlook. Public-private partnerships enhance integration across primary and tertiary care centers.
Africa
Africa accounted for 3.0% of the global PHM market in 2024, valued at USD 2,583.36 million, up from USD 976.44 million in 2018. The market is forecast to reach USD 10,890.67 million by 2032 at a CAGR of 19.3%. Growth is supported by rising chronic disease cases, donor-led digital health projects, and mobile-based care delivery. Countries like South Africa, Kenya, and Nigeria invest in telehealth and basic PHM platforms to extend access. Despite infrastructure challenges, NGOs and global health organizations play a key role in deploying scalable population-level care management initiatives.
Population Health Management Market Segmentations:
By Product
- Software
- Services
By End-Use Segment
- Providers
- Payers
- Employer Groups
By Delivery Mode
- On-Premise
- Cloud-Based
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Population Health Management Market Competitive Landscape
The population health management market features a dynamic competitive landscape dominated by established healthcare IT firms and specialized solution providers. Key players include Optum, Oracle, Veradigm LLC, McKesson Corporation, eClinicalWorks, Philips, Athenahealth, and Conifer Health Solutions. These companies offer comprehensive platforms that integrate data analytics, care coordination, and risk stratification tools. Strategic partnerships, acquisitions, and product innovations are common as firms aim to expand client base and strengthen capabilities. Cloud-based deployment models and AI integration have become critical differentiators. Veradigm focuses on physician-centric solutions, while Oracle leverages its expansive cloud and EHR ecosystem. Companies like Cedar Gate Technologies (Enli Health) and Welltok (Virgin Pulse) target value-based care with consumer engagement platforms. Market competition intensifies as regulatory compliance, data interoperability, and real-time analytics become essential. Vendors also compete by enhancing usability, security, and patient engagement features to meet the needs of providers, payers, and employer groups seeking population-wide outcome improvement.
Key Player Analysis
- Veradigm LLC
- Oracle
- Conifer Health Solutions, LLC
- eClinicalWorks
- Enli Health Intelligence (Cedar Gate Technologies)
- McKesson Corporation
- Medecision
- Optum, Inc.
- Koninklijke Philips N.V.
- Athenahealth, Inc.
- Welltok (Virgin Pulse)
Recent Developments
- In February 2024, Everside Health and Marathon Health partnered to deliver advanced primary care and strengthen its healthcare software and solutions.
- In December 2023, Golden Valley Health Centers (GVHC) announced its participation in the Population Health Management Initiative and launched an innovative immunization program. The initiative is aimed at expanding access to vaccines and streamlining the vaccination processes.
- In August 2023, Epic Systems Corporation partnered with Microsoft to accelerate the impact of generative AI on healthcare solutions, including population healthcare management tools, among others.
Report Coverage
The research report offers an in-depth analysis based on Product, End-Use Segment, Delivery Mode and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Population health management adoption will grow as healthcare shifts further toward value-based care.
- AI and machine learning will improve risk prediction, patient segmentation, and care pathway optimization.
- Cloud-based platforms will dominate due to scalability, remote access, and lower IT infrastructure needs.
- Interoperability will become critical as providers demand unified health records across care systems.
- Patient engagement tools will gain importance to support self-care and reduce readmissions.
- Governments will expand support for digital health infrastructure and data-sharing frameworks.
- Chronic disease management will remain a key application area driving continuous market demand.
- Strategic partnerships between IT firms and healthcare providers will reshape the competitive landscape.
- Emerging economies in Asia Pacific will drive the next wave of PHM market expansion.
- Data privacy, cybersecurity, and regulatory compliance will remain top priorities for solution providers.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Shift Toward Value-Based Care Models
Healthcare systems are moving from fee-for-service to value-based care, incentivizing providers and payers to improve patient outcomes and reduce costs. Population health management (PHM) platforms enable tracking of quality metrics, risk stratification, and care coordination, which are essential for success in value-based contracts and reimbursement models.
Rising Burden of Chronic Diseases
The increasing prevalence of chronic conditions such as diabetes, cardiovascular diseases, and respiratory disorders is driving demand for PHM solutions. These tools help segment patient populations, enable proactive interventions, and support long-term disease management, reducing hospitalizations and improving outcomes.
Government Support and Policy Mandates
Government initiatives and regulatory mandates, such as the Affordable Care Act and national digital health strategies, are accelerating PHM adoption. Financial incentives, grants, and requirements for electronic health records and data sharing are pushing providers and payers to invest in PHM technologies.
Advancements in AI and Predictive Analytics
The integration of artificial intelligence and machine learning into PHM platforms enhances predictive capabilities, enabling early identification of at-risk individuals and optimizing care pathways. These innovations improve decision-making, resource allocation, and patient engagement, making PHM solutions more effective and attractive.
Expansion of Cloud-Based Delivery Models
Cloud-based PHM solutions offer scalability, remote access, and cost savings on IT infrastructure, making them especially appealing for multi-site providers and payers. Improved cybersecurity and compliance with data protection regulations have increased confidence in cloud platforms, accelerating their adoption across the healthcare sector.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for the Population Health Management market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Population Health Management market projected to grow between 2024 and 2032?
Which Population Health Management market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Population Health Management market?
Who are the leading companies in the Population Health Management market?
Which region commanded the largest share of the Population Health Management market in 2024?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Product
- 1.2.1 Software
- 1.2.2 Services
- 1.3 By Delivery Mode
- 1.3.1 On-Premise
- 1.3.2 Cloud-Based
- 1.4 By End-Use Segment
- 1.4.1 Providers
- 1.4.2 Payers
- 1.4.3 Employer Groups
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 84,688.96 million → 2032: USD 409,897.42 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Population Health Management Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Population Health Management Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Population Health Management Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Population Health Management Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Population Health Management Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Population Health Management Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Population Health Management Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Population Health Management Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 84,688.96 million → 2032: USD 409,897.42 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Population Health Management Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Product - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Software
- 12.3.7.2 Services
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Delivery Mode - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 On-Premise
- 12.4.7.2 Cloud-Based
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By End-Use Segment - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Providers
- 12.5.7.2 Payers
- 12.5.7.3 Employer Groups
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global Population Health Management End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Population Health Management Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Population Health Management Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Population Health Management Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Optum
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Oracle
- 18.4 Veradigm LLC
- 18.5 McKesson Corporation
- 18.6 eClinicalWorks
- 18.7 Philips
- 18.8 Athenahealth
- 18.9 Conifer Health Solutions
- 18.10 Cedar Gate Technologies
- 18.11 Welltok (Virgin Pulse)
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

