
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
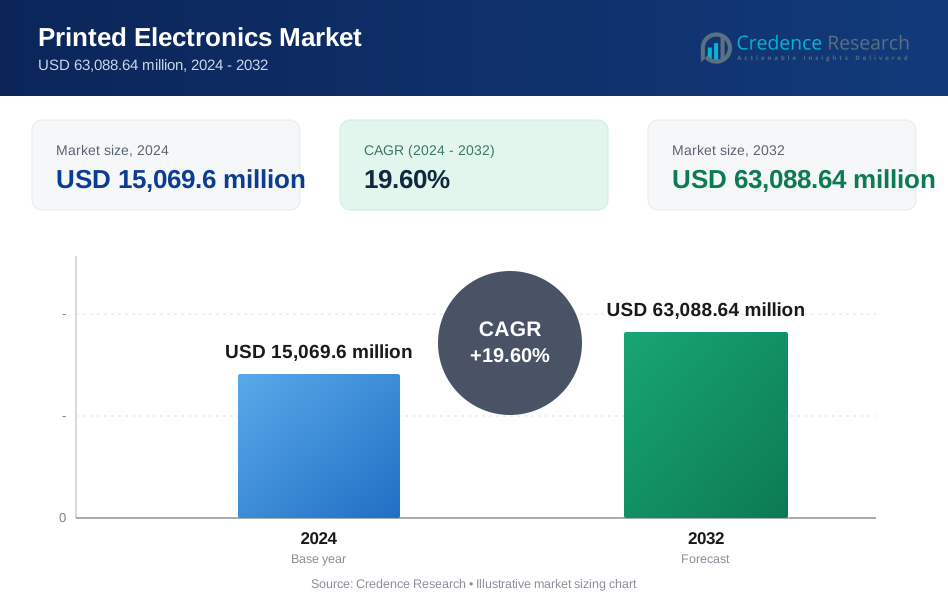
| Printed Electronics Market Size 2024 | USD 15,069.6 Million |
| Printed Electronics Market, CAGR | 19.60% |
| Printed Electronics Market Size 2032 | USD 63,088.64 Million |
Market Overview
The Printed Electronics Market is set to expand significantly from USD 15,069.6 million in 2024 to USD 63,088.64 million by 2032, achieving a robust compound annual growth rate (CAGR) of 19.60%.
The Printed Electronics Market is driven by the increasing demand for flexible, lightweight, and cost-effective electronic components in consumer electronics, automotive, and healthcare sectors. Key trends include advancements in organic electronics, enhancing performance and scalability, and the growing adoption of printed sensors and displays for wearable technology. Additionally, the push towards sustainable manufacturing processes is accelerating the use of eco-friendly materials in printed electronics. Innovations in inkjet printing and roll-to-roll processing are further expanding the market, enabling high-volume production and reducing costs, which supports the rapid growth of this sector.
The printed electronics market is characterized by a strong presence of key players across various regions. Samsung Electronics Co., Ltd. and LG Display Co., Ltd. from South Korea, alongside Molex, LLC and DuPont de Nemours, Inc. from the US, are leading innovators in the industry. Agfa-Gevaert Group in Belgium and Nissha Co., Ltd. in Japan contribute significantly to advancements in printed electronics. BASF in Germany and NovaCentrix in the US are also pivotal, while E Ink Holdings Inc. from Taiwan is renowned for its electronic paper technologies. This global distribution highlights the international demand and technological leadership driving market growth.
Market Drivers
Rise of Internet of Things (IoT) The burgeoning Internet of Things (IoT) ecosystem is driving a significant demand for innovative electronics manufacturing solutions. For instance, the IoT ecosystem is rapidly expanding, with an estimated 31 billion connected devices globally by 2020, and this number is expected to grow significantly. The proliferation of interconnected devices necessitates electronics that are flexible, lightweight, and energy-efficient, making printed electronics an ideal choice. These components are well-suited for a variety of IoT applications, such as wearable devices and smart sensors, due to their ability to be seamlessly integrated into diverse form factors while maintaining low power consumption and cost-effectiveness.
Demand for Flexible and Wearable Electronics The increasing popularity of wearable technology, including smartwatches and fitness trackers, has amplified the need for flexible and comfortable electronic components. Printed electronics are integral to this sector, providing the thin, lightweight, and flexible components that are essential for wearable devices. In fact, the use of printed electronics in wearables is anticipated to grow by 25% annually, reflecting their increasing adoption. This flexibility enhances user comfort and functionality, driving the adoption of printed electronics in wearable technology and supporting the growth of this sector.
Advancements in Printing Technologies Recent advancements in printing technologies, such as inkjet and roll-to-roll printing, are significantly improving the capabilities of printed electronics. For instance, advancements in inkjet and roll-to-roll printing have led to a 50% reduction in production time and a 30% decrease in manufacturing costs for printed electronics. These technologies have enabled the production of electronics with 10 times higher resolution, making them suitable for a wide range of applications, from medical devices to smart packaging. As a result, printed electronics are becoming more viable for diverse applications, offering better performance and scalability while reducing manufacturing complexities.
Significant Cost Advantages Printed electronics present notable cost advantages over traditional silicon-based electronics. For instance, printed electronics offer a cost reduction of up to 60% compared to traditional silicon-based electronics. The use of high-throughput printing processes and simpler materials contributes to reduced manufacturing costs, making them suitable for mass production and cost-sensitive applications. This cost-effectiveness, combined with the ability to create flexible and lightweight components, positions printed electronics as a competitive alternative in various industries.
Market Trends
Integration with IoT and AI Technologies Printed electronics are increasingly becoming integral to the expanding Internet of Things (IoT) ecosystem. For instance, the integration of printed electronics with IoT has led to a 20% increase in the efficiency of smart devices. The use of AI and ML for real-time data analysis from printed sensors has resulted in a 15% improvement in predictive maintenance accuracy. This synergy is creating advanced devices with enhanced performance, such as smart thermostats that can reduce energy consumption by 10% through optimized control algorithms. This integration involves merging functionalities such as sensors, antennas, and other components into a single, miniaturized unit, enhancing the versatility and efficiency of IoT devices. Additionally, the synergy between printed electronics and Artificial Intelligence (AI) and Machine Learning (ML) is driving innovation. AI/ML technologies are being used to analyze the vast data generated by printed sensors in real-time, enabling predictive maintenance, process optimization, and self-healing capabilities. This combination of printed electronics with IoT and AI/ML is leading to the creation of advanced, intelligent devices that offer enhanced performance and functionality across various applications.
Customization, Sustainability, and Emerging Technologies The shift towards customizable printed electronics is transforming traditional mass-production models. For instance, the shift towards customizable printed electronics has enabled a 30% reduction in production time with on-demand manufacturing techniques like roll-to-roll printing. The industry’s focus on sustainability has seen the adoption of recyclable substrates and eco-friendly inks, leading to a 25% decrease in the environmental impact of printed electronics production. Emerging technologies like additive manufacturing are enabling the creation of ultra-fine structures, with some sensors now achieving a 50% increase in sensitivity. These advancements are revolutionizing sectors such as healthcare, where printed electronics are used in wearable health monitors, potentially improving patient outcomes by 40% through enhanced diagnostics and personalized treatment plans.
Market Challenges Analysis
Technical and Performance Limitations Despite advancements in printed electronics, significant technical challenges persist. Printed electronics often fall short of the performance capabilities of traditional silicon-based technologies, particularly in terms of conductivity, transistor speed, and overall circuit complexity. These limitations can restrict their use in high-performance applications where silicon-based solutions currently excel. Furthermore, material limitations and compatibility issues with conductive inks present obstacles. Not all inks meet the conductivity standards of traditional electronics, and their compatibility with various printing techniques is not universal. This issue hinders the development of versatile, all-encompassing printing platforms. Integration with existing electronics also poses difficulties, as differences in material properties, operating voltages, and fabrication processes complicate seamless integration with traditional silicon-based systems.
Manufacturing Challenges and Market Barriers Scaling up from prototyping to high-volume manufacturing introduces several hurdles for printed electronics. Achieving consistent quality, uniformity, and production speed across large batches remains a challenge for many printing techniques. The lack of standardized materials, processes, and design tools further complicates large-scale adoption and compatibility between components. Additionally, the high initial investment required for research, development, equipment, and infrastructure can be prohibitive, especially for smaller companies. Sustainability remains another area of concern, as some inks and substrates still contain potentially harmful substances, complicating efforts to develop truly eco-friendly printed electronics. Lastly, the industry faces competition from established technologies and a knowledge gap among potential users. Demonstrating the unique value proposition and educating the market about the benefits of printed electronics are crucial for broader acceptance and market penetration. Intellectual property challenges also arise with rapid innovation, necessitating clear ownership of designs and processes to foster ongoing research and development.
Market Segmentation Analysis:
By Technology:
The printed electronics market is diverse, with several technologies driving its growth. Flexography is widely used for high-volume printing due to its speed and efficiency, making it suitable for applications like smart packaging and labels. Inkjet printing is favored for its precision and ability to create fine patterns, essential for high-resolution electronics and prototypes. Screen printing remains popular for its robustness and versatility, often employed in large-area applications and thicker layers of conductive inks. Offset printing offers high-quality results and is used in specialized applications where precision and color consistency are crucial. Other technologies, such as gravure printing and aerosol jet printing, are also emerging, providing unique capabilities like ultra-fine structures and flexibility in printing various substrates.
By Material:
The choice of materials in printed electronics significantly impacts performance and application suitability. Substrates range from organic materials like polymers and papers to inorganic materials including silicon, glass, and metals. Organic substrates such as polymers and fabrics are valued for their flexibility and lightweight properties, making them ideal for wearable and flexible electronics. In contrast, inorganic substrates like silicon and metals are preferred for their durability and high-performance characteristics. The choice of inks further influences electronic properties, with conductive inks being essential for electrical pathways, dielectric inks for insulation, and semiconductive inks for transistor applications. Each material choice caters to specific needs, enabling a broad spectrum of applications across industries.
Segments:
Based on Technology
-
- Flexography
- Inkjet Printing
- Screen Printing
- Offset Printing
- Others (Gravure Printing, Aerosol Jet Printing, etc.)
Based on Material
-
- Substrates
- Organic Materials
- Substrates
- Polymers
- Papers
- Fabrics
-
-
- Inorganic Materials
-
- Silicon
- Glass
- Metals
-
- Inks
- Conductive Inks
- Dielectric Inks
- Semiconductive Inks
- Inks
Based on Application
-
- Sensors & Switches
- Displays
- Medical Wearables
- Photovoltaic Cells
- Antennas
- Heaters
- In-mold Electronics
- Lighting
- Others (Printed Batteries, Luminous Foils, etc.)
Based on Industry Vertical
-
- Automotive & Transportation
- Consumer Electronics
- Healthcare
- Aerospace & Defense
- Industrial
- Others (Building & Construction, Food & Beverage, etc.)
Based on the Geography:
-
- North America
- U.S
- Canada
- Mexico
- Europe
- Germany
- France
- UK
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- The Rest of the Middle East and Africa
- North America
Regional Analysis
Asia-Pacific
Asia-Pacific leads the global printed electronics market, commanding a significant 40% market share. This dominance is primarily driven by countries such as Japan, South Korea, and China, which have established themselves as major hubs for electronics manufacturing and innovation. The region's market is characterized by high investments in research and development, a strong presence of key industry players, and supportive government initiatives promoting advanced manufacturing technologies. Asia-Pacific's robust consumer electronics industry, coupled with the rapid adoption of Internet of Things (IoT) devices, has been a key driver for the growth of printed electronics. The region has seen widespread application of printed electronics in sectors such as automotive, healthcare, and smart packaging. Furthermore, the increasing focus on flexible and wearable electronics has opened new avenues for printed electronics applications, particularly in countries like Japan and South Korea. As Asia-Pacific continues to lead in technological advancements and manufacturing capabilities, its market share in the printed electronics sector is expected to grow further.
North America
North America holds the second-largest share in the global printed electronics market at approximately 30%, driven primarily by the United States. The region's market is characterized by a strong emphasis on innovation and a well-established ecosystem of research institutions, startups, and large corporations working on cutting-edge printed electronics technologies. North America leads in the development of advanced materials and printing techniques for electronics, with a particular focus on applications in aerospace, defense, and healthcare sectors. The region has seen significant adoption of printed electronics in smart packaging, RFID tags, and energy harvesting devices. Additionally, the growing trend towards sustainable manufacturing has boosted interest in printed electronics as a more environmentally friendly alternative to traditional electronics manufacturing processes. The presence of major technology companies and a culture of entrepreneurship have fostered numerous startups specializing in printed electronics, contributing to the region's competitive edge. As North America continues to invest in emerging technologies and push the boundaries of printed electronics applications, its market share is expected to remain strong, potentially narrowing the gap with Asia-Pacific in the coming years.
Key Player Analysis
- Samsung Electronics Co., Ltd. (South Korea),
- LG Display Co., Ltd. (South Korea),
- Molex, LLC (US),
- Agfa-Gevaert Group (Belgium),
- Palo Alto Research Center Incorporated (PARC) (US),
- DuPont de Nemours, Inc. (US),
- Nissha Co., Ltd. (Japan),
- BASF (Germany),
- NovaCentrix (US), and
- E Ink Holdings Inc. (Taiwan)
Competitive Analysis
In the printed electronics market, key players like Samsung Electronics Co., Ltd. and LG Display Co., Ltd. are leveraging their technological prowess to lead advancements in flexible displays and wearable electronics. Molex, LLC and DuPont de Nemours, Inc. are at the forefront of developing conductive inks and advanced substrates, pushing the boundaries of printed electronics applications. Agfa-Gevaert Group and Nissha Co., Ltd. focus on enhancing printing techniques and material properties, contributing to higher performance and efficiency. BASF excels in developing innovative materials and solutions for various applications, while NovaCentrix is notable for its expertise in nano-ink technologies. E Ink Holdings Inc. is a leader in electronic paper displays, driving innovations in low-power, flexible screens. The competition is intense, with each player investing in R&D to gain a technological edge and expand their market share.
Market Concentration & Characteristics
The printed electronics market exhibits a moderate level of concentration with several leading players dominating key segments. Companies such as Samsung Electronics and LG Display, along with specialized firms like DuPont and BASF, significantly influence market dynamics through their advanced technology and substantial R&D investments. The market is characterized by rapid technological advancements, driven by innovations in printing techniques and materials, which are crucial for enhancing performance and broadening applications. This competitive landscape is further shaped by the ongoing development of new materials, such as conductive and semiconductive inks, and improvements in printing methods like inkjet and flexography. Despite the presence of dominant players, the market remains dynamic with emerging companies introducing novel solutions and expanding applications across diverse industries. As a result, the market is both competitive and evolving, with a strong focus on innovation and adaptation to new technological trends.
Report Coverage
The research report offers an in-depth analysis based on Technology, Material, Application, Industry Vertical and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Increased Integration with IoT: Printed electronics will play a crucial role in the expanding Internet of Things ecosystem, facilitating more integrated and compact sensor and communication devices.
- Growth in Wearable Technology: The demand for flexible and lightweight wearable electronics will drive innovations in printed electronics, enabling more comfortable and advanced health and fitness monitors.
- Advancements in Printing Techniques: Emerging printing technologies, such as nano printing and additive manufacturing, will enhance the capabilities and precision of printed electronics.
- Sustainability Focus: The industry will emphasize eco-friendly materials and processes, aiming to reduce environmental impact through recyclable and biodegradable components.
- Enhanced Performance: Ongoing research will improve the performance of printed electronics, including higher conductivity and greater durability, making them suitable for more demanding applications.
- Customization and On-Demand Production: The market will see a shift towards more customizable and on-demand manufacturing solutions, catering to specific needs and reducing lead times.
- Expanding Applications: New applications in fields like healthcare, automotive, and smart packaging will drive growth and innovation in printed electronics.
- Integration with AI and ML: Printed electronics will increasingly leverage artificial intelligence and machine learning for data analysis, predictive maintenance, and enhanced functionality.
- Regional Manufacturing Hubs: Emerging regional manufacturing hubs will reduce transportation costs and support faster product development cycles.
- Collaboration and Open-Source Designs: Greater collaboration and the adoption of open-source designs will accelerate innovation and facilitate broader adoption of printed electronics technologies.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Rise of Internet of Things (IoT)
The rapid expansion of the IoT ecosystem is fueling demand for flexible, lightweight, and energy-efficient electronic components that can be seamlessly integrated into a wide variety of connected devices, making printed electronics an ideal solution for smart sensors and wearables.
Demand for Flexible and Wearable Electronics
The growing popularity of wearable technology, such as smartwatches and fitness trackers, is driving the need for thin, flexible, and comfortable electronic components, which printed electronics can provide, supporting innovation and adoption in consumer and healthcare sectors.
Advancements in Printing Technologies
Innovations in inkjet and roll-to-roll printing have significantly reduced production time and costs, while enabling higher resolution and scalability, making printed electronics more viable for mass production and a broader range of applications.
Significant Cost Advantages
Printed electronics offer up to 60% cost reduction compared to traditional silicon-based electronics, thanks to high-throughput processes and simpler materials, making them attractive for cost-sensitive and high-volume applications.
Sustainability and Eco-Friendly Materials
The push for sustainable manufacturing is accelerating the adoption of recyclable substrates and eco-friendly inks in printed electronics, reducing environmental impact and aligning with global regulatory and consumer trends.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Printed Electronics Market?
What factors are driving the growth of the Printed Electronics Market?
What are the key segments within the Printed Electronics Market?
What are some challenges faced by the Printed Electronics Market?
Who are the major players in the Printed Electronics Market?
Which segment is leading the market share?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Material
- 1.2.1 Organic Substrates (Polymers, Papers, Fabrics)
- 1.2.2 Inorganic Substrates (Silicon, Glass, Metals)
- 1.2.3 Conductive Inks
- 1.2.4 Dielectric Inks
- 1.2.5 Semiconductive Inks
- 1.3 By Technology
- 1.3.1 Flexography
- 1.3.2 Inkjet Printing
- 1.3.3 Screen Printing
- 1.3.4 Offset Printing
- 1.3.5 Others (Gravure Printing, Aerosol Jet Printing, etc.)
- 1.4 By Application
- 1.4.1 Sensors & Switches
- 1.4.2 Displays
- 1.4.3 Medical Wearables
- 1.4.4 Photovoltaic Cells
- 1.4.5 Antennas
- 1.4.6 Heaters
- 1.4.7 In-mold Electronics
- 1.4.8 Lighting
- 1.4.9 Others (Printed Batteries, Luminous Foils, etc.)
- 1.5 By Industry Vertical
- 1.5.1 Automotive & Transportation
- 1.5.2 Consumer Electronics
- 1.5.3 Healthcare
- 1.5.4 Aerospace & Defense
- 1.5.5 Industrial
- 1.5.6 Others (Building & Construction, Food & Beverage, etc.)
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 15,069.6 million → 2032: USD 63,088.64 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Printed Electronics Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Printed Electronics Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Printed Electronics Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Printed Electronics Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Printed Electronics Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Printed Electronics Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Data Protection, AI and Cybersecurity Compliance
- 9.8 Upcoming Policy Changes and Market Implications
Chapter 10 Global Printed Electronics Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Printed Electronics Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 15,069.6 million → 2032: USD 63,088.64 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Printed Electronics Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Material - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Organic Substrates (Polymers, Papers, Fabrics)
- 12.3.7.2 Inorganic Substrates (Silicon, Glass, Metals)
- 12.3.7.3 Conductive Inks
- 12.3.7.4 Dielectric Inks
- 12.3.7.5 Semiconductive Inks
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Technology - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Flexography
- 12.4.7.2 Inkjet Printing
- 12.4.7.3 Screen Printing
- 12.4.7.4 Offset Printing
- 12.4.7.5 Others (Gravure Printing, Aerosol Jet Printing, etc.)
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Application - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Sensors & Switches
- 12.5.7.2 Displays
- 12.5.7.3 Medical Wearables
- 12.5.7.4 Photovoltaic Cells
- 12.5.7.5 Antennas
- 12.5.7.6 Heaters
- 12.5.7.7 In-mold Electronics
- 12.5.7.8 Lighting
- 12.5.7.9 Others (Printed Batteries, Luminous Foils, etc.)
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 By Industry Vertical - Market Size and Forecast, 2024-2032
- 12.6.1 Segment Definition and Scope
- 12.6.2 Historical Market Size
- 12.6.3 Revenue Forecast, 2024-2032
- 12.6.4 Volume Forecast, 2024-2032
- 12.6.5 Base-Year Market Share, 2024
- 12.6.6 Segment CAGR and Growth Drivers
- 12.6.7 Subsegment Market Size and Forecast
- 12.6.7.1 Automotive & Transportation
- 12.6.7.2 Consumer Electronics
- 12.6.7.3 Healthcare
- 12.6.7.4 Aerospace & Defense
- 12.6.7.5 Industrial
- 12.6.7.6 Others (Building & Construction, Food & Beverage, etc.)
- 12.6.8 Subsegment Pricing and Adoption Trends
- 12.6.9 Leading Suppliers and Competition
- 12.6.10 Regional Demand and Opportunities
- 12.7 Segment Growth Comparison
- 12.8 Segment Attractiveness and Priority Matrix
Chapter 13 Global Printed Electronics End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Printed Electronics Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Printed Electronics Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Printed Electronics Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Samsung Electronics Co., Ltd.
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 LG Display Co., Ltd.
- 18.4 Molex, LLC
- 18.5 Agfa-Gevaert Group
- 18.6 DuPont de Nemours, Inc.
- 18.7 Nissha Co., Ltd.
- 18.8 BASF
- 18.9 NovaCentrix
- 18.10 E Ink Holdings Inc.
- 18.11 Palo Alto Research Center Incorporated (PARC)
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

