
Market Overview
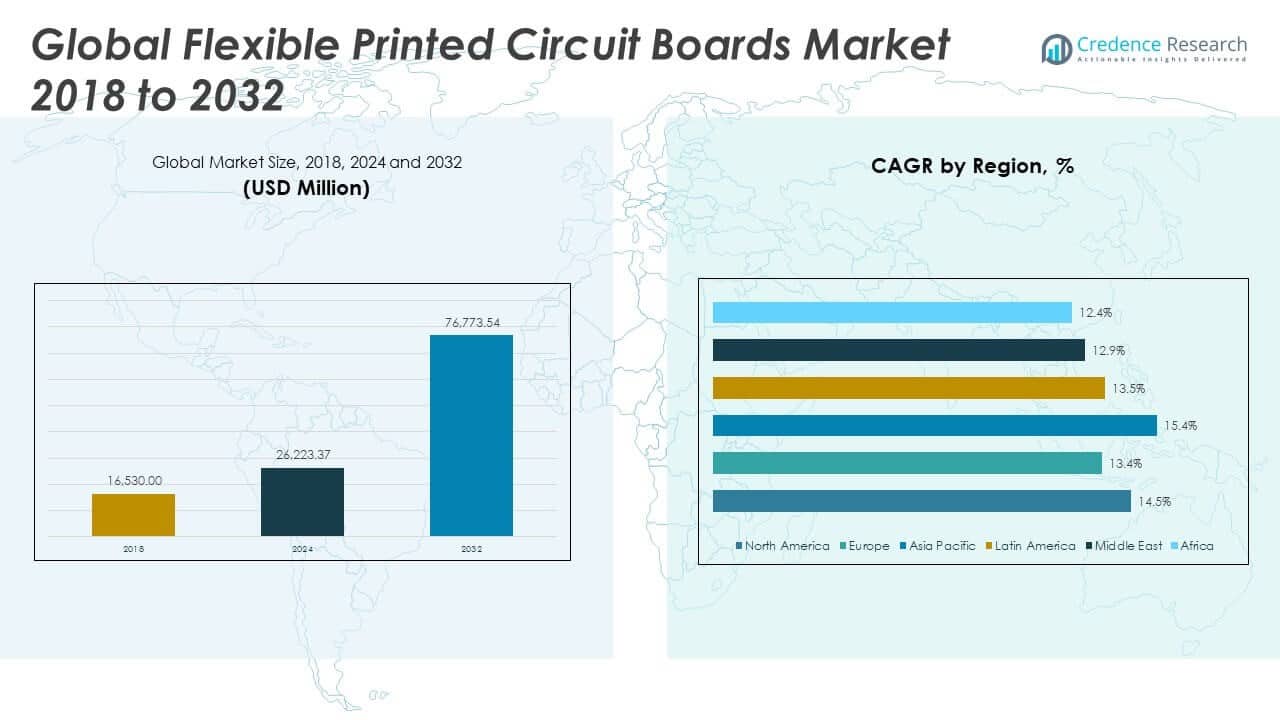
The Flexible Printed Circuit Boards Market size was valued at USD 16,530.00 million in 2018 to USD 26,223.37 million in 2024 and is anticipated to reach USD 76,773.54 million by 2032, at a CAGR of 14.45% during the forecast period.| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2024 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Flexible Printed Circuit Boards Market Size 2024 | USD 26,223.37 Million |
| Flexible Printed Circuit Boards Market, CAGR | 14.45% |
| Flexible Printed Circuit Boards Market Size 2032 | USD 76,773.54 Million |
Market Insights:
- Flexible PCBs accounted for a market size of USD 26,223.37 million in 2024 and play a critical role in enabling innovation across foldable, lightweight, and compact electronic devices.
- The Asia Pacific region leads global demand, supported by large-scale consumer electronics manufacturing hubs in China, Japan, and South Korea.
- Automotive and medical device sectors continue to emerge as high-growth verticals for flexible PCB integration.
- Government-backed semiconductor and electronics initiatives in countries such as India and the U.S. are driving regional production capabilities.
- Ongoing innovations in flexible PCB materials enhance heat dissipation, signal integrity, and circuit durability.
- Complex multilayer manufacturing processes pose challenges for quality control and require significant technical expertise.
- Customization capabilities and cost-efficient mass production are increasingly important for maintaining market competitiveness.
Market Drivers
Growing Demand for Miniaturized Electronics Flexible Printed Circuit Boards Market is experiencing accelerated growth due to the rising demand for compact and lightweight electronic devices. As the electronics industry pushes toward device miniaturization, flexible PCBs offer an ideal solution by enabling complex circuitry within limited space. Devices such as smartphones, tablets, wearables, and medical implants require intricate circuits that traditional rigid boards cannot support. Flexible PCBs allow for dynamic bending and folding, which enhances design freedom and reduces assembly complexity. This capability is essential in producing multifunctional devices with high portability and durability. Moreover, the reduction in weight and volume directly contributes to user convenience, particularly in portable medical and consumer electronics. OEMs across sectors are incorporating flexible PCBs to align with this miniaturization trend.- For example, according to All Flex’s technical documentation, manufacturers now routinely achieve substrate thicknesses as low as 25μm, enabling FPCBs to fit within the thinnest wearable and implantable devices.
- For instance, Liquid crystal polymer (LCP)-based FPCBs used in 5G IoT modules are documented with dielectric constants of 3.0–3.5 and moisture absorption rates below 0.04%
Market Trends
Integration with Advanced Materials Flexible Printed Circuit Boards Market is seeing a trend toward integration with advanced materials to enhance performance. Manufacturers are experimenting with polyimide, liquid crystal polymers, and other heat-resistant substrates. These materials offer better thermal stability, flexibility, and signal integrity. By improving dielectric properties and reducing losses, they cater to high-frequency applications. Emerging materials also support thinner form factors without compromising strength. The shift toward eco-friendly and recyclable materials is aligning with sustainability goals. These developments are creating new application areas across medical and aerospace industries. Material innovation is becoming a key differentiator in the competitive landscape.- For example, Rogers Corporation’s ULTRALAM® 3850 liquid crystal polymer (LCP) flex circuits are documented to deliver dielectric constants (ϵᵣ) as low as 2.9 with loss tangents of 0.0025 at 10 GHz, directly supporting millimeter-wave 5G and satellite communication modules.
- For example, in 2024, Samsung Display introduced ultra-thin glass (~30 μm) and multi-layer flexible PCBs qualified for bend radii below 1.5 mm. These components were tested to withstand over 200,000 mechanical fold cycles without electrical failure. TÜV Rheinland independently verified the results, confirming durability for use in Galaxy Z Fold and upcoming G Fold devices.
Market Challenges Analysis
Complex Manufacturing Processes and Quality Control Flexible Printed Circuit Boards Market faces challenges due to intricate manufacturing processes. Producing flexible circuits requires precision engineering and specialized materials, which raise production costs. Any deviation in etching, lamination, or drilling can compromise product quality. Maintaining dimensional stability and adhesion in multilayer boards adds complexity. Manufacturers also struggle with limited yield rates due to high rejection during inspection. Ensuring reliability and durability in bend-intensive applications remains a critical concern. Material Costs and Supply Chain Disruptions Flexible Printed Circuit Boards Market encounters limitations from volatile raw material prices and supply chain issues. High-performance base materials such as polyimide films and advanced adhesives carry significant cost. Shortages or delays in sourcing can impact production timelines and profitability. Geopolitical tensions and trade restrictions often disrupt electronics component flow. Manufacturers face pressure to maintain price competitiveness while absorbing rising input costs. These material and logistics concerns restrain market scalability and pose risks for global players.Market Segmentation Analysis
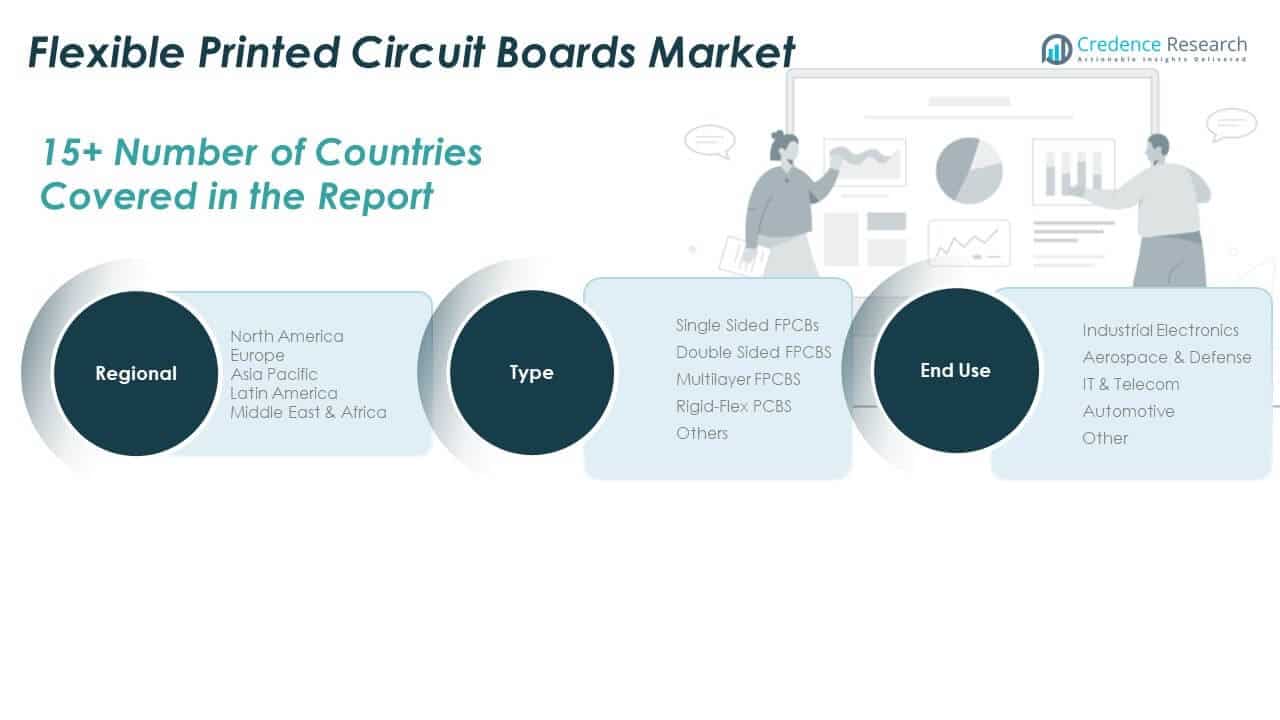
By Type: Flexible Printed Circuit Boards Market comprises various product types tailored to different applications and mechanical needs. Single sided FPCBs are widely used in simple electronic devices where one conductive layer suffices. Double sided FPCBs provide higher circuit density and are common in more complex consumer electronics. Multilayer FPCBs cater to advanced applications like medical imaging and avionics by enabling intricate routing. Rigid-Flex PCBs combine the benefits of both flexible and rigid boards and are popular in aerospace and automotive sectors. Other niche types are also gaining relevance based on specific design and cost requirements.- For example, Fujikura’s technical datasheets document single-sided flex circuits as thin as 25 microns, used in automotive dashboard switches and simple LED lighting strips.
- For example, TTM Technologies delivers mission-critical multi-layer and rigid-flex PCBs for aerospace systems covering radar, C4ISR, and space applications designed for high reliability in harsh environments (shock, vibration, weight-sensitive).
Segmentation:
By Type:- Single Sided FPCBs
- Double Sided FPCBs
- Multilayer FPCBs
- Rigid-Flex PCBs
- Others
- Industrial Electronics
- Aerospace & Defense
- IT & Telecom
- Automotive
- Others
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis:
The North America Flexible Printed Circuit Boards Market size was valued at USD 4380.45 million in 2018 to USD 6833.65 million in 2024 and is anticipated to reach USD 19968.94 million by 2032, at a CAGR of 14.5% during the forecast period. North America is experiencing steady demand due to the presence of major electronics and automotive manufacturers. The region's growth is supported by robust investments in communication infrastructure, wearable technology, and defense electronics. Increasing adoption of flexible electronics across industrial and healthcare applications is enhancing market prospects. Government initiatives and R&D support are also fueling domestic production and innovation in this market. The Europe Flexible Printed Circuit Boards Market size was valued at USD 3520.89 million in 2018 to USD 5317.38 million in 2024 and is anticipated to reach USD 14491.21 million by 2032, at a CAGR of 13.4% during the forecast period. Europe is experiencing steady demand due to the presence of major electronics and automotive manufacturers. The region's growth is supported by robust investments in communication infrastructure, wearable technology, and defense electronics. Increasing adoption of flexible electronics across industrial and healthcare applications is enhancing market prospects. Government initiatives and R&D support are also fueling domestic production and innovation in this market. The Asia Pacific Flexible Printed Circuit Boards Market size was valued at USD 6364.05 million in 2018 to USD 10380.41 million in 2024 and is anticipated to reach USD 32421.53 million by 2032, at a CAGR of 15.4% during the forecast period. Asia Pacific is experiencing steady demand due to the presence of major electronics and automotive manufacturers. The region's growth is supported by robust investments in communication infrastructure, wearable technology, and defense electronics. Increasing adoption of flexible electronics across industrial and healthcare applications is enhancing market prospects. Government initiatives and R&D support are also fueling domestic production and innovation in this market. The Latin America Flexible Printed Circuit Boards Market size was valued at USD 1206.69 million in 2018 to USD 1898.31 million in 2024 and is anticipated to reach USD 5210.62 million by 2032, at a CAGR of 13.5% during the forecast period. Latin America is experiencing steady demand due to the presence of major electronics and automotive manufacturers. The region's growth is supported by robust investments in communication infrastructure, wearable technology, and defense electronics. Increasing adoption of flexible electronics across industrial and healthcare applications is enhancing market prospects. Government initiatives and R&D support are also fueling domestic production and innovation in this market. The Middle East Flexible Printed Circuit Boards Market size was valued at USD 578.55 million in 2018 to USD 854.71 million in 2024 and is anticipated to reach USD 2234.53 million by 2032, at a CAGR of 12.9% during the forecast period. Middle East is experiencing steady demand due to the presence of major electronics and automotive manufacturers. The region's growth is supported by robust investments in communication infrastructure, wearable technology, and defense electronics. Increasing adoption of flexible electronics across industrial and healthcare applications is enhancing market prospects. Government initiatives and R&D support are also fueling domestic production and innovation in this market. The Africa Flexible Printed Circuit Boards Market size was valued at USD 479.37 million in 2018 to USD 938.9 million in 2024 and is anticipated to reach USD 2446.72 million by 2032, at a CAGR of 12.4% during the forecast period. Africa is experiencing steady demand due to the presence of major electronics and automotive manufacturers. The region's growth is supported by robust investments in communication infrastructure, wearable technology, and defense electronics. Increasing adoption of flexible electronics across industrial and healthcare applications is enhancing market prospects. Government initiatives and R&D support are also fueling domestic production and innovation in this market.Key Player Analysis:
- AT&S
- Benchmark Electronics
- Cicor Management AG
- Eltek Ltd.
- Jabil Inc.
- Sumitomo Electric Industries, Ltd.
- TTM Technologies
- SigmaTron International, Inc.
- SMTC Corp
- Flex Ltd
- IEC Electronics
Competitive Analysis:
Flexible Printed Circuit Boards Market exhibits a moderately consolidated structure with several key players dominating global production and innovation. Companies like Jabil Inc., AT&S, and TTM Technologies lead through technological advancements, strategic acquisitions, and expansive manufacturing capabilities. Competitive strategies include expanding into emerging markets, enhancing fabrication technologies, and forming partnerships with OEMs. Mid-tier players are focusing on niche applications and customized solutions to differentiate themselves. Product innovation and cost optimization remain central to gaining market share. Vendors are also investing in vertical integration and automation to improve operational efficiency. Intellectual property, reliability, and high-frequency performance are emerging as key parameters in competitive positioning. As customer expectations evolve, companies must maintain agility and invest consistently in R&D to retain their market standing.Recent Developments:
- In July 2025, AT&S officially opened its new R&D and IC Substrate Production Competence Center in Leoben, Austria. This facility marks a significant step in advancing research and development around flexible substrates for high-end electronics, enhancing innovation in the microelectronics and PCB markets
- In April 2025, Cicor Management AG made strategic moves to strengthen its European and global defense sector presence. The company entered a five-year supply partnership with Mercury, aimed at transferring electronics manufacturing operations to Cicor for increased efficiency.
- In Aug 2024, Eltek Ltd. secured $3.5 million in orders from two defense sector clients, extending from Q4 2024 to 2026 for high-technology printed circuit boards, particularly supporting their focus in flexible and rigid-flex PCBs for aerospace and defense applications.
Market Concentration & Characteristics:
Flexible Printed Circuit Boards Market displays a moderately concentrated landscape characterized by high technological innovation and R&D intensity. Market leaders hold significant shares through vertically integrated operations and global manufacturing footprints. The industry is marked by substantial entry barriers due to complex production processes and the need for precision engineering. Continuous advancements in substrate materials and multilayer fabrication contribute to rapid innovation cycles. Customization, miniaturization, and quality control remain critical competitive factors. While major players dominate high-volume production, niche players are gaining ground through application-specific solutions and agile supply chains.Future Outlook:
- Demand for flexible PCBs in wearables and medical devices will continue to surge, driven by miniaturization needs and growing adoption of smart health monitoring systems like glucose trackers and implantables.
- Emerging regions like Southeast Asia and Latin America will register high growth rates, supported by the expansion of electronics manufacturing hubs, low-cost labor, and government-led industrial incentives.
- Foldable and curved electronics will drive design innovation across applications, requiring ultra-thin, durable flex circuits for use in next-gen smartphones, tablets, and display panels.
- Automotive sector adoption will expand due to rising EV and ADAS integration, with flexible PCBs supporting critical systems like battery management, in-cabin electronics, and sensor arrays.
- Material science breakthroughs will enhance thermal performance and durability, particularly with LCPs and advanced polyimide films enabling better heat resistance and signal integrity.
- OEMs will shift toward domestic sourcing to mitigate supply chain risks, promoting regional self-reliance and faster turnaround times amid global uncertainties.
- Government incentives will boost local PCB manufacturing in key markets, through subsidies, tax benefits, and investments in advanced fabrication facilities.
- Strategic partnerships will increase to co-develop specialized flex circuits, allowing faster innovation cycles and tailored solutions for niche applications.
- Flexible PCBs will play a central role in next-gen IoT ecosystems, powering connected devices across smart homes, industrial automation, and wearable tech.
Report Coverage:
The research report offers an in-depth analysis based on Type and End Use. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.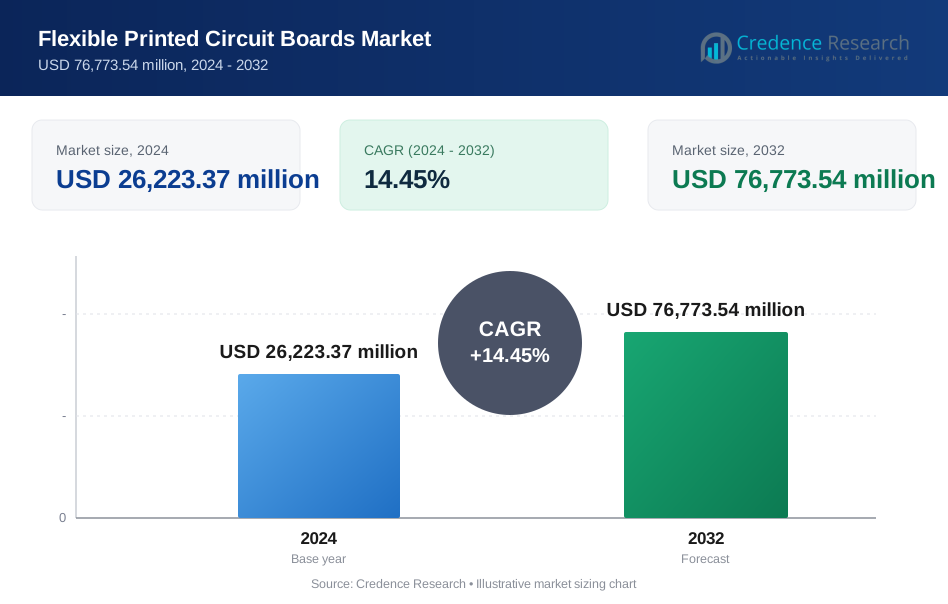
Report Attribute Details
Details
Historical Period
-
Base Year
2024
Forecast Period
2024–2032
Flexible Printed Circuit Boards Size 2024
USD 26,223.37 million
Flexible Printed Circuit Boards CAGR
14.45%
Flexible Printed Circuit Boards Size 2032
USD 76,773.54 million
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Flexible Printed Circuit Boards Market Market?
The Flexible Printed Circuit Boards Market size was valued at USD 26,223.37 million in 2024.
What factors are driving the growth of the Flexible Printed Circuit Boards Market Market?
Rising demand for miniaturized electronics, IoT devices, automotive electronics, and flexible displays are key drivers.
What are the key segments within the Flexible Printed Circuit Boards Market Market?
The market is segmented by Type (Single Sided, Double Sided, Multilayer, Rigid-Flex, Others) and End Use (Industrial Electronics, Aerospace & Defense, IT & Telecom, Automotive, Others).
What are some challenges faced by the Flexible Printed Circuit Boards Market Market?
Complex manufacturing processes, material costs, and supply chain disruptions are major challenges.
Who are the major players in the Flexible Printed Circuit Boards Market Market?
Key players include Jabil Inc., TTM Technologies, AT&S, Benchmark Electronics, and Sumitomo Electric Industries.
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 26,223.37 million → 2032: USD 76,773.54 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Flexible Printed Circuit Boards Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Flexible Printed Circuit Boards Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Flexible Printed Circuit Boards Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Flexible Printed Circuit Boards Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Flexible Printed Circuit Boards Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Flexible Printed Circuit Boards Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Flexible Printed Circuit Boards Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Flexible Printed Circuit Boards Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 26,223.37 million → 2032: USD 76,773.54 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Flexible Printed Circuit Boards Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 Segment Growth Comparison
- 12.4 Segment Attractiveness and Priority Matrix
Chapter 13 Global Flexible Printed Circuit Boards Geographic Market Outlook, 2024-2032
- 13.1 Regional Market Size and Share, 2024
- 13.2 Regional Market Forecast, 2024-2032
- 13.3 Regional Pricing, Production and Demand Differences
- 13.4 North America
- 13.4.1 United States
- 13.4.2 Canada
- 13.4.3 Mexico
- 13.5 Europe
- 13.5.1 Germany
- 13.5.2 France
- 13.5.3 Italy
- 13.5.4 United Kingdom
- 13.5.5 Spain
- 13.5.6 Poland
- 13.5.7 Russia
- 13.5.8 Netherlands
- 13.5.9 Belgium
- 13.5.10 Sweden
- 13.5.11 Denmark
- 13.5.12 Norway
- 13.5.13 Rest of Europe
- 13.6 Asia Pacific
- 13.6.1 China
- 13.6.2 India
- 13.6.3 Japan
- 13.6.4 South Korea
- 13.6.5 Thailand
- 13.6.6 Indonesia
- 13.6.7 Vietnam
- 13.6.8 Malaysia
- 13.6.9 Australia
- 13.6.10 Rest of Asia Pacific
- 13.7 Latin America
- 13.7.1 Brazil
- 13.7.2 Argentina
- 13.7.3 Colombia
- 13.7.4 Chile
- 13.7.5 Rest of Latin America
- 13.8 Middle East
- 13.8.1 Saudi Arabia
- 13.8.2 United Arab Emirates
- 13.8.3 Turkey
- 13.8.4 Israel
- 13.8.5 Iran
- 13.8.6 Rest of the Middle East
- 13.9 Africa
- 13.9.1 South Africa
- 13.9.2 Egypt
- 13.9.3 Nigeria
- 13.9.4 Morocco
- 13.9.5 Rest of Africa
- 13.10 Regional Investment, Policy and Supply Chain Differences
- 13.11 Regional Competitive Landscape
- 13.12 Geographic Growth Hotspots
Chapter 14 Global Flexible Printed Circuit Boards Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2024-2032
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 Global Flexible Printed Circuit Boards Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2024
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2024-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Leading Market Participants – Standard Profile Structure
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.
