
Quick Service Restaurant Market Overview:
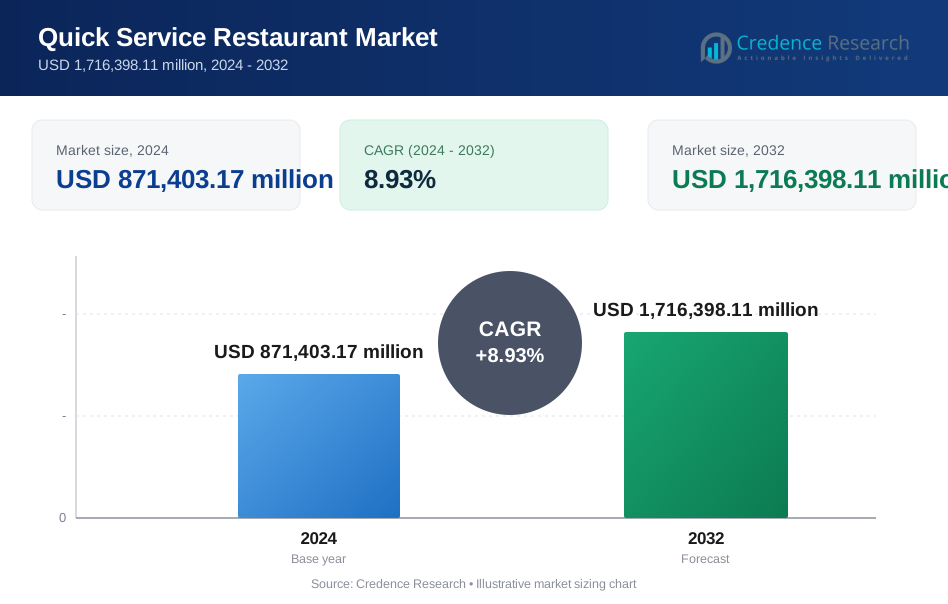
The Quick Service Restaurant market size was valued at USD 637,800.00 million in 2018, increased to USD 871,403.17 million in 2024, and is anticipated to reach USD 1,716,398.11 million by 2032, at a CAGR of 8.93% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Quick Service Restaurant Market Size 2024 | USD 871,403.17 million |
| Quick Service Restaurant Market, CAGR | 8.93% |
| Quick Service Restaurant Market Size 2032 | USD 1,716,398.11 million |
The Quick Service Restaurant (QSR) market is led by global giants such as McDonald’s Corporation, Yum! Brands, Inc., Starbucks Corporation, Restaurant Brands International Inc., and Domino’s Pizza, Inc. These companies leverage expansive franchise models, high brand equity, and continuous menu innovation to maintain dominance. North America holds a 32.4% market share in 2024, driven by strong consumer demand, digital integration, and a mature franchise ecosystem. Asia Pacific follows as the fastest-growing region with a 35.9% market share, supported by rising urbanization, income growth, and western food adoption. Leading players invest in digital platforms, plant-based offerings, and strategic global expansion to sustain growth and competitive advantage across regions.

Quick Service Restaurant Market Insights
- The Quick Service Restaurant market was valued at USD 637,800.00 million in 2018 and is projected to reach USD 1,716,398.11 million by 2032, growing at a CAGR of 8.93%.
- Rising demand for convenience, time-saving meals, and digital ordering platforms are fueling market growth, especially among urban working populations.
- Key trends include menu innovation with health-conscious and plant-based options, alongside widespread adoption of mobile ordering and loyalty apps.
- The market is dominated by major players such as McDonald’s, Starbucks, Yum! Brands, Domino’s, and Restaurant Brands International, which leverage strong brand equity and global franchise networks.
- Asia Pacific leads with a 35.9% share in 2024, driven by rapid urbanization and rising disposable incomes, followed by North America at 32.4%; the delivery segment dominates by service type, while American cuisine holds the highest share among cuisine types.
Quick Service Restaurant Market Segmentation Analysis:
By Service Type
The delivery segment dominates the Quick Service Restaurant (QSR) market, accounting for over 42% of the revenue share in 2024. Strong demand for convenience, rising smartphone penetration, and the expansion of third-party delivery platforms such as DoorDash and Uber Eats drive growth. Consumers prefer app-based ordering and flexible delivery windows, especially in urban areas. Takeaway follows closely, favored by time-conscious customers and office workers. Dine-in holds a smaller share due to shifting preferences toward digital and off-premise channels, though it remains relevant for social and family dining experiences.
- For instance, DoorDash reported over 20 million monthly active consumers in 2024, while Uber Eats operates in more than 11,000 cities, enabling average delivery times under 30 minutes in dense metros.
By Cuisine Type
American cuisine leads the QSR market with over 38% market share, supported by the global popularity of burgers, fries, and fried chicken. Iconic chains like McDonald's, Burger King, and KFC maintain brand loyalty and high footfall. Fast-food branding, affordable menus, and consistent offerings boost American cuisine's dominance. Asian cuisine is the fastest-growing segment, driven by urban multicultural preferences and rising demand for noodles, sushi, and rice-based dishes. Italian cuisine holds a moderate share, led by pizza and pasta outlets, while “Others” includes fusion, Mexican, and local options gaining traction regionally.
- For instance, McDonald's operates over 40,000 restaurants worldwide and serves about 69 million customers daily, while KFC runs more than 27,000 outlets, supporting high throughput during peak meal hours.
By Restaurant Type
Chained restaurants hold a commanding share of over 70% in the global QSR market. Standardized menus, brand trust, promotional campaigns, and digital infrastructure drive their market lead. Global and regional chains scale operations through franchising and adapt offerings to local tastes. Their ability to invest in tech-enabled ordering, loyalty apps, and delivery partnerships strengthens their position. Independent QSRs hold a smaller share but cater to niche demands and regional cuisines. They attract loyal customers through personalized services and differentiated menus, though limited scalability and marketing budgets cap their growth compared to large chains.
Key Growth Drivers
Rising Urbanization and Time-Constrained Lifestyles
Urbanization and changing work patterns continue to drive demand for quick, affordable meals. Urban dwellers, especially young professionals, increasingly rely on fast food due to packed schedules and long commuting times. Quick Service Restaurants fulfill this need by offering efficient ordering systems, short wait times, and consistent product availability. Growing dual-income households and nuclear families further support dine-out frequency. QSR formats are increasingly favored over traditional full-service dining due to their faster turnaround and lower cost. The expanding base of urban consumers across developing regions ensures recurring demand. Combined with a growing appetite for global food brands, this trend solidifies QSRs as the go-to option for modern, time-starved consumers.
- For instance, McDonald's reports average in-store service times of approximately 3 minutes and 49 seconds, while digital kiosks can reduce the ordering phase to roughly 90 to 120 seconds, significantly cutting total wait times during peak hours compared to traditional counter service.
Digital Transformation and Delivery Ecosystem Expansion
The digitization of food service is a key growth lever for the QSR market. Operators leverage mobile apps, AI chatbots, and online ordering systems to enhance customer experience and operational efficiency. Food aggregators like Uber Eats, DoorDash, and Zomato expand customer reach and streamline last-mile delivery. Contactless payment systems and personalized app-based promotions improve user convenience and loyalty. Cloud kitchens reduce capital expenditure and support delivery-focused business models. Integration of data analytics helps brands optimize menus and predict demand patterns. As digital adoption rises globally, these innovations reshape the competitive landscape, creating new revenue streams and improving service scalability.
- For instance, Zomato processed over 1.7 million orders per day in 2023, while Uber Eats supports average delivery distances of 4–6 km, enabling consistent sub-30-minute delivery in major cities.
Aggressive Franchise Growth and Global Brand Penetration
Franchising remains a critical growth engine for leading QSR brands. It allows companies to rapidly scale across domestic and international markets while minimizing operational risks. Brands like McDonald's, Subway, and Domino’s continue expanding into emerging regions via local partnerships. Franchisees benefit from standardized operating procedures, brand equity, and shared marketing strategies. This model also adapts well to local market preferences through regional customization. In developing economies, rising disposable incomes and retail expansion drive franchise interest. The growing middle class in Asia, Latin America, and Africa presents untapped potential. As a result, franchising enables global QSR players to penetrate underserved regions and secure long-term market presence.
Quick Service Restaurant Market Key Trends & Opportunities
Menu Diversification and Plant-Based Innovations
Consumer preferences are evolving toward healthier and more sustainable eating habits, creating space for menu innovation. Quick Service Restaurants now offer plant-based options, gluten-free meals, and low-calorie alternatives to attract health-conscious diners. Brands are investing in R&D to incorporate clean-label ingredients, reduce sugar and sodium, and develop meat alternatives. Plant-based burgers, oat milk beverages, and vegan sides have entered mainstream menus, especially in North America and Europe. Seasonal and localized items cater to regional tastes, increasing customer engagement. Innovation also extends to beverages, desserts, and functional foods. This trend not only broadens customer segments but also strengthens brand image among eco-conscious consumers.
- For instance, McDonald's introduced the McPlant burger using a pea-protein patty with 19 g of protein and zero cholesterol, while Starbucks serves oat milk options that add about 7 g of carbohydrates per cup and cut saturated fat versus whole milk in standard beverages.
Expansion in Emerging Markets and Tier-2 Cities
Emerging markets present vast growth opportunities for QSR operators. Rising income levels, urban migration, and a growing youth population are fueling out-of-home food consumption across Asia Pacific, Latin America, the Middle East, and Africa. Tier-2 and Tier-3 cities are becoming attractive expansion zones due to improving infrastructure and reduced market saturation. Digital literacy, mobile payments, and increased internet access support online ordering even in smaller cities. Global and local QSR brands are tapping into these areas through compact store formats, value menus, and strategic franchising. As demand in metro areas matures, these emerging zones will contribute significantly to future market expansion.

Quick Service Restaurant Market Key Challenges
Rising Input Costs and Margin Pressure
Cost inflation across supply chains poses a major challenge for QSR operators. Food ingredient prices fluctuate due to weather events, geopolitical tensions, and global trade disruptions. Labor costs continue to rise, driven by minimum wage regulations and high employee turnover. Packaging and utility expenses further burden operating budgets. Additionally, delivery platforms charge commission fees that reduce net margins on online orders. To offset costs, many operators streamline menus, reduce portion sizes, or increase prices-risking customer dissatisfaction. Sustaining profitability while maintaining value perception becomes difficult, especially for small and independent QSRs competing with global chains.
Intense Competitive Landscape and Brand Saturation
The QSR market faces intense competition from global brands, regional chains, and fast-casual hybrids. New entrants continually emerge with niche concepts or digital-first models, increasing fragmentation. Heavy promotional spending by established players sets high benchmarks for customer acquisition and retention. Price wars and discount campaigns erode profit margins. Brand loyalty remains limited in price-sensitive segments, where switching costs are low. Digital platforms list multiple competing brands, making differentiation harder. Customer expectations for quality, speed, and variety continue to rise, pushing brands to innovate constantly. For smaller operators, competing at scale without compromising service quality becomes increasingly difficult.
Quick Service Restaurant Market Regional Analysis
North America
North America held a 32.4% market share in 2024, making it the second-largest regional market. The market grew from USD 209,198.40 million in 2018 to USD 281,980.84 million in 2024 and is expected to reach USD 554,571.32 million by 2032, at a CAGR of 8.9%. Growth is driven by established chains, rising online food ordering, and heavy investments in AI-based ordering systems. The U.S. dominates with a mature consumer base and wide franchise networks, while Canada shows steady demand through urban expansion and changing lifestyles.
Europe
Europe captured a 20.4% share in 2024, driven by changing eating habits and the popularity of global QSR brands. The market was valued at USD 136,489.20 million in 2018, rising to USD 177,568.14 million in 2024 and is forecast to reach USD 325,691.11 million by 2032, growing at a CAGR of 8.0%. Growth is supported by increased health-conscious menu innovation and cross-border franchise expansion. Countries like the UK, Germany, and France are leading the region’s QSR footprint due to strong brand recognition and evolving dining culture.
Asia Pacific
Asia Pacific is the largest and fastest-growing region, with a 35.9% share in 2024. The market rose from USD 222,337.08 million in 2018 to USD 313,222.21 million in 2024 and is projected to reach USD 662,359.40 million by 2032, registering the highest CAGR of 9.9%. Rapid urbanization, a growing middle class, and strong demand for international cuisine fuel expansion. China, India, and Southeast Asia are key hotspots for both global chains and regional players. Mobile delivery, digital wallets, and aggressive franchising further strengthen regional performance.
Latin America
Latin America accounted for a 4.1% market share in 2024, with rising appetite for Western fast food formats and digital delivery services. The market expanded from USD 26,787.60 million in 2018 to USD 36,067.37 million in 2024 and is anticipated to reach USD 63,283.58 million by 2032, growing at a CAGR of 7.4%. Brazil and Mexico are the primary markets, with favorable demographics and increasing urban density. Competitive pricing and mobile ordering innovations attract younger consumers, helping to increase QSR penetration across mid-tier cities.
Middle East
The Middle East held a 2.6% market share in 2024, showing consistent growth through rising tourism and westernization of food preferences. The region’s market grew from USD 18,432.42 million in 2018 to USD 23,086.52 million in 2024 and is set to reach USD 39,486.60 million by 2032, at a CAGR of 7.1%. GCC countries, particularly the UAE and Saudi Arabia, lead in QSR adoption. Mall-centric retail growth and rising demand for international brands drive expansion. Strategic franchise partnerships and delivery models further accelerate market growth.
Africa
Africa contributed a 4.5% market share in 2024, with strong growth prospects driven by urban development and rising disposable incomes. The market increased from USD 24,555.30 million in 2018 to USD 39,478.09 million in 2024 and is expected to reach USD 71,006.10 million by 2032, growing at a CAGR of 7.5%. South Africa leads the regional market, followed by Egypt and Nigeria. Expansion is supported by growing mobile penetration, evolving food habits, and foreign investments in regional QSR chains. Low-cost menu models resonate well with mass consumers.
Quick Service Restaurant Market Segmentations:
By Service Type
- Dine-In
- Takeaway
- Delivery
By Cuisine Type
- American
- Italian
- Asian
- Others
By Restaurant Type
- Chained
- Independent
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa

Competitive Landscape
The Quick Service Restaurant (QSR) market remains highly competitive, led by global brands with extensive geographic reach, standardized operations, and strong franchise networks. Major players such as McDonald’s, Yum! Brands, Starbucks, and Restaurant Brands International dominate through brand recognition, scale efficiencies, and innovation in digital ordering and delivery systems. U.S.-based companies, including Chick-fil-A, Domino’s, and Wendy’s, maintain strong domestic and growing international footprints. Franchise-driven growth, menu innovation, and aggressive marketing strategies strengthen market positions. Regional players compete through localized offerings and faster adaptation to consumer trends. Investment in technology, sustainability, and customer experience further differentiates leaders. Mergers, acquisitions, and strategic partnerships continue to shape the competitive landscape, with companies focusing on expanding in emerging markets and Tier-2 cities. The ability to balance operational efficiency, evolving menu demands, and digital convenience will remain central to long-term competitiveness in the global QSR space.
Key Player Analysis
- Chick-fil-A
- Papa John's International, Inc.
- Subway IP LLC
- Starbucks Corporation
- Yum! Brands, Inc.
- McDonald's Corporation
- Restaurant Brands International Inc.
- The Wendy's Company
- Dunkin
- Domino's Pizza, Inc.
Recent Developments
- In October 2023, Domino's U.S. announced the Free Emergency Pizza program. The selected members of the program were entitled to a free medium pizza to consume whenever they needed it most.
- In August 2023, American sandwich chain Subway entered a definitive agreement to sell its business to the affiliates of Roark Capital. Roark Capital focuses mainly on investments in consumer business service companies, specializing in franchise and franchise-like businesses.
- In March 2023, Starbucks announced its plan to open around 100 new stores in the U.K. over the next year as part of the company’s Europe-wide investment program. Starbucks has over 1,000 stores in the U.K., with an investment of around USD 35 million. The company will also refurbish its store estate over the next three years.
Report Coverage
The research report offers an in-depth analysis based on Service Type, Cuisine Type, Restaurant Type and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The market will continue expanding as demand for quick, affordable meals rises across urban centers.
- Digital ordering and delivery services will play a larger role in customer acquisition and retention.
- Franchise expansion will increase in emerging markets and tier-two cities worldwide.
- Plant-based and health-conscious menu items will gain more prominence across major QSR brands.
- Data analytics and AI will drive personalized marketing and operational efficiency improvements.
- Drive-thru and self-service kiosks will see higher adoption for faster customer service.
- Cloud kitchens will support delivery-only models, reducing overhead costs for operators.
- Mobile payment integration and loyalty apps will enhance customer engagement and repeat visits.
- Global chains will invest more in sustainability practices and eco-friendly packaging.
- Competitive pressure will intensify, pushing regional players to differentiate through local flavors and niche offerings.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Urbanization and Time-Constrained Lifestyles
Increasing urban populations and busy work schedules are driving demand for quick, affordable meals, making QSRs the preferred choice for urban dwellers and young professionals seeking convenience and speed.
Digital Transformation and Delivery Ecosystem Expansion
The widespread adoption of mobile apps, online ordering, and third-party delivery platforms has expanded customer reach and improved operational efficiency, fueling growth in both established and emerging markets.
Aggressive Franchise Growth and Global Brand Penetration
Franchise models enable rapid expansion into new regions, allowing global QSR brands to scale efficiently, adapt to local tastes, and penetrate underserved markets, especially in developing economies.
Menu Innovation and Health-Conscious Offerings
QSRs are diversifying menus with plant-based, gluten-free, and low-calorie options to attract health-conscious consumers, broadening their customer base and enhancing brand image.
Expansion in Emerging Markets and Tier-2 Cities
Rising disposable incomes, urban migration, and digital literacy in emerging markets and smaller cities are creating new growth opportunities for QSR operators, supported by compact store formats and value-driven menus.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for the Quick Service Restaurant market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Quick Service Restaurant market projected to grow between 2024 and 2032?
Which Quick Service Restaurant market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Quick Service Restaurant market?
Who are the leading companies in the Quick Service Restaurant market?
Which region commanded the largest share of the Quick Service Restaurant market in 2024?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Cuisine Type
- 1.2.1 American
- 1.2.2 Italian
- 1.2.3 Asian
- 1.2.4 Others
- 1.3 By Service Type
- 1.3.1 Dine-In
- 1.3.2 Takeaway
- 1.3.3 Delivery
- 1.4 By Restaurant Type
- 1.4.1 Chained
- 1.4.2 Independent
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 871,403.17 million → 2032: USD 1,716,398.11 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Quick Service Restaurant Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Quick Service Restaurant Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Quick Service Restaurant Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Quick Service Restaurant Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Quick Service Restaurant Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Quick Service Restaurant Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Data Protection, AI and Cybersecurity Compliance
- 9.8 Upcoming Policy Changes and Market Implications
Chapter 10 Global Quick Service Restaurant Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Quick Service Restaurant Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 871,403.17 million → 2032: USD 1,716,398.11 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Quick Service Restaurant Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Cuisine Type - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 American
- 12.3.7.2 Italian
- 12.3.7.3 Asian
- 12.3.7.4 Others
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Service Type - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Dine-In
- 12.4.7.2 Takeaway
- 12.4.7.3 Delivery
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Restaurant Type - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Chained
- 12.5.7.2 Independent
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global Quick Service Restaurant Geographic Market Outlook, 2024-2032
- 13.1 Regional Market Size and Share, 2024
- 13.2 Regional Market Forecast, 2024-2032
- 13.3 Regional Pricing, Production and Demand Differences
- 13.4 North America
- 13.4.1 United States
- 13.4.2 Canada
- 13.4.3 Mexico
- 13.5 Europe
- 13.5.1 Germany
- 13.5.2 France
- 13.5.3 Italy
- 13.5.4 United Kingdom
- 13.5.5 Spain
- 13.5.6 Poland
- 13.5.7 Russia
- 13.5.8 Netherlands
- 13.5.9 Belgium
- 13.5.10 Sweden
- 13.5.11 Denmark
- 13.5.12 Norway
- 13.5.13 Rest of Europe
- 13.6 Asia Pacific
- 13.6.1 China
- 13.6.2 India
- 13.6.3 Japan
- 13.6.4 South Korea
- 13.6.5 Thailand
- 13.6.6 Indonesia
- 13.6.7 Vietnam
- 13.6.8 Malaysia
- 13.6.9 Australia
- 13.6.10 Rest of Asia Pacific
- 13.7 Latin America
- 13.7.1 Brazil
- 13.7.2 Argentina
- 13.7.3 Colombia
- 13.7.4 Chile
- 13.7.5 Rest of Latin America
- 13.8 Middle East
- 13.8.1 Saudi Arabia
- 13.8.2 United Arab Emirates
- 13.8.3 Turkey
- 13.8.4 Israel
- 13.8.5 Iran
- 13.8.6 Rest of the Middle East
- 13.9 Africa
- 13.9.1 South Africa
- 13.9.2 Egypt
- 13.9.3 Nigeria
- 13.9.4 Morocco
- 13.9.5 Rest of Africa
- 13.10 Regional Investment, Policy and Supply Chain Differences
- 13.11 Regional Competitive Landscape
- 13.12 Geographic Growth Hotspots
Chapter 14 Global Quick Service Restaurant Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2024-2032
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 Global Quick Service Restaurant Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2024
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2024-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 McDonald's Corporation
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 Yum! Brands, Inc.
- 17.4 Starbucks Corporation
- 17.5 Restaurant Brands International Inc.
- 17.6 Domino's Pizza, Inc.
- 17.7 Chick-fil-A
- 17.8 Papa John's International, Inc.
- 17.9 Subway IP LLC
- 17.10 The Wendy's Company
- 17.11 Dunkin
- 17.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

