
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
| Refrigerated Trucks Market Size 2024 | USD 3,949.3 million |
| Refrigerated Trucks Market, CAGR | 6.05% |
| Refrigerated Trucks Market Size 2032 | USD 6,318.37 million |
Market Overview:
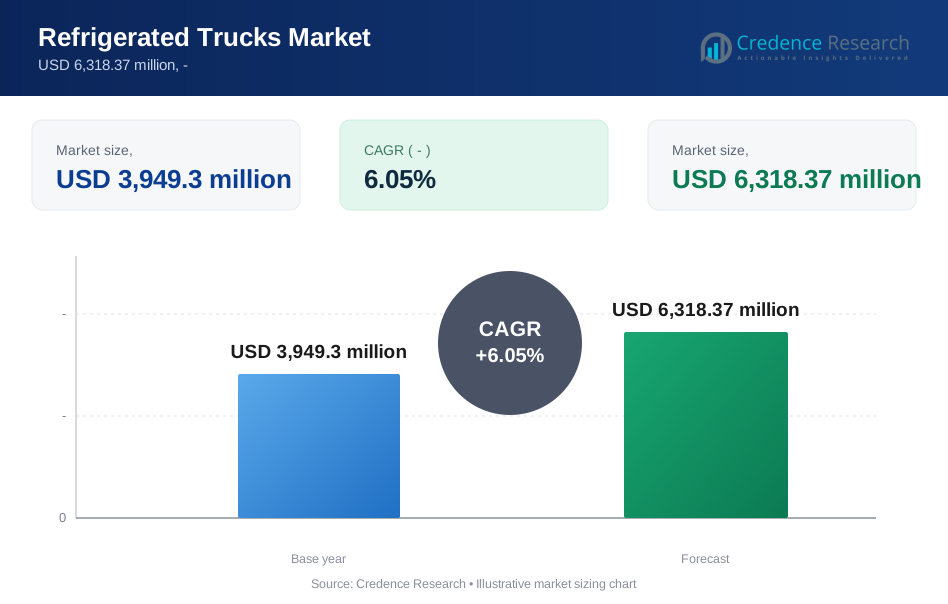
The global refrigerated trucks market is set for robust growth, with the market size expected to expand from USD 3,949.3 million in 2024 to USD 6,318.37 million by 2032, reflecting a compound annual growth rate (CAGR) of 6.05% over the forecast period. This growth is driven by the increasing demand for temperature-controlled transportation solutions across various industries, including food and beverages, pharmaceuticals, and chemicals. As global supply chains become more complex, the need for efficient and reliable refrigerated transport has surged, particularly for perishable goods that require precise temperature management to maintain quality and safety during transit.
Several key factors are propelling the growth of the refrigerated trucks market. The expanding global trade in perishable goods, particularly in the food and beverage industry, is a major driver. As consumers demand fresh produce, dairy products, and frozen foods year-round, the need for advanced refrigerated transportation solutions is rising. Additionally, the pharmaceutical industry's growth, especially in the distribution of temperature-sensitive drugs and vaccines, has significantly increased the demand for refrigerated trucks. The rise of e-commerce and the trend towards online grocery shopping are also contributing to market growth, as retailers seek reliable logistics solutions to ensure timely delivery of perishable items to consumers.
North America is expected to dominate the refrigerated trucks market, holding the largest market share during the forecast period. This is due to the region's well-established cold chain infrastructure and the high demand for perishable goods transportation, particularly in the United States and Canada. The Asia-Pacific region is projected to be the fastest-growing market, driven by rapid urbanization, increasing disposable incomes, and the expanding middle class in countries like China and India. These factors are boosting demand for fresh and frozen foods, thereby increasing the need for refrigerated transportation. Europe also represents a significant market, supported by stringent regulations regarding food safety and the transportation of pharmaceuticals, particularly in countries like Germany, France, and the United Kingdom.
Market Drivers:
Growing Demand for Perishable Goods:
The increasing global demand for perishable goods is a major driver of the refrigerated trucks market. As consumers become more health-conscious, there is a rising preference for fresh produce, dairy products, and frozen foods that require temperature-controlled transportation. For instance, the U.S. Department of Agriculture has reported a steady increase in the consumption of fresh fruits and vegetables, driven by consumer awareness of healthy eating habits. This trend necessitates reliable refrigerated logistics to ensure that these perishable items reach retail outlets and consumers in optimal condition, thereby driving the need for refrigerated trucks.
Expansion of the Pharmaceutical Industry:
The pharmaceutical industry's growth, particularly in the distribution of temperature-sensitive medications, is significantly contributing to the demand for refrigerated trucks. The need to transport vaccines, biologics, and other temperature-sensitive pharmaceuticals safely has led to stricter regulations and the adoption of advanced cold chain logistics solutions. For example, during the COVID-19 pandemic, the global distribution of vaccines required highly specialized refrigerated transportation to maintain the efficacy of the vaccines, underscoring the critical role of refrigerated trucks in the pharmaceutical supply chain.
Rise of E-commerce and Online Grocery Shopping:
The rapid growth of e-commerce, particularly in the grocery segment, is another key driver of the refrigerated trucks market. With consumers increasingly opting to purchase groceries online, retailers are under pressure to deliver perishable items quickly and in perfect condition. Companies like Amazon and Walmart have expanded their online grocery services, offering same-day or next-day delivery of fresh and frozen foods. This trend is driving the demand for a fleet of refrigerated trucks that can support the logistics of delivering temperature-sensitive goods to consumers' doorsteps efficiently.
Stringent Food Safety Regulations:
Stringent regulations regarding food safety and transportation standards are also driving the refrigerated trucks market. Governments worldwide are enforcing regulations that mandate the proper handling and transportation of perishable goods to prevent contamination and ensure food safety. For instance, the European Union's food safety regulations require that all perishable foods be transported at specific temperatures to prevent spoilage. These regulations compel companies to invest in reliable refrigerated transport solutions, thereby fueling the demand for refrigerated trucks equipped with advanced temperature control technologies.
Market Trends:
Adoption of Advanced Refrigeration Technologies:
One of the notable trends in the refrigerated trucks market is the adoption of advanced refrigeration technologies aimed at improving efficiency and reducing environmental impact. Companies are increasingly investing in technologies that offer better temperature control, lower energy consumption, and reduced emissions. For instance, electric-powered refrigeration units are becoming more popular as they provide consistent cooling without relying on the vehicle's engine, thus reducing fuel consumption and carbon emissions. This shift towards greener refrigeration solutions is driven by both regulatory pressures and the growing demand for sustainable practices within the logistics industry.
Integration of Telematics and IoT:
The integration of telematics and Internet of Things (IoT) technologies in refrigerated trucks is transforming the logistics industry by enhancing real-time monitoring and management capabilities. These technologies allow fleet managers to track the location, temperature, and operational status of their vehicles remotely, ensuring that perishable goods are transported under optimal conditions. For example, IoT-enabled sensors can alert drivers and fleet operators if there is a temperature deviation within the cargo area, allowing for immediate corrective actions. This trend is leading to improved efficiency, reduced spoilage rates, and enhanced customer satisfaction in the refrigerated transport sector.
Growth of Cold Chain Logistics in Emerging Markets:
The growth of cold chain logistics in emerging markets is another significant trend impacting the refrigerated trucks market. As economies in regions like Asia-Pacific and Latin America continue to expand, there is a rising demand for reliable cold chain solutions to support the transportation of perishable goods. For instance, countries like India and Brazil are witnessing increased investments in cold storage infrastructure and refrigerated transportation, driven by the growing middle class and rising consumer demand for fresh and processed foods. This trend is creating new opportunities for refrigerated truck manufacturers and logistics providers in these rapidly developing regions.
Emphasis on Regulatory Compliance and Food Safety:
The emphasis on regulatory compliance and food safety is shaping the refrigerated trucks market, with companies striving to meet increasingly stringent standards. Governments around the world are implementing regulations that require the proper handling and transportation of perishable goods to prevent spoilage and contamination. For instance, the U.S. Food and Drug Administration (FDA) enforces the Food Safety Modernization Act (FSMA), which mandates strict controls over the transportation of food products. This focus on compliance is driving the demand for advanced refrigerated trucks equipped with reliable temperature control systems and real-time monitoring capabilities, ensuring that food safety standards are consistently met throughout the supply chain.
Market Challenges Analysis:
High Operational Costs:
One of the primary restraints in the refrigerated trucks market is the high operational costs associated with maintaining and operating these specialized vehicles. Refrigerated trucks require sophisticated refrigeration units, which are expensive to purchase, install, and maintain. Additionally, these units consume significant amounts of energy, often relying on diesel-powered engines, which contribute to high fuel costs. The rising cost of fuel further exacerbates these expenses, making it challenging for logistics companies to manage operational costs effectively. For smaller operators, these high costs can be prohibitive, limiting their ability to compete with larger, more established players in the market.
Environmental and Regulatory Challenges:
The refrigerated trucks market also faces significant environmental and regulatory challenges. Governments around the world are increasingly imposing stringent emissions standards and environmental regulations, aimed at reducing the carbon footprint of the transportation sector. For instance, the European Union’s Euro 6 standards and similar regulations in other regions mandate lower emissions from commercial vehicles, including refrigerated trucks. Complying with these regulations often requires costly upgrades to vehicles or the adoption of alternative, lower-emission refrigeration technologies, which can be financially burdensome for companies. Additionally, the need to ensure compliance with food safety regulations, such as maintaining precise temperature control during transportation, adds another layer of complexity and cost to operations.
Supply Chain Disruptions:
Supply chain disruptions pose another significant challenge for the refrigerated trucks market. The global supply chain has been under considerable strain due to events such as the COVID-19 pandemic, geopolitical tensions, and natural disasters. These disruptions can lead to delays in the delivery of refrigerated trucks, spare parts, and refrigeration units, causing operational challenges for logistics companies. Furthermore, supply chain volatility can lead to fluctuating prices for key components, further impacting the cost structure and profitability of companies operating in the refrigerated trucks market. As supply chains become more complex and global, these challenges are likely to persist, requiring companies to develop more resilient and adaptable strategies.
Market Segmentation Analysis:
By Type:
The market is divided into light commercial vehicles (LCVs), medium commercial vehicles (MCVs), and heavy commercial vehicles (HCVs). LCVs are widely used for short-distance transportation of perishable goods, offering flexibility and cost-effectiveness. MCVs and HCVs are preferred for long-distance and bulk transportation, providing higher payload capacities and advanced refrigeration systems.
By Technology:
Technological segmentation includes vapor compression systems, eutectic systems, and cryogenic systems. Vapor compression systems dominate the market due to their efficiency and reliability in maintaining precise temperature control. Eutectic systems are gaining popularity for their energy efficiency and ability to maintain low temperatures for extended periods. Cryogenic systems, utilizing liquid nitrogen or carbon dioxide, offer rapid cooling and are used in specialized applications requiring ultra-low temperatures.
By End User:
The end-user segmentation comprises food and beverages, pharmaceuticals, chemicals, and others. The food and beverages segment is the largest, driven by the increasing demand for fresh and frozen products. Pharmaceuticals also contribute significantly, requiring precise temperature control for the safe transportation of vaccines, biologics, and other temperature-sensitive products. The chemicals segment includes the transportation of temperature-sensitive chemicals and industrial products.
Segmentation:
By Type
- Light Commercial Vehicle
- Medium Commercial Vehicle
- Heavy Commercial Vehicle
By Tonnage Capacity
- <10 Tons
- 10-20 Tons
- >20 Tons
By Application
- Food & Beverages
- Pharmaceuticals
- Chemicals
- Others
By Region
- North America
- The U.S
- Canada
- Mexico
- Europe
- Germany
- France
- The U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of Middle East and Africa
Regional Analysis:
North America
North America holds the largest market share, accounting for approximately 35% of the global refrigerated trucks market. This dominance is driven by the region's well-established cold chain infrastructure and the high demand for perishable goods transportation, particularly in the United States and Canada. The U.S., with its vast food and pharmaceutical industries, relies heavily on refrigerated transport to ensure the timely and safe delivery of temperature-sensitive products. The presence of key players in the logistics and transportation sectors further bolsters the market in North America.
Europe
Europe follows closely, holding around 30% of the global market share. The region is characterized by stringent food safety regulations and environmental standards, which drive the demand for advanced refrigerated trucks equipped with efficient and eco-friendly refrigeration systems. Countries such as Germany, France, and the United Kingdom are leading markets within Europe, supported by strong demand for fresh and frozen foods, as well as the transportation of pharmaceuticals. The European Union’s strict regulatory framework, including the Euro 6 emission standards, has prompted significant investments in upgrading fleets to meet these requirements, further stimulating market growth.
Asia-Pacific
Asia-Pacific is the fastest-growing region in the refrigerated trucks market, projected to account for about 25% of the global market share by 2032. This rapid growth is fuelled by increasing urbanization, rising disposable incomes, and the expanding middle class in countries like China and India. The demand for fresh and processed foods, as well as the growing pharmaceutical industry, are key drivers in this region. Additionally, the region is witnessing substantial investments in cold chain logistics infrastructure, particularly in China, where the government is prioritizing the development of efficient logistics systems to support its burgeoning e-commerce sector.
Latin America and the Middle East & Africa
Latin America and the Middle East & Africa together account for the remaining 10% of the market share, with Latin America leading at approximately 7%. In Latin America, Brazil and Mexico are the primary contributors to market growth, driven by the expanding agricultural sector and increasing exports of perishable goods. In the Middle East & Africa, the market is gradually expanding, supported by rising investments in infrastructure and the growing demand for temperature-controlled transportation of food and pharmaceuticals, particularly in the United Arab Emirates and Saudi Arabia.
Key Player Analysis:
- Thermo King (Ingersoll Rand)
- Carrier Transicold (United Technologies Corporation)
- DAF Trucks N.V.
- Hyundai Translead
- DAIKIN INDUSTRIES Ltd.
- Ingersoll Rand
- China International Marine Containers (Group) Co., Ltd.
- Utility Trailer Manufacturing Company
- Hyundai Translead Inc.
- Schmitz Cargobull AG
- KRONE
- LAMBERET SAS
- Wabash National Corporation
Competitive Analysis:
The refrigerated trucks market is highly competitive, characterized by the presence of several key players who dominate the industry through innovation, extensive distribution networks, and advanced technology integration. Major companies such as Thermo King (Ingersoll Rand), Carrier Transicold (United Technologies Corporation), DAF Trucks N.V., and Hyundai Translead lead the market, leveraging their expertise in refrigeration technologies and global reach to maintain a strong market position. These companies focus on developing energy-efficient, environmentally friendly refrigeration systems to meet the increasing regulatory demands and consumer preferences for sustainable solutions. Additionally, they invest significantly in research and development to introduce advanced refrigeration units that offer better temperature control and lower operating costs. The market also sees competition from regional players, particularly in emerging markets, where companies are expanding their fleets to meet the growing demand for cold chain logistics. This competitive landscape is driving continuous innovation and technological advancements in the refrigerated trucks sector.
Recent Developments:
- Thermo King (Ingersoll Rand) launched a new electric-powered refrigeration unit in 2023, designed to reduce emissions and improve energy efficiency. This unit is part of Thermo King's broader initiative to develop sustainable cold chain solutions that meet stricter environmental regulations while offering lower operating costs for fleet operators. The new unit has been well-received in markets with stringent emissions standards, such as Europe and North America.
- Carrier Transicold (United Technologies Corporation) introduced an upgraded version of its flagship refrigeration system in 2022, featuring advanced telematics capabilities. The new system allows fleet operators to monitor and control temperature settings remotely, ensuring optimal conditions for perishable goods during transit. This innovation aligns with Carrier Transicold's focus on enhancing the reliability and efficiency of cold chain logistics through digital technologies.
- DAF Trucks N.V. announced in 2024 the expansion of its refrigerated truck portfolio to include models with enhanced fuel efficiency and lower emissions. These new models are equipped with state-of-the-art refrigeration units that comply with the latest European emissions standards, offering customers a more environmentally friendly option for transporting temperature-sensitive goods. DAF’s commitment to sustainability is reflected in its continuous investment in eco-friendly technologies.
- Hyundai Translead introduced a new line of refrigerated trailers in 2023, featuring lightweight materials and improved insulation technology. These trailers are designed to enhance thermal efficiency, reducing the energy required to maintain stable temperatures inside the trailer. This development is part of Hyundai Translead's strategy to provide innovative, cost-effective solutions that meet the evolving needs of the cold chain logistics industry.
Market Concentration & Characteristics:
The refrigerated trucks market is moderately concentrated, with a few key players dominating the industry through their advanced technological capabilities, extensive distribution networks, and strong market presence. Companies such as Thermo King (Ingersoll Rand), Carrier Transicold (United Technologies Corporation), DAF Trucks N.V., and Hyundai Translead lead the market by offering innovative and sustainable refrigeration solutions that meet stringent environmental regulations. These market leaders focus on continuous innovation, integrating advanced telematics and energy-efficient refrigeration technologies into their products to maintain a competitive edge. The market is also characterized by a growing emphasis on sustainability, as companies respond to increasing regulatory pressures and consumer demand for eco-friendly solutions. Despite the dominance of these major players, the market remains competitive, with regional companies expanding their operations to meet the rising demand for cold chain logistics in emerging markets. This combination of global dominance and regional competition drives ongoing innovation and technological advancements in the refrigerated trucks market.
Report Coverage:
The research report offers an in-depth analysis based on Type, Tonnage Capacity, Application, and Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- The demand for refrigerated trucks is expected to continue growing, driven by increasing global trade in perishable goods and the expanding food and beverage industry.
- The market will see further advancements in refrigeration technology, including more energy-efficient and environmentally friendly systems.
- Emerging markets, particularly in Asia-Pacific and Latin America, will experience significant growth in refrigerated truck demand due to rising urbanization.
- The integration of telematics and IoT technologies in refrigerated trucks will become more widespread.
- The market will witness a shift towards electric and hybrid refrigerated trucks as part of a broader effort to reduce carbon emissions.
- Companies will prioritize sustainability, developing new refrigeration units that minimize environmental impact while maintaining efficiency and reliability.
- The rise of e-commerce, particularly in the grocery sector, will drive demand for refrigerated trucks as retailers seek reliable logistics solutions for the timely delivery of perishable goods.
- Smart refrigeration solutions that use AI and machine learning to optimize energy use and maintain optimal temperatures will become more prevalent in the market.
- Investments in expanding cold chain infrastructure globally will support the growth of the refrigerated trucks market, particularly in regions with developing logistics capabilities.
- The market will remain competitive, with key players continuing to innovate and expand their product offerings to maintain market leadership and meet evolving customer needs.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Refrigerated Trucks Market?
What factors are driving the growth of the Refrigerated Trucks Market?
What are some challenges faced by the Refrigerated Trucks Market?
Who are the major players in the Refrigerated Trucks Market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Refrigerated Trucks Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (the historical period; forecast to the forecast period)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Refrigerated Trucks Market Snapshot
- 2.1.1 Market Size – Historical (the historical period) & Forecast (the forecast period) (base year: USD 3,949.3 million → forecast year: USD 6,318.37 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Refrigerated Trucks Market Segmentation Snapshot
- 2.2.1 Market Split by Region – vs.
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share –
- 2.3.2 Top 10 Players by Volume Share –
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Refrigerated Trucks Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Refrigerated Trucks Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Refrigerated Trucks Market Drivers
- 3.3 Refrigerated Trucks Market Restraints & Challenges
- 3.4 Refrigerated Trucks Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Refrigerated Trucks Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Refrigerated Trucks Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Refrigerated Trucks category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Refrigerated Trucks Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through the forecast period
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through the forecast period
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Refrigerated Trucks Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (the historical period)
- 5.1.2 Global Export Volume by Country (the historical period)
- 5.1.3 Global Import Value by Country (the historical period)
- 5.1.4 Global Import Volume by Country (the historical period)
- 5.1.5 Net Trade Balance by Country (the historical period)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (the historical period)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Refrigerated Trucks market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Refrigerated Trucks Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs.
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Refrigerated Trucks Market Share Analysis –
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. )
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Refrigerated Trucks Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Refrigerated Trucks (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Refrigerated Trucks Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Refrigerated Trucks Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel ( & )
- 7.1.2 Channel Mix Evolution (the forecast period)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through the forecast period
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Refrigerated Trucks Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Refrigerated Trucks Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Refrigerated Trucks Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Refrigerated Trucks Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Refrigerated Trucks Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Refrigerated Trucks Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Refrigerated Trucks Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
