
Market Overview
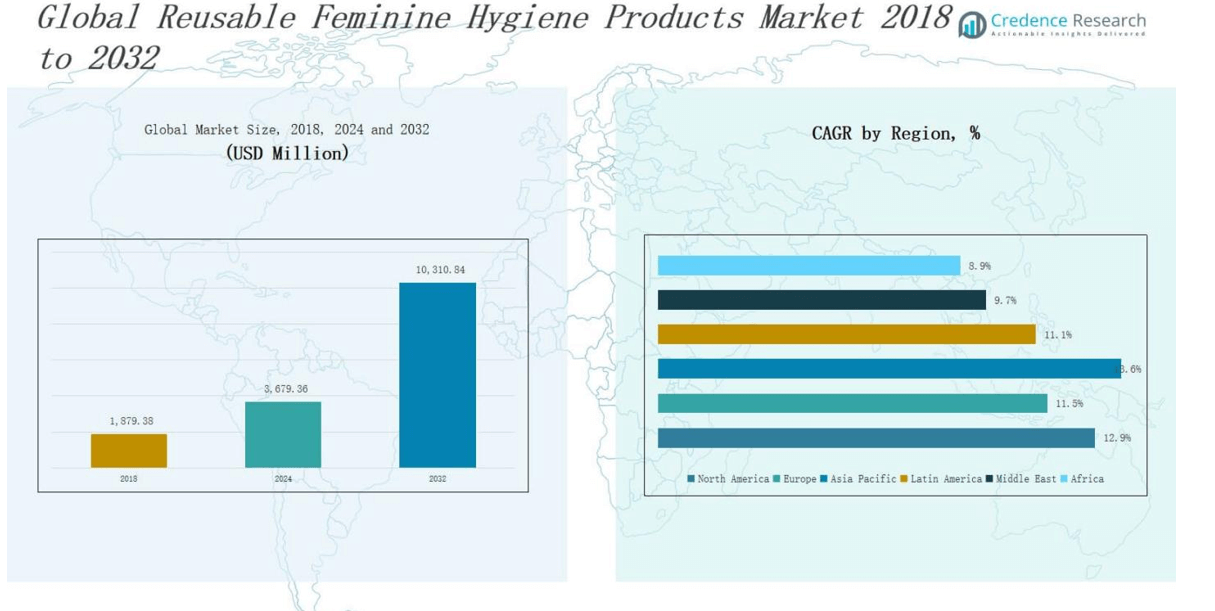
The Reusable Feminine Hygiene Products Market size was valued at USD 1,879.38 million in 2018 to USD 3,679.36 million in 2024 and is anticipated to reach USD 10,310.84 million by 2032, at a CAGR of 12.81% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Reusable Feminine Hygiene Products Market Size 2024 | USD 3,679.36 million |
| Reusable Feminine Hygiene Products Market, CAGR | 12.81% |
| Reusable Feminine Hygiene Products Market Size 2032 | USD 10,310.84 million |
The Reusable Feminine Hygiene Products Market is driven by rising environmental awareness, cost-efficiency over time, and increasing demand for sustainable personal care solutions. Consumers seek eco-friendly alternatives to disposables, supported by government initiatives and NGO-led menstrual health campaigns. The market benefits from innovations in design, comfort, and materials such as organic cotton and bamboo fiber. Digital platforms, influencer marketing, and e-commerce expansion enhance product visibility and consumer education. Growing adoption in emerging markets, along with personalized and inclusive product offerings, further accelerates growth and aligns with evolving health, hygiene, and sustainability preferences.
The Reusable Feminine Hygiene Products Market spans North America, Europe, Asia Pacific, Latin America, the Middle East, and Africa. Asia Pacific leads in market size, driven by population growth and awareness programs, while North America and Europe show strong adoption due to sustainability demand. Latin America is emerging, supported by youth and retail growth. The Middle East and Africa show steady progress through health campaigns. Key players include Pee Safe, Charlie Banana, Femy, Glad Rags, FabPad, Saathi, Isweven, Eco Femme, Aisle, and Rebelle Pads, with strategic focus on innovation and outreach.
Market Insights
- The Reusable Feminine Hygiene Products Market was valued at USD 1,879.38 million in 2018 and is projected to reach USD 10,310.84 million by 2032, growing at a CAGR of 12.81%.
- Rising environmental concerns and support from NGOs and governments are driving demand for reusable menstrual solutions across global markets.
- Product innovation in comfort, fit, and material (e.g., organic cotton and bamboo fiber) supports widespread adoption.
- E-commerce and digital education platforms are boosting product visibility, especially among younger consumers.
- Cultural stigma and limited infrastructure in rural areas continue to challenge growth, particularly in traditional markets.
- Asia Pacific holds the largest market share, while North America and Europe follow with strong sustainability adoption.
- Key players such as Pee Safe, Charlie Banana, Femy, Glad Rags, and Eco Femme focus on education, affordability, and outreach to expand presence across regions.
Market Drivers
Rising Awareness of Sustainable and Eco-Friendly Alternatives
The Reusable Feminine Hygiene Products Market is experiencing growth due to increasing consumer awareness of environmental sustainability. Women are actively seeking alternatives to disposable sanitary products, which contribute significantly to plastic waste. Governments, NGOs, and influencers are promoting eco-conscious choices, reinforcing the shift toward reusable solutions. Brands are educating consumers through digital campaigns about long-term savings and reduced environmental impact. It benefits from rising demand for products that align with zero-waste lifestyles and green purchasing behavior.
- For instance, Indian startup SanFe has developed a reusable sanitary pad made from composite banana fiber, which can be used for up to two years with 120 washes, offering an affordable and eco-friendly alternative.
Cost Efficiency and Long-Term Economic Benefits
Economic considerations play a vital role in the expansion of the Reusable Feminine Hygiene Products Market. While initial costs are higher, consumers recognize the long-term financial savings offered by reusable products. Menstrual cups, cloth pads, and period underwear can last several years, reducing the need for monthly purchases. This financial appeal is gaining traction among younger, budget-conscious consumers. It positions itself as a cost-effective solution for menstrual health. Economic uncertainty has further strengthened demand for reusable options.
- For instance, Thinx, a leading brand in period underwear, provides products designed to last several years, offering users durable and washable alternatives to disposables, helping reduce recurring menstrual hygiene expenses.
Improved Product Innovation and Comfort
Advancements in design, material technology, and user experience are driving the Reusable Feminine Hygiene Products Market forward. Manufacturers are investing in research to develop more comfortable, leak-proof, and skin-friendly products. The market has seen significant improvements in fit, absorption capacity, and antimicrobial features. It appeals to consumers seeking better comfort without compromising health or hygiene. Innovation in breathable and hypoallergenic fabrics strengthens trust and repeat use. Enhanced product quality directly influences adoption across demographics.
Supportive Regulatory and Institutional Frameworks
The Reusable Feminine Hygiene Products Market benefits from favorable policy initiatives and public health campaigns. Governments and educational institutions are distributing reusable products to promote menstrual hygiene. Subsidy programs and tax exemptions are increasing product accessibility in both urban and rural areas. It gains traction from NGO-led awareness programs focused on health, affordability, and dignity. Institutional support accelerates mainstream adoption. Collaborations between manufacturers and public agencies further reinforce market growth.
Market Trends
Integration of Digital Platforms to Educate and Influence Consumers
The Reusable Feminine Hygiene Products Market is witnessing a growing reliance on digital platforms to shape consumer behavior and product awareness. Social media influencers, health professionals, and eco-conscious brands use targeted campaigns to highlight the environmental and economic benefits of reusable products. E-commerce channels simplify access and offer discreet purchasing experiences. It leverages digital content to overcome stigma and misinformation. Reviews and tutorials improve confidence in usage. Online presence plays a pivotal role in product discovery and brand loyalty.
- For instance, HealthFab, an Indian feminine hygiene company, introduced its washable and reusable GoPadFree Ultra period panty online in October 2022, using e-commerce and social media campaigns to highlight durability and sustainability.
Expansion of Product Lines and Hybrid Menstrual Solutions
Brands in the Reusable Feminine Hygiene Products Market are diversifying their portfolios to cater to different age groups, flow levels, and personal preferences. Hybrid solutions that combine features of menstrual cups, pads, and underwear are gaining popularity. It encourages cross-category experimentation among consumers who value flexibility. Innovation focuses on design inclusivity, enabling better fit and comfort for varied body types. Manufacturers are offering bundles to simplify adoption. Personalization drives product differentiation in a competitive landscape.
- For instance, Essity launched the Libresse V-Cup, a reusable menstrual cup made from 100% medical-grade silicone, providing up to 12 hours of protection and reducing waste, now available in Nordic countries.
Increased Focus on Circular Economy and Closed-Loop Models
Sustainability remains a dominant theme in the Reusable Feminine Hygiene Products Market, with manufacturers prioritizing recyclable materials and ethical sourcing. Brands are introducing take-back programs to recycle worn-out products responsibly. It aligns with circular economy principles to reduce waste and resource dependency. Certification labels such as OEKO-TEX and GOTS influence purchasing decisions. Supply chain transparency supports consumer trust. Companies are integrating life cycle assessment metrics into product development to enhance environmental credibility.
Rising Adoption in Emerging Markets Through Awareness and Accessibility
The Reusable Feminine Hygiene Products Market is expanding in emerging economies where NGOs and health ministries promote menstrual health education. Initiatives in countries across Africa, South Asia, and Latin America focus on breaking cultural taboos and providing free or subsidized products. It responds to growing demand from underserved communities facing cost and access challenges. Localization strategies include community workshops and culturally sensitive designs. Multilingual packaging and mobile outreach increase acceptance and reach. Mass adoption is gradually accelerating.
Market Challenges Analysis
Cultural Barriers and Lack of Awareness in Traditional Markets
The Reusable Feminine Hygiene Products Market faces resistance in regions where menstruation remains a cultural taboo. In many communities, limited awareness and social stigma hinder open discussions about menstrual health. Misconceptions about product hygiene and safety create hesitation toward adoption. It struggles to gain acceptance where education and outreach programs are absent or underfunded. Language barriers and lack of culturally adapted communication further slow market penetration. Building trust requires long-term community engagement and localized education efforts.
Limited Infrastructure and Product Accessibility in Rural Areas
Inadequate distribution networks and lack of retail availability restrict the reach of reusable menstrual products in remote locations. Many rural consumers rely on local vendors who do not stock these products due to low perceived demand. It often faces challenges in creating scalable and cost-effective supply chains for underserved areas. Absence of water and sanitation infrastructure affects usage, especially for products like menstrual cups. Poor electricity access limits the effectiveness of digital education campaigns. Logistical hurdles reduce product visibility and adoption.
Market Opportunities
Growing Demand for Customizable and Inclusive Product Designs
The Reusable Feminine Hygiene Products Market holds strong potential in offering customizable products that suit diverse body types, flow levels, and age groups. Consumers increasingly seek personalized comfort and functionality in menstrual care. Brands that introduce adjustable sizes, inclusive color ranges, and skin-sensitive materials can capture a wider customer base. It benefits from a growing trend toward body positivity and inclusive wellness. Targeted innovations can improve product adoption across various demographics. User-driven design presents a key avenue for differentiation.
Rising Government and NGO Support in Emerging Economies
Expanding partnerships with public health organizations and NGOs creates substantial opportunity in the Reusable Feminine Hygiene Products Market. Governments are allocating funds for menstrual health programs, focusing on sustainable and cost-effective solutions. It stands to gain from national campaigns promoting hygiene education and access to reusable alternatives. Institutional distribution channels help bridge affordability gaps. Pilot programs in schools and rural communities can scale with the right policy backing. Public sector collaboration enhances both visibility and impact.
Market Segmentation Analysis:
By Product Type
The Reusable Feminine Hygiene Products Market includes reusable sanitary pads, menstrual cups, period underwear, pantyliners, and others. Reusable sanitary pads lead the segment due to their familiarity and ease of transition from disposables. Menstrual cups follow closely, offering durability and long-term cost savings. Period underwear is gaining popularity among younger consumers for its convenience and comfort. Reusable pantyliners serve lighter flow needs or daily use. It benefits from increasing product innovation and wider consumer acceptance across all product types.
- For instance, brands like Modibodi and THINX have innovated with multiple absorbent layers and moisture-wicking fabrics, making period underwear a comfortable and reliable option.
By Material
Material selection significantly influences consumer preference in the Reusable Feminine Hygiene Products Market. Organic cotton holds a dominant share due to its softness, breathability, and hypoallergenic properties. Bamboo fiber is valued for its high absorbency and antibacterial traits, attracting eco-conscious buyers. Charcoal-lined fabrics are emerging for odor control and moisture-wicking functions. It sees rising demand for ethically sourced, biodegradable, and skin-safe materials. Sustainability and skin sensitivity continue to shape product development in this segment.
- For instance, Brown Living produces reusable sanitary pads using organic cotton, bamboo cotton zorb, and bamboo fiber, providing moisture-wicking, antibacterial benefits while ensuring chemical- and fragrance-free products that prevent irritation and odor.
By Distribution Channel
Online e-commerce dominates the distribution channel segment of the Reusable Feminine Hygiene Products Market. Consumers prefer the convenience, privacy, and product variety offered by online platforms. Pharmacies remain key for health-focused buyers seeking trusted brands. Supermarkets and hypermarkets support impulse purchases and broad consumer access. Specialty stores cater to niche preferences with curated sustainable product lines. It adapts distribution strategies to address both urban convenience and rural outreach across all channels.
Segments:
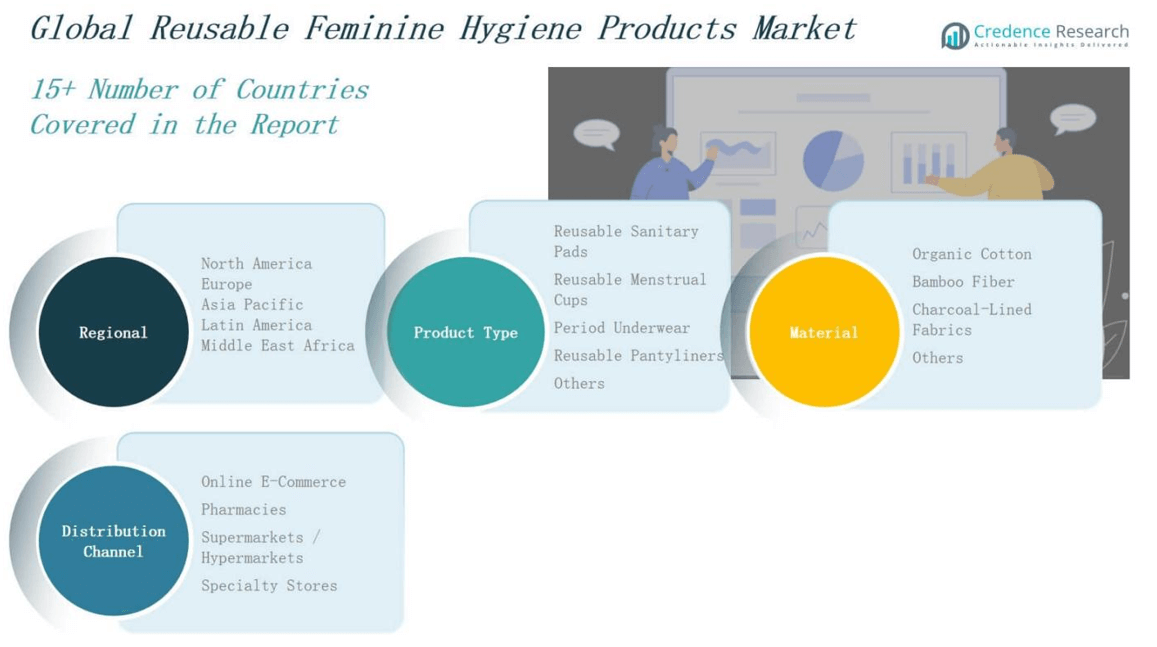
Based on Product Type:
- Reusable Sanitary Pads
- Reusable Menstrual Cups
- Period Underwear
- Reusable Pantyliners
- Others
Based on Material:
- Organic Cotton
- Bamboo Fiber
- Charcoal-Lined Fabrics
- Others
Based on Distribution Channel:
- Online E-Commerce
- Pharmacies
- Supermarkets / Hypermarkets
- Specialty Stores
Based on Region:
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis
North America
The North America Reusable Feminine Hygiene Products Market size was valued at USD 554.85 million in 2018 to USD 1,069.57 million in 2024 and is anticipated to reach USD 3,009.68 million by 2032, at a CAGR of 12.9% during the forecast period. North America accounts for a significant share of the global market, driven by high consumer awareness and product availability. The U.S. leads regional demand with strong e-commerce infrastructure and growing focus on sustainability. It benefits from government initiatives promoting menstrual health and reusable alternatives. Canadian consumers are increasingly adopting eco-friendly menstrual products, especially among younger demographics. The region supports innovation and product standardization through stringent regulatory frameworks.
Europe
The Europe Reusable Feminine Hygiene Products Market size was valued at USD 348.12 million in 2018 to USD 643.90 million in 2024 and is anticipated to reach USD 1,639.45 million by 2032, at a CAGR of 11.5% during the forecast period. Europe holds a substantial market share, supported by environmental regulations and consumer preference for sustainable products. Countries like Germany, France, and the UK drive demand through retail availability and health education programs. It sees high penetration of organic and biodegradable materials. Regional manufacturers focus on ethical sourcing and transparency in product labeling. Market growth is also fueled by subsidies and awareness campaigns across educational institutions and NGOs.
Asia Pacific
The Asia Pacific Reusable Feminine Hygiene Products Market size was valued at USD 820.05 million in 2018 to USD 1,664.82 million in 2024 and is anticipated to reach USD 4,950.39 million by 2032, at a CAGR of 13.6% during the forecast period. Asia Pacific dominates the global market with the largest share due to its large population and rising awareness about menstrual hygiene. Countries such as India, China, and Japan are key contributors, supported by government and NGO-led programs. It benefits from rapid urbanization, affordability-driven demand, and growing online platforms. Local manufacturers offer culturally adaptive and affordable solutions. Rising school initiatives and social campaigns expand reach among underserved communities.
Latin America
The Latin America Reusable Feminine Hygiene Products Market size was valued at USD 90.44 million in 2018 to USD 174.90 million in 2024 and is anticipated to reach USD 434.87 million by 2032, at a CAGR of 11.1% during the forecast period. Latin America is emerging as a promising region due to increased awareness and affordability concerns. Brazil and Argentina lead demand, supported by growing retail networks and youth-driven sustainability trends. It shows rising acceptance of menstrual cups and reusable pads in urban areas. Governments and NGOs are collaborating to promote hygiene education and product access. Language-sensitive campaigns help strengthen adoption across diverse communities.
Middle East
The Middle East Reusable Feminine Hygiene Products Market size was valued at USD 41.99 million in 2018 to USD 73.36 million in 2024 and is anticipated to reach USD 164.34 million by 2032, at a CAGR of 9.7% during the forecast period. The market in the Middle East is growing steadily, supported by increasing health awareness and female empowerment initiatives. Countries like the UAE and Israel are leading adoption, with expanding product availability through online and pharmacy channels. It faces cultural challenges but gains traction among younger consumers and expatriate populations. Brands invest in targeted marketing and education to shift consumer perceptions. Market development relies on partnerships with schools and health organizations.
Africa
The Africa Reusable Feminine Hygiene Products Market size was valued at USD 23.93 million in 2018 to USD 52.81 million in 2024 and is anticipated to reach USD 112.11 million by 2032, at a CAGR of 8.9% during the forecast period. Africa represents a high-potential but underpenetrated market with strong NGO and government involvement. South Africa leads the region, followed by Kenya and Nigeria, where menstrual health education programs are gaining momentum. It faces infrastructural and affordability challenges in rural regions. Subsidized distribution and school-based programs drive initial adoption. Culturally sensitive outreach and low-cost product innovation are essential to scaling regional demand.
Key Player Analysis
- Femy
- Pee Safe
- Glad Rags
- FabPad
- Saathi
- Isweven
- Eco Femme
- Charlie Banana
- Aisle
- Rebelle Pads
Competitive Analysis
The Reusable Feminine Hygiene Products Market features a competitive landscape marked by innovation, sustainability, and consumer-centric strategies. Key players such as Pee Safe, Charlie Banana, Femy, and Glad Rags focus on expanding their product lines to include organic, skin-safe, and customizable options. It emphasizes direct-to-consumer models through e-commerce and leverages social media for brand engagement. Companies invest in biodegradable materials and ergonomic designs to improve product performance. Collaborations with NGOs and health institutions support market penetration in underserved regions. New entrants challenge incumbents through aggressive pricing and region-specific solutions. Strategic branding, eco-certifications, and user education drive long-term customer loyalty and differentiation. Players also engage in regional partnerships, subscription-based models, and awareness campaigns to strengthen presence. Continuous R&D in absorbent technology, comfort, and reusability ensures a competitive edge.
Recent Developments
- In January 2024, Compass Diversified acquired The Honey Pot Company in a $380 million deal to expand its footprint in reusable and herbal-based feminine care products.
- In July 2024, Unilever Ventures invested over £2 million in Luna Daily, a UK-based brand specializing in microbiome-friendly and sustainable intimate care products.
- In July 2025, Essity partnered with UNICEF to support access to reusable menstrual hygiene products in underserved regions through global health and sustainability initiatives.
- In October 2024, Good Glamm Group acquired Sirona Hygiene for ₹450 crore, strengthening its presence in India’s reusable menstrual product market, including menstrual cups and organic pads.
Market Concentration & Characteristics
The Reusable Feminine Hygiene Products Market displays moderate market concentration, with several established players and a growing number of emerging brands competing across global and regional levels. It features a mix of legacy manufacturers like Glad Rags and newer entrants such as Pee Safe and FabPad, each leveraging innovation, affordability, and eco-conscious branding to gain share. The market is highly consumer-driven, with purchasing behavior shaped by comfort, sustainability, price, and health awareness. E-commerce channels dominate distribution, supported by strong digital engagement strategies. Product differentiation centers on materials, design, and customization, catering to diverse user preferences. The market remains fragmented in developing regions due to infrastructural limitations and cultural resistance. It benefits from growing institutional support, educational outreach, and increasing retail penetration in both urban and semi-urban areas. Manufacturers prioritize transparency, certifications, and user education to build loyalty and distinguish themselves in a rapidly evolving competitive environment.
Report Coverage
The research report offers an in-depth analysis based on Product Type, Material, Distribution Channel and Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Demand for reusable menstrual products will increase due to rising environmental awareness and plastic waste concerns.
- Manufacturers will focus on developing more comfortable, skin-friendly, and leak-proof designs.
- E-commerce platforms will play a larger role in expanding product reach and consumer education.
- Adoption will grow in emerging markets through NGO programs and school-based hygiene campaigns.
- Product offerings will diversify to include more size, flow, and material variations.
- Governments will introduce more policy support, including subsidies and tax exemptions.
- Brands will invest in biodegradable and certified organic materials to meet sustainability goals.
- Social media and influencers will continue to drive awareness and normalize usage.
- Localization strategies will become important to address cultural sensitivities and regional needs.
- Partnerships between public institutions and private companies will strengthen market penetration efforts.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Rising Environmental Awareness and Sustainability
Growing concerns about plastic waste and environmental impact are pushing consumers to seek eco-friendly alternatives to disposable menstrual products. This shift is reinforced by government and NGO campaigns promoting sustainable menstrual hygiene solutions.
Cost Efficiency and Long-Term Savings
Reusable feminine hygiene products offer significant long-term cost savings compared to disposables, appealing to budget-conscious consumers and those in emerging markets. The economic benefits are increasingly highlighted in marketing and educational campaigns.
Product Innovation in Comfort and Materials
Advancements in design, fit, and the use of skin-friendly materials like organic cotton and bamboo fiber are making reusable products more comfortable and appealing. Enhanced absorption, antimicrobial features, and customizable options are driving broader adoption.
Supportive Policy and Institutional Initiatives
Government subsidies, tax exemptions, and NGO-led distribution programs are improving accessibility and affordability of reusable products, especially in underserved and rural areas. These initiatives are critical in overcoming barriers to adoption.
Digital Platforms and Influencer Marketing
The expansion of e-commerce and the use of social media influencers are increasing product visibility and consumer education. Digital channels help normalize reusable products, address stigma, and provide easy access for younger and urban consumers.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Reusable Feminine Hygiene Products Market?
What are the key segments within the Reusable Feminine Hygiene Products Market?
What are some challenges faced by the Reusable Feminine Hygiene Products Market?
Who are the major players in the Reusable Feminine Hygiene Products Market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Material
- 1.2.1 Organic Cotton
- 1.2.2 Bamboo Fiber
- 1.2.3 Charcoal-Lined Fabrics
- 1.2.4 Others
- 1.3 By Product Type
- 1.3.1 Reusable Sanitary Pads
- 1.3.2 Reusable Menstrual Cups
- 1.3.3 Period Underwear
- 1.3.4 Reusable Pantyliners
- 1.3.5 Others
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 3,679.36 million → 2032: USD 10,310.84 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Reusable Feminine Hygiene Products Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Reusable Feminine Hygiene Products Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Reusable Feminine Hygiene Products Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Reusable Feminine Hygiene Products Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Reusable Feminine Hygiene Products Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Reusable Feminine Hygiene Products Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Reusable Feminine Hygiene Products Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Reusable Feminine Hygiene Products Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 3,679.36 million → 2032: USD 10,310.84 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Reusable Feminine Hygiene Products Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Material - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Organic Cotton
- 12.3.7.2 Bamboo Fiber
- 12.3.7.3 Charcoal-Lined Fabrics
- 12.3.7.4 Others
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Product Type - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Reusable Sanitary Pads
- 12.4.7.2 Reusable Menstrual Cups
- 12.4.7.3 Period Underwear
- 12.4.7.4 Reusable Pantyliners
- 12.4.7.5 Others
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 Segment Growth Comparison
- 12.6 Segment Attractiveness and Priority Matrix
Chapter 13 Global Reusable Feminine Hygiene Products Geographic Market Outlook, 2024-2032
- 13.1 Regional Market Size and Share, 2024
- 13.2 Regional Market Forecast, 2024-2032
- 13.3 Regional Pricing, Production and Demand Differences
- 13.4 North America
- 13.4.1 United States
- 13.4.2 Canada
- 13.4.3 Mexico
- 13.5 Europe
- 13.5.1 Germany
- 13.5.2 France
- 13.5.3 Italy
- 13.5.4 United Kingdom
- 13.5.5 Spain
- 13.5.6 Poland
- 13.5.7 Russia
- 13.5.8 Netherlands
- 13.5.9 Belgium
- 13.5.10 Sweden
- 13.5.11 Denmark
- 13.5.12 Norway
- 13.5.13 Rest of Europe
- 13.6 Asia Pacific
- 13.6.1 China
- 13.6.2 India
- 13.6.3 Japan
- 13.6.4 South Korea
- 13.6.5 Thailand
- 13.6.6 Indonesia
- 13.6.7 Vietnam
- 13.6.8 Malaysia
- 13.6.9 Australia
- 13.6.10 Rest of Asia Pacific
- 13.7 Latin America
- 13.7.1 Brazil
- 13.7.2 Argentina
- 13.7.3 Colombia
- 13.7.4 Chile
- 13.7.5 Rest of Latin America
- 13.8 Middle East
- 13.8.1 Saudi Arabia
- 13.8.2 United Arab Emirates
- 13.8.3 Turkey
- 13.8.4 Israel
- 13.8.5 Iran
- 13.8.6 Rest of the Middle East
- 13.9 Africa
- 13.9.1 South Africa
- 13.9.2 Egypt
- 13.9.3 Nigeria
- 13.9.4 Morocco
- 13.9.5 Rest of Africa
- 13.10 Regional Investment, Policy and Supply Chain Differences
- 13.11 Regional Competitive Landscape
- 13.12 Geographic Growth Hotspots
Chapter 14 Global Reusable Feminine Hygiene Products Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2024-2032
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 Global Reusable Feminine Hygiene Products Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2024
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2024-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Pee Safe
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 Charlie Banana
- 17.4 Femy
- 17.5 Glad Rags
- 17.6 FabPad
- 17.7 Saathi
- 17.8 Isweven
- 17.9 Eco Femme
- 17.10 Aisle
- 17.11 Rebelle Pads
- 17.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

