
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Robot Operating System Market Size 2024 | USD 643 Million |
| Robot Operating System Market , CAGR | 12.6% |
| Robot Operating System Market Size 2032 | USD 1661.5 Million |
Market Overview:
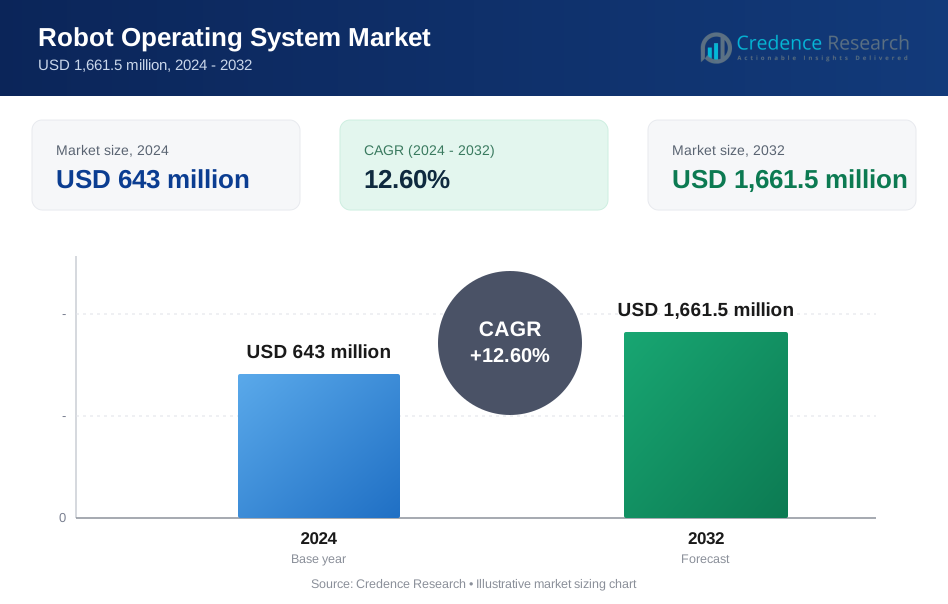
Robot Operating System Market size was valued at USD 643 million in 2024 and is anticipated to reach USD 1661.5 million by 2032, at a CAGR of 12.6% during the forecast period (2024-2032).
A major driver of the Robot Operating System market is the rising demand for collaborative robots (cobots) in industrial settings. These systems require modular, scalable, and customizable frameworks—features inherently supported by ROS. Additionally, the growing interest in robotics for medical surgeries, rehabilitation, warehouse automation, and personal assistance is broadening the scope of ROS applications. Advancements in sensor technologies and edge computing are further strengthening the role of ROS in enabling real-time data processing and navigation capabilities for robots. The growing ecosystem of ROS-based tools, packages, and simulation environments also enhances developer productivity and accelerates deployment cycles across use cases. The increasing adoption of ROS in academic research and university robotics programs is also nurturing a skilled talent pool and accelerating innovations. Moreover, the emergence of ROS 2, with its improved real-time capabilities and security enhancements, is expected to further drive adoption in safety-critical and industrial applications.
Regionally, North America dominates the global Robot Operating System market due to the early adoption of advanced robotics and the strong presence of leading robotics companies and research institutions in the United States and Canada. Europe follows closely, supported by government initiatives promoting Industry 4.0 and automation. The Asia-Pacific region is expected to witness the fastest growth over the forecast period, driven by rapid industrialization, expanding manufacturing sectors in China, Japan, and South Korea, and increasing investments in robotics and AI infrastructure. Strategic government programs such as Japan’s Society 5.0 and China’s Made in China 2025 are further accelerating ROS integration into industrial and service sectors. Additionally, collaborations between global ROS developers and regional tech companies are fostering localized innovation and expanding market penetration in emerging economies.
Market Insights:
- The Robot Operating System Market was valued at USD 643 million in 2024 and is projected to reach USD 1,661.5 million by 2032, growing at a CAGR of 12.6%.
- Increasing automation across manufacturing, logistics, and healthcare is driving demand for ROS due to its modularity and flexibility.
- AI and sensor technology advancements are enabling ROS to support complex, autonomous, and intelligent robotic functions.
- Collaborative robots (cobots) are boosting ROS adoption by enabling safe, customizable, and scalable robotic solutions.
- Universities and research centers are integrating ROS, expanding the talent pool and accelerating robotics innovation.
- Integration issues, security concerns, and a shortage of skilled professionals remain key challenges for market expansion.
- North America holds 38% market share, followed by Europe (28%) and Asia Pacific (24%), with the latter showing the fastest growth.
Market Drivers:
Industrial Automation and Demand for Operational Efficiency Drive Market Expansion
The Robot Operating System Market is experiencing robust growth, propelled by the escalating adoption of automation across manufacturing, logistics, healthcare, and service industries. Organizations seek to enhance productivity, precision, and operational efficiency, and robot operating systems provide the flexibility and modularity required to meet these needs. It enables seamless integration of robotic hardware and software, simplifying deployment and reducing development time. The surge in industrial automation, supported by the need to minimize human intervention and optimize processes, continues to be a primary market driver. Companies leverage it to address labor shortages, improve quality control, and achieve cost savings. The market benefits from the ongoing shift toward digital transformation and smart manufacturing practices.
Technological Advancements and Integration of Artificial Intelligence Accelerate Adoption
Advancements in robotics hardware, sensor technologies, and artificial intelligence are significantly enhancing the capabilities of robot operating systems. The integration of AI and machine learning enables robots to perform more complex, autonomous tasks and adapt to dynamic environments. It allows developers to build intelligent robotic applications that can analyze data, make decisions, and interact safely with humans. The open-source nature of many robot operating systems encourages rapid innovation and collaboration, further accelerating technology adoption. These technological improvements expand the range of use cases, making it an attractive solution for industries seeking to deploy sophisticated robotics at scale.
- For instance, Boston Dynamics’ Atlas humanoid robot now utilizes the NVIDIA Jetson Thor computing platform, enabling it to run complex, multimodal AI models for advanced dexterity and locomotion; this collaboration was publicly demonstrated in March 2025.
Collaborative Robots and Modular Platforms Expand Market Reach
The rising adoption of collaborative robots, or cobots, is transforming industrial operations by enabling safe human-robot interaction on factory floors and in service environments. The Robot Operating System Market leverages modular software frameworks to facilitate the development of customizable and scalable robotic solutions. It reduces the complexity of software engineering, allowing businesses to deploy robots for repetitive, hazardous, or precision-driven tasks. The growing popularity of Robotics-as-a-Service (RaaS) models and increased R&D funding for modular platforms are further broadening the market’s application landscape. This trend supports organizations in streamlining robotics development and responding quickly to evolving operational demands.
Education, Research, and Industry Collaboration Foster Ecosystem Growth
The integration of robot operating systems into educational curricula and research initiatives is cultivating a skilled workforce capable of advancing robotics innovation. Universities and training centers use it to teach robotics concepts and support hands-on projects, strengthening the talent pipeline and driving adoption in new sectors. Industry collaborations, strategic partnerships, and increased R&D investments by leading providers are expanding the ecosystem and enhancing product offerings. These efforts lower barriers to entry for small and medium enterprises, enabling broader participation and accelerating market growth. The continuous evolution of the robot operating system ecosystem ensures it remains at the forefront of industrial automation and intelligent robotics solutions.
- For instance, the TU Delft Online "Hello (Real) World with ROS" MOOC equips students to program full robotic applications, including building a simulated industrial production line with two robot arms and a mobile robot, using ROS tools such as Move It! and Gazebo.
Market Trends:
Integration of Cloud Robotics and Edge Computing Redefines Deployment Strategies
The Robot Operating System Market is witnessing a significant shift with the integration of cloud robotics and edge computing technologies. Companies are adopting hybrid architectures that combine centralized cloud processing with distributed edge nodes to enhance real-time decision-making and reduce latency. It enables robots to process large volumes of data locally while leveraging cloud resources for advanced analytics and machine learning. This trend supports the deployment of scalable, flexible robotic systems across industries such as manufacturing, healthcare, and logistics. Security and data privacy concerns prompt organizations to balance cloud and edge solutions, ensuring compliance and operational resilience. The market continues to evolve as vendors introduce platforms that seamlessly connect robots to both cloud and edge environments.
- For instance, ABB’s OmniCore platform now serves as a unified control architecture for nearly its entire robotics portfolio after a $170 million investment in next-generation automation technology.
Open-Source Collaboration and Standardization Fuel Ecosystem Expansion
Open-source collaboration and the push for standardization are shaping the development landscape within the Robot Operating System Market. Developers, research institutions, and industry leaders contribute to open-source frameworks, accelerating innovation and lowering barriers to entry for new participants. It fosters interoperability between different robotic platforms, encouraging the adoption of modular and reusable software components. The trend toward standardization simplifies integration, reduces development costs, and promotes widespread adoption in emerging sectors such as agriculture, retail, and autonomous vehicles. Strategic alliances and industry consortia play a crucial role in defining best practices and technical standards. The ongoing expansion of the ecosystem ensures a vibrant, competitive market that supports rapid technological advancement.
- For instance, the Clearpath Husky platform, a medium-sized robotic development unit, was deployed in a major field trial at the Joint European Torus (JET), where one of six Husky units was modified to withstand nuclear environments, autonomously scanning for radiation and returning to base after several hours of operation.
Market Challenges Analysis:
Complex Integration and Interoperability Issues Hinder Seamless Deployment
The Robot Operating System Market faces persistent challenges related to complex integration and interoperability across diverse hardware and software environments. Many organizations encounter difficulties aligning legacy systems and proprietary platforms with modern robot operating systems. It often requires significant customization, technical expertise, and time to achieve seamless connectivity. Varying communication protocols and inconsistent standards further complicate system integration. These issues can delay project timelines and increase implementation costs. The market must address these technical barriers to unlock broader adoption and operational efficiency.
Security Concerns and Skills Shortages Limit Market Growth
Security vulnerabilities and a shortage of skilled professionals present ongoing obstacles for the Robot Operating System Market. It remains susceptible to cyber threats targeting both software and networked robotic devices. Organizations express concerns about data privacy, unauthorized access, and system reliability. The demand for specialized talent in robotics, AI, and cybersecurity often exceeds supply, slowing innovation and deployment. Training and upskilling initiatives are critical to bridge this gap. Addressing these concerns is essential for building trust and sustaining long-term market growth.
Market Opportunities:
Expansion into Emerging Sectors and Service Robotics Unlocks New Revenue Streams
The Robot Operating System Market holds significant opportunities in emerging sectors such as agriculture, retail, and healthcare. Organizations in these industries seek automation solutions to address labor shortages, improve efficiency, and enhance service quality. It enables rapid development and deployment of customized robotic applications tailored to sector-specific needs. The growing demand for service robots in areas like delivery, cleaning, and elder care presents new avenues for market growth. Companies can leverage it to create innovative solutions that address unique operational challenges. The expansion into non-traditional markets supports revenue diversification and long-term sustainability.
Advancements in Artificial Intelligence and 5G Connectivity Enhance Market Potential
Advancements in artificial intelligence and the rollout of 5G connectivity create new possibilities for the Robot Operating System Market. It allows robots to perform more complex, autonomous tasks and interact seamlessly with humans and other machines. Enhanced connectivity supports real-time data sharing, remote monitoring, and decentralized control of robotic fleets. These technological improvements increase the value proposition for industries seeking scalable, intelligent automation. Strategic investments in AI-driven robotics and next-generation networks will accelerate adoption across global markets. The convergence of these trends positions the market for sustained innovation and growth.
Market Segmentation Analysis:
By Application Segment:
By Application, the Robot Operating System Market demonstrates strong momentum in industrial automation, logistics, and healthcare. Industrial automation holds the largest share, driven by demand for precision, efficiency, and reduced operational costs. Logistics applications follow, where it streamlines warehouse management, inventory tracking, and material handling. Healthcare robotics is gaining traction, supporting surgical assistance, patient care, and laboratory automation. These applications highlight the market’s versatility and adaptability to diverse operational needs.
- For instance, DHL Supply Chain has already deployed 3,000 Locus Origin AMRs globally, with a plan to reach 5,000 units by year-end.
By End-Use Segment:
By End-Use, manufacturing leads adoption, reflecting the sector’s focus on productivity and quality improvement. The automotive and electronics industries are early adopters, using it to automate assembly, inspection, and packaging. The healthcare sector is expanding its use of robot operating systems for diagnostics, rehabilitation, and hospital logistics. Retail and agriculture are emerging end-users, leveraging robotics to enhance customer experience and optimize supply chains. The market’s broad end-use base supports sustained growth and innovation.
- For instance, BMW is testing the Figure 02 humanoid robot, which weighs 70 kg and can lift 20 kg, in its Spartanburg automotive plant.
By Robot Type Segment:
By Robot Type, articulated robots dominate the market due to their flexibility and wide usage in industrial settings. Service robots are gaining market share, providing solutions for cleaning, delivery, and healthcare support. Collaborative robots, or cobots, are seeing rapid adoption, enabling safe human-robot interaction in shared workspaces. It supports the development of both traditional and next-generation robot types, ensuring relevance across multiple industries. The diversity of robot types underscores the market’s capacity to address evolving technological and business requirements.
Segmentations:
By Application- Industrial Robots
- Service Robots
- Mobile Robots
- Autonomous Vehicles
- Humanoid Robots
- Medical Robots
- Automotive
- Healthcare
- Electronics
- Food & Beverage
- Logistics & Transportation
- Aerospace & Defense
- Education & Research
- Agriculture
- Articulated Robots
- SCARA Robots
- Cartesian Robots
- Collaborative Robots (Cobots)
- Spherical Robots
- Parallel Robots
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis:
North America Leads Market Growth with Strong Industrial and Research Ecosystem
North America holds 38% share of the Robot Operating System Market, reflecting its leadership in automation and robotics innovation. The United States drives regional dominance, supported by a robust industrial base, advanced research institutions, and significant investments in automation technologies. It benefits from strong government support for innovation, as well as partnerships between academia and industry. High demand for automation in manufacturing, logistics, and healthcare sectors continues to propel market expansion. Organizations in North America prioritize integration of advanced robotics to enhance productivity and address labor shortages. The region’s focus on digital transformation and smart manufacturing reinforces its leadership position.
Europe Advances Adoption through Regulatory Support and Industry Collaboration
Europe accounts for 28% share of the Robot Operating System Market, supported by regulatory frameworks and collaborative industry initiatives. Countries such as Germany, France, and the United Kingdom invest heavily in robotics research and development, aiming to strengthen their positions in global value chains. It benefits from strong cross-sector partnerships and public-private investments that accelerate technology adoption. European manufacturers increasingly deploy robot operating systems to improve operational efficiency and meet sustainability goals. The region’s emphasis on standardization and interoperability fosters a competitive and innovative market environment. Strong regulatory support and workforce development initiatives further enhance Europe’s market potential.
Asia Pacific Emerges as a High-Growth Region with Expanding Industrial Base
Asia Pacific commands 24% share of the Robot Operating System Market, driven by a rapidly expanding manufacturing sector and rising demand for automation. Countries such as China, Japan, and South Korea lead adoption, supported by government initiatives and substantial investments in smart factories. It enables local manufacturers to enhance productivity, reduce costs, and maintain global competitiveness. The region’s growing focus on robotics in healthcare, logistics, and agriculture creates new opportunities for market players. Increasing R&D activities and a large pool of skilled engineers drive continuous innovation. Asia Pacific’s dynamic economic landscape positions it as a key contributor to the global market’s future growth.
Key Player Analysis:
- iRobot Corporation
- Denso
- Microsoft
- Clearpath Robots
- Universal Robotics
- FANUC
- KUKA AG
- ABB
- Omron Corporation
- Yaskawa Electric Corporation
Competitive Analysis:
The Robot Operating System Market features a competitive landscape shaped by innovation, strategic partnerships, and continuous software enhancement. Key players focus on expanding their ecosystem of packages, simulation tools, and middleware capabilities to support a wide range of robotic applications. Companies actively collaborate with academic institutions and industry partners to drive adoption and refine system compatibility. The open-source nature of ROS encourages contributions from both established enterprises and emerging developers, fostering rapid evolution and diverse use cases. It benefits from increasing demand across sectors such as automotive, healthcare, logistics, and manufacturing. Major vendors prioritize real-time performance, cybersecurity, and integration support to meet industrial requirements. Competition intensifies with the rollout of ROS 2, which introduces robust improvements in scalability and safety. Regional players are also strengthening their presence by customizing ROS solutions for local industries and regulatory environments. This dynamic ecosystem continues to fuel technological progress and market expansion.
Recent Developments:
- In June 2025, Universal Robots launched UR Studio, an advanced online simulation tool built on PolyScope X, at Automatica 2025.
- In July 2025, ABB announced the launch of three new robot families—Lite+, PoWa, and IRB1200—specifically designed for the Chinese market to target mid-sized customers.
- In June 2025, KUKA AG launched an AI assistant designed to simplify robot programming, showcased at Automatica 2025.
Market Concentration & Characteristics:
The Robot Operating System Market exhibits moderate concentration with a mix of established players and emerging contributors driving innovation. It is characterized by an open-source foundation, which promotes collaboration, flexibility, and rapid customization. Key vendors focus on enhancing modularity, middleware integration, and support for real-time systems. The market supports a broad spectrum of applications, from industrial automation to healthcare and autonomous vehicles. It maintains strong ties with research institutions, fueling continuous development and academic involvement. The adoption of ROS 2 marks a shift toward improved reliability and security for commercial deployments. Demand for scalable, interoperable solutions continues to shape market behavior, with companies prioritizing compatibility across hardware platforms. Regional differentiation, driven by industrial maturity and regulatory focus, further influences the competitive dynamics and product offerings within this evolving landscape.
Report Coverage:
The research report offers an in-depth analysis based on Application, End-Use, Robot Type and Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- Industry adapts ROS 2 features to support real-time operations, enhancing adoption in safety-critical sectors.
- Companies embed AI modules within ROS platforms to enable smarter and more autonomous robotic applications.
- Developers integrate edge computing with ROS to reduce latency and improve real-time decision-making in on-site operations.
- Research institutions expand ROS-based curricula, producing a skilled workforce ready for commercial innovation.
- Vendors collaborate across industries to create standardized ROS packages targeting specific verticals like healthcare and logistics.
- Robotics-as-a-Service providers incorporate ROS to accelerate deployment timelines and delivery models globally.
- Regional players customize ROS solutions to comply with local regulations and meet market-specific requirements.
- Open-source community advances support for novel hardware architectures, boosting compatibility and developer engagement.
- Emphasis on cybersecurity leads to integration of robust encryption, authentication, and secure communication protocols within ROS.
- ROS ecosystems evolve toward cloud-native and digital twin integration, enabling scalable simulation and remote management.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Robot Operating System Market?
What factors are driving the growth of the Robot Operating System Market?
What are the key segments within the Robot Operating System Market?
What are some challenges faced by the Robot Operating System Market?
Who are the major players in the Robot Operating System Market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Robot Operating System Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Robot Operating System Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 643 million → 2032: USD 1,661.5 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Robot Operating System Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Robot Operating System Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Robot Operating System Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Robot Operating System Market Drivers
- 3.3 Robot Operating System Market Restraints & Challenges
- 3.4 Robot Operating System Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Robot Operating System Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Robot Operating System Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Robot Operating System category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Robot Operating System Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Robot Operating System Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Robot Operating System market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Robot Operating System Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Robot Operating System Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Robot Operating System Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Robot Operating System (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Robot Operating System Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Robot Operating System Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Robot Operating System Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Robot Operating System Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Robot Operating System Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Robot Operating System Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Robot Operating System Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Robot Operating System Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Robot Operating System Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
