
Market Overview:
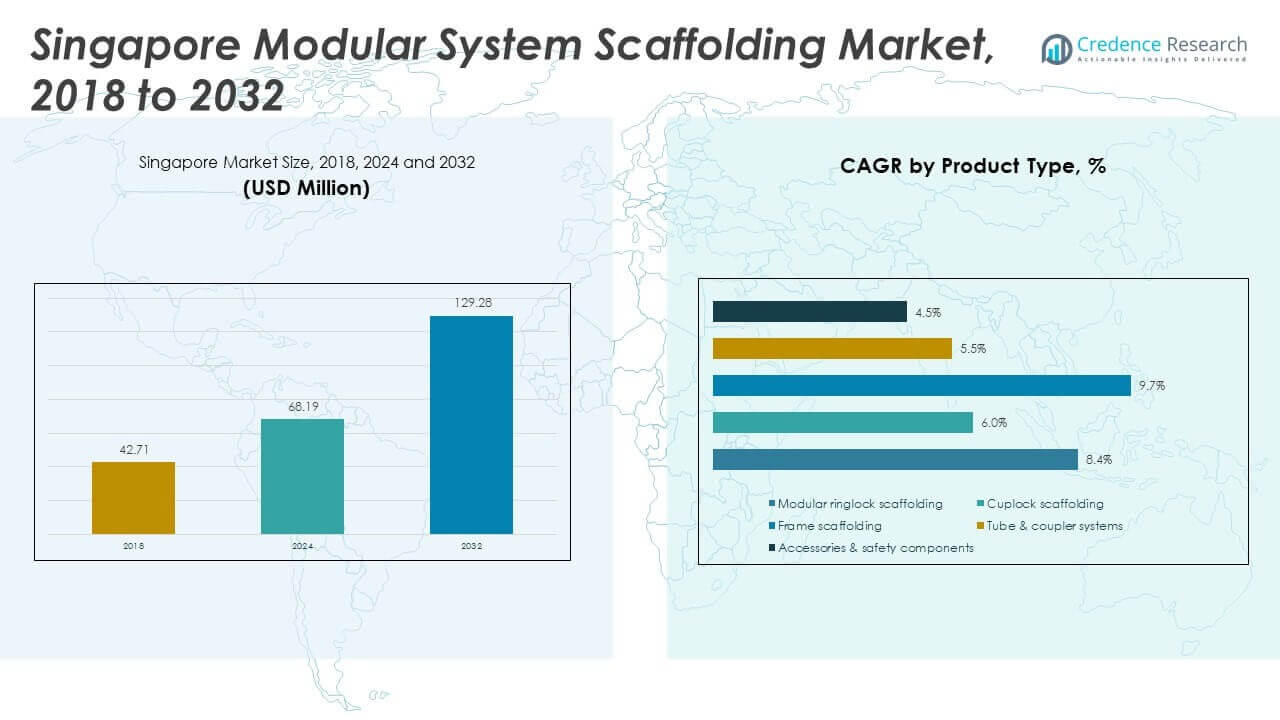
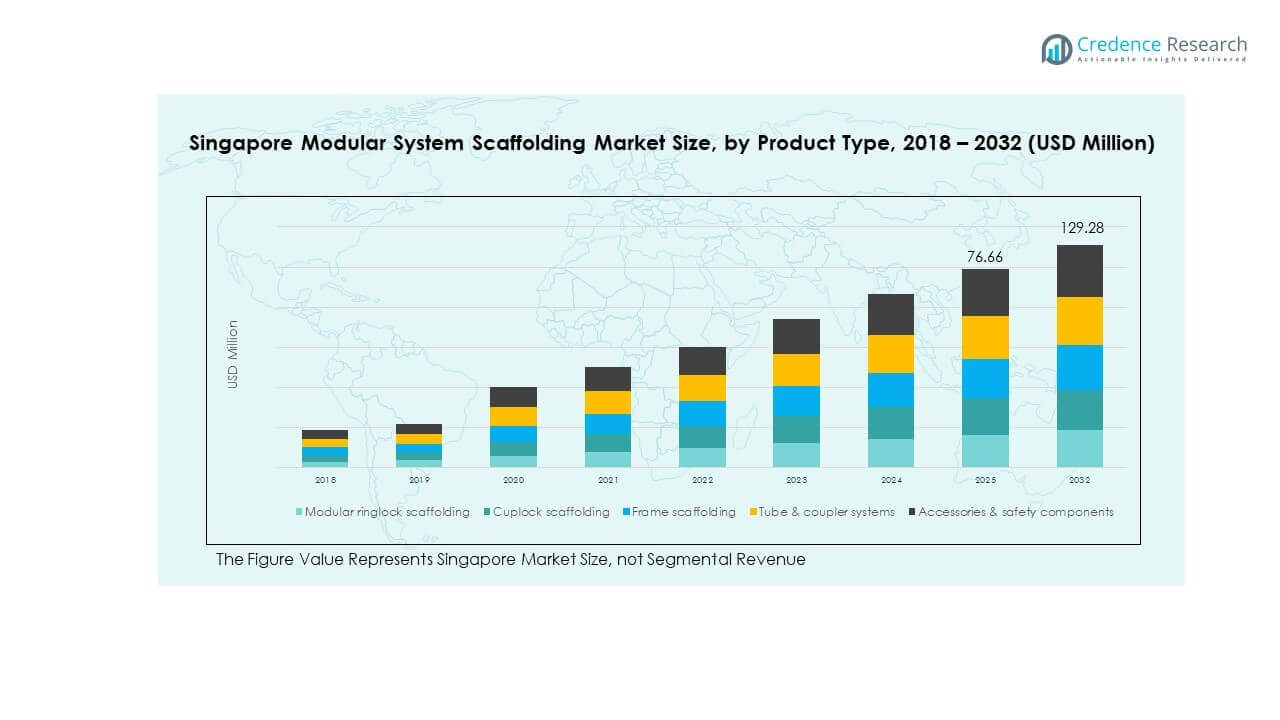
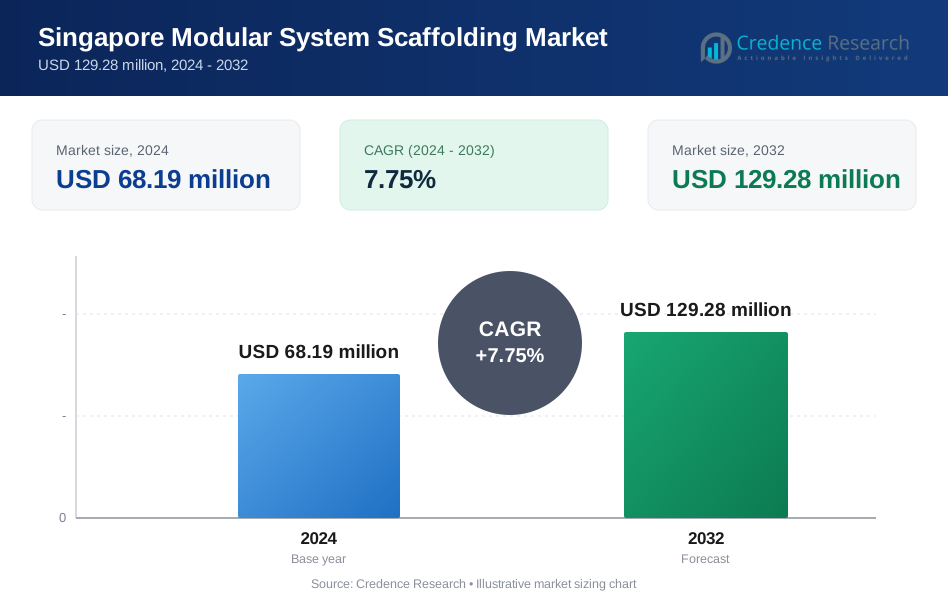
The Singapore Modular System Scaffolding Market size was valued at USD 42.71 million in 2018 to USD 68.19 million in 2024 and is anticipated to reach USD 129.28 million by 2032, at a CAGR of 7.75% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Singapore Modular System Scaffolding Market Size 2024 | USD 68.19 million |
| Singapore Modular System Scaffolding Market , CAGR | 7.75% |
| Singapore Modular System Scaffolding Market Size 2032 | USD 129.28 million |
Growth in the market is driven by strict safety regulations, rising demand for high-rise construction, and a shift toward productivity-enhancing construction technologies. Modular systems offer faster assembly, better load management, and compliance with safety standards, making them a preferred choice over traditional scaffolding. Government-led public infrastructure projects and retrofitting of older buildings continue to support strong demand. Rental-based models allow small and mid-sized contractors to access premium systems. Increasing urban redevelopment and industrial maintenance work further boost market expansion.
The Central Region leads scaffold demand due to dense commercial activity and ongoing infrastructure upgrades. It dominates due to high project volume and tight compliance norms. The West Region follows, supported by industrial zones, marine projects, and shipyards that need durable and corrosion-resistant systems. Northern and eastern areas contribute through public housing redevelopment and school facility upgrades. These zones show growing interest in rental scaffolding for short-term or project-based applications. Local demand patterns reflect Singapore’s tight space constraints, high safety expectations, and preference for reusable systems.
Market Insights
- The Singapore Modular System Scaffolding Market grew from USD 42.71 million in 2018 to USD 68.19 million in 2024 and is projected to reach USD 129.28 million by 2032, registering a CAGR of 7.75% during the forecast period.
- The Central Region leads with a 52% market share, driven by dense high-rise construction and institutional developments. The West Region follows with 28%, supported by shipyards and industrial activity, while North, East, and Northeast regions collectively contribute 20% through public housing and school retrofits.
- Among all regions, the West Region is projected to grow fastest due to sustained marine maintenance and long-cycle industrial scaffold leasing, enabled by specialized demand for corrosion-resistant systems.
- By product type, modular ringlock scaffolding holds the largest share and grows at a CAGR of 9.7%, driven by strong adoption in vertical construction and complex façades. Accessories and safety components follow with 8.4%, reflecting rising compliance demands.
- Tube and coupler systems are declining in preference, with a CAGR of 4.5%, while frame scaffolding and cuplock scaffolding maintain moderate growth at 6.0% and 5.5%, respectively, serving niche and mid-scale construction needs.
Market Drivers
Strict Regulatory Enforcement Promotes Safety-Oriented Scaffold Adoption Across All Project Scales
Singapore’s construction codes demand full compliance with safety and fall-protection standards. The regulatory pressure forces contractors to adopt system scaffolding with better load distribution and anchoring design. It supports faster inspections and consistent modular alignment, reducing risks of human error. The Singapore Modular System Scaffolding Market benefits directly from government audits and penalties linked to scaffold violations. Engineering firms prefer modular systems to pass site inspections and meet ISO standards. Workplace Safety and Health (WSH) initiatives further prioritize certified modular scaffold use. Public infrastructure and government housing projects consistently specify system scaffolds in contracts. Contractors choose modularity to shorten assembly time and comply with mandatory safety guidelines.
- For instance, Layher Allround Scaffolding systems are widely recognized for reducing assembly and dismantling times by over 30% in complex projects, supported by efficient modular design and globally certified performance standards that align with Singapore’s BCA compliance requirements.
Accelerated Infrastructure And Public Sector Construction Drives Consistent Product Demand
Singapore's investment in mass rapid transit expansions, airport upgrades, and health infrastructure fuels steady scaffold demand. It plays a critical role in supporting safe vertical and facade work on public sector projects. Modular systems are preferred in dense construction zones requiring minimal obstruction and fast turnaround. The Singapore Modular System Scaffolding Market gains momentum through public housing redevelopment and industrial expansion in Jurong and Tuas. Tender requirements increasingly favor vendors offering rapid-installation, reusable systems. Engineering consultants recommend modular scaffolds to meet urban timeline constraints. Contractors adopt modular designs to reduce project delays and cut overtime labor. Public-private partnerships support scaffold leasing for long-cycle infrastructure programs.
Contractor Shift Toward Productivity-Linked Construction Tools Boosts System Usage
The government’s productivity roadmap encourages companies to modernize tools that reduce site congestion. Modular scaffolding reduces reliance on manual setup and delivers higher consistency across elevation works. It contributes to Singapore’s push for Design for Manufacturing and Assembly (DfMA) compliance. Developers favor these systems in tender evaluations for BCA score optimization. The Singapore Modular System Scaffolding Market grows with adoption across structural, MEP, and finishing works. Contractors use system scaffolds to limit downtime during site transitions and tower lift jumps. Prefabricated modular layouts align with crane logistics and project phasing needs. Industry training programs promote modular scaffold certification to close skill gaps.
- For instance, Doka Xlife formwork systems are engineered for high reuse rates often exceeding 500 cycles under optimal conditions and support DfMA-aligned construction through reduced erection times and consistent performance in structural works, in line with Singapore’s regulatory focus.
Increased High-Rise And Retrofit Activity Requires Customizable And Non-Intrusive Scaffold Solutions
Singapore’s vertical construction trends create pressure for scalable scaffolding in tight access zones. Modular systems meet this demand by offering multi-angle configurations and rapid height adjustment. It reduces risks during maintenance of occupied buildings and supports work under limited site windows. The Singapore Modular System Scaffolding Market sees traction from retrofits in commercial and institutional buildings. Lightweight systems avoid structural overloads during exterior repair or recladding. Retail projects also use modular scaffold to minimize disruption in active premises. Event infrastructure setups deploy similar systems due to speed and reuse value. Fire-rated and corrosion-resistant materials improve scaffold reliability for long-duration use.
Market Trends
Integration Of Digital Site Monitoring With Scaffold Tracking Enhances Safety Compliance
Technology integration into scaffolding operations is becoming standard in complex projects. Site managers now use RFID and IoT-based solutions to track scaffold erection progress and asset movement. It enables real-time alerts on missing braces or overloading conditions. The Singapore Modular System Scaffolding Market supports integration with BIM and digital twin platforms for pre-site modeling. This improves scaffold planning during early project stages and reduces on-site revisions. Digital dashboards allow better scaffold inventory control across multiple jobsites. Government-led smart construction pilots encourage scaffold digitization. Safety records are improving due to automated checklists and system tagging during setup and dismantling.
Rental Companies Expand Inventory Of Modular Scaffold Systems For Flexible Leasing
Rental firms play a growing role in supplying system scaffolds to small and mid-size contractors. They invest in high-rotation modules that allow fast leasing across different project types. The Singapore Modular System Scaffolding Market benefits from rental models that include maintenance and transport services. Flexible contracts reduce ownership costs and enable scalable access for contractors with intermittent needs. Leasing supports peak project phases without large capital expenditure. Vendors offer digital portals for online bookings and delivery scheduling. System compatibility across brands supports mixed-use deployments. The rental trend creates a secondary market for refurbished and inspected scaffold stock.
- For instance, Aedge Technologies Pte Ltd in Singapore offers rental solutions for system scaffolds such as Cuplok and Ringlock, supporting diverse urban construction projects with modular setups designed for rapid deployment and operational efficiency.
Eco-Friendly Scaffold Materials And Lifecycle Reusability Gain Market Priority
Environmental sustainability is influencing material selection in scaffold systems. Clients prefer aluminum and coated steel for longer reuse cycles and corrosion resistance. It enables scaffold components to be reused across projects with minimal maintenance. The Singapore Modular System Scaffolding Market aligns with green procurement policies and LEED project standards. Waste reduction during setup and teardown appeals to developers targeting BCA Green Mark certification. Recycled material content and traceability features improve compliance with ESG benchmarks. Scaffold firms offer take-back programs for end-of-life components. Project audits now factor lifecycle impact in scaffold vendor selection.
- For instance, HAKI Universal system scaffolds, known for their reusable steel components and corrosion-resistant coatings, support green building goals by minimizing waste in high-rise applications. In Singapore, firms offering modular scaffold rentals increasingly align with such sustainable systems to meet project and regulatory requirements.
Compact Storage And Modular Packaging Support Urban Logistics Constraints
Urban project sites in Singapore face limited laydown areas for scaffold storage. Vendors address this by offering flat-pack, stackable modules and pre-configured bundles. It supports faster crane loading and better material tracking. The Singapore Modular System Scaffolding Market aligns its product formats with containerized delivery practices. Compact scaffold pallets reduce handling time and improve last-mile logistics. Logistic providers optimize delivery schedules to align with short site access windows. Scaffold modules arrive labeled by bay or tower floor for speedier deployment. Return packaging also enhances reverse logistics efficiency after scaffold dismantling.
Market Challenges Analysis
High Initial Investment And Transition Costs Limit Wider Adoption In Smaller Projects
Small contractors and subcontractors face difficulty absorbing the upfront cost of modular scaffold systems. Traditional tube and coupler scaffolding remains cheaper for minor repairs and fit-outs. The Singapore Modular System Scaffolding Market faces barriers when users compare capital cost instead of lifecycle value. Smaller firms struggle to retrain workers or acquire modular certifications. They hesitate to switch systems due to short project durations or limited asset reuse potential. Financing options for scaffold modernization remain limited in the SME segment. Rental models address some issues but do not eliminate deployment learning curves. Manual labor reliance continues in informal sectors despite safety concerns.
Fragmented Contractor Base And Varied Project Scales Complicate Scaffold Standardization
Singapore’s market has a broad mix of building owners, developers, and specialist contractors with varying scaffold needs. Projects range from temporary installations to long-term façade access. The Singapore Modular System Scaffolding Market must navigate inconsistent specifications and deployment conditions. Lack of common tender language for modular systems leads to variable adoption. Scaffold system providers struggle with customization for niche sectors like shipyards or heritage buildings. Standardizing across sectors requires regulatory incentives and clearer scaffold performance benchmarks. Fragmented demand slows economies of scale for local manufacturers. Safety compliance remains uneven across project types and client expectations.
Market Opportunities
In Public Sector Retrofitting And Facilities Upgrades Create Recurring Demand
Government-funded retrofits in schools, transport stations, and hospitals open steady opportunities for modular scaffold use. These projects require minimal disruption, fast setup, and limited access interference. The Singapore Modular System Scaffolding Market gains from mandates around energy upgrades and facade renewal programs. Public agencies prioritize system scaffolds with compliance certifications and lower lifecycle costs. These opportunities favor vendors with local servicing and on-call support teams. Redevelopment zones generate multi-phase demand from early demolition to final fit-out stages. Urban greening and solar integration projects also require short-term scaffold installation.
Growth Potential In Maritime, Industrial, And Event Infrastructure Segments
Sectors like ship repair, manufacturing, and entertainment increasingly adopt modular scaffolds for short-cycle tasks. These industries demand safe, mobile, and adjustable systems. The Singapore Modular System Scaffolding Market finds untapped potential in warehouses, offshore platforms, and convention setups. Event venues use modular setups for lighting rigs, camera towers, and stages. Industrial zones adopt scaffolds for pipework access and ceiling repairs. Providers offering modular scaffold kits with rapid assembly training can scale in these sectors. Specialized modules for circular tanks or complex geometries offer new product development paths.
Market Segmentation Analysis
By Product Type
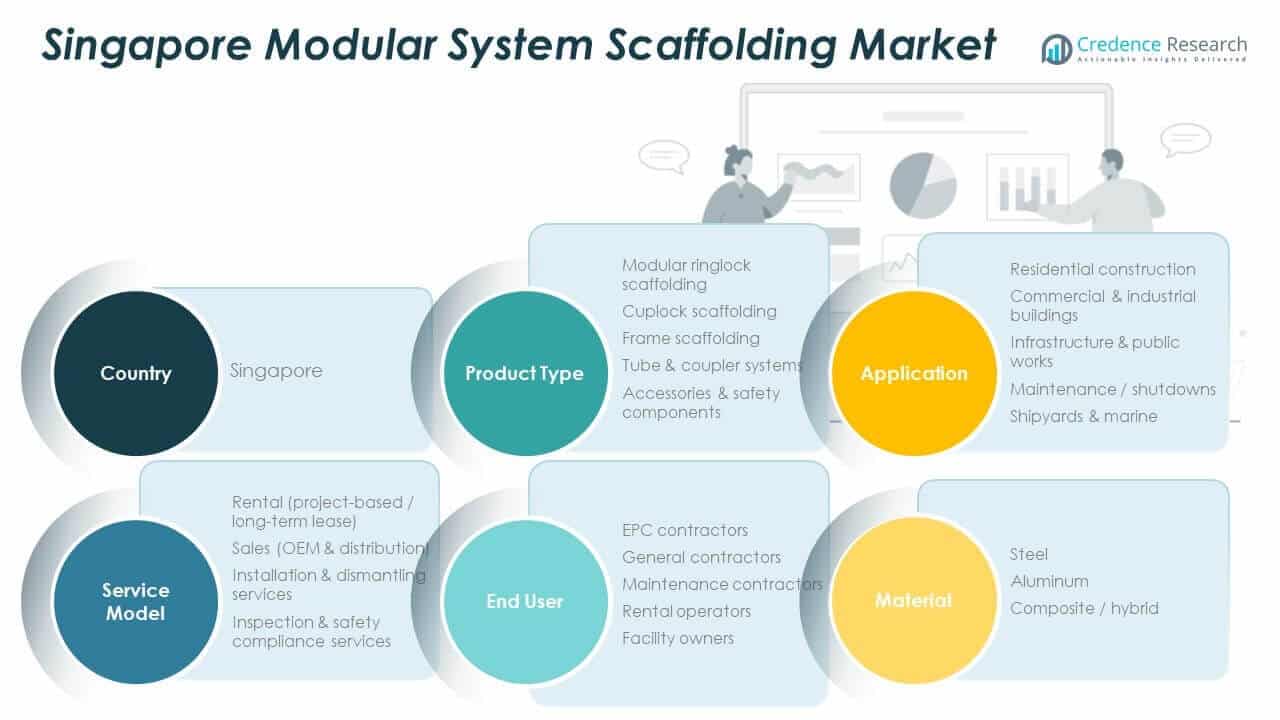
Modular ringlock scaffolding holds a dominant position due to its fast assembly, strength, and flexibility in high-rise and complex structures. Cuplock scaffolding remains preferred for repetitive operations and large-scale facades. Frame scaffolding sees moderate use in low-rise or light commercial projects. Tube and coupler systems are slowly phasing out but still find relevance in irregular structures or specialized retrofits. Accessories and safety components such as guardrails, connectors, and toe boards enhance operational safety and compliance. The Singapore Modular System Scaffolding Market relies heavily on product adaptability to project scale and complexity.
- For instance, PERI’s Cuplok scaffolding system has been deployed in high-rise projects like Singapore’s 52-story Tanjong Pagar Centre, supporting extensive facade access with thousands of modular units.
By Application
Commercial and industrial buildings drive steady scaffold demand due to strict safety requirements and complex geometries. Residential construction follows closely with consistent usage in both new and retrofit housing segments. Infrastructure and public works generate large-volume scaffold needs, especially in transport, healthcare, and utility upgrades. Maintenance and shutdowns require lightweight, quick-install systems for limited-duration jobs. Shipyards and marine settings use corrosion-resistant scaffold materials for hull and dock-side access. The Singapore Modular System Scaffolding Market caters to highly diversified application zones with different safety and mobility demands.
By Service Model
Rental, both project-based and long-term, leads the segment due to capital cost avoidance and scalable demand. Sales through OEMs and distributors cater to large EPCs and long-term contractors. Installation and dismantling services ensure safety compliance and skill availability for complex builds. Inspection and safety services form a growing value-add segment, driven by audits and certification requirements. The Singapore Modular System Scaffolding Market aligns its services with client flexibility and regulatory needs.
- For instance, PERI supplied large volumes of ringlock scaffolding to Obayashi Corporation for the construction of Singapore’s National Heritage Board headquarters, completing logistics within a tight three-week window to meet project delivery schedules.
By End User
General and EPC contractors represent key users, requiring large, customizable systems across multiple sites. Maintenance contractors use modular units for short timelines and repeat works. Rental operators support smaller contractors with fast-deploy units and logistical support. Facility owners engage scaffolding for periodic retrofits or façade access. The Singapore Modular System Scaffolding Market evolves with end-user preferences toward outsourced, tech-integrated solutions.
By Material
Steel remains the preferred material due to its durability and load-bearing properties. Aluminum scaffolds gain popularity for lightweight and corrosion-resistant applications in interiors or marine jobs. Composite and hybrid materials emerge for their strength-to-weight ratio, improving ease of transport and setup. The Singapore Modular System Scaffolding Market reflects a clear material shift driven by jobsite safety, lifecycle cost, and ESG goals.
By Compliance and Certification
MOM and WSH standards form the regulatory baseline, ensuring consistent enforcement across sectors. ISO certifications reflect vendor credibility and product consistency. Structural testing approvals validate scaffold use under complex loading and environmental conditions. The Singapore Modular System Scaffolding Market integrates these certifications into procurement, training, and project audits.
Segmentation
By Product Type
- Modular Ringlock Scaffolding
- Cuplock Scaffolding
- Frame Scaffolding
- Tube and Coupler Systems
- Accessories and Safety Components
By Application
- Residential Construction
- Commercial and Industrial Buildings
- Infrastructure and Public Works
- Maintenance and Shutdowns
- Shipyards and Marine
By Service Model
- Rental (Project-Based and Long-Term Lease)
- Sales (OEM and Distribution)
- Installation and Dismantling Services
- Inspection and Safety Compliance Services
By End User
- EPC Contractors
- General Contractors
- Maintenance Contractors
- Rental Operators
- Facility Owners
By Material
- Steel
- Aluminum
- Composite and Hybrid
By Compliance and Certification
- MOM and WSH Standards
- ISO Certifications
- Structural Testing Approvals
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis
Central Region – 52% Market Share
The Central Region accounts for 52% of the Singapore Modular System Scaffolding Market, led by large-scale commercial, mixed-use, and institutional projects. It includes core districts such as Orchard, Downtown Core, and Novena, where high-rise developments and retrofitting projects drive sustained scaffold usage. Developers and contractors in this region prefer modular systems to meet tight timelines, strict access limits, and aesthetic compliance. Demand from MRT station upgrades and vertical extensions of hospitals contributes to steady volume. Scaffold rental operators concentrate their inventory in this area to serve multiple job sites with fast turnaround. The Central Region remains the largest revenue contributor due to its project density and regulatory oversight.
West Region – 28% Market Share
The West Region holds 28% of the market, supported by industrial estates, manufacturing zones, and infrastructure works in Jurong, Tuas, and Clementi. Projects involving petrochemical plants, logistics centers, and shipyards use modular scaffolds for maintenance, shutdowns, and safety access. The presence of ports and marine services creates specialized demand for corrosion-resistant and heavy-duty systems. It shows higher uptake of aluminum and hybrid scaffolding, aligning with the region’s focus on industrial safety standards. The Singapore Modular System Scaffolding Market benefits here from long-term contracts and bundled service models. System leasing remains a preferred route due to project complexity and turnaround pressure.
North, East, and Northeast Regions – 20% Market Share Combined
These regions together contribute 20% of the market, mainly through public housing, educational upgrades, and small commercial developments. Scaffold demand here is fragmented but consistent, driven by redevelopment projects under the Housing & Development Board (HDB). The use of modular ringlock systems supports fast cycling across multiple blocks. Contractors working in Sengkang, Tampines, and Yishun adopt scaffolding for MEP retrofits, repainting, and solar panel integration. It shows rising interest in system leasing for short-term deployment. Market growth here is linked to public infrastructure and facility upgrades under long-term planning initiatives.
Key Player Analysis
- Tiong Seng Contractors / TS Group
- United U-LI / U-LITE
- PERI Singapore
- Layher Asia Pte Ltd
- Yew Chuan Scaffolding & Construction Pte Ltd
Competitive Analysis
The Singapore Modular System Scaffolding Market features a concentrated landscape with a mix of international brands, regional suppliers, and local service firms. Leading players include PERI, Layher, and ULMA, which offer modular systems with tested certifications and strong brand equity. Local providers such as Tuff Scaffolding, Scaf-Link, and Yong Ngai Engineering compete on service speed, rental flexibility, and installation quality. It favors vendors with strong safety credentials, WSH compliance, and ability to support fast site transitions. Digital integration, project-based customization, and on-demand logistics have become key differentiators. Market participants also invest in training and product upgrades to align with Singapore’s productivity and safety goals. The competitive space continues to evolve toward bundled service models, lifecycle support, and rapid deployment capabilities. The Singapore Modular System Scaffolding Market rewards firms that balance price efficiency with reliability and compliance assurance.
Recent Developments
- In August 2025, Boxabl announced a $3.5 billion merger to go public via SPAC boosting modular construction capabilities that could influence scaffolding-integrated systems.
Report Coverage
The research report offers an in-depth analysis based on Product Type, Application, Service Model, End User, Material and Compliance /Certification. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The market will benefit from sustained public infrastructure upgrades tied to transport, healthcare, and urban redevelopment programs across dense city zones.
- Safety-driven procurement policies will continue to favor certified modular systems over traditional tube-based scaffolding formats.
- High-rise construction and façade retrofitting activity will strengthen demand for flexible, fast-assembly scaffold configurations.
- Rental-led business models will expand as contractors prioritize cost control, asset flexibility, and short deployment cycles.
- Digital site planning and scaffold tracking tools will gain acceptance within large commercial and institutional projects.
- Lightweight and corrosion-resistant materials will see higher adoption in marine, industrial, and maintenance applications.
- Workforce skill shortages will push greater reliance on turnkey installation and dismantling service providers.
- Sustainability goals will influence material selection, reuse cycles, and lifecycle-focused procurement decisions.
- Compact storage and logistics-efficient scaffold designs will support operations in space-constrained urban sites.
- Strong regulatory enforcement will keep compliance-driven innovation central to competitive differentiation strategies.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Strict Regulatory Enforcement and Safety Standards
Singapore’s rigorous construction codes and active government audits require full compliance with safety and fall-protection standards, driving contractors to adopt modular system scaffolding for better load management, faster inspections, and reduced risk of human error.
Accelerated Public Infrastructure and Urban Redevelopment
Ongoing investments in mass rapid transit, healthcare, and public housing redevelopment fuel consistent demand for modular scaffolding, as these projects require fast, safe, and reusable systems to meet tight urban timelines and minimize site disruption.
Shift Toward Productivity-Enhancing Construction Technologies
Government productivity roadmaps and industry incentives encourage the adoption of modular scaffolding, which reduces manual labor, speeds up assembly, and aligns with Design for Manufacturing and Assembly (DfMA) principles, supporting faster project delivery and compliance.
Growth in High-Rise Construction and Retrofit Activity
The prevalence of high-rise and retrofit projects in Singapore’s dense urban environment necessitates customizable, non-intrusive scaffolding solutions that can be rapidly deployed and adjusted for complex façades and tight access zones.
Expansion of Rental-Based Service Models
Rental models lower the capital barrier for small and mid-sized contractors, enabling broader access to premium modular systems and supporting flexible, project-based deployment, which is increasingly favored in Singapore’s dynamic construction landscape.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Singapore Modular System Scaffolding Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Singapore Modular System Scaffolding Market projected to grow between 2024 and 2032?
Which Singapore Modular System Scaffolding Market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Singapore Modular System Scaffolding Market?
Who are the leading companies in the Singapore Modular System Scaffolding Market?
Which region commanded the largest share of the Singapore Modular System Scaffolding Market in 2024?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Material
- 1.2.1 Steel
- 1.2.2 Aluminum
- 1.2.3 Composite and Hybrid
- 1.3 By Application
- 1.3.1 Residential Construction
- 1.3.2 Commercial and Industrial Buildings
- 1.3.3 Infrastructure and Public Works
- 1.3.4 Maintenance and Shutdowns
- 1.3.5 Shipyards and Marine
- 1.4 By Product Type
- 1.4.1 Modular Ringlock Scaffolding
- 1.4.2 Cuplock Scaffolding
- 1.4.3 Frame Scaffolding
- 1.4.4 Tube and Coupler Systems
- 1.4.5 Accessories and Safety Components
- 1.5 By Service Model
- 1.5.1 Rental (Project-Based and Long-Term Lease)
- 1.5.2 Sales (OEM and Distribution)
- 1.5.3 Installation and Dismantling Services
- 1.5.4 Inspection and Safety Compliance Services
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 68.19 million → 2032: USD 129.28 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Singapore Modular System Scaffolding Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Singapore Modular System Scaffolding Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Singapore Modular System Scaffolding Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Singapore Modular System Scaffolding Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Singapore Modular System Scaffolding Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Singapore Modular System Scaffolding Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Singapore Modular System Scaffolding Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Singapore Modular System Scaffolding Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 68.19 million → 2032: USD 129.28 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Singapore Modular System Scaffolding Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Material - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Steel
- 12.3.7.2 Aluminum
- 12.3.7.3 Composite and Hybrid
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Application - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Residential Construction
- 12.4.7.2 Commercial and Industrial Buildings
- 12.4.7.3 Infrastructure and Public Works
- 12.4.7.4 Maintenance and Shutdowns
- 12.4.7.5 Shipyards and Marine
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Product Type - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Modular Ringlock Scaffolding
- 12.5.7.2 Cuplock Scaffolding
- 12.5.7.3 Frame Scaffolding
- 12.5.7.4 Tube and Coupler Systems
- 12.5.7.5 Accessories and Safety Components
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 By Service Model - Market Size and Forecast, 2024-2032
- 12.6.1 Segment Definition and Scope
- 12.6.2 Historical Market Size
- 12.6.3 Revenue Forecast, 2024-2032
- 12.6.4 Volume Forecast, 2024-2032
- 12.6.5 Base-Year Market Share, 2024
- 12.6.6 Segment CAGR and Growth Drivers
- 12.6.7 Subsegment Market Size and Forecast
- 12.6.7.1 Rental (Project-Based and Long-Term Lease)
- 12.6.7.2 Sales (OEM and Distribution)
- 12.6.7.3 Installation and Dismantling Services
- 12.6.7.4 Inspection and Safety Compliance Services
- 12.6.8 Subsegment Pricing and Adoption Trends
- 12.6.9 Leading Suppliers and Competition
- 12.6.10 Regional Demand and Opportunities
- 12.7 Segment Growth Comparison
- 12.8 Segment Attractiveness and Priority Matrix
Chapter 13 Singapore Modular System Scaffolding End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Singapore Modular System Scaffolding Geographic Market Outlook, 2024-2032
- 14.1 Domestic Market Distribution and Demand Clusters
- 14.2 State- or Province-Wise Market Size and Forecast, 2024-2032
- 14.3 City and Metropolitan Market Outlook
- 14.4 Industrial, Manufacturing and Commercial Clusters
- 14.5 Geographic Concentration of Key End Users
- 14.6 Local Pricing and Purchasing Differences
- 14.7 Domestic Production Facilities and Capacity Map
- 14.8 Local Infrastructure and Project Pipeline
- 14.9 State-Level Policy and Incentive Differences
- 14.10 Subnational Investment Hotspots and Opportunities
- 14.11 Distribution and Logistics Networks
- 14.12 Domestic Competitive Footprint
Chapter 15 Singapore Modular System Scaffolding Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Singapore Modular System Scaffolding Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 PERI Singapore
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Layher Asia Pte Ltd
- 18.4 Tiong Seng Contractors / TS Group
- 18.5 United U-LI / U-LITE
- 18.6 Yew Chuan Scaffolding & Construction Pte Ltd
- 18.7 ULMA Construction
- 18.8 Tuff Scaffolding
- 18.9 Scaf-Link Engineering
- 18.10 Yong Ngai Engineering
- 18.11 Aedge Technologies Pte Ltd
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

