
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Singapore Data Center Containment Market Size 2024 | USD 12.94 million |
| Singapore Data Center Containment Market, CAGR | 11.99% |
| Singapore Data Center Containment Market Size 2032 | USD 32.02 million |
Market Overview
The Singapore Data Center Containment Market is projected to grow from USD 12.94 million in 2024 to an estimated USD 32.02 million by 2032, reflecting a compound annual growth rate (CAGR) of 11.99% from 2025 to 2032. This growth is driven by the increasing demand for efficient cooling solutions in data centers, as organizations strive to manage rising data processing requirements while minimizing energy consumption.
Key market drivers include the rapid expansion of digital services, the proliferation of data-intensive applications, and the need for effective thermal management in data centers. Trends such as the adoption of modular containment systems and the integration of advanced cooling technologies are further propelling market growth.
Geographically, Singapore serves as a strategic hub for data center operations in the Asia-Pacific region, attracting significant investments from global and regional players. Key market participants include companies like Vertiv Holdings Co., Schneider Electric SE, and STULZ GmbH, which offer innovative containment solutions to meet the evolving demands of data center operators.
Market Insights
- The Singapore Data Center Containment Market is projected to grow from USD 12.94 million in 2024 to USD 32.02 million by 2032, with a CAGR of 11.99% from 2025 to 2032.
- The increasing need for efficient cooling due to rising data processing and digital services is a major driver of market growth.
- Data center operators are increasingly adopting containment solutions to reduce energy consumption and improve cooling efficiency, responding to environmental and cost concerns.
- Singapore’s government policies promoting sustainable data center operations and energy-efficient technologies are fueling market growth.
- Integration of modular containment systems and advanced cooling technologies are helping data centers optimize space, reduce cooling costs, and scale efficiently.
- The high cost of real estate and space limitations in existing data centers present challenges in deploying new containment solutions.
- Singapore remains a strategic data center hub in the Asia-Pacific region, attracting both regional and global players to meet the increasing demand for data services
Market Drivers
Growing Demand for Data Centers and Cloud Services
The surge in data consumption driven by digital transformation initiatives is a significant driver for the growth of the data center containment market in Singapore. As businesses, governments, and consumers increasingly rely on cloud-based services and digital applications, the demand for efficient data storage and processing solutions has grown substantially. This has resulted in the expansion of data centers, which are essential for supporting the rapid growth of data traffic. Singapore, being a regional hub for digital infrastructure in Southeast Asia, has seen a steady increase in data center construction projects. For instance, major global players like Google, Microsoft, and Amazon Web Services have invested heavily in hyperscale and colocation facilities in Singapore, underlining the country's strategic importance as a data hub. The need to manage and optimize energy consumption in these data centers has led to an increased demand for containment solutions that improve cooling efficiency and ensure optimal performance. Data center operators are looking for ways to reduce operational costs while maintaining high levels of performance, driving the adoption of advanced containment systems.
Need for Efficient Cooling Solutions to Reduce Operational Costs
Data centers are energy-intensive, with cooling systems accounting for a significant portion of their overall energy consumption. As the power density of servers continues to increase, so does the demand for cooling solutions that can efficiently manage the heat generated by these systems. Singapore’s tropical climate, characterized by high temperatures and humidity, further exacerbates the need for effective cooling in data centers. Containment solutions, such as hot aisle and cold aisle containment systems, have become crucial in reducing energy consumption and preventing hot spots that can cause equipment failure. For instance, the Singapore government's initiatives, such as the Green Data Centre Roadmap, emphasize the importance of energy-efficient cooling technologies like liquid cooling to reduce energy consumption and carbon emissions. By isolating hot and cold air within the data center, containment systems can enhance the overall efficiency of cooling systems, leading to substantial energy savings. As data center operators seek ways to lower energy costs and meet sustainability targets, the adoption of containment solutions is expected to grow in the coming years.
Government Initiatives and Support for Green Data Centers
The Singaporean government has played a pivotal role in supporting the development of sustainable data centers by introducing policies and regulations that encourage energy efficiency and environmental sustainability. In line with the country's Smart Nation initiative, the government has made significant investments in building a robust digital infrastructure, positioning Singapore as a leading data center hub in the Asia-Pacific region. The government’s emphasis on energy-efficient technologies and green practices has fueled the demand for containment solutions that help data centers optimize their energy consumption. Furthermore, the Singapore Economic Development Board (EDB) has introduced incentives to encourage businesses to adopt green technologies in data centers, such as energy-efficient cooling and containment systems. These initiatives are driving data center operators to seek solutions that align with sustainability goals while reducing their carbon footprint.
Technological Advancements and Innovations in Containment Solutions
The rapid pace of technological innovation in data center infrastructure has been a major driver for the growth of the Singapore Data Center Containment Market. With the constant evolution of IT equipment, including servers, storage devices, and networking systems, the demands on data center cooling systems have become more complex. To address these challenges, containment solutions have evolved to incorporate advanced technologies such as modular designs, airflow management systems, and high-efficiency cooling technologies. These innovations enable data center operators to achieve better cooling performance, enhance scalability, and ensure operational reliability. The integration of Internet of Things (IoT) sensors and automation systems into containment solutions has also improved real-time monitoring and control of cooling systems, further enhancing energy efficiency. As data center operators in Singapore look for ways to future-proof their infrastructure, the adoption of these advanced containment solutions is expected to increase.
Market Trends
Adoption of Modular Containment Solutions
One of the most prominent trends in the Singapore Data Center Containment Market is the shift towards modular containment systems. Modular containment solutions are gaining traction due to their scalability, flexibility, and cost-effectiveness. These systems allow data center operators to design and implement customized cooling containment structures that can be easily expanded as data center capacities grow. For instance, companies like KoolLogix have developed modular systems that eliminate the need for expensive precision row cooling equipment and aisle containment systems, making them highly sought after for their ability to optimize airflow management and reduce energy consumption. Singapore’s data center market, characterized by its rapid growth and frequent upgrades, has seen increasing demand for modular containment systems, as they enable operators to avoid the large upfront investments traditionally associated with building containment structures. This trend is further driven by the need to maintain competitive advantages in a fast-evolving market, where the ability to quickly scale and respond to changes in demand is crucial.
Integration of Advanced Cooling Technologies
As the power density of servers continues to increase, data centers are seeking more efficient ways to manage heat generation. In response to these challenges, there has been a marked shift towards the integration of advanced cooling technologies, including liquid cooling, direct expansion (DX) systems, and in-row cooling. Singapore's hot and humid climate exacerbates the challenges data centers face in terms of cooling, prompting operators to seek cutting-edge containment and cooling solutions that deliver greater efficiency. For instance, Digital Realty has implemented innovative liquid cooling methods, such as using electrolysis to purify cooling water, which not only reduces chemical usage but also enhances system efficiency. Advanced cooling systems, such as cold aisle containment with in-row cooling or rear-door heat exchangers, have become increasingly popular as they provide targeted cooling where it is most needed, minimizing energy waste and improving overall operational efficiency. By combining innovative containment systems with advanced cooling technologies, data centers in Singapore are achieving significant energy savings while maintaining optimal operating conditions for their IT infrastructure.
Focus on Energy Efficiency and Sustainability
With rising energy costs and growing environmental concerns, energy efficiency and sustainability have become major priorities for data center operators in Singapore. The Singaporean government’s emphasis on reducing carbon emissions and meeting sustainability targets has further accelerated this trend. Data centers in the region are increasingly adopting green technologies and sustainable practices, and containment systems are a key component in achieving these goals. Cold aisle and hot aisle containment systems, for example, help isolate cold and hot air, ensuring that air conditioning systems work more efficiently and consume less energy. The integration of renewable energy sources, such as solar power, into data center operations is also gaining traction, with several data centers in Singapore exploring the use of green energy to reduce their reliance on traditional power sources. Data center operators are also adopting energy-efficient cooling methods, such as evaporative cooling, which works in conjunction with containment systems to minimize energy consumption. The drive towards sustainability is reshaping the market, as more operators strive to achieve higher levels of energy efficiency, meet regulatory requirements, and enhance their corporate social responsibility (CSR) profiles.
Smart and Automated Data Center Management
The rise of smart and automated data center management systems is another key trend in the Singapore Data Center Containment Market. Data center operators are increasingly turning to Internet of Things (IoT) technology and AI-driven automation tools to optimize their containment systems and cooling performance. These technologies allow for real-time monitoring of environmental conditions within the data center, such as temperature, humidity, and airflow, ensuring that containment solutions are operating at peak efficiency. By integrating IoT sensors and advanced software systems, data centers can achieve predictive maintenance, alerting operators to potential issues before they lead to equipment failure or downtime. Additionally, automated systems can adjust cooling and airflow in response to changing workloads or temperature variations, further enhancing energy efficiency and reducing operational costs. This trend is also supporting the growing need for remote management and control, as operators can access and monitor data centers from anywhere, providing greater flexibility and operational control. As data centers in Singapore continue to modernize, the integration of smart, automated systems is expected to play a central role in driving operational excellence and improving overall performance.
Market Challenges
High Initial Investment and Implementation Costs
High initial investment and implementation costs remain a significant barrier for data center operators in Singapore when adopting containment solutions. These systems, while offering long-term benefits such as improved energy efficiency and operational savings, demand substantial upfront capital for installation, customization, and integration with existing infrastructure. For instance, the Singapore government has introduced initiatives like the Investment Allowance Scheme to offset fixed capital expenditures for retrofitting projects, aiming to encourage energy-efficient upgrades. However, smaller operators with limited budgets still find it challenging to bear these costs, especially in a market where frequent upgrades are necessary to stay competitive. The reliance on advanced cooling technologies and tailored containment designs further escalates expenses. Despite the potential for reduced energy consumption and operational efficiency gains, the financial strain of initial investments continues to deter widespread adoption. This challenge is exacerbated by Singapore’s high energy costs and space constraints, which necessitate innovative yet costly solutions to optimize data center operations. Operators must carefully weigh the long-term advantages of containment systems against the immediate financial burdens they impose.
Space Limitations and Scalability Issues
Another key challenge is the space limitations within existing data centers in Singapore, which are often built on land with high real estate costs. As data center demand grows and power densities increase, many existing facilities are facing space constraints, making it difficult to implement containment solutions that can scale with business needs. Adding or upgrading containment systems in already crowded data centers can be a complex and costly process. Moreover, the physical constraints of smaller facilities may limit the flexibility and scalability of containment solutions, making it challenging to adapt to changing operational requirements. In a fast-evolving market, where data center operators must rapidly expand their capacities to accommodate increasing data traffic, ensuring that containment solutions can be easily scaled or modified to meet future demands is crucial. These space and scalability issues can hinder the growth and efficiency of data centers, posing significant challenges for operators looking to maximize their infrastructure’s potential while maintaining operational efficiency.
Market Opportunities
Expansion of Green Data Centers
As sustainability continues to be a key focus across industries, there is a growing market opportunity for data center operators in Singapore to adopt green data center solutions. The Singaporean government has implemented various policies to support energy-efficient practices and the reduction of carbon footprints in the data center industry. As businesses aim to meet stringent environmental regulations and corporate social responsibility (CSR) goals, there is a clear opportunity to integrate energy-efficient containment solutions that minimize energy consumption. Cold aisle and hot aisle containment systems, combined with advanced cooling technologies, offer an effective means of improving energy efficiency, reducing operational costs, and achieving sustainability targets. As more data centers in Singapore embrace eco-friendly practices, the demand for innovative containment solutions that align with these sustainability objectives will increase, creating growth opportunities for market players.
Rising Demand for Edge Data Centers
With the increasing adoption of edge computing and the expansion of 5G networks, there is a significant opportunity for data center containment solutions tailored to edge data centers in Singapore. Edge computing brings computing resources closer to the end user, requiring smaller, localized data centers to process data efficiently. As edge data centers proliferate in Singapore to support real-time data processing needs, operators will need scalable and efficient containment systems to optimize cooling and airflow management within these compact facilities. This trend provides a promising opportunity for containment solution providers to offer modular, flexible, and highly efficient systems that cater to the unique requirements of edge data centers. The growth of edge computing is expected to drive the demand for innovative containment technologies, presenting a significant market opportunity in the coming years.
Market Segmentation Analysis
By Containment Type
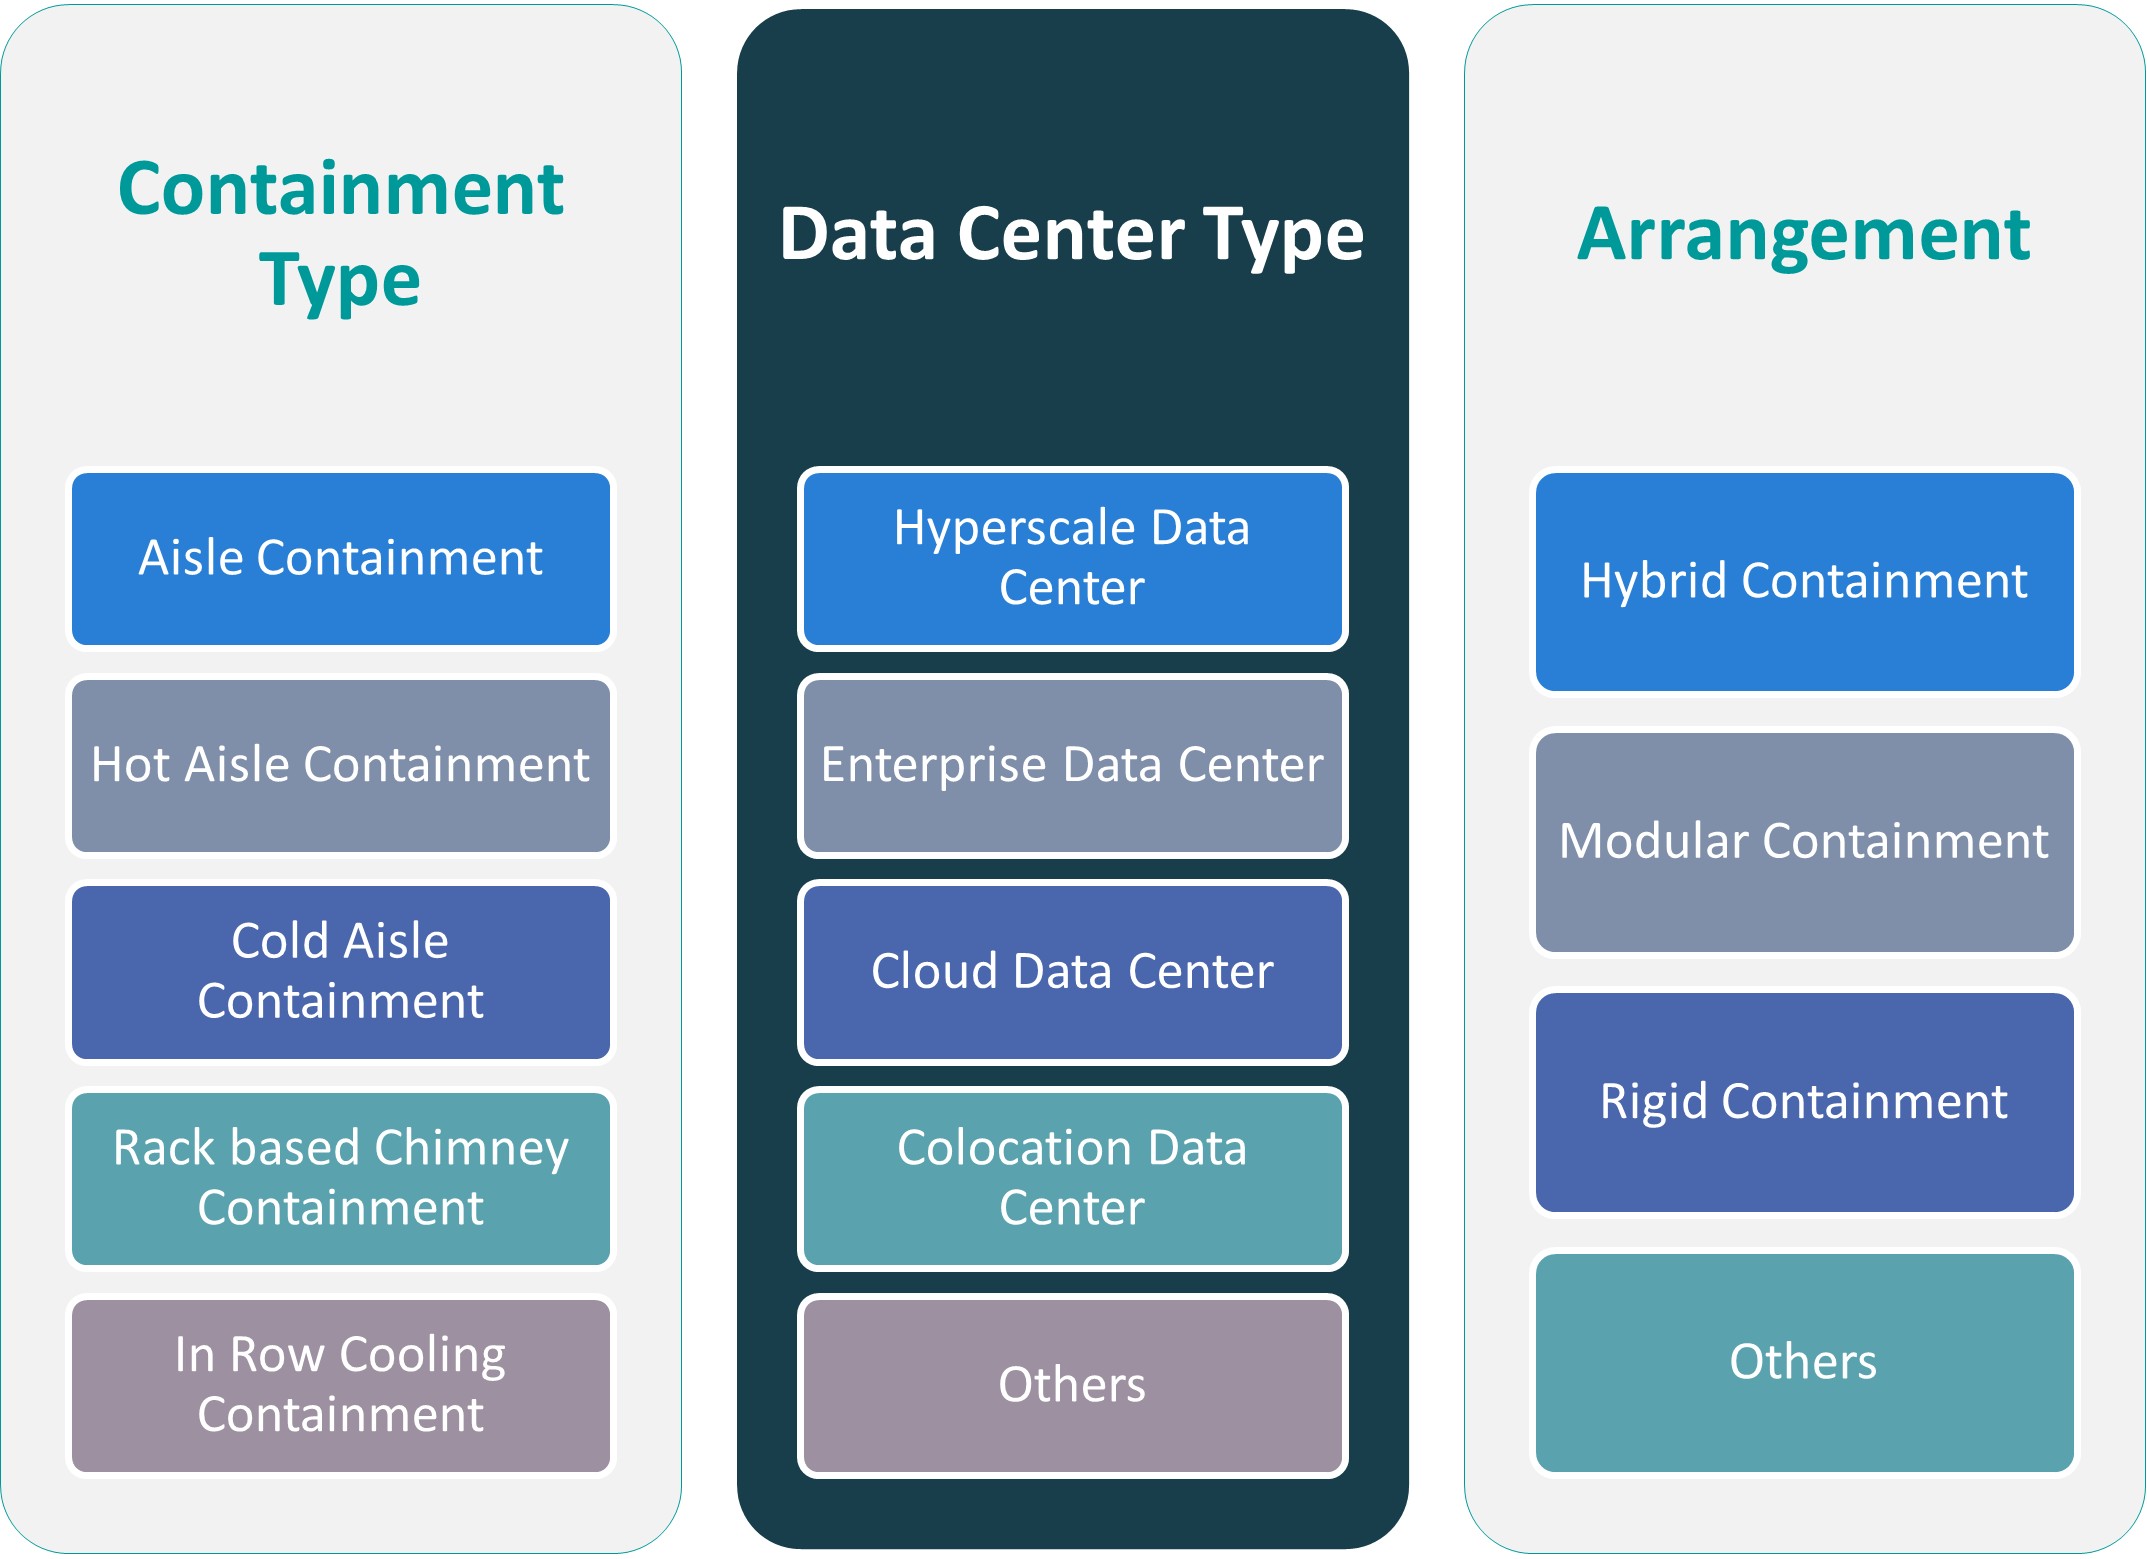
Hot aisle containment systems involve the isolation of hot air generated by server racks, preventing it from mixing with the cooler air from air conditioning systems. HAC is one of the most widely used containment systems due to its ability to enhance cooling efficiency by directing the hot air to designated areas for expulsion. This solution is particularly popular in Singapore's data centers, where efficient thermal management is critical due to the region's hot and humid climate. HAC is expected to dominate the market segment as the need for energy-efficient systems grows. Cold aisle containment focuses on isolating cool air in front of the server racks, ensuring that servers receive consistent cooling while preventing the warm air from disrupting the cooling flow. This containment type is increasingly being adopted by Singaporean data centers to optimize airflow and reduce cooling costs, making it a major player in the market segment. As energy efficiency becomes a priority, the adoption of CAC is anticipated to increase further. Rack-based chimney containment involves using vertical structures attached to server racks to guide hot air to the exhaust system. This containment type offers targeted cooling for high-density IT equipment, improving airflow and reducing the cooling load. Although niche, this solution is gaining traction in environments with specific thermal management needs. In-row cooling containment integrates cooling units directly between rows of racks to manage the heat generated by servers. This system offers high efficiency, particularly in dense server environments where cooling requirements are elevated. It is increasingly preferred for its space-saving benefits and energy-efficient performance, with demand growing in Singapore as data centers look for more flexible, modular solutions.
By Data Center Type
Hyperscale data centers, which support large-scale IT infrastructure, represent a major segment in the market. These facilities are characterized by their massive size and high-density server racks, which require sophisticated containment solutions. Singapore, as a digital hub, is seeing increased investment in hyperscale facilities, driven by the demand for cloud services, big data, and AI applications. Enterprise data centers cater to the internal IT infrastructure needs of large corporations. These centers, though smaller than hyperscale facilities, require efficient containment solutions to ensure optimal performance and cost savings. As businesses in Singapore focus on improving operational efficiency, the adoption of advanced containment systems in enterprise data centers is increasing. Cloud data centers, which serve cloud service providers (CSPs), are witnessing rapid growth in Singapore. These centers are designed to offer flexible, scalable, and secure cloud-based services, and they require highly efficient containment solutions to optimize cooling and energy management. The demand for cloud services in the region is driving the need for robust containment solutions tailored to the unique requirements of cloud data centers. Colocation data centers provide shared hosting spaces for multiple businesses, offering them cost-effective data storage and networking solutions. As Singapore continues to attract businesses looking to outsource their data storage needs, colocation data centers are increasingly incorporating advanced containment technologies to enhance their energy efficiency and cooling capabilities.
Segments
Based on Containment Type
- Aisle Containment
- Hot Aisle Containment
- Cold Aisle Containment
- Rack based Chimney Containment
- In Row Cooling Containment
Based on Data Center Type
- Hyperscale Data Center
- Enterprise Data Center
- Cloud Data Center
- Colocation Data Center
- Others
Based on Arrangement
- Hybrid Containment
- Modular Containment
- Rigid Containment
- Others
Based on Region
- Central Region
- Eastern Region
- Western Region
Regional Analysis
Central Region (45%)
The central region, which encompasses the heart of Singapore’s business and technological infrastructure, holds the largest market share in the Data Center Containment Market, accounting for approximately 45% of the market. This region is home to the highest concentration of data centers due to the availability of prime real estate, advanced infrastructure, and proximity to international connectivity hubs. The central area houses both hyperscale and colocation data centers, catering to multinational corporations, cloud service providers, and telecommunications companies. The demand for advanced containment systems is driven by the need to optimize cooling and ensure energy efficiency in these high-density environments. Furthermore, the Singapore government’s pro-business policies and initiatives like the Smart Nation Vision play a crucial role in supporting the growth of data centers in this region.
Eastern Region (15%)
The eastern region of Singapore, particularly areas near Changi, has also seen growing investment in data center infrastructure, contributing around 15% to the overall market. This region benefits from its proximity to major transportation hubs and the growing demand for colocation and enterprise data centers. As businesses look for cost-effective solutions outside of the central business district, the eastern region presents a compelling option. The growing need for sustainable data center operations is driving the adoption of advanced containment solutions, such as hot and cold aisle containment systems, in this region.
Key players
- Parker Hannifin Corporation
- Stulz
- Daikin Industries, Ltd.
- Emerson Electric Co.
- Rittal
Competitive Analysis
The Singapore Data Center Containment Market is highly competitive, with leading players such as Parker Hannifin Corporation, Stulz, Daikin Industries, Emerson Electric Co., and Rittal driving innovation and market growth. Parker Hannifin Corporation stands out with its broad portfolio of containment solutions, offering advanced cooling and airflow management technologies. Stulz focuses on precision cooling systems, providing reliable containment solutions tailored to high-density environments. Daikin Industries, known for its energy-efficient systems, continues to develop advanced containment solutions to meet the growing demands for sustainability in data centers. Emerson Electric Co. brings expertise in both cooling and power solutions, integrating its containment products with its robust electrical management systems. Rittal, with its modular data center containment systems, appeals to operators looking for scalable and customizable solutions. These companies are strengthening their positions through product innovations, strategic collaborations, and a focus on energy-efficient solutions.
Recent Developments
- In November 2023, Huawei introduced two new additions to its Smart Modular Data Center and SmartLi uninterruptible power supply (UPS) series – FusionModule2000 6.0, a modular small/medium-sized data center solution, and UPS2000-H, a small-footprint power supply solution running on SmartLi Mini.
- In February 2025, Trane Technologies expanded its data center solutions to include liquid cooling thermal management systems, introducing the Trane 1MW Coolant Distribution Unit for high-performance workloads.
- In 2025, Honeywell launched a data center management suite to improve efficiency and sustainability by integrating operational and IT infrastructure data.
- In March 2025, Vertiv introduced new solutions to support dense AI and high-performance computing workloads, including consolidated infrastructure management software and prefabricated modular overhead infrastructure.
- In March 2025, Siemens announced a $285 million investment in U.S. manufacturing, including establishing new facilities in California and Texas. This investment aims to enhance manufacturing capabilities and advance AI technologies, supporting sectors such as commercial, industrial, construction, and AI data centers.
Market Concentration and Characteristics
The Singapore Data Center Containment Market exhibits a moderate level of concentration, with several key players dominating the market, including Parker Hannifin Corporation, Stulz, Daikin Industries, Emerson Electric Co., and Rittal. These companies lead the market by offering innovative and energy-efficient containment solutions that cater to the diverse needs of data center operators. The market is characterized by a strong focus on energy efficiency, sustainability, and customization, driven by the increasing demand for high-performance data centers. Given Singapore's position as a regional hub for digital infrastructure, the market is competitive, with established players continuously advancing their product portfolios to meet the evolving needs of hyperscale, cloud, and enterprise data centers. Additionally, the market benefits from favorable government policies supporting green technologies, fueling the growth of containment systems that optimize cooling and reduce operational costs.
Report Coverage
The research report offers an in-depth analysis based on Containment Type, Data Center Type, Arrangement and Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The demand for data center services in Singapore will continue to grow, driven by the increasing adoption of cloud services and digital transformation initiatives. This growth will further elevate the need for advanced containment solutions to optimize cooling and efficiency.
- As energy costs rise and environmental regulations tighten, data center operators will increasingly adopt energy-efficient containment solutions to meet sustainability goals. This trend will be critical in reducing operational costs and supporting Singapore’s green initiatives.
- Hyperscale data centers, requiring sophisticated containment systems to manage high power densities, will drive market expansion. Singapore’s strategic location and robust digital infrastructure make it a prime location for hyperscale data center development.
- Modular containment systems will see greater adoption, offering scalability and cost-effective solutions for rapidly expanding data centers. These systems will enable operators to quickly adapt to changing needs and optimize energy use.
- The rise of edge computing and the expansion of 5G networks will drive the need for edge data centers. These smaller, localized facilities will require flexible and efficient containment solutions to optimize performance
- Technological advancements, such as liquid cooling and in-row cooling, will become more common in Singapore’s data centers. These innovations will enable more efficientmanagement of heat in high-density environments.
- Government initiatives to support the development of green data centers will provide opportunities for market players to offer energy-efficient containment solutions. Policies focused on sustainability will drive further investments in containment systems that reduce energy consumption.
- Colocation data centers will continue to thrive in Singapore, as businesses look to outsource data storage and processing. This will increase the demand for flexible containment solutions that maximize space and cooling efficiency.
- The integration of IoT sensors and AI-driven automation systems into containment solutions will become more prevalent. These technologies will enhance real-time monitoring, predictive maintenance, and overall system performance in data centers.
- The competitive landscape will remain dynamic, with key players like Parker Hannifin, Stulz, and Emerson Electric Co. investing in product innovations. As the market evolves, companies will need to differentiate themselves through advanced technologies, cost-effective solutions, and customer-centric services.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Expansion of Digital Services and Cloud Adoption
The rapid growth of digital transformation initiatives and cloud-based applications in Singapore is driving the need for more data centers, which in turn increases demand for advanced containment solutions to manage higher data processing and storage requirements efficiently.
Need for Efficient Cooling and Energy Cost Reduction
Singapore’s hot and humid climate, combined with rising power densities in data centers, makes efficient cooling critical. Containment systems help reduce energy consumption and operational costs by optimizing airflow and preventing hot spots, supporting both economic and sustainability goals.
Government Support for Green Data Centers
Singapore’s government policies and incentives, such as the Green Data Centre Roadmap, actively promote the adoption of energy-efficient and sustainable technologies, encouraging data center operators to invest in advanced containment solutions that align with environmental targets.
Technological Advancements in Containment Solutions
Innovations such as modular containment, IoT-enabled monitoring, and integration with advanced cooling technologies are enabling data centers to achieve greater scalability, flexibility, and operational efficiency, fueling market growth as operators seek to future-proof their facilities.
Growth of Hyperscale and Edge Data Centers
Significant investments by global cloud and technology companies in hyperscale and edge data centers in Singapore are increasing the need for scalable, high-performance containment systems that can support dense workloads and localized data processing.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the market size of the Singapore Data Center Containment Market in 2023 and 2032, and what is the projected CAGR?
What are the key drivers of growth in the Singapore Data Center Containment Market?
Which companies are leading the Singapore Data Center Containment Market?
How are trends like modular containment systems impacting the market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Arrangement
- 1.2.1 Hybrid Containment
- 1.2.2 Modular Containment
- 1.2.3 Rigid Containment
- 1.2.4 Others
- 1.3 By Containment Type
- 1.3.1 Hot Aisle Containment
- 1.3.2 Cold Aisle Containment
- 1.3.3 Rack-based Chimney Containment
- 1.3.4 In Row Cooling Containment
- 1.3.5 Aisle Containment
- 1.4 By Data Center Type
- 1.4.1 Hyperscale Data Center
- 1.4.2 Enterprise Data Center
- 1.4.3 Cloud Data Center
- 1.4.4 Colocation Data Center
- 1.4.5 Others
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 12.94 million → 2032: USD 32.02 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Singapore Data Center Containment Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Singapore Data Center Containment Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Singapore Data Center Containment Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Singapore Data Center Containment Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Singapore Data Center Containment Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Singapore Data Center Containment Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Data Protection, AI and Cybersecurity Compliance
- 9.8 Upcoming Policy Changes and Market Implications
Chapter 10 Singapore Data Center Containment Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Singapore Data Center Containment Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 12.94 million → 2032: USD 32.02 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Singapore Data Center Containment Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Arrangement - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Hybrid Containment
- 12.3.7.2 Modular Containment
- 12.3.7.3 Rigid Containment
- 12.3.7.4 Others
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Containment Type - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Hot Aisle Containment
- 12.4.7.2 Cold Aisle Containment
- 12.4.7.3 Rack-based Chimney Containment
- 12.4.7.4 In Row Cooling Containment
- 12.4.7.5 Aisle Containment
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Data Center Type - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Hyperscale Data Center
- 12.5.7.2 Enterprise Data Center
- 12.5.7.3 Cloud Data Center
- 12.5.7.4 Colocation Data Center
- 12.5.7.5 Others
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Singapore Data Center Containment Geographic Market Outlook, 2024-2032
- 13.1 Domestic Market Distribution and Demand Clusters
- 13.2 State- or Province-Wise Market Size and Forecast, 2024-2032
- 13.3 City and Metropolitan Market Outlook
- 13.4 Industrial, Manufacturing and Commercial Clusters
- 13.5 Geographic Concentration of Key End Users
- 13.6 Local Pricing and Purchasing Differences
- 13.7 Domestic Production Facilities and Capacity Map
- 13.8 Local Infrastructure and Project Pipeline
- 13.9 State-Level Policy and Incentive Differences
- 13.10 Subnational Investment Hotspots and Opportunities
- 13.11 Distribution and Logistics Networks
- 13.12 Domestic Competitive Footprint
Chapter 14 Singapore Data Center Containment Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2024-2032
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 Singapore Data Center Containment Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2024
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2024-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Parker Hannifin Corporation
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 Stulz
- 17.4 Daikin Industries, Ltd.
- 17.5 Emerson Electric Co.
- 17.6 Rittal
- 17.7 Vertiv Holdings Co.
- 17.8 Schneider Electric SE
- 17.9 Huawei
- 17.10 Honeywell
- 17.11 Trane Technologies
- 17.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

