
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
| Solid State Relay Market Size 2024 | USD 1,460.2 million |
| Solid State Relay Market, CAGR | 4.30% |
| Solid State Relay Market Size 2032 | USD 2,044.97 million |
Market Overview
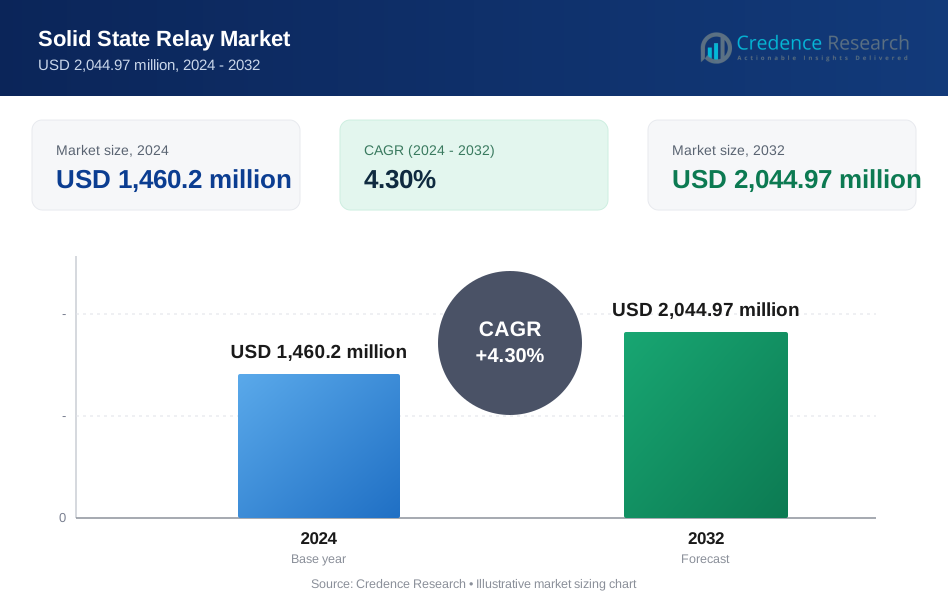
The Solid State Relay Market is projected to grow from USD 1,460.2 million in 2024 to USD 2,044.97 million by 2032, at a compound annual growth rate (CAGR) of 4.30%.
The Solid State Relay Market is driven by the increasing demand for energy-efficient devices and automation across various industries. Advancements in semiconductor technology enhance relay performance and reliability, contributing to market growth. The rise in industrial automation and the need for precise control systems further boost the adoption of solid state relays. Trends such as the integration of IoT and smart technologies in manufacturing processes are propelling market expansion. Additionally, the growing emphasis on reducing carbon footprints and improving energy management systems supports the widespread use of solid state relays in modern industrial applications.
The solid state relay market exhibits significant geographical diversity, with North America, Europe, Asia-Pacific, and other regions showcasing varied growth dynamics. North America and Europe lead due to advanced industrial automation and strong demand in automotive and energy sectors. Asia-Pacific is emerging rapidly, driven by industrialization and the growing electronics market. Key players in the market include Crydom Inc. (Sensata Technology), Omron Corporation, Schneider Electric, ABB Ltd., IXYS Corp. (Littelfuse), STMicroelectronics, Rockwell Automation Inc., General Electric, Vishay Intertechnology (Siliconix), Fujitsu Limited, Carlo Gavazzi Holding AG, Honeywell International Inc., and Texas Instruments Inc. These companies drive innovation and competitiveness in the SSR market.
Market Drivers
Rising Demand for Energy Efficiency
Solid state relays (SSRs) offer significant advantages in terms of energy efficiency, making them increasingly popular across various industries. For instance, in the realm of energy efficiency, solid state relays (SSRs) are known to have a power loss as low as 0.1 watts per ampere, compared to mechanical relays which can lose up to 2.5 watts per ampere during operation. This translates to a potential energy saving of up to 96% in applications like data centers, which can consume over 70 billion kWh of electricity annually in the United States alone. Unlike mechanical relays that generate heat and experience power loss during operation, SSRs have minimal power loss, leading to substantially lower energy consumption. This efficiency is particularly crucial in sectors where energy conservation is a priority, such as data centers, green buildings, and renewable energy systems. The shift towards more sustainable practices and the need to reduce operational costs drive the adoption of SSRs, as they contribute to both energy savings and enhanced performance.
Increased Automation in Manufacturing
The surge in automation across manufacturing sectors is another key driver for the Solid State Relay Market. In terms of automation in manufacturing, SSRs are capable of switching speeds of less than 1 millisecond, whereas mechanical relays may take up to 15 milliseconds. This is particularly beneficial in high-speed automation environments where, for example, a production line might need to perform thousands of operations per hour, and even a fraction of a second can impact overall productivity. As industries move towards more automated processes, the demand for reliable and efficient switching solutions has grown. SSRs provide several benefits over traditional mechanical relays, including faster switching speeds, silent operation, and a longer lifespan. These characteristics make SSRs ideal for controlling automated machinery, robots, and production lines, where precise and consistent performance is essential. The increasing reliance on automation to boost productivity and reduce labor costs further fuels the demand for SSRs in manufacturing environments.
Advancements in Semiconductor Technology
Continuous advancements in semiconductor technology are pivotal to the development and adoption of solid state relays. When discussing advancements in semiconductor technology, modern SSRs can now handle currents of up to 100 amperes and voltages up to 600 volts, with some designs even pushing these limits further. This is a significant improvement from earlier SSRs that were limited to lower current and voltage capacities, thus broadening their applicability across more power-intensive industries. These technological improvements have led to the creation of more efficient, compact, and cost-effective SSRs, enhancing their performance and expanding their range of applications. Modern SSRs benefit from superior design and materials, which contribute to their enhanced durability and functionality. As a result, SSRs are becoming more accessible to various industries, including those that previously relied on mechanical relays. The ongoing innovation in semiconductor technology ensures that SSRs will continue to evolve, offering even greater efficiency and reliability.
Growing Demand for Miniaturization and Improved Reliability
The trend towards miniaturization is creating new opportunities for solid state relays, particularly in applications where space is limited. From consumer electronics to industrial control panels, the compact size and lightweight design of SSRs make them ideal for environments with space constraints. This miniaturization trend aligns with the broader market demand for smaller, more efficient components. Additionally, SSRs offer improved reliability and reduced maintenance requirements compared to mechanical relays, as they have no moving parts. This lack of mechanical wear and tear results in a longer lifespan and fewer maintenance needs, which is crucial for applications where downtime can be costly. The combination of compact design, enhanced reliability, and lower maintenance costs makes SSRs a preferred choice in many high-demand industries.
Market Trends
Focus on High-Performance SSRs and Integration with Smart Grid Technologies
The demand for high-performance solid state relays (SSRs) with advanced capabilities is on the rise. Industries are increasingly seeking SSRs with faster switching speeds, higher current and voltage ratings, and enhanced thermal performance. For instance, high-performance solid state relays (SSRs) are now capable of switching speeds up to 100 times faster than traditional mechanical relays, with some models achieving speeds of less than 1 microsecond. This is particularly crucial for applications in electric vehicle charging infrastructure, where SSRs are used to manage power flows of up to 350 kW the equivalent of charging a typical electric car battery in under 10 minutes. These high-performance SSRs are crucial for applications in high-power electronics, renewable energy systems, and electric vehicle charging infrastructure, where efficiency and reliability are paramount. As these sectors continue to expand, the need for SSRs that can handle more demanding conditions becomes more critical. This trend is driving manufacturers to innovate and develop SSRs that meet the stringent requirements of modern high-power applications. In parallel, the integration of SSRs with smart grid technologies is gaining momentum. The advent of smart grids, which facilitate two-way communication and intelligent control of electricity distribution, presents significant opportunities for the adoption of SSRs.
IoT and Industrial Automation Alongside Material Innovation for Wider Applications
The growth of the Internet of Things (IoT) and Industrial Automation, often referred to as Industry 4.0, is significantly driving the demand for intelligent and interconnected devices, including solid state relays. In the context of smart grid technologies, SSRs with integrated communication capabilities can handle load currents of up to 120 amperes and are designed to withstand voltage spikes of over 600 volts, ensuring they can operate reliably even under the stress of grid disturbances. This robustness is essential for smart grids, which are expected to manage up to 80% of all electricity in the United States by 2030. SSRs with embedded intelligence and connectivity features can seamlessly integrate into IoT networks, enabling remote control, condition monitoring, and predictive maintenance of industrial equipment. This integration facilitates enhanced operational efficiency, as businesses can monitor the performance of their machinery in real time and address potential issues before they escalate. The interconnected nature of IoT and industrial automation systems amplifies the need for SSRs that can communicate and operate within these advanced frameworks, ensuring seamless operation and increased productivity. Simultaneously, advancements in material science are broadening the range of applications for SSRs. Innovations such as gallium nitride (GaN) and silicon carbide (SiC) based SSRs are emerging, offering improved efficiency, faster switching speeds, and suitability for high-temperature environments. GaN-based SSRs, for example, are recognized for their high efficiency and rapid switching capabilities, making them ideal for modern high-performance applications.
Market Challenges Analysis
Higher Initial Cost and Counterfeit Products
Solid state relays (SSRs), despite their technological advancements and numerous benefits, often come with a higher initial cost compared to traditional mechanical relays. This price difference can be a significant barrier to entry for cost-sensitive applications, particularly in sectors with stringent budget constraints. Industries that are heavily reliant on cost-effective solutions may hesitate to adopt SSRs due to this upfront financial outlay, even though the long-term benefits such as reduced maintenance and enhanced reliability could offset these initial costs. To mitigate this challenge, manufacturers and suppliers need to emphasize the total cost of ownership (TCO) and demonstrate the potential long-term savings that SSRs can offer over their mechanical counterparts. Highlighting the energy efficiency, longer lifespan, and reduced downtime associated with SSRs can help to justify the higher initial investment and promote broader adoption across various industries. The presence of substandard SSRs not only risks operational efficiency but also tarnishes the reputation of legitimate manufacturers who must contend with the fallout from these unreliable products. Strategies to combat counterfeiting are crucial and should include rigorous quality assurance processes, the implementation of robust anti-counterfeit measures, and consumer education on the importance of purchasing genuine SSRs. Efforts to raise awareness about the risks associated with counterfeit SSRs and the benefits of investing in authentic, high-quality products can help protect both consumers and reputable manufacturers from the adverse effects of counterfeit goods.
Limited Application Awareness and Thermal Management Considerations
Despite the increasing awareness of solid state relays, there remains a notable knowledge gap in certain industries regarding their potential benefits and suitability for specific applications. This limited application awareness can hinder the broader adoption of SSRs, as some sectors may not fully understand the advantages these relays offer over traditional mechanical options. Educational initiatives and targeted marketing campaigns are essential to bridge this knowledge gap. By providing detailed information and practical examples of successful SSR implementations, manufacturers can better communicate the value and versatility of SSRs to potential users. These efforts should aim to highlight how SSRs can enhance operational efficiency, reduce maintenance costs, and improve overall system reliability, thereby encouraging wider adoption across diverse industries. Thermal management considerations present another significant challenge for the effective use of SSRs. While solid state relays are generally more efficient than mechanical relays, they can still generate heat during operation, particularly in high-frequency switching applications. Proper thermal management is essential to ensure optimal performance and reliability of SSRs. This involves the careful selection of SSRs with appropriate voltage and current ratings for the specific application, as well as the design and implementation of effective heat dissipation mechanisms, such as heat sinks. Failure to address thermal management adequately can lead to overheating, reduced performance, and potential failure of the SSRs. Therefore, it is critical for users to understand and implement the necessary measures for managing heat in their systems to maximize the benefits of using SSRs.
Market Segmentation Analysis:
By Type:
The solid state relay market is segmented based on type into DC to AC, DC to DC, AC to DC, and AC/DC to AC. DC to AC SSRs are widely used in applications that require the conversion of direct current to alternating current, such as inverters and motor drives. DC to DC SSRs are crucial in DC power management and distribution systems, offering high efficiency and precise control. AC to DC SSRs play a vital role in applications needing conversion from alternating current to direct current, which is common in power supplies and battery charging systems. AC/DC to AC SSRs are essential in applications that involve alternating current control with enhanced efficiency and reliability. Each type serves specific needs, contributing to the overall versatility and applicability of solid state relays across various industries.
By Mounting:
The solid state relay market is further segmented based on mounting into panel mount, PCB mount, din rail mount, and others. Panel mount SSRs are favored in industrial environments where space and ease of installation are critical. They are commonly used in control panels and industrial machinery. PCB mount SSRs are designed for integration into printed circuit boards, making them suitable for compact and space-constrained applications like consumer electronics and small appliances. Din rail mount SSRs offer a modular and standardized mounting solution, ideal for use in electrical distribution systems and automation equipment. Other mounting types cater to niche applications and custom installations, providing flexibility for specific industry needs. This segmentation allows manufacturers and users to choose the most appropriate mounting type based on their application requirements and installation preferences.
Segments:
Based on Type:
- DC to AC
- DC to DC
- AC to DC
- AC/DC to AC
Based on Mounting:
- Panel Mount
- PCB Mount
- Din Rail Mount
- Others
Based on Output Voltage:
- DC Solid State Relay
- Constant Current
- Resistive Current
- AC Solid State Relay
- Single Phase
- Three-Phase
Based on Current Rating:
- Low (0-20A)
- Medium (20A-50A)
- High (50A and above)
Based on Application:
- Industrial Automation
- Building Equipment
- Energy & Power
- Automotive & Transportation
- Food & Beverage
- Military & Defense
- Others
Based on the Geography:
- North America
- U.S
- Canada
- Mexico
- Europe
- Germany
- France
- UK
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- The Rest of the Middle East and Africa
Regional Analysis
Asia-Pacific
Asia-Pacific dominates the global solid state relay market, commanding a substantial 40% market share. This leadership is primarily driven by countries such as China, Japan, and South Korea, which have robust manufacturing sectors and a strong focus on industrial automation. The region's market is characterized by high demand from various industries, including automotive, consumer electronics, and telecommunications. China, in particular, has emerged as a major hub for solid state relay manufacturing and consumption, benefiting from its vast industrial base and government initiatives promoting smart manufacturing. The Asia-Pacific market has seen significant growth in the adoption of solid state relays in renewable energy applications, especially in solar power systems and electric vehicle charging infrastructure. Additionally, the region's rapid urbanization and infrastructure development have fueled demand for solid state relays in building automation and power distribution systems. The presence of key market players and a strong supply chain in the region further contribute to Asia-Pacific's dominant position in the global solid state relay market.
North America
North America holds the second-largest share in the global solid state relay market at approximately 30%, with the United States leading the adoption. The North American market is characterized by a high level of technological innovation and a strong emphasis on energy efficiency. The region has seen widespread implementation of solid state relays in industrial control systems, HVAC equipment, and medical devices. North America's advanced semiconductor industry has been instrumental in developing high-performance solid state relays with enhanced features such as integrated diagnostics and communication capabilities. The region's focus on Industry 4.0 and the Industrial Internet of Things (IIoT) has driven the demand for smart solid state relays that can be seamlessly integrated into networked control systems. Furthermore, stringent safety regulations and the need for reliable switching solutions in critical applications have boosted the adoption of solid state relays across various sectors.
Key Player Analysis
- Crydom Inc. (Sensata Technology)
- Omron Corporation
- Schneider Electric
- ABB Ltd.
- IXYS Corp.. (Littelfuse)
- STMicroelectronics
- Rockwell Automation Inc.
- General Electric
- Vishay Intertechnology (Siliconix)
- Fujitsu Limited
- Carlo Gavazzi Holding AG
- Honeywell International Inc
- Texas Instruments Inc.
Competitive Analysis
The solid state relay (SSR) market is highly competitive, with key players such as Crydom Inc. (Sensata Technology), Omron Corporation, Schneider Electric, ABB Ltd., IXYS Corp. (Littelfuse), STMicroelectronics, and Rockwell Automation Inc. dominating the landscape. These companies leverage advanced technology and extensive R&D to enhance product performance, reliability, and efficiency. Crydom Inc. and Omron Corporation are known for their extensive product portfolios and strong market presence. Schneider Electric and ABB Ltd. emphasize energy efficiency and automation solutions, while IXYS Corp. (Littelfuse) and STMicroelectronics focus on semiconductor innovations. Rockwell Automation Inc. integrates SSRs into comprehensive automation systems. The competitive environment drives continuous improvement and technological advancements, ensuring that these leaders maintain their market position by meeting diverse industrial needs and pushing the boundaries of SSR capabilities.
Recent Developments
- In September 2023, Texas Instruments launched a new solid-state relay (SSR) portfolio that integrates power and signal transfer in a single chip, while also eliminating at least three components from their designs. The SSRs are designed to provide industry-leading reliability and high accuracy for improved system safety. TI's SSRs can reduce the number of moving parts in a design and enable basic isolation up to 3.75 kVrms and reinforced isolation up to 5 kVrms.
- In March 2023, Carlo Gavazzi Holding AG has launched the NRG digital solid-state relays with an EtherCAT interface. This system of digital solid-state relays allows for real-time switching, monitoring, and diagnostics via EtherCAT.
Market Concentration & Characteristics
The solid state relay (SSR) market exhibits moderate to high market concentration, with a few key players holding significant market shares. Leading companies such as Crydom Inc. (Sensata Technology), Omron Corporation, Schneider Electric, and ABB Ltd. dominate the market, benefiting from strong brand recognition, extensive product portfolios, and advanced technological capabilities. These firms drive innovation and set industry standards, leveraging economies of scale to maintain competitive advantages. The SSR market is characterized by its focus on energy efficiency, reliability, and long lifespan, catering to a wide range of applications including industrial automation, renewable energy, and automotive sectors. Continuous advancements in semiconductor technology and increasing automation in manufacturing processes further define the market's dynamic nature. Despite the dominance of major players, opportunities exist for smaller companies and new entrants to innovate and capture niche segments, contributing to the market's overall growth and diversification.
Report Coverage
The research report offers an in-depth analysis based on Type, Mounting, Output Voltage, Current Rating, Application and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The demand for energy-efficient switching solutions will drive the growth of the solid state relay market.
- Increased automation across various industries will continue to boost the adoption of SSRs.
- Advancements in semiconductor technology will lead to the development of more efficient and compact SSRs.
- The growing trend of miniaturization in electronics will create new opportunities for SSR applications.
- The integration of SSRs with smart grid technologies will become more prevalent, enhancing remote monitoring and control.
- The rise of IoT and industrial automation will drive demand for intelligent and interconnected SSR devices.
- Material innovations, such as GaN and SiC-based SSRs, will expand the range of applications for these relays.
- The focus on sustainability will push manufacturers to develop environmentally friendly SSR options.
- Increased awareness and education about the benefits of SSRs will encourage wider adoption across various sectors.
- Strategies to combat counterfeit SSR products will become crucial to ensure quality and safety standards are maintained.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Rising Demand for Energy Efficiency
Solid state relays (SSRs) offer significant energy savings compared to mechanical relays, with much lower power loss during operation. This makes them highly attractive for sectors like data centers, green buildings, and renewable energy systems where reducing operational costs and carbon footprints is a priority.
Increased Automation in Manufacturing
The shift towards automated manufacturing processes requires reliable, fast-switching, and durable switching solutions. SSRs provide silent operation, rapid switching speeds, and long lifespans, making them ideal for controlling automated machinery and production lines.
Advancements in Semiconductor Technology
Continuous improvements in semiconductor materials and design have enabled SSRs to handle higher currents and voltages, expanding their use in power-intensive industries. These advancements also result in more compact, efficient, and cost-effective relay solutions.
Integration with IoT and Smart Technologies
The adoption of IoT and smart grid technologies in industrial and energy sectors is driving demand for SSRs with embedded intelligence and connectivity. These relays enable remote monitoring, predictive maintenance, and seamless integration into advanced automation and energy management systems.
Growing Trend Toward Miniaturization and Reliability
As electronic devices and industrial systems become more compact, the need for smaller, more reliable components increases. SSRs, with their compact size and lack of moving parts, offer improved reliability and reduced maintenance, supporting their adoption in space-constrained and high-demand applications.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Solid State Relay Market?
What factors are driving the growth of the Solid State Relay Market?
What are the key segments within the Solid State Relay Market?
What are some challenges faced by the Solid State Relay Market?
Who are the major players in the Solid State Relay Market?
Which segment is leading the market share?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Type
- 1.2.1 DC to AC
- 1.2.2 DC to DC
- 1.2.3 AC to DC
- 1.2.4 AC/DC to AC
- 1.3 By Mounting
- 1.3.1 Panel Mount
- 1.3.2 PCB Mount
- 1.3.3 Din Rail Mount
- 1.3.4 Others
- 1.4 By Application
- 1.4.1 Industrial Automation
- 1.4.2 Building Equipment
- 1.4.3 Energy & Power
- 1.4.4 Automotive & Transportation
- 1.4.5 Food & Beverage
- 1.4.6 Military & Defense
- 1.4.7 Others
- 1.5 By Output Voltage
- 1.5.1 DC Solid State Relay (Constant Current, Resistive Current)
- 1.5.2 AC Solid State Relay (Single Phase, Three-Phase)
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 1,460.2 million → 2032: USD 2,044.97 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Solid State Relay Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Solid State Relay Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Solid State Relay Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Solid State Relay Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Solid State Relay Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Solid State Relay Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Solid State Relay Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Solid State Relay Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 1,460.2 million → 2032: USD 2,044.97 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Solid State Relay Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Type - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 DC to AC
- 12.3.7.2 DC to DC
- 12.3.7.3 AC to DC
- 12.3.7.4 AC/DC to AC
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Mounting - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Panel Mount
- 12.4.7.2 PCB Mount
- 12.4.7.3 Din Rail Mount
- 12.4.7.4 Others
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Application - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Industrial Automation
- 12.5.7.2 Building Equipment
- 12.5.7.3 Energy & Power
- 12.5.7.4 Automotive & Transportation
- 12.5.7.5 Food & Beverage
- 12.5.7.6 Military & Defense
- 12.5.7.7 Others
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 By Output Voltage - Market Size and Forecast, 2024-2032
- 12.6.1 Segment Definition and Scope
- 12.6.2 Historical Market Size
- 12.6.3 Revenue Forecast, 2024-2032
- 12.6.4 Volume Forecast, 2024-2032
- 12.6.5 Base-Year Market Share, 2024
- 12.6.6 Segment CAGR and Growth Drivers
- 12.6.7 Subsegment Market Size and Forecast
- 12.6.7.1 DC Solid State Relay (Constant Current, Resistive Current)
- 12.6.7.2 AC Solid State Relay (Single Phase, Three-Phase)
- 12.6.8 Subsegment Pricing and Adoption Trends
- 12.6.9 Leading Suppliers and Competition
- 12.6.10 Regional Demand and Opportunities
- 12.7 Segment Growth Comparison
- 12.8 Segment Attractiveness and Priority Matrix
Chapter 13 Global Solid State Relay End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Solid State Relay Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Solid State Relay Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Solid State Relay Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Crydom Inc. (Sensata Technology)
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Omron Corporation
- 18.4 Schneider Electric
- 18.5 ABB Ltd.
- 18.6 IXYS Corp. (Littelfuse)
- 18.7 STMicroelectronics
- 18.8 Rockwell Automation Inc.
- 18.9 General Electric
- 18.10 Vishay Intertechnology (Siliconix)
- 18.11 Carlo Gavazzi Holding AG
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

