
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Financial Consolidation Software Market Size 2024 | USD 2,701.45 million |
| Financial Consolidation Software Market, CAGR | 11.4% |
| Financial Consolidation Software Market Size 2032 | USD 6,407.3 million |
Market Overview:
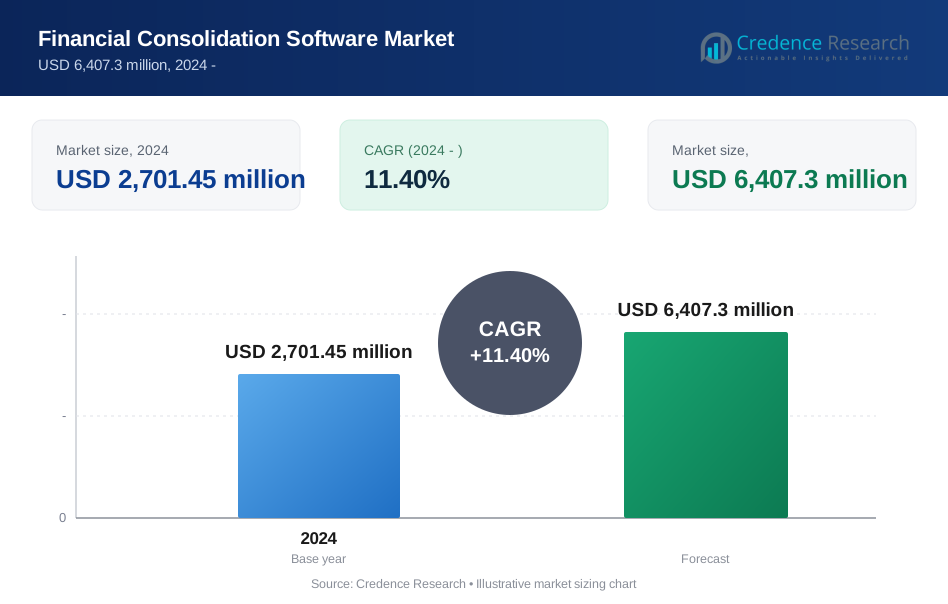
The global market for Financial Consolidation Software is projected to grow from USD 2,701.45 million in 2024 to USD 6,407.3 million by 2032, at a compound annual growth rate (CAGR) of 11.4%.
The Financial Consolidation Software market is driven by the growing demand for streamlined financial reporting, increased regulatory compliance requirements, and the need for accurate, real-time financial data analysis. Organizations are increasingly adopting these solutions to automate consolidation processes, reduce errors, and enhance decision-making capabilities. The rise of cloud-based solutions offers greater scalability, flexibility, and cost-effectiveness, further fueling market growth. Additionally, the shift towards integrated financial management systems and the emphasis on digital transformation within enterprises is accelerating the adoption of financial consolidation tools. As businesses expand globally, the complexity of financial reporting increases, propelling the need for automated consolidation systems that can handle multiple currencies, taxation laws, and diverse financial data. Moreover, the growing importance of data security and fraud prevention is pushing organizations to adopt more secure, robust software platforms, driving innovation and adoption in the market. These factors collectively contribute to the steady expansion of the financial consolidation software industry.
The financial consolidation software market shows strong regional growth, with North America leading with a 38% market share in 2024, driven by key players like Oracle Corporation and SAP SE. Europe follows with a 30% share, where regulatory complexity and digitalization fuel demand for solutions from IBM Corporation and Workiva Inc. Asia-Pacific, holding a 20% market share, sees rapid growth due to emerging economies in China and India, with players like OneStream Software LLC and Anaplan Inc. expanding their presence. The Rest of the World region, with a 12% share, is also witnessing growth, particularly in Latin America and the Middle East, where cloud-based solutions from companies like CCH Tagetik (Wolters Kluwer) and Prophix Software Inc. are becoming popular. These regions are characterized by increasing adoption of financial consolidation software due to digital transformation and compliance needs.
Market Insights:
- The global market for financial consolidation software is projected to grow from USD 2,701.45 million in 2024 to USD 6,407.3 million by 2032, at a CAGR of 11.4%.
- Demand for streamlined financial reporting and increased regulatory compliance is driving market growth.
- The rise of cloud-based solutions offers greater scalability, flexibility, and cost-effectiveness, further boosting market expansion.
- Digital transformation and integration with financial management systems are accelerating the adoption of financial consolidation software.
- The increasing complexity of financial reporting for global businesses requires automated consolidation systems capable of handling multiple currencies and diverse financial data.
- The need for enhanced data security and fraud prevention is propelling demand for secure, robust financial consolidation software platforms.
- Regional markets show strong growth: North America leads with 38%, followed by Europe at 30%, Asia-Pacific at 20%, and Rest of the World at 12%.
Market Drivers:
Demand for Streamlined Financial Reporting:
The increasing complexity of financial reporting requirements is a primary driver for the growth of the financial consolidation software market. Organizations are seeking solutions that can simplify and expedite the consolidation process while ensuring compliance with various regulations. For instance, Oracle’s EPM Cloud offers out-of-the-box financial consolidations, enabling organizations to accelerate their financial close and deliver pre-built cash flow, balance sheet, and income statement reports, which help ensure regulatory compliance and faster decision-making. Financial consolidation software helps automate the preparation and aggregation of financial data, reducing manual errors and enhancing the speed of reporting. This demand is further intensified by the need for businesses to deliver accurate, real-time financial insights to stakeholders, investors, and regulators.
Regulatory Compliance and Risk Management:
As global financial regulations continue to evolve, companies are under increasing pressure to meet compliance standards. Financial consolidation software ensures organizations adhere to complex tax laws, accounting standards, and reporting frameworks across multiple jurisdictions. This software offers built-in features that help mitigate the risk of non-compliance, such as automated checks, validation protocols, and updates to align with changing regulations. For instance, OneStream’s unified platform automates complex consolidations for over 1,300 customers worldwide, supporting compliance with US GAAP, IFRS, and local regulations through features like automated intercompany eliminations, advanced currency translation, and cell-level audit trails. With the rising focus on corporate governance and risk management, businesses are increasingly relying on these solutions to ensure both accuracy and transparency in their financial reporting.
Cloud-Based Solutions and Digital Transformation:
The adoption of cloud-based financial consolidation software has become a significant trend, driven by the benefits of scalability, cost-effectiveness, and remote access. Cloud solutions allow businesses to reduce infrastructure costs while enabling real-time data updates and collaboration across multiple departments and regions. Furthermore, as businesses continue their digital transformation journeys, the integration of financial consolidation tools with other enterprise resource planning (ERP) and financial management systems becomes increasingly vital. The seamless exchange of data between systems ensures enhanced operational efficiency and better decision-making capabilities.
Global Expansion and Multinational Operations:
As organizations expand globally, the complexity of financial consolidation increases. Businesses with subsidiaries in multiple countries must deal with different currencies, tax laws, and accounting practices. Financial consolidation software provides the tools necessary to handle these complexities, allowing organizations to consolidate financial data from different regions into a single, unified report. This capability is crucial for multinational corporations that need to comply with various local and international financial reporting standards, making financial consolidation software an essential tool for businesses operating across borders.
Market Trends:
Cloud Adoption and SaaS Solutions:
One of the most notable trends in the financial consolidation software market is the rapid adoption of cloud-based solutions, particularly Software-as-a-Service (SaaS). Businesses are increasingly moving away from on-premise installations in favor of scalable, flexible cloud platforms. For instance, Konsolidator, a 100% cloud-based financial consolidation platform, enables finance teams to complete group consolidations in as little as 15 minutes, with automated processes that eliminate manual errors and provide a full audit trail. These solutions offer significant advantages, including reduced IT maintenance costs, automatic software updates, and enhanced collaboration across geographies. The cloud allows for real-time access to financial data, enabling quicker consolidation and reporting, which is crucial in today’s fast-paced business environment.
Artificial Intelligence and Automation:
The integration of artificial intelligence (AI) and machine learning into financial consolidation software is transforming the industry. These technologies help automate repetitive tasks, such as data entry, data validation, and financial reporting, reducing manual errors and improving accuracy. AI-driven features can also offer predictive analytics and insights, allowing businesses to anticipate trends and make informed financial decisions. As AI continues to evolve, its application in automating complex consolidation processes will become even more widespread, driving efficiency and improving decision-making capabilities.
Integration with Other Enterprise Systems:
Another current trend is the growing integration of financial consolidation software with other enterprise systems, such as enterprise resource planning (ERP), business intelligence (BI) tools, and customer relationship management (CRM) platforms. This integration ensures a seamless flow of data across various departments and functions, improving the overall accuracy and efficiency of financial reporting. For instance, Prophix One enables organizations to quickly connect their financial consolidation software with ERP, HRIS, and CRM tools without the need for third-party integration, allowing for automated reporting, planning, and forecasting across business units. By connecting financial consolidation software with other business systems, companies can reduce data silos, enhance cross-functional collaboration, and achieve a more holistic view of their financial performance.
Enhanced Data Security and Compliance Features:
As data security and regulatory compliance become even more critical, financial consolidation software vendors are incorporating advanced security features to protect sensitive financial information. With increasing cyber threats and stringent data protection laws, businesses are prioritizing software that offers encryption, role-based access controls, and secure cloud hosting environments. Enhanced compliance features ensure that businesses meet the latest regulatory requirements, reducing the risk of non-compliance and financial penalties.
Market Challenges Analysis:
Complexity of Implementation and Integration:
The implementation and integration of financial consolidation software remain one of the most significant challenges for organizations. Deploying such software often involves complex configurations to ensure that it aligns with the company’s specific financial structures, accounting systems, and reporting requirements. Many businesses struggle with the integration of these tools into their existing IT infrastructure, especially when they are using legacy systems or multiple financial software platforms. Customization is typically required to harmonize the software with various data sources, creating a process that can be both time-consuming and costly. Additionally, large enterprises with subsidiaries across different regions or operating in multiple currencies face further complexity, as the software must be capable of handling diverse financial reporting standards, tax laws, and currency conversions. The implementation phase can be disruptive to day-to-day operations, requiring significant resources in terms of both time and personnel, and often leading to delays in achieving full functionality and adoption.
Data Security and Compliance Concerns:
Data security and regulatory compliance represent another significant challenge in the financial consolidation software market. Given that these tools handle sensitive financial data, businesses must ensure they meet rigorous data protection standards to mitigate the risk of cyberattacks or data breaches. With growing concerns about privacy and the increasing volume of financial data being processed, organizations must ensure their software provides robust encryption, access controls, and data storage protocols. Compliance is also a major concern, as businesses must navigate a complex landscape of local and international regulations. For instance, Workiva’s SOX compliance software enables companies to automate internal controls documentation and risk assessment, providing audit trails and real-time monitoring to support Sarbanes-Oxley Act compliance and prevent fraudulent financial practices. For multinational companies, meeting compliance requirements such as the Sarbanes-Oxley Act in the U.S., GDPR in Europe, and other regional standards is an ongoing challenge. Software providers must continuously update their systems to reflect changes in regulatory frameworks, which can place additional strain on businesses that are already facing increasing pressure to maintain compliance. Failing to address these concerns could lead to significant legal and financial consequences.
Market Opportunities:
The financial consolidation software market presents numerous growth opportunities, driven by the increasing need for businesses to streamline financial operations, enhance data accuracy, and comply with evolving regulatory standards. As organizations continue to expand globally and diversify their operations, the complexity of managing financial consolidation across multiple subsidiaries and regions has become more challenging. This complexity creates a significant demand for automation and real-time data processing. Financial consolidation software offers businesses the ability to consolidate data from different geographies, currencies, and accounting standards seamlessly, presenting a strong opportunity for software providers. Additionally, the growing emphasis on digital transformation and the shift towards cloud-based solutions open new avenues for vendors to offer scalable, flexible, and cost-effective platforms that integrate with other enterprise systems, further enhancing operational efficiency.
Another key opportunity lies in the increasing adoption of artificial intelligence (AI) and machine learning (ML) technologies within financial consolidation software. AI-powered tools can automate routine tasks, such as data entry, validation, and reporting, while offering advanced analytics and predictive insights. This enhances decision-making processes and reduces the risk of human error. As businesses seek more intelligent solutions to improve operational efficiency, the integration of AI and ML in financial consolidation systems offers a promising market for innovation. Furthermore, the rising importance of data security and the need to protect sensitive financial information provide an opportunity for software providers to develop more secure and compliant solutions. By offering cutting-edge features such as enhanced encryption, fraud detection, and secure cloud environments, companies can address the growing demand for secure and regulatory-compliant financial consolidation tools.
Market Segmentation Analysis:
By Component
The financial consolidation software market is segmented into software and services. The software segment dominates, offering essential tools for financial data aggregation, reporting, and compliance. Services, including consulting, implementation, and support, complement the software by assisting organizations with system integration, training, and ongoing maintenance, ensuring effective utilization of the software.
By Deployment Mode
Deployment mode is categorized into on-premises and cloud-based solutions. On-premises software is preferred by organizations seeking full control over their infrastructure and data security. Cloud-based solutions, however, are gaining popularity due to their flexibility, scalability, and cost-effectiveness, allowing businesses to access real-time financial data from any location, enhancing operational efficiency.
By Organization Size
The market serves both small and medium enterprises (SMEs) and large enterprises. SMEs are increasingly adopting financial consolidation software to automate financial reporting and improve accuracy, often opting for cloud-based solutions due to their affordability. Large enterprises, managing complex financial operations across regions, typically invest in on-premises or customized cloud solutions to handle diverse financial data and meet compliance standards.
Segments:
Based on Component
- Software
- Services
Based on Deployment Mode
- On-Premises
- Cloud
Based on Organization Size
- Small and Medium Enterprises
- Large Enterprises
Based on End-User
- BFSI
- Healthcare
- Retail
- Manufacturing
- IT and Telecommunications
- Others
Based on the Geography:
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis:
North America
North America holds the largest market share in the financial consolidation software market, with a dominant share of 38% in 2024. The region's strong market position is attributed to the presence of major technology providers, including established players such as Oracle, SAP, and IBM, who offer robust financial consolidation solutions. The demand for these solutions is driven by the increasing need for businesses to comply with stringent financial regulations such as the Sarbanes-Oxley Act, alongside the growing emphasis on automation and real-time financial data processing. Additionally, the rapid adoption of cloud-based solutions and the ongoing digital transformation across various sectors further fuel the market’s growth in North America.
Europe
Europe follows North America, capturing a significant share of 30% of the market in 2024. The market growth in Europe is largely driven by the increasing complexity of financial consolidation due to multi-jurisdictional operations, tax regulations, and accounting standards across countries. As the region embraces digitalization, companies are turning to financial consolidation software to streamline reporting processes and enhance data accuracy. Furthermore, the European Union's regulatory frameworks, such as the General Data Protection Regulation (GDPR), push businesses to adopt secure, compliant financial systems. The rise in cloud-based software adoption is also a key trend, allowing companies to scale their financial operations more efficiently.
Asia-Pacific
Asia-Pacific is experiencing rapid growth in the financial consolidation software market, contributing 20% of the market share in 2024. The region’s market expansion is driven by the increasing number of businesses, especially in emerging economies like China and India, seeking to adopt modern financial management systems to cope with growing business complexities. The increasing focus on automation, enhanced reporting, and compliance due to the region’s evolving regulatory landscape is another factor driving demand. Furthermore, the shift toward cloud-based solutions in Asia-Pacific offers scalability and cost-effectiveness for businesses of all sizes. As companies continue to expand regionally and globally, the need for effective financial consolidation tools becomes more pronounced.
Rest of the World
The Rest of the World region, comprising Latin America, the Middle East, and Africa, holds the smallest market share at 12% in 2024. Despite its smaller share, the market in this region is steadily growing, driven by increased digital adoption and the push for greater financial transparency and efficiency. Businesses in these regions are increasingly turning to financial consolidation software to streamline operations and ensure compliance with global standards. In Latin America and the Middle East, the demand for cloud-based financial consolidation solutions is rising, as they offer affordable and scalable solutions for small and medium-sized enterprises (SMEs) in these developing markets.
Key Player Analysis:
- Workiva Inc.
- IBM Corporation
- Oracle Corporation
- Vena Solutions Inc.
- BOARD International S.A.
- CCH Tagetik (Wolters Kluwer)
- OneStream Software LLC
- SAP SE
- Prophix Software Inc.
- Host Analytics Inc.
- Anaplan Inc.
- BlackLine, Inc.
- Unit4
Competitive Analysis:
The financial consolidation software market is highly competitive, with several leading players offering comprehensive solutions tailored to various organizational needs. Oracle Corporation, SAP SE, IBM Corporation, Workiva Inc., Anaplan Inc., CCH Tagetik (Wolters Kluwer), BlackLine, Inc., OneStream Software LLC, Host Analytics Inc., BOARD International S.A., Unit4, Prophix Software Inc., and Vena Solutions Inc. dominate the landscape. These companies offer a diverse range of software solutions, with strong emphasis on automation, real-time data processing, and integration capabilities. Oracle and SAP maintain a competitive edge through their extensive enterprise resource planning (ERP) systems that integrate financial consolidation with broader financial management. Workiva and BlackLine are well-positioned due to their focus on cloud-based solutions and ease of use, appealing to small and medium enterprises (SMEs). OneStream and Anaplan differentiate themselves with AI-driven financial reporting and predictive analytics. As businesses continue to focus on compliance, operational efficiency, and scalability, these players will continue to innovate, enhancing their market positioning.
Recent Developments:
- In Aril 2025, CCH Tagetik (Wolters Kluwer) advanced its unified, AI-powered financial corporate management platform, expanding capabilities in financial close and consolidation, account reconciliation, ESG, global minimum tax, and integrated disclosure, with strong automation and workflow features for midsize and large organizations.
- On May 8, 2025, BlackLine announced the expansion of its Agentic AI capabilities, natively integrating AI agents into its platform to automate and enhance financial consolidation, close, and analytics processes.
- In 2024, BlackLine launched its Studio360 platform, aiming to drive future-ready financial operations for the Office of the CFO, and was recognized as a leader in accounts receivable utomation.
Market Concentration & Characteristics:
The financial consolidation software market exhibits a moderately high level of market concentration, with a few dominant players such as Oracle Corporation, SAP SE, and IBM Corporation maintaining a significant share due to their extensive product portfolios and global reach. These firms benefit from long-standing client relationships, advanced technological capabilities, and integrated enterprise solutions. However, the market also features a growing presence of specialized vendors like Workiva Inc., Anaplan Inc., and OneStream Software LLC that offer agile, cloud-based platforms tailored to specific business needs. The market is characterized by rapid technological advancements, a strong focus on cloud deployment, and the increasing integration of AI and automation tools. Enterprises across all sizes are prioritizing real-time data analysis, regulatory compliance, and operational efficiency, which continues to drive demand. As financial reporting becomes more complex, especially for multinational operations, the need for scalable and secure financial consolidation solutions defines the competitive dynamics of this evolving market.
Report Coverage
The research report offers an in-depth analysis based on Component, Deployment Mode, Organization Size, End-User and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Cloud-based financial consolidation solutions will continue to gain traction across enterprises of all sizes.
- Integration with advanced analytics and AI will enhance financial planning and forecasting capabilities.
- Demand for real-time data consolidation and reporting will shape product development.
- Regulatory compliance requirements will drive ongoing software updates and enhancements.
- Cross-border financial operations will increase the need for multi-currency and multi-GAAP support.
- Mid-sized companies will adopt financial consolidation tools to improve operational efficiency.
- Cybersecurity features will become a key differentiator among solution providers.
- Partnerships between software vendors and ERP providers will strengthen solution ecosystems.
- Mobile and remote accessibility will become essential for global finance teams.
- User-friendly interfaces and low-code customization options will influence customer preferences.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Demand for Streamlined Financial Reporting
The increasing complexity of financial reporting requirements is pushing organizations to adopt financial consolidation software that automates data aggregation and reporting, reducing manual errors and accelerating the financial close process.
Regulatory Compliance and Risk Management
Evolving global financial regulations require companies to ensure compliance with diverse tax laws and accounting standards, driving adoption of software that offers automated compliance checks, audit trails, and up-to-date regulatory features.
Cloud-Based Solutions and Digital Transformation
The shift toward cloud-based financial consolidation software provides scalability, flexibility, and cost savings, enabling real-time data access and collaboration across geographically dispersed teams, which is especially valuable as businesses digitize their operations.
Global Expansion and Multinational Operations
As organizations expand internationally, the need to consolidate financial data across multiple currencies, tax regimes, and accounting standards increases, making robust consolidation software essential for accurate, unified reporting.
Enhanced Data Security and Fraud Prevention
With rising concerns over data breaches and financial fraud, companies are prioritizing secure financial consolidation platforms that offer advanced encryption, role-based access controls, and compliance with data protection regulations.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Financial Consolidation Software market?
What factors are driving the growth of the Financial Consolidation Software market?
What are some challenges faced by the Financial Consolidation Software market?
Who are the major players in the Financial Consolidation Software market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By End-User
- 1.2.1 BFSI
- 1.2.2 Healthcare
- 1.2.3 Retail
- 1.2.4 Manufacturing
- 1.2.5 IT and Telecommunications
- 1.2.6 Others
- 1.3 By Component
- 1.3.1 Software
- 1.3.2 Services
- 1.4 By Deployment Mode
- 1.4.1 On-Premises
- 1.4.2 Cloud
- 1.5 By Organization Size
- 1.5.1 Small and Medium Enterprises
- 1.5.2 Large Enterprises
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 2,701.45 million → 2032: USD 6,407.3 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Financial Consolidation Software Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Financial Consolidation Software Market Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Supply Chain Structure and Procurement Trends
- 5.4 Supply-Demand Gap and Bottlenecks
- 5.5 Import Dependence and Sourcing Structure
- 5.6 Regional Supply and Demand Concentration
Chapter 6 Global Financial Consolidation Software Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Pricing by Product and Market Segment
- 6.5 Geographic Pricing Differences
- 6.6 Key Input, Energy, Labor and Logistics Costs
- 6.7 Contract Pricing and Purchasing Models
- 6.8 Pricing Sensitivity and Competitive Positioning
- 6.9 Price, Margin and Profitability Implications
Chapter 7 Global Financial Consolidation Software Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Financial Consolidation Software Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Financial Consolidation Software Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Data Protection, AI and Cybersecurity Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Financial Consolidation Software Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Financial Consolidation Software Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 2,701.45 million → 2032: USD 6,407.3 million)
- 11.1.2 Historical Market Size
- 11.1.3 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 CAGR and Year-on-Year Growth
- 11.2.3 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Financial Consolidation Software Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By End-User - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Base-Year Market Share, 2024
- 12.3.5 Segment CAGR and Growth Drivers
- 12.3.6 Subsegment Market Size and Forecast
- 12.3.6.1 BFSI
- 12.3.6.2 Healthcare
- 12.3.6.3 Retail
- 12.3.6.4 Manufacturing
- 12.3.6.5 IT and Telecommunications
- 12.3.6.6 Others
- 12.3.7 Subsegment Pricing and Adoption Trends
- 12.3.8 Leading Suppliers and Competition
- 12.3.9 Regional Demand and Opportunities
- 12.4 By Component - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Base-Year Market Share, 2024
- 12.4.5 Segment CAGR and Growth Drivers
- 12.4.6 Subsegment Market Size and Forecast
- 12.4.6.1 Software
- 12.4.6.2 Services
- 12.4.7 Subsegment Pricing and Adoption Trends
- 12.4.8 Leading Suppliers and Competition
- 12.4.9 Regional Demand and Opportunities
- 12.5 By Deployment Mode - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Base-Year Market Share, 2024
- 12.5.5 Segment CAGR and Growth Drivers
- 12.5.6 Subsegment Market Size and Forecast
- 12.5.6.1 On-Premises
- 12.5.6.2 Cloud
- 12.5.7 Subsegment Pricing and Adoption Trends
- 12.5.8 Leading Suppliers and Competition
- 12.5.9 Regional Demand and Opportunities
- 12.6 By Organization Size - Market Size and Forecast, 2024-2032
- 12.6.1 Segment Definition and Scope
- 12.6.2 Historical Market Size
- 12.6.3 Revenue Forecast, 2024-2032
- 12.6.4 Base-Year Market Share, 2024
- 12.6.5 Segment CAGR and Growth Drivers
- 12.6.6 Subsegment Market Size and Forecast
- 12.6.6.1 Small and Medium Enterprises
- 12.6.6.2 Large Enterprises
- 12.6.7 Subsegment Pricing and Adoption Trends
- 12.6.8 Leading Suppliers and Competition
- 12.6.9 Regional Demand and Opportunities
- 12.7 Segment Growth Comparison
- 12.8 Segment Attractiveness and Priority Matrix
Chapter 13 Global Financial Consolidation Software End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Financial Consolidation Software Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Financial Consolidation Software Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Financial Consolidation Software Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Oracle Corporation
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Financial Performance and Investment
- 18.2.6 Market Share and Competitive Position
- 18.2.7 Technology and Innovation Capabilities
- 18.2.8 Strategic Alliances or Partnerships
- 18.2.9 Recent Developments
- 18.2.10 Growth Strategy and Outlook
- 18.3 SAP SE
- 18.4 IBM Corporation
- 18.5 Workiva Inc.
- 18.6 OneStream Software LLC
- 18.7 CCH Tagetik (Wolters Kluwer)
- 18.8 BlackLine, Inc.
- 18.9 Anaplan Inc.
- 18.10 Prophix Software Inc.
- 18.11 Vena Solutions Inc.
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

