
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Solid Vacuum Reclosers Market Size 2024 | USD 2110 Million |
| Solid Vacuum Reclosers Market, CAGR | 5.5% |
| Solid Vacuum Reclosers Market Size 2032 | USD 3238.1 Million |
Market Overview:
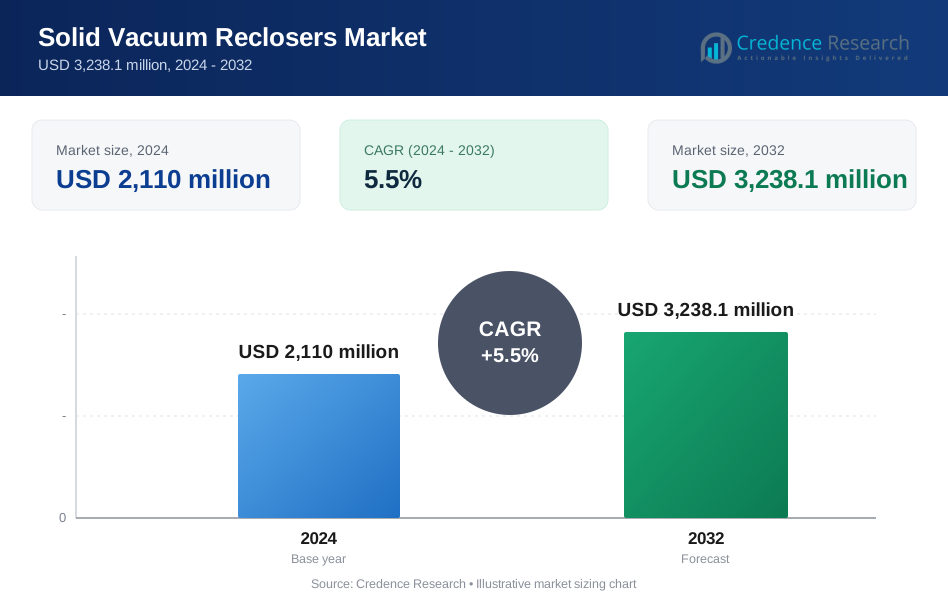
The Solid Vacuum Reclosers Market is projected to grow from USD 2110 million in 2024 to an estimated USD 3238.1 million by 2032, with a compound annual growth rate (CAGR) of 5.5% from 2024 to 2032.
One of the most significant growth drivers of the solid vacuum reclosers market is the global push toward grid modernization. Aging electrical infrastructure in regions like North America and Europe is undergoing substantial upgrades, with utilities investing in digital substations and intelligent distribution equipment to improve reliability and efficiency. Solid vacuum reclosers are a critical component of this transformation, enabling faster fault isolation and restoring power with minimal manual intervention. In parallel, the rapid expansion of renewable energy sources such as solar and wind has necessitated the integration of advanced protection devices capable of managing fluctuating loads. Solid vacuum reclosers offer the ideal solution by maintaining grid stability in distributed generation scenarios. In emerging economies, particularly across Asia-Pacific, rising electricity consumption due to urbanization, industrial growth, and rural electrification is fueling the deployment of distribution automation systems, with solid vacuum reclosers playing a central role in this expansion. Regulatory mandates around safety, efficiency, and emissions also encourage utilities to phase out oil-insulated reclosers and adopt vacuum alternatives. Although the initial investment is relatively high and retrofitting with existing infrastructure can pose challenges, the long-term benefits in terms of reliability, reduced downtime, and lower maintenance costs continue to validate these investments.
Regionally, North America currently dominates the solid vacuum reclosers market, accounting for nearly half of the global revenue share. This leadership stems from large-scale smart grid initiatives, favorable regulatory policies, and a well-established electric utility sector committed to improving system reliability. The U.S. Department of Energy’s continued funding of grid modernization programs, including the deployment of recloser systems that support automation and real-time control, significantly contributes to market growth. Europe follows closely, with strong demand driven by sustainability targets, rising renewable integration, and the need for improved fault isolation in aging grid networks. Countries like Germany, the United Kingdom, and France are accelerating their transition to smart distribution infrastructure, boosting the demand for vacuum-based reclosers. However, the Asia-Pacific region is expected to witness the fastest growth over the forecast period, with countries such as China, India, and Southeast Asian nations investing heavily in power infrastructure to support industrialization and urban development. In China, for example, ongoing electrification efforts and rural grid expansions create vast opportunities for recloser deployment. India’s state-owned utilities are also increasingly adopting vacuum reclosers to enhance rural and semi-urban distribution systems. Latin America and the Middle East & Africa, though currently holding smaller market shares, are gradually emerging as promising markets due to expanding energy access initiatives and increased investments in grid stability and automation.
Market Insights:
- The solid vacuum reclosers market is projected to grow from USD 2,110 million in 2024 to USD 3,238.1 million by 2032, registering a CAGR of 5.5%, driven by increasing investments in smart grid modernization and resilient distribution networks.
- The push to replace aging infrastructure in North America and Europe is accelerating adoption, with utilities upgrading to digital substations that rely on solid vacuum reclosers for rapid fault isolation and reduced downtime.
- Rising deployment of solar and wind energy has created a need for advanced protection devices; solid vacuum reclosers are being adopted to manage bidirectional power flows and maintain grid stability under variable loads.
- Regulatory mandates targeting improved safety, operational efficiency, and environmental compliance are prompting a shift from oil-insulated reclosers to vacuum-based alternatives with sealed, low-maintenance designs.
- Emerging markets in Asia-Pacific, Latin America, and Africa are adopting solid vacuum reclosers to support urbanization, industrial growth, and rural electrification, enhancing grid reliability under diverse operating conditions.
- Despite strong demand, high initial investment and integration complexity remain key challenges, particularly for smaller utilities lacking capital or digital infrastructure readiness.
- North America currently leads the market due to federal funding and widespread grid automation, while Asia-Pacific is expected to witness the fastest growth driven by infrastructure development in countries like China and India.
Market Drivers:
Expansion of Smart Grid Infrastructure and Automation Technologies:
The solid vacuum reclosers market is gaining traction due to the rapid modernization of electrical grids across the globe. Utility companies are transitioning from conventional grid systems to smart, automated infrastructure capable of real-time monitoring and intelligent control. This shift is essential to improve outage response times, reduce manual intervention, and enhance grid reliability. Solid vacuum reclosers are integral to these advanced networks, offering automatic fault detection and isolation capabilities that help minimize service disruptions. They enable seamless integration with supervisory control and data acquisition (SCADA) systems and support remote operation, which reduces labor and maintenance costs. The growing emphasis on digital grid transformation is creating sustained demand for high-performance recloser technologies.
- For instance, The RER620 is designed for protection, control, measurement, and supervision of utility distribution feeders and industrial power systems.
Rising Integration of Renewable Energy and Distributed Generation:
The increasing deployment of distributed energy resources such as solar and wind farms is driving the need for flexible and resilient distribution systems. Renewable power generation introduces variability and bidirectional power flows, which require fast and intelligent fault response solutions. Solid vacuum reclosers serve this role effectively by managing load fluctuations, clearing faults quickly, and supporting safe re-energization. Their design is suited for modern distribution networks that connect distributed generation at various voltage levels. The solid vacuum reclosers market is benefiting from widespread investment in clean energy infrastructure, especially in regions prioritizing net-zero carbon goals. As governments accelerate renewable integration, demand for these reclosers continues to rise.
- For instance, The GridShield recloser is designed for up to 10,000 full-load operations and offers modular pole assembly for flexible installation.
Regulatory Pressures and Replacement of Aging Grid Equipment:
Many countries are introducing stricter regulations on grid reliability, safety, and environmental performance, prompting utilities to replace outdated infrastructure. Older reclosers that use oil-based insulation pose safety risks and require frequent maintenance, increasing operational expenses. Solid vacuum reclosers offer a safer, more efficient alternative with sealed units that reduce fire hazards and environmental exposure. They also comply with evolving industry standards related to arc fault containment and eco-friendly design. The solid vacuum reclosers market is seeing strong replacement demand across developed economies where aging grid components must be modernized to meet current and future energy requirements. This regulatory landscape is acting as a catalyst for the widespread adoption of vacuum-based switching devices.
Urbanization, Electrification, and Reliability Demands in Emerging Markets:
Emerging economies are investing heavily in power distribution infrastructure to support urbanization, rural electrification, and industrial expansion. With electricity demand rising sharply, especially in Asia-Pacific and parts of Latin America and Africa, utilities need robust, automated solutions that can operate reliably in diverse environments. Solid vacuum reclosers meet this need with their compact footprint, low maintenance profile, and adaptability to various installation conditions. The market is gaining momentum in these regions where grid extension and quality-of-service improvements are policy priorities. It offers an ideal solution for networks that require modern fault protection while operating under limited technical and financial resources. The solid vacuum reclosers market stands to benefit significantly from this infrastructural transformation.
Market Trends:
Shift Toward Modular and Compact Product Designs:
Manufacturers are increasingly focusing on the development of compact and modular solid vacuum reclosers to address space constraints in urban and retrofit applications. These designs allow for easier installation on existing pole structures or inside compact enclosures, improving deployment speed and reducing civil infrastructure requirements. Utilities are prioritizing equipment that offers operational flexibility and supports future upgrades without full system overhauls. Compact reclosers also facilitate deployment in densely populated areas where traditional switchgear poses space and logistical challenges. The solid vacuum reclosers market is witnessing steady growth in demand for such adaptable systems. It is enabling operators to modernize without major physical reconfigurations to their distribution networks.
- For instance, ABB’s GridShield recloser uses a modular design with hydrophobic cycloaliphatic epoxy (HCEP) insulation, which enhances reliability and durability in harsh environments.
Integration of IoT and Advanced Data Analytics:
Digital transformation is reshaping how utilities manage and maintain their networks, with solid vacuum reclosers becoming part of broader Internet of Things (IoT) ecosystems. These reclosers are now being embedded with sensors and communication modules that transmit real-time data on voltage, current, and breaker status. Utilities are leveraging this information to perform predictive maintenance, optimize fault management, and enhance system diagnostics. The incorporation of analytics tools allows operators to identify trends, track asset performance, and make data-driven decisions to improve uptime. The solid vacuum reclosers market is aligning with this trend by integrating intelligent functions directly into hardware. It is contributing to the shift from reactive to proactive grid management.
- For instance, The RER620 supports advanced data collection, including voltage metering, event and fault recording, breaker condition monitoring, and trip-circuit monitoring.
Increased Use of Eco-Friendly and Sustainable Materials:
Environmental sustainability has become a defining factor in equipment selection and procurement policies within the utility sector. Manufacturers are responding by using recyclable materials and eliminating hazardous substances in the construction of solid vacuum reclosers. Designs that reduce lifecycle emissions and minimize environmental impact are gaining preference, especially in regions with strict environmental regulations. Vacuum technology already offers a cleaner alternative to oil-based insulation, and current trends are extending this benefit through sustainable material sourcing and lower energy consumption during operation. The solid vacuum reclosers market is responding to utility preferences for greener solutions. It is reinforcing its position as a sustainable technology choice in modern power distribution.
Growing Adoption of Cloud-Based Monitoring Platforms:
Utilities are increasingly deploying cloud-based platforms to centralize control and monitoring of distributed assets, including reclosers. These platforms facilitate real-time visibility into the performance of field devices across multiple locations and allow operators to make remote adjustments. Cloud integration enhances system scalability, making it easier to add new devices and adapt to evolving network requirements. Service providers are offering solid vacuum reclosers that come pre-configured for seamless connectivity with cloud-based asset management systems. The solid vacuum reclosers market is evolving in tandem with this trend toward virtualization and remote operations. It is enabling utilities to streamline workflows and improve grid responsiveness through centralized digital control.
Market Challenges Analysis:
High Initial Costs and Budget Constraints Among Utilities:
The upfront cost of deploying solid vacuum reclosers remains a major barrier, particularly for utilities operating under tight capital budgets. These systems, while offering long-term operational advantages, require significant investment in hardware, communication modules, and installation infrastructure. Smaller utilities and those in developing regions often face difficulty justifying these expenditures without external funding or regulatory incentives. The complexity of integrating solid vacuum reclosers with legacy equipment further adds to the total implementation cost. The solid vacuum reclosers market faces resistance from stakeholders focused on minimizing immediate capital outlay rather than long-term savings. It must address these concerns through cost-effective product variants and flexible financing options.
Technical Integration and Skill Gaps in Workforce:
Implementing solid vacuum reclosers within existing grid systems requires technical expertise in communication protocols, system configuration, and real-time monitoring tools. Many utilities struggle with limited in-house capabilities to support digital recloser technologies, particularly in regions where grid automation remains nascent. A shortage of trained technicians and engineers creates delays in deployment, reduces operational efficiency, and increases reliance on third-party service providers. Compatibility issues with legacy SCADA systems or outdated infrastructure can cause integration failures or require expensive retrofitting. The solid vacuum reclosers market must navigate these challenges by supporting comprehensive training programs and offering user-friendly interfaces. It also depends on strong vendor-utility partnerships to ensure smooth commissioning and long-term maintenance.
Market Opportunities:
Rural Electrification and Grid Expansion in Emerging Economies:
Governments across Asia-Pacific, Africa, and Latin America are accelerating rural electrification efforts to ensure universal access to electricity. These initiatives require cost-effective, low-maintenance, and reliable switching equipment suitable for remote and challenging environments. Solid vacuum reclosers offer an ideal solution by enabling automatic fault isolation and rapid power restoration with minimal human intervention. The solid vacuum reclosers market stands to benefit from large-scale infrastructure programs focused on expanding and upgrading distribution networks. It can play a pivotal role in enhancing power quality and reliability in underserved regions. Manufacturers that tailor their offerings to meet the needs of these high-growth areas can unlock significant revenue potential.
Growing Demand for Resilient Infrastructure Against Climate Risks:
Climate change is increasing the frequency of extreme weather events, which disrupt power supply and damage outdated grid infrastructure. Utilities are investing in resilient distribution systems capable of withstanding physical and electrical stress. Solid vacuum reclosers, with sealed construction and robust fault-handling capability, provide a dependable solution for storm-prone and high-risk zones. The solid vacuum reclosers market is well-positioned to support resilience planning across utility networks. It creates opportunities for suppliers to collaborate with governments and disaster management agencies on grid hardening projects. Long-term climate adaptation goals will continue to drive demand for rugged and automated recloser technologies.
Market Segmentation Analysis:
By Type
The solid vacuum reclosers market includes single-phase, three-phase, and triple-single reclosers. Single-phase units are widely used in rural or low-load areas due to their simplicity and cost efficiency. Three-phase reclosers dominate urban and industrial grids for handling balanced power loads. Triple-single reclosers offer independent phase operation, making them suitable for complex or unbalanced network conditions.
- For instance, Minimum phase trip values can be set from 20 to 2,000 A, supporting a wide range of network conditions and operational requirements.
By Application
Distribution networks represent the primary application area, where reclosers support fault isolation and service continuity. Substation protection uses them to safeguard high-value equipment and maintain stability. Grid automation is a growing segment, driven by demand for intelligent, remote-controlled switching. Remote and rural electrification projects prefer solid vacuum reclosers for their low-maintenance, high-reliability performance in hard-to-reach locations.
- For instance, The RER620 and GridShield reclosers are applied in overhead line protection, cable feeder protection, and distribution substations, offering up to four shots to lockout, cold load pickup, and fault current indication.
By End User
Utilities form the largest end-user segment, driven by large-scale grid modernization programs. Industrial facilities adopt reclosers to protect internal distribution and reduce downtime. Commercial buildings are emerging users, requiring advanced protection for critical infrastructure.
By Voltage Rating
Medium voltage reclosers dominate the market, serving standard distribution needs. High voltage variants are gaining adoption in larger grids and industrial operations.
By Technology/Features
Microprocessor-based controls enhance protection speed and decision-making. Remote monitoring and automation reduce manual intervention. Smart grid integration enables interoperability with digital platforms and real-time diagnostics.
Segmentation:
By Type
- Single-phase solid vacuum reclosers
- Three-phase solid vacuum reclosers
- Triple-single solid vacuum reclosers
By Application
- Distribution networks
- Substation protection
- Grid automation
- Remote and rural electrification
By End User
- Utilities
- Industrial facilities
- Commercial buildings
By Voltage Rating
- Medium voltage
- High voltage
By Technology/Features
- Microprocessor-based control
- Remote monitoring and automation
- Smart grid integration
By Region
- North America
- U.S.
- Canada
- Mexico
- Europe
- UK
- France
- Germany
- Italy
- Spain
- Russia
- Belgium
- Netherlands
- Austria
- Sweden
- Poland
- Denmark
- Switzerland
- Rest of Europe
- Asia Pacific
- China
- Japan
- South Korea
- India
- Australia
- Thailand
- Indonesia
- Vietnam
- Malaysia
- Philippines
- Taiwan
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Peru
- Chile
- Colombia
- Rest of Latin America
- Middle East
- UAE
- KSA
- Israel
- Turkey
- Iran
- Rest of Middle East
- Africa
- Egypt
- Nigeria
- Algeria
- Morocco
- Rest of Africa
Regional Analysis:
North America and Europe Lead with Grid Modernization Initiatives
North America holds the largest share of the solid vacuum reclosers market, accounting for approximately 46% of global revenue. Strong utility investment in smart grid infrastructure, coupled with aging electrical networks, is driving widespread deployment across the U.S. and Canada. Government funding and regulatory support from agencies like the U.S. Department of Energy continue to promote adoption of automated fault protection systems. Utilities are replacing outdated oil-insulated equipment with vacuum-based solutions to improve safety, reduce maintenance, and support digital grid platforms. Europe holds an estimated 23% market share, led by countries like Germany, the UK, and France. Demand in the region is driven by decarbonization goals, high renewable integration, and the need to modernize outdated substation and distribution infrastructure.
Asia-Pacific Emerges as the Fastest-Growing Region
The Asia-Pacific region represents around 20% of the solid vacuum reclosers market but is projected to register the highest growth rate through the forecast period. Governments across China, India, and Southeast Asia are investing in rural electrification, smart distribution systems, and industrial grid expansion. China is rapidly deploying reclosers to support grid reliability in urban, suburban, and remote regions, while India's state-owned utilities are actively incorporating vacuum technology into rural and semi-urban feeder systems. High electricity demand, infrastructure upgrades, and growing renewable capacity are major drivers in the region. It offers a high-volume, cost-sensitive market that favors compact, low-maintenance reclosers with intelligent features. Regional manufacturers are also expanding production capabilities to meet domestic and export demand.
Latin America and Middle East & Africa Offer Emerging Potential
Latin America and the Middle East & Africa together account for approximately 11% of the global market share, with steady growth supported by power access initiatives and urban expansion. Countries such as Brazil, Mexico, South Africa, and the UAE are focusing on improving grid reliability and reducing power outages, prompting investments in automated switching devices. The solid vacuum reclosers market is gradually gaining momentum in these regions due to the need for remote monitoring, low-maintenance operation, and resilience against environmental challenges. Utilities in these markets prioritize cost-effectiveness and long lifecycle performance. As energy demand increases and modernization efforts progress, the adoption of vacuum reclosers is expected to accelerate across both public and private sector distribution networks.
Key Player Analysis:
- ABB Ltd
- Eaton Corporation plc
- Siemens AG
- Schneider Electric
- Tavrida Electric AG
- NOJA Power Switchgear Pty Ltd
- Electrical Connections Ltd
- ESTECO SpA
- ZENSOL AUTOMATION INC.
- Arteche Group
- General Electric (GE)
- Mitsubishi Electric
- Togami Electric
- G&W Electric
Competitive Analysis:
The solid vacuum reclosers market is highly competitive, with key players focusing on technological innovation, product reliability, and strategic partnerships. Companies like ABB, Eaton, Siemens, and Schneider Electric lead the market through strong global presence, advanced engineering capabilities, and integrated smart grid solutions. Tavrida Electric, NOJA Power, and G&W Electric specialize in recloser technologies and offer tailored solutions for medium- and high-voltage applications. Emerging players and regional manufacturers are targeting cost-sensitive markets with compact, digitally enabled devices. The solid vacuum reclosers market sees active investment in R&D to enhance automation, remote control, and energy efficiency. It is also witnessing a trend toward cloud-based monitoring and predictive diagnostics. Competitive differentiation is driven by performance features, system compatibility, after-sales service, and pricing strategies. As utilities prioritize reliability and smart grid integration, leading companies are expanding product lines, strengthening supply chains, and forming alliances to secure long-term contracts across global utility sectors.
Recent Developments:
- In May 2025, ABB Ltd announced the acquisition of BrightLoop, a French innovator in advanced power electronics. This move will expand ABB’s capabilities in delivering compact, high-efficiency energy systems for demanding environments, supporting its electrification strategy across industrial and mobility sectors. BrightLoop’s modular, software-defined power converters are recognized for their reliability and performance in harsh applications, including grid and distribution systems.
- In March 2025, ABB deployed its RER620 reclosers in a 33 kV distribution project in Southeast Asia, resulting in improved grid reliability and reduced outage times. The RER620 reclosers offer advanced protection and control features for medium-voltage networks, supporting grid modernization and the integration of renewables.
- In May 2025, Schneider Electric and its EcoXpert partner Advanced Power Technology won the DCS Award for Data Centre Consolidation/Upgrade Project of the Year, recognizing their deployment of a modular data centre with resilient and energy-efficient infrastructure at The Pirbright Institute.
Market Concentration & Characteristics:
The solid vacuum reclosers market is moderately concentrated, with a mix of global conglomerates and specialized manufacturers competing across regional and application-specific segments. It features strong participation from companies like ABB, Siemens, Eaton, and Schneider Electric, which hold significant market share due to their broad product portfolios and established customer networks. The market favors technologically advanced products with remote operability, smart grid compatibility, and minimal maintenance. It serves a utility-dominated customer base, where purchasing decisions are driven by long-term reliability, compliance, and lifecycle cost. The solid vacuum reclosers market exhibits high entry barriers due to the need for technical expertise, capital-intensive manufacturing, and certifications. It is characterized by long sales cycles, contract-based procurement, and a growing preference for digital functionality and predictive monitoring. Competitive dynamics are shaped by innovation, service capabilities, and adaptability to evolving grid modernization standards.
Report Coverage:
The research report offers an in-depth analysis based on By Type, By Application, By End User, By Voltage Rating, By Technology/Features and By Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- Growing demand for grid reliability will drive sustained investment in solid vacuum reclosers across both developed and emerging regions.
- Rising adoption of renewable energy sources will increase the need for reclosers capable of managing intermittent power flow.
- Expansion of smart grids will accelerate integration of intelligent reclosers with advanced monitoring and communication capabilities.
- Utilities will continue replacing aging oil-insulated switchgear with vacuum-based alternatives to meet regulatory and safety standards.
- Asia-Pacific is expected to lead in volume growth due to large-scale electrification and infrastructure modernization.
- Technological innovations in microprocessor control and IoT connectivity will enhance operational efficiency and fault response.
- Manufacturers will focus on compact, modular designs to address space constraints in urban and retrofit applications.
- Growing use of remote and cloud-based asset management platforms will increase demand for reclosers with real-time data capabilities.
- Strategic partnerships and government-funded grid upgrade projects will create new business opportunities for key players.
- Demand for high-voltage reclosers will rise in industrial and utility-scale applications requiring extended protection coverage.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Solid Vacuum Reclosers Market?
What factors are driving the growth of the Solid Vacuum Reclosers Market?
What are the key segments within the Solid Vacuum Reclosers Market?
What are some challenges faced by the Solid Vacuum Reclosers Market?
Who are the major players in the Solid Vacuum Reclosers Market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Solid Vacuum Reclosers Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Solid Vacuum Reclosers Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 2,110 million → 2032: USD 3,238.1 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Solid Vacuum Reclosers Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Solid Vacuum Reclosers Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Solid Vacuum Reclosers Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Solid Vacuum Reclosers Market Drivers
- 3.3 Solid Vacuum Reclosers Market Restraints & Challenges
- 3.4 Solid Vacuum Reclosers Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Solid Vacuum Reclosers Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Solid Vacuum Reclosers Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Solid Vacuum Reclosers category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Solid Vacuum Reclosers Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Solid Vacuum Reclosers Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Solid Vacuum Reclosers market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Solid Vacuum Reclosers Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Solid Vacuum Reclosers Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Solid Vacuum Reclosers Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Solid Vacuum Reclosers (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Solid Vacuum Reclosers Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Solid Vacuum Reclosers Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Solid Vacuum Reclosers Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Solid Vacuum Reclosers Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Solid Vacuum Reclosers Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Solid Vacuum Reclosers Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Solid Vacuum Reclosers Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Solid Vacuum Reclosers Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Solid Vacuum Reclosers Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
