
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| South Korea Vendor Neutral Archives (VNA) and Picture Archiving and Communication Systems (PACS) Market Size 2024 | USD 187.86 million |
| JSouth Korea Vendor Neutral Archives (VNA) and Picture Archiving and Communication Systems (PACS) Market, CAGR | 8.38% |
| South Korea Vendor Neutral Archives (VNA) and Picture Archiving and Communication Systems (PACS) Market Size 2032 | USD 357.56 million |
Market Overview
South Korea Vendor Neutral Archives (VNA) and Picture Archiving and Communication Systems (PACS) market size was valued at USD 187.86 million in 2024 and is anticipated to reach USD 357.56 million by 2032, at a CAGR of 8.38% during the forecast period (2024-2032).
The South Korea Vendor Neutral Archives (VNA) and Picture Archiving and Communication Systems (PACS) market is experiencing robust growth, driven by the increasing adoption of digital healthcare solutions, rising demand for efficient data management, and government initiatives supporting healthcare IT infrastructure. As hospitals and diagnostic centers transition to digital imaging and data interoperability, the need for scalable, vendor-agnostic storage systems becomes critical. The growing geriatric population and a corresponding rise in chronic disease prevalence are further accelerating imaging volumes, necessitating streamlined archiving and retrieval solutions. Moreover, advancements in artificial intelligence and cloud integration are reshaping workflow efficiency, enabling real-time access and remote diagnostics. Trends also show a shift toward enterprise imaging platforms that unify various imaging modalities under a single interface, enhancing clinical decision-making and reducing operational silos. These factors collectively position VNA and PACS technologies as integral components of South Korea’s evolving healthcare ecosystem.
The South Korea Vendor Neutral Archives (VNA) and Picture Archiving and Communication Systems (PACS) market is primarily concentrated in major urban regions, particularly in the Seoul Metropolitan Area, Gyeonggi Province, and Busan. These regions host the majority of the country’s advanced healthcare infrastructure, including hospitals, diagnostic centers, and research institutions, which drive demand for modern imaging and data management solutions. Key players in this market include global technology leaders like Fujifilm Holdings Corporation, Canon Medical Systems, and GE Healthcare, alongside regional companies such as INFINITT Healthcare and Konica Minolta Healthcare. These companies provide innovative PACS and VNA solutions tailored to the needs of healthcare providers, focusing on interoperability, AI integration, and cloud-based deployment models. The competition in the market is intensified by the increasing trend toward digital health transformation, which pushes providers to adopt cutting-edge imaging systems that enhance clinical workflows and patient outcomes.
Market Insights
- The South Korea Vendor Neutral Archives (VNA) and Picture Archiving and Communication Systems (PACS) market was valued at USD 187.86 million in 2024 and is expected to reach USD 357.56 million by 2032, growing at a CAGR of 8.38% during the forecast period.
- The Global VNA and PACS market was valued at USD 4,411.05 million in 2024 and is expected to reach USD 8,046.15 million by 2032, growing at a CAGR of 7.80% from 2024 to 2032.
- The market is driven by the increasing adoption of digital healthcare technologies and the need for seamless data sharing across healthcare facilities.
- Rising healthcare spending, an aging population, and growing diagnostic imaging volumes are contributing to market growth.
- Cloud-based and hybrid PACS/VNA solutions are seeing a surge due to their scalability, remote access, and cost-efficiency.
- Key players in the market include Fujifilm, Canon Medical Systems, GE Healthcare, and INFINITT Healthcare.
- Market restraints include high implementation costs, integration complexities, and concerns over data privacy.
- The Seoul Metropolitan Region, Gyeonggi Province, and Busan dominate the market, with strong healthcare infrastructure and digital health initiatives.
Report Scope
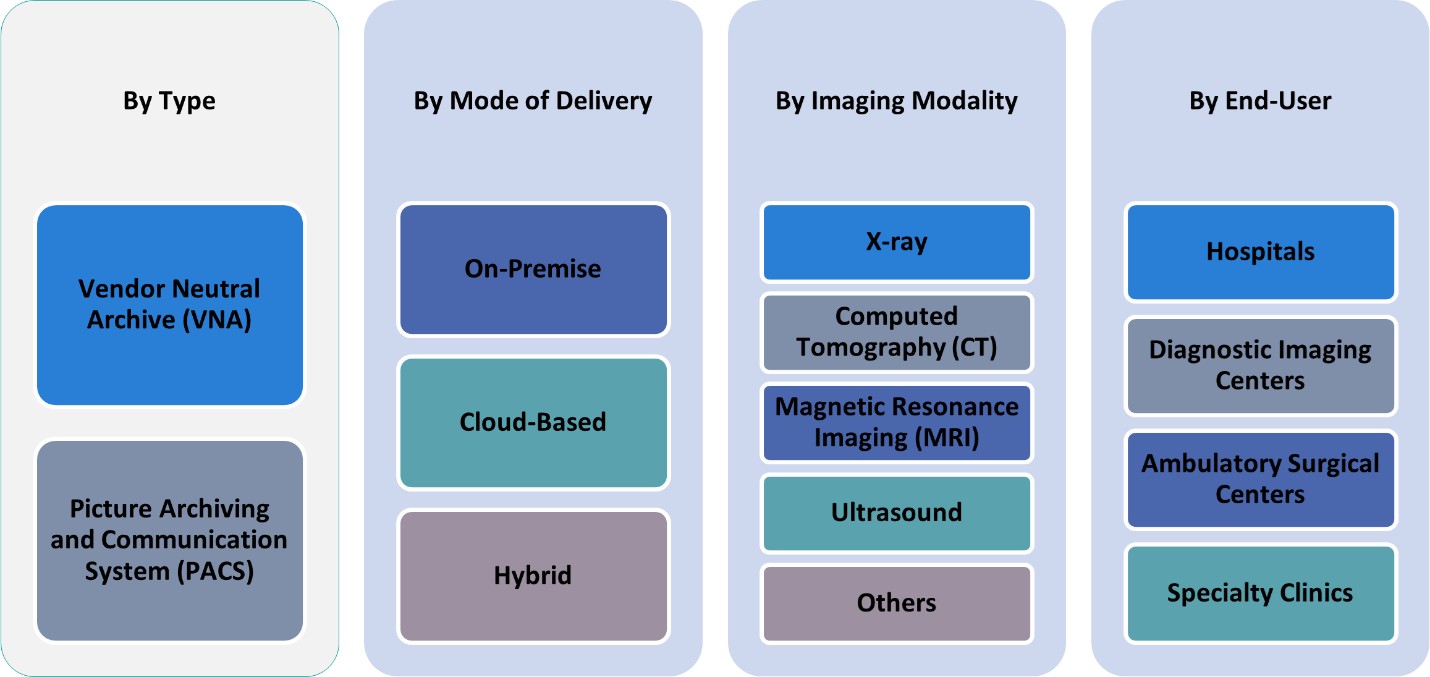
This report segments the South Korea Vendor Neutral Archives (VNA) and Picture Archiving and Communication Systems (PACS) Market as follows:
Market Drivers
Growing Demand for Digital Healthcare Infrastructure
One of the primary drivers of the South Korean VNA and PACS market is the country’s ongoing investment in digital healthcare infrastructure. South Korea’s advanced IT ecosystem and government-backed healthcare digitization programs are accelerating the adoption of medical imaging technologies. For instance, South Korea’s National Healthcare Information Infrastructure (NHII) supports data sharing and preventive care, with approximately 70% of Koreans undergoing regular health checkups. Hospitals and diagnostic centers are increasingly integrating digital systems to improve operational efficiency, reduce paperwork, and enhance patient care delivery. As healthcare providers transition to electronic health records (EHRs) and integrated IT environments, the demand for robust, vendor-neutral data storage and seamless image archiving becomes essential. VNA and PACS solutions provide the interoperability and flexibility needed to support these digital transformation goals.
Rising Imaging Volumes Due to Aging Population
South Korea’s rapidly aging population is contributing to a higher incidence of age-related health conditions, which in turn drives demand for diagnostic imaging services. The increasing need for MRI, CT, and ultrasound procedures generates large volumes of medical images that must be efficiently stored, managed, and accessed. For instance, South Korea is projected to become a “super-aged society” by 2025, with over 20% of its population aged 65 or older, increasing the demand for chronic disease management and diagnostic imaging. VNA and PACS platforms offer scalable solutions that can handle high imaging workloads while ensuring data integrity and quick retrieval. This surge in imaging volumes makes it critical for healthcare providers to adopt systems that support long-term storage and centralized image access across multiple departments and facilities.
Shift Toward Interoperability and Vendor Neutrality
Interoperability has become a cornerstone of modern healthcare IT systems. Traditional PACS systems often lock users into proprietary formats, limiting cross-platform compatibility. South Korean healthcare institutions are increasingly prioritizing VNA solutions that enable seamless integration across different imaging devices and hospital information systems (HIS). The ability to access, manage, and share images across various departments and facilities-regardless of vendor enhances clinical collaboration and speeds up diagnosis and treatment. This trend toward vendor neutrality is also driven by the need to future-proof investments and reduce long-term costs associated with system upgrades or replacements.
Technological Advancements and AI Integration
The integration of artificial intelligence (AI), cloud computing, and advanced analytics into PACS and VNA solutions is another key growth driver in South Korea. AI-enabled imaging platforms assist in image analysis, anomaly detection, and workflow automation, significantly reducing radiologists’ workload and enhancing diagnostic accuracy. Cloud-based VNAs provide scalable storage, remote accessibility, and disaster recovery capabilities, all of which are increasingly valued in the post-pandemic healthcare landscape. These technological innovations not only improve operational efficiency but also align with the broader trend of digital health transformation, making advanced VNA and PACS systems a strategic priority for healthcare providers.
Market Trends
Accelerated Shift Toward Cloud-Based Deployments
South Korea is witnessing a significant transition from traditional on-premises systems to cloud-based VNA and PACS solutions. This shift is driven by the need for scalable, cost-effective, and remotely accessible imaging platforms. Cloud deployments offer enhanced disaster recovery, seamless data sharing across facilities, and reduced capital expenditure on physical infrastructure. This trend aligns with the broader Asia-Pacific movement, where cloud-based models are experiencing rapid adoption due to their flexibility and efficiency.
Integration of Artificial Intelligence in Imaging Workflows
The incorporation of artificial intelligence (AI) into VNA and PACS systems is revolutionizing medical imaging in South Korea. AI enhances image analysis, automates workflow processes, and aids in anomaly detection, thereby improving diagnostic accuracy and reducing the workload on radiologists. For instance, a survey by the Korean Society of Radiology found that AI-based imaging tools are increasingly being integrated into clinical workflows to improve efficiency and diagnostic precision. The integration of AI facilitates predictive analytics and clinical decision support, contributing to more personalized and efficient patient care.
Emphasis on Interoperability and Standardization
There is a growing emphasis on interoperability and standardization within South Korea's healthcare IT landscape. Healthcare providers are increasingly adopting VNA solutions that support seamless integration across various imaging devices and hospital information systems. For instance, South Korea’s Health Data Standardization Taskforce has introduced national interoperability standards to improve healthcare data exchange. This focus on interoperability ensures that imaging data can be easily accessed and shared across different platforms, enhancing clinical collaboration and streamlining patient care.
Rising Demand for Enterprise Imaging Solutions
The demand for enterprise imaging solutions is on the rise in South Korea, driven by the need for centralized access to imaging data across multiple departments and facilities. Enterprise imaging platforms consolidate various imaging modalities into a single interface, facilitating comprehensive patient records and improving clinical decision-making. This trend is particularly evident in hospitals and large healthcare networks seeking to enhance operational efficiency and patient outcomes.
Market Challenges Analysis
High Implementation Costs and Integration Complexities
One of the foremost challenges in the South Korean VNA and PACS market is the high initial cost of implementation and the complexity of integrating new systems with existing healthcare infrastructure. Despite the long-term benefits of centralized and vendor-neutral image storage, the upfront investment in advanced PACS and VNA platforms including hardware upgrades, software licensing, and staff training can be substantial. For instance, South Korea’s regulatory framework requires extensive compliance measures for integrating new healthcare IT systems, adding to implementation complexity. Smaller hospitals and clinics, in particular, may face budgetary constraints that hinder adoption. Additionally, integrating these systems with legacy electronic medical records (EMRs), radiology information systems (RIS), and other hospital IT platforms often requires customization and technical expertise, which can prolong deployment timelines and increase total cost of ownership.
Data Security Concerns and Regulatory Hurdles
As healthcare data becomes increasingly digitized and cloud-based, concerns about data privacy and cybersecurity present a significant challenge for the VNA and PACS market in South Korea. Handling vast amounts of sensitive patient data requires compliance with stringent local and international data protection regulations, such as South Korea’s Personal Information Protection Act (PIPA). Ensuring end-to-end encryption, secure data transmission, and access control across integrated systems is complex and costly. Moreover, cloud-based deployments while beneficial for scalability and remote access raise additional concerns about data sovereignty and third-party risk management. Healthcare institutions must invest in robust security frameworks and stay updated with evolving regulatory standards, which can slow down adoption and create operational uncertainty.
Market Opportunities
The South Korea Vendor Neutral Archives (VNA) and Picture Archiving and Communication Systems (PACS) market presents substantial opportunities fueled by the country's rapidly evolving digital healthcare landscape. As South Korea continues to invest in smart hospital infrastructure and nationwide health information exchange systems, the demand for interoperable, scalable image management solutions is rising. This creates a strong growth avenue for VNA and PACS vendors that can offer flexible deployment models, including hybrid and cloud-based systems tailored to meet local compliance and data security requirements. Moreover, the government’s focus on strengthening healthcare IT through initiatives such as the “Digital New Deal” supports large-scale digitalization projects, which include expanding telemedicine and AI-driven diagnostics-both of which rely on robust medical image storage and retrieval platforms.
In addition to the growing public sector demand, private healthcare institutions are increasingly adopting advanced imaging solutions to improve efficiency, reduce operational costs, and enhance patient care. With South Korea being a leader in technology adoption, there is significant potential for AI-integrated PACS systems that offer advanced analytics, automated workflows, and enhanced diagnostic support. The expansion of specialized healthcare services, such as oncology, cardiology, and orthopedics, also opens niche markets for targeted imaging solutions. Furthermore, rising interest in cross-border medical tourism and remote consultations could encourage the development of unified imaging platforms that support multi-site access, second opinions, and seamless data exchange. These factors position South Korea as an attractive market for innovation-driven vendors seeking to offer next-generation VNA and PACS solutions.
Market Segmentation Analysis:
By Type:
The South Korea market for medical imaging IT is primarily segmented into Vendor Neutral Archive (VNA) and Picture Archiving and Communication System (PACS), each playing distinct yet complementary roles. PACS holds a larger market share owing to its long-standing presence in radiology departments and widespread adoption for image viewing and management. It serves as a critical component in streamlining diagnostic workflows and enabling timely access to patient imaging data. However, VNAs are rapidly gaining traction due to the increasing demand for data interoperability and system-wide integration across healthcare networks. Unlike traditional PACS, VNAs offer vendor-agnostic storage that allows healthcare providers to manage imaging data from multiple departments and modalities under a unified framework. This feature is particularly valuable in multi-site hospitals and facilities planning for long-term digital transformation. The rising need for centralized image repositories and the shift toward enterprise-wide imaging strategies continue to drive growth in both segments, with VNAs expected to see faster adoption in the coming years.
By Mode of Delivery:
In terms of delivery mode, the South Korea market is segmented into on-premise, cloud-based, and hybrid models, each offering distinct benefits based on facility size, IT capabilities, and strategic goals. On-premise solutions remain widely used, particularly in large hospitals and institutions with dedicated IT infrastructure, as they offer full control over data and systems. However, cloud-based solutions are gaining strong momentum due to their scalability, lower upfront costs, and enhanced data accessibility-benefits that align with South Korea’s growing interest in telemedicine and remote diagnostics. Cloud deployment also enables seamless collaboration and faster disaster recovery, which are critical for modern healthcare operations. The hybrid model, which combines the strengths of both on-premise and cloud systems, is emerging as a preferred approach for institutions transitioning from legacy systems while exploring cloud capabilities. This model offers flexibility and incremental modernization, making it particularly suitable for mid-sized providers seeking operational agility without overhauling their entire IT environment.
Segments:
Based on Type:
- Vendor Neutral Archive (VNA)
- Picture Archiving and Communication System (PACS)
Based on Mode of Delivery:
- On-Premise
- Cloud-Based
- Hybrid
Based on End- User:
- Hospitals
- Diagnostic Imaging Centers
- Ambulatory Surgical Centers
- Specialty Clinics
Based on Imaging Modality:
- X-ray
- Computed Tomography (CT)
- Magnetic Resonance Imaging (MRI)
- Ultrasound
- Others
Based on the Geography:
- Seoul Metropolitan Region
- Gyeonggi Province
- Busan and Ulsan Regions
- Daegu Region
Regional Analysis
Seoul Metropolitan Region
The Seoul Metropolitan Region commands the largest share of the South Korean VNA and PACS market, accounting for approximately 38% of the national market. As the capital and central hub for the country’s healthcare infrastructure, Seoul hosts a concentration of advanced tertiary hospitals, research institutions, and university-affiliated medical centers. These facilities drive high demand for cutting-edge imaging and data management technologies. Furthermore, strong government funding, skilled medical professionals, and well-established IT infrastructure support the adoption of enterprise imaging platforms, artificial intelligence integration, and vendor-neutral solutions. The region’s ongoing investments in digital transformation, smart hospital projects, and telehealth services further strengthen its dominance in the VNA and PACS space.
Gyeonggi Province
The Gyeonggi Province, which surrounds the Seoul metropolitan area, holds the second-largest market share at approximately 27%. This region has seen rapid urbanization and healthcare infrastructure development, with numerous general hospitals and specialized clinics serving both urban and suburban populations. The growing demand for imaging services, especially in rapidly developing cities like Suwon, Seongnam, and Goyang, fuels the expansion of PACS and VNA systems. Many healthcare institutions in Gyeonggi are actively upgrading their IT systems to enable interoperability and support remote diagnostics. Additionally, the province benefits from proximity to Seoul, facilitating collaborative medical services and shared data platforms among healthcare providers. This synergy positions Gyeonggi as a key growth area for imaging IT investment.
Busan and Ulsan Regions
The Busan and Ulsan Regions, located in the southeastern coastal area, collectively contribute approximately 18% of the South Korean VNA and PACS market. Busan, as the second-largest city, has a well-established healthcare sector, while Ulsan’s industrial base is increasingly complemented by investments in regional medical facilities. Hospitals in this area are focusing on modernizing their imaging infrastructure to support the growing patient base and complex diagnostic needs. Regional government initiatives aimed at promoting digital health transformation and increasing public-private partnerships have accelerated the adoption of cloud-based PACS and enterprise-level VNA solutions in these cities.
Daegu Region
The Daegu Region accounts for an estimated 10% of the national VNA and PACS market. While smaller in market share, Daegu is emerging as a significant player due to the presence of several regional medical centers and ongoing healthcare IT innovation efforts. The city’s strategic focus on medical technology and smart healthcare is encouraging hospitals to implement interoperable and AI-enhanced imaging solutions. Local government support and the presence of a robust academic-medical ecosystem are contributing to increased investments in PACS upgrades and vendor-neutral archiving platforms. As digital adoption accelerates in mid-tier cities, Daegu is expected to gain more prominence in South Korea’s imaging IT landscape.
Key Player Analysis
- Fujifilm Holdings Corporation
- INFINITT Healthcare
- Canon Medical Systems
- Konica Minolta Healthcare
- Shimadzu Corporation
- Hitachi Healthcare
- Hologic Asia-Pacific
- Carestream Health
- GE Healthcare
- Philips Healthcare
Competitive Analysis
The South Korea Vendor Neutral Archives (VNA) and Picture Archiving and Communication Systems (PACS) market is highly competitive, with key players offering innovative solutions to address the growing demand for digital healthcare transformation. Fujifilm Holdings Corporation, Canon Medical Systems, GE Healthcare, INFINITT Healthcare, Konica Minolta Healthcare, Shimadzu Corporation, Hitachi Healthcare, Hologic Asia-Pacific, Carestream Health, and Philips Healthcare are the leading players in this space. Companies are competing by offering integrated imaging solutions with AI capabilities, interoperability, and enhanced data security. The emphasis is on providing systems that streamline clinical workflows, improve diagnostic accuracy, and enable seamless data sharing across multiple healthcare facilities. Key competitive strategies include continuous innovation, such as AI-based analytics for image recognition and predictive diagnostics, and cloud-based deployments that offer scalability, cost-efficiency, and remote access. Companies are also focusing on developing flexible and customizable solutions to cater to a wide range of healthcare providers, from small clinics to large hospital networks. Additionally, competitive players are enhancing their customer support services, offering training, and ensuring smooth system integration with existing healthcare IT infrastructures. With the market's rapid growth, organizations are increasingly entering partnerships and collaborations with healthcare institutions to establish a foothold and expand their market share in the evolving digital health landscape.
Recent Developments
- In March 2024, at the European Congress of Radiology in Vienna, Philips unveiled new hardware innovations, focusing on integrating artificial intelligence into their imaging solutions to enhance diagnostic accuracy and workflow efficiency.
- In February 2024, FUJIFILM Healthcare Americas Corporation announced that it’s Synapse VNA and Synapse Radiology PACS solutions (in Asia/Oceania) were ranked #1 in the 2024 Best in KLAS Awards: Software and Services. The recognition, based on insights from KLAS Research, highlights companies excelling in improving patient care through their software and services.
- In January 2024, RamSoft (Canada) launched imaging EMR solution, named OmegaAI. The solution is a cloud-native, serverless imaging EMR software platform that consolidates VNA, Enterprise Imaging, PACS, RIS, simplified image exchange/sharing, routing & storage, a zero-footprint (ZFP) viewer, unified worklist, radiology reporting, document management, peer, patient portal, and a real-time business intelligence and analytics solution.
- In November 2023, InsiteOne (US) announced to acquire BRIT Systems cloud native RIS/PACS/VNA solution to advance imaging workflows. This acquisition will continue to focus on developing cost-effective solutions that improve operational productivity while enhancing patient care.
- In July 2023, Fujifilm Sonosite joined the newly formed Medical Imaging Division under the Advanced Medical Technology Association (AdvaMed), collaborating with industry leaders to advance medical imaging technologies.
Market Concentration & Characteristics
The South Korea Vendor Neutral Archives (VNA) and Picture Archiving and Communication Systems (PACS) market is moderately concentrated, with a few dominant players leading the industry, while also witnessing the entry of regional and niche vendors offering specialized solutions. The market characteristics include a strong focus on technological innovation, particularly in cloud-based and AI-powered imaging solutions. These advancements aim to enhance interoperability, streamline workflows, and improve diagnostic accuracy. The competitive landscape is driven by the demand for scalable, flexible, and cost-effective systems that can integrate seamlessly with existing healthcare infrastructures. Additionally, healthcare providers are increasingly seeking solutions that offer secure data storage, real-time access, and collaboration across multiple departments and locations. As the market matures, strategic partnerships, acquisitions, and collaborations are common, enabling companies to expand their offerings and cater to the growing need for comprehensive and integrated medical imaging solutions across South Korea's healthcare facilities.
Report Coverage
The research report offers an in-depth analysis based on Type, Mode of Delivery, End-User, Imaging Modality and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The demand for cloud-based PACS and VNA solutions will continue to rise due to their scalability, cost-efficiency, and remote accessibility.
- AI integration in imaging systems will drive improvements in diagnostic accuracy, workflow automation, and predictive analytics.
- Increased focus on interoperability and seamless data exchange between different healthcare facilities will fuel the adoption of vendor-neutral solutions.
- Healthcare institutions will prioritize cybersecurity features to ensure the protection of sensitive patient data amidst growing data privacy concerns.
- The shift toward enterprise imaging solutions will accelerate, as hospitals seek centralized access to imaging data across multiple departments.
- Smaller hospitals and clinics will increasingly adopt cloud-based PACS to lower initial capital expenditures and reduce IT management complexities.
- The aging population in South Korea will drive greater demand for diagnostic imaging, expanding the need for efficient image storage and retrieval systems.
- Government initiatives and policies supporting digital health transformation will create more opportunities for VNA and PACS providers.
- Partnerships and collaborations between healthcare institutions and technology companies will foster innovation and the development of next-generation imaging solutions.
- The market will see growth in AI-powered diagnostic tools, enabling healthcare providers to offer faster, more accurate results and improve patient care.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Expansion of Digital Healthcare Infrastructure
South Korea's government-backed healthcare digitization programs and advanced IT ecosystem are accelerating the adoption of VNA and PACS solutions, enabling seamless data sharing and operational efficiency across hospitals and diagnostic centers.
Rising Imaging Volumes from Aging Population
The rapidly aging population in South Korea is increasing the prevalence of chronic diseases, driving up demand for diagnostic imaging and necessitating scalable, efficient image storage and retrieval systems.
Shift Toward Interoperability and Vendor Neutrality
Healthcare providers are prioritizing vendor-neutral solutions to ensure seamless integration across diverse imaging devices and hospital information systems, supporting future-proof investments and reducing long-term costs.
Technological Advancements and AI Integration
The integration of artificial intelligence, cloud computing, and advanced analytics into PACS and VNA platforms is enhancing diagnostic accuracy, automating workflows, and enabling remote access, making these technologies essential for modern healthcare delivery.
Government Initiatives and Regulatory Support
Policies such as the National Healthcare Information Infrastructure (NHII) and the Digital New Deal are fostering large-scale digital transformation in healthcare, creating a favorable environment for the adoption of advanced imaging IT solutions.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the South Korea Vendor Neutral Archives (VNA) and Picture Archiving and Communication Systems (PACS)?
What factors are driving the growth of the South Korea Vendor Neutral Archives (VNA) and Picture Archiving and Communication Systems (PACS)?
What are some challenges faced by the South Korea Vendor Neutral Archives (VNA) and Picture Archiving and Communication Systems (PACS)?
Who are the major players in the South Korea Vendor Neutral Archives (VNA) and Picture Archiving and Communication Systems (PACS)?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Type
- 1.2.1 Vendor Neutral Archive (VNA)
- 1.2.2 Picture Archiving and Communication System (PACS)
- 1.3 By End-User
- 1.3.1 Hospitals
- 1.3.2 Diagnostic Imaging Centers
- 1.3.3 Ambulatory Surgical Centers
- 1.3.4 Specialty Clinics
- 1.4 By Imaging Modality
- 1.4.1 X-ray
- 1.4.2 Computed Tomography (CT)
- 1.4.3 Magnetic Resonance Imaging (MRI)
- 1.4.4 Ultrasound
- 1.4.5 Others
- 1.5 By Mode of Delivery
- 1.5.1 On-Premise
- 1.5.2 Cloud-Based
- 1.5.3 Hybrid
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 187.86 million → 2032: USD 357.56 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 South Korea Vendor Neutral Archives (VNA) and PACS Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 South Korea Vendor Neutral Archives (VNA) and PACS Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 South Korea Vendor Neutral Archives (VNA) and PACS Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 South Korea Vendor Neutral Archives (VNA) and PACS Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 South Korea Vendor Neutral Archives (VNA) and PACS Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 South Korea Vendor Neutral Archives (VNA) and PACS Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Data Protection, AI and Cybersecurity Compliance
- 9.8 Upcoming Policy Changes and Market Implications
Chapter 10 South Korea Vendor Neutral Archives (VNA) and PACS Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 South Korea Vendor Neutral Archives (VNA) and PACS Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 187.86 million → 2032: USD 357.56 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 South Korea Vendor Neutral Archives (VNA) and PACS Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Type - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Vendor Neutral Archive (VNA)
- 12.3.7.2 Picture Archiving and Communication System (PACS)
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By End-User - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Hospitals
- 12.4.7.2 Diagnostic Imaging Centers
- 12.4.7.3 Ambulatory Surgical Centers
- 12.4.7.4 Specialty Clinics
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Imaging Modality - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 X-ray
- 12.5.7.2 Computed Tomography (CT)
- 12.5.7.3 Magnetic Resonance Imaging (MRI)
- 12.5.7.4 Ultrasound
- 12.5.7.5 Others
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 By Mode of Delivery - Market Size and Forecast, 2024-2032
- 12.6.1 Segment Definition and Scope
- 12.6.2 Historical Market Size
- 12.6.3 Revenue Forecast, 2024-2032
- 12.6.4 Volume Forecast, 2024-2032
- 12.6.5 Base-Year Market Share, 2024
- 12.6.6 Segment CAGR and Growth Drivers
- 12.6.7 Subsegment Market Size and Forecast
- 12.6.7.1 On-Premise
- 12.6.7.2 Cloud-Based
- 12.6.7.3 Hybrid
- 12.6.8 Subsegment Pricing and Adoption Trends
- 12.6.9 Leading Suppliers and Competition
- 12.6.10 Regional Demand and Opportunities
- 12.7 Segment Growth Comparison
- 12.8 Segment Attractiveness and Priority Matrix
Chapter 13 South Korea Vendor Neutral Archives (VNA) and PACS End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 South Korea Vendor Neutral Archives (VNA) and PACS Geographic Market Outlook, 2024-2032
- 14.1 Domestic Market Distribution and Demand Clusters
- 14.2 State- or Province-Wise Market Size and Forecast, 2024-2032
- 14.3 City and Metropolitan Market Outlook
- 14.4 Industrial, Manufacturing and Commercial Clusters
- 14.5 Geographic Concentration of Key End Users
- 14.6 Local Pricing and Purchasing Differences
- 14.7 Domestic Production Facilities and Capacity Map
- 14.8 Local Infrastructure and Project Pipeline
- 14.9 State-Level Policy and Incentive Differences
- 14.10 Subnational Investment Hotspots and Opportunities
- 14.11 Distribution and Logistics Networks
- 14.12 Domestic Competitive Footprint
Chapter 15 South Korea Vendor Neutral Archives (VNA) and PACS Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 South Korea Vendor Neutral Archives (VNA) and PACS Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Fujifilm Holdings Corporation
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 INFINITT Healthcare
- 18.4 Canon Medical Systems
- 18.5 Konica Minolta Healthcare
- 18.6 Shimadzu Corporation
- 18.7 Hitachi Healthcare
- 18.8 Hologic Asia-Pacific
- 18.9 Carestream Health
- 18.10 GE Healthcare
- 18.11 Philips Healthcare
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

