
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Spain Cheese Market Size 2024 | USD 1,952.36 million |
| Spain Cheese Market,CAGR | 3.34% |
| Spain Cheese Market Size 2032 | USD 2,538.51 million |
Market Overview
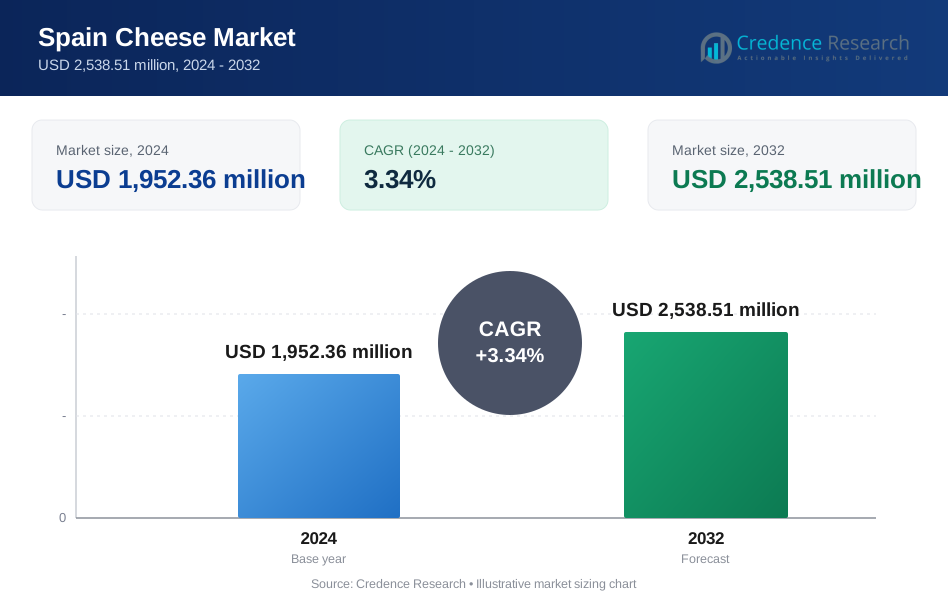
Spain Cheese market size was valued at USD 1,952.36 million in 2024 and is anticipated to reach USD 2,538.51 million by 2032, at a CAGR of 3.34% during the forecast period (2024-2032).
The Spain cheese market is driven by increasing consumer preference for natural and high-protein dairy products, alongside a growing inclination towards traditional Spanish cheese varieties such as Manchego and Idiazabal. Rising health awareness has encouraged demand for organic and low-fat cheese options, further supporting market expansion. Additionally, the integration of cheese in convenience foods and gourmet cuisine has amplified its appeal across urban households and the foodservice sector. The surge in tourism and hospitality industries continues to boost local cheese consumption, particularly in hotels and restaurants. Market players are also innovating with new flavors, textures, and packaging solutions to cater to evolving consumer tastes. Furthermore, the growing influence of e-commerce and digital grocery platforms has made premium and regional cheese varieties more accessible, enhancing market penetration. These factors, combined with government support for dairy farming and artisanal cheese production, are collectively shaping the positive outlook of Spain’s cheese market.
The geographical landscape of the Spain cheese market reveals diverse consumption patterns influenced by regional culinary traditions and economic activity. Urban centers like Madrid and Barcelona lead in innovation and demand for premium, gourmet, and international cheese varieties due to higher consumer purchasing power and modern retail infrastructure. In contrast, rural and inland regions exhibit a strong preference for traditional, locally produced cheeses made from goat and sheep milk, reflecting cultural heritage and artisanal practices. Coastal regions benefit from robust tourism and hospitality sectors, driving demand for versatile cheese products in foodservice applications. Key players operating in the Spain cheese market include Arla Foods, FrieslandCampina, Groupe Bel, Fonterra Co-operative Group, Glanbia plc, Hochland SE, Parmalat S.p.A., Emmi AG, and Valio Ltd. These companies are actively expanding their product portfolios, adopting sustainable practices, and leveraging distribution networks to cater to the dynamic tastes of Spanish consumers across various regions.
Market Insights
- The Spain cheese market was valued at USD 1,952.36 million in 2024 and is projected to reach USD 2,538.51 million by 2032, growing at a CAGR of 3.34% during the forecast period.
- The global cheese market was valued at USD 97,440.00 million in 2024 and is projected to reach USD 1,46,171.12 million by 2032, growing at a CAGR of 5.20% during the forecast period.
- Increasing consumer preference for premium and artisanal cheeses is driving market growth, particularly in urban centers.
- Rising demand for flavored, organic, and clean-label cheeses aligns with evolving dietary trends and health-conscious consumption.
- The market is competitive, with key players like Arla Foods, FrieslandCampina, and Groupe Bel focusing on product innovation and expansion strategies.
- High production costs, raw material price fluctuations, and strict EU regulations pose challenges to manufacturers.
- Urban centers such as Madrid and Barcelona dominate consumption, while rural and coastal regions support traditional and tourism-driven demand.
- Expansion of e-commerce and online grocery platforms is opening new opportunities for cheese distribution and direct-to-consumer sales.
Report scope
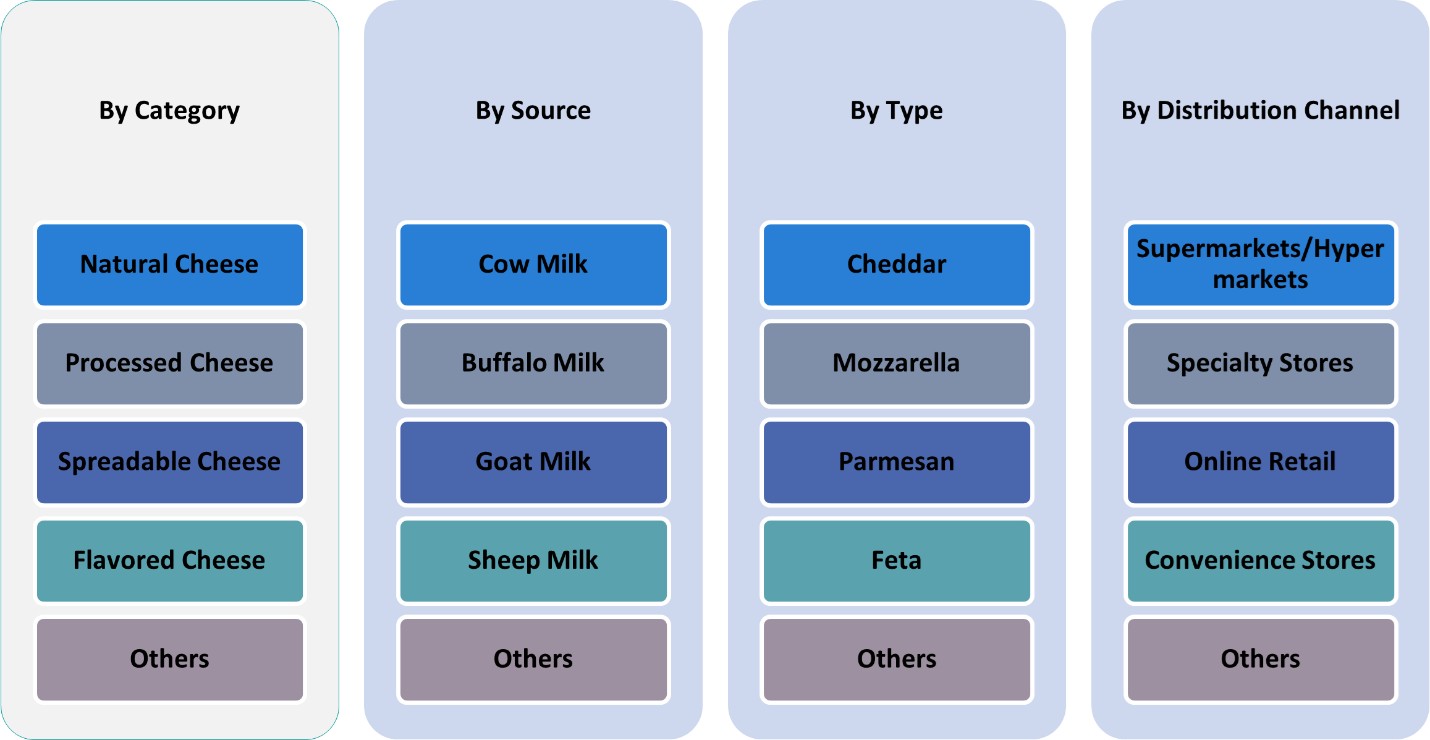
This report segments the Spain Cheese Market as follows:
Market Drivers
Rising Consumer Demand for Artisanal and Traditional Cheese
One of the primary drivers of the Spain cheese market is the increasing consumer inclination toward artisanal and traditional cheese varieties. For instance, the Spanish Ministry of Agriculture highlights the growing popularity of region-specific cheeses like Manchego and Mahón, which are protected under the EU's Protected Designation of Origin (PDO) scheme. The demand for high-quality, handcrafted cheeses has gained momentum among both domestic buyers and international tourists seeking authentic culinary experiences. This shift reflects a broader trend of valuing artisanal craftsmanship over mass-produced alternatives. In response, local producers are expanding their product portfolios and improving distribution channels to capitalize on this growing preference.
Health Consciousness Fueling Organic and Functional Cheese Choices
The growing health awareness among consumers in Spain has significantly contributed to the demand for organic, low-fat, and functional cheese products. Cheese enriched with probiotics, fortified with calcium, or labeled as organic is becoming increasingly popular, especially among health-conscious and lactose-sensitive individuals. Consumers are also opting for cheese with reduced sodium and fat content, aligning with modern dietary preferences. This trend is encouraging producers to innovate by offering nutritionally enhanced options without compromising on taste. Government initiatives and EU regulations supporting organic dairy farming have further fueled this segment, enabling manufacturers to adopt cleaner labeling and sustainable production methods.
Expansion of Foodservice and Hospitality Industry
Spain's robust tourism sector and the expansion of the foodservice industry have played a crucial role in driving cheese consumption. For instance, the Spanish Hospitality Association reports that cheese-based dishes like tapas and gourmet platters are staples in restaurants and cafés catering to millions of tourists annually. Spanish cheeses are commonly featured in tapas, salads, and gourmet platters, reflecting their integration into both traditional and contemporary cuisines. Moreover, the growing popularity of international cuisines has led to increased usage of various cheese types in pizzas, pastas, and sandwiches, thereby broadening the market scope. Foodservice providers are partnering with local dairy producers to offer fresh, high-quality cheese products that enhance customer experience and boost repeat business.
Innovation in Packaging and Retail Distribution Channels
Innovative packaging and the rise of modern retail formats have further accelerated the growth of the Spain cheese market. Vacuum-sealed packaging, resealable packs, and portion-controlled units are enhancing product shelf life and convenience, attracting busy urban consumers. Simultaneously, the expansion of supermarket chains, gourmet food stores, and online grocery platforms has improved accessibility to diverse cheese options across regions. E-commerce, in particular, has become a vital sales channel, offering customers access to premium and imported cheese varieties at competitive prices. These advancements in packaging and distribution have allowed cheese manufacturers to extend their market reach, reduce wastage, and strengthen brand visibility in an increasingly competitive landscape.
Market Trends
Surge in Premium and Gourmet Cheese Consumption
The Spain cheese market is witnessing a noticeable shift toward premium and gourmet cheese varieties, driven by evolving consumer preferences and higher disposable incomes. For instance, the Spanish Ministry of Agriculture has highlighted the growing demand for artisanal cheeses like Manchego and Cabrales, which are protected under the EU's Protected Designation of Origin (PDO) scheme. Gourmet cheeses, including those infused with herbs, truffles, or regional spices, are gaining popularity not only among food enthusiasts but also within high-end hospitality and catering sectors. This trend reflects a broader desire for experiential eating, where taste, origin, and artisanal appeal hold significant value. As a result, manufacturers and specialty stores are investing in exclusive cheese lines and curated assortments to meet the growing appetite for premium offerings.
Growth of Plant-Based and Lactose-Free Cheese Alternatives
The rising demand for plant-based and lactose-free cheese alternatives marks a significant trend in the Spain cheese market. For instance, the Spanish Consumer Agency has reported an increase in the availability of plant-based cheeses made from almond and soy milk, catering to vegan and lactose-intolerant consumers. These alternatives are formulated to mimic the taste and texture of traditional dairy cheese while catering to health-conscious and environmentally aware consumers. This trend is further supported by advancements in food technology that have improved the quality and shelf stability of plant-based cheeses. As consumer awareness of animal welfare and sustainability grows, plant-based options are gaining shelf space in both supermarkets and specialty food outlets.
Rising Popularity of Convenient and Ready-to-Eat Formats
Busy lifestyles and a growing preference for convenient food solutions have accelerated the demand for ready-to-eat and easy-to-serve cheese formats in Spain. Single-serve packs, sliced and shredded cheese, and snackable cheese portions are becoming increasingly common in retail channels. These formats are particularly appealing to working professionals, students, and parents seeking nutritious yet convenient food options. In addition, the inclusion of cheese in ready-made meals, salads, and on-the-go snack kits has further fueled this trend. Manufacturers are responding by investing in advanced packaging technologies that extend shelf life while maintaining freshness and taste, thereby boosting product appeal and consumption frequency.
Emphasis on Sustainability and Eco-Friendly Production
Sustainability has become a central theme across Spain’s dairy sector, with cheese producers adopting environmentally responsible practices. Consumers are showing a growing preference for products from brands that prioritize animal welfare, use eco-friendly packaging, and adopt sustainable farming techniques. Organic cheese production, waste reduction initiatives, and local sourcing of ingredients are increasingly influencing purchasing decisions. This trend is pushing manufacturers to obtain certifications and adopt transparent labeling that highlights sustainability credentials. As environmental awareness continues to rise, sustainability is expected to remain a key differentiator and competitive advantage in the evolving Spain cheese market.
Market Challenges Analysis
Price Volatility in Raw Materials and Production Costs
One of the significant challenges facing the Spain cheese market is the volatility in raw material prices, particularly milk, which serves as the primary input in cheese production. Fluctuations in feed costs, climate-related disruptions affecting dairy farming, and supply chain inefficiencies have contributed to inconsistent milk supply and pricing. These dynamics directly impact cheese production costs, making it difficult for manufacturers to maintain stable pricing and profit margins. Additionally, the increasing energy costs associated with refrigeration, transportation, and storage add financial pressure on producers, especially small and mid-sized enterprises. As a result, some local producers struggle to compete with imported cheese products, which may be priced more competitively due to economies of scale or government subsidies in exporting countries. This cost sensitivity often translates to pricing pressure across the value chain, potentially affecting product quality and consumer affordability.
Regulatory Hurdles and Market Fragmentation
The Spain cheese market also contends with regulatory challenges and industry fragmentation, which can hinder smooth market operations and scalability. For instance, the Spanish Food Safety Agency enforces strict compliance protocols for labeling and food safety, requiring significant administrative investments from producers. For small-scale dairies, meeting these regulatory requirements can be resource-intensive, reducing their agility and delaying market entry for new products. Furthermore, the market remains highly fragmented, with a mix of multinational corporations, regional brands, and local artisans competing for market share. This fragmentation often leads to inconsistent quality standards, limited brand recognition, and fierce competition in pricing. It also creates barriers to large-scale distribution, making it harder for traditional producers to expand beyond regional markets. Addressing these challenges requires stronger collaboration between regulatory bodies and industry stakeholders to simplify compliance processes and promote a more cohesive and competitive market environment.
Market Opportunities
The Spain cheese market presents strong growth opportunities fueled by increasing international demand for Spanish cheese varieties. As global interest in Mediterranean cuisine rises, traditional cheeses such as Manchego, Idiazabal, and Cabrales are gaining prominence in export markets. Spanish cheese producers have the potential to expand their global footprint by leveraging the unique qualities and geographical indications of their offerings. Participation in international food exhibitions, strategic export partnerships, and targeted marketing campaigns can help position Spanish cheeses as premium products in North America, Asia, and other parts of Europe. In addition, the growing demand for organic and clean-label food products globally aligns well with Spain's rich tradition of natural, minimally processed cheese production, enabling producers to cater to health-conscious consumers in both domestic and international markets.
Domestically, the rise of e-commerce and digital retail platforms opens new avenues for cheese producers to reach a broader customer base. Online grocery shopping continues to gain traction in Spain, offering opportunities for niche and artisanal cheese brands to showcase their products beyond traditional retail shelves. Collaborations with food delivery services, gourmet subscription boxes, and digital influencers can further enhance brand visibility and consumer engagement. Moreover, the increasing trend of experiential dining and culinary tourism presents opportunities to integrate cheese into gastronomic tours, tastings, and local food festivals, adding cultural value and stimulating demand. Innovation in product offerings—such as cheese-based snacks, functional cheese with added nutrients, or convenient packaging formats—can also help brands tap into younger demographics and modern lifestyles. Together, these factors create a favorable environment for sustained growth and diversification within the Spain cheese market.
Market Segmentation Analysis:
By Category:
The Spain cheese market is segmented into Cheddar, Processed Cheese, Spreadable Cheese, Flavored Cheese, and Others. Among these, Cheddar holds a prominent share due to its widespread usage in both household and foodservice applications. Its versatility in cooking, snacking, and sandwich preparation makes it a staple in many Spanish homes. Processed cheese also commands significant market presence, especially within the ready-to-eat and convenience food segments, appealing to consumers seeking affordable and long-lasting options. Spreadable cheese, often consumed with bread and crackers, is increasingly popular among younger consumers and urban households. Meanwhile, flavored cheese—infused with herbs, spices, or wine—has gained traction in recent years as part of the premium and gourmet product trend. This category is particularly favored in high-end dining and specialty retail outlets. The “Others” segment includes niche offerings such as blue cheese and smoked varieties, which cater to regional and traditional tastes. Together, these categories reflect the diversity in consumer preferences and evolving culinary applications in Spain’s dynamic cheese market.
By Source:
Based on source, the market is segmented into Cow Milk, Buffalo Milk, Goat Milk, Sheep Milk, and Others. Cow milk dominates the segment, attributed to its high availability and widespread consumer acceptance. It is the primary source for producing mainstream cheese varieties such as Cheddar and processed cheese, widely consumed across all regions. Sheep milk follows as a key contributor, especially due to its use in producing iconic Spanish cheeses like Manchego, which is both domestically popular and a strong export product. Goat milk-based cheese is also gaining popularity, particularly among health-conscious consumers and those seeking lactose-light or distinctive flavor profiles. Buffalo milk, while less common in Spain, is gradually finding niche acceptance, particularly in gourmet products like mozzarella. The “Others” category may include plant-based milk alternatives, which are emerging in response to rising demand for vegan and lactose-free cheeses. This segmentation highlights the growing importance of source-specific branding and dietary preferences in shaping consumer choice and product innovation.
Segments:
Based on Category:
- Cheddar
- Processed Cheese
- Spreadable Cheese
- Flavored Cheese
- Others
Based on Source:
- Cow Milk
- Buffalo Milk
- Goat Milk
- Sheep Milk
- Others
Based on Type:
- Cheddar
- Mozzarella
- Parmesan
- Feta
- Others
Based on Distribution Channel:
- Supermarkets/Hypermarkets
- Specialty Stores
- Online Retail
- Convenience Stores
- Others
Based on the Geography:
- Urban Centers (Madrid, Barcelona)
- Rural Areas
- Coastal regions
Regional Analysis
Urban centers
Urban centers, particularly Madrid and Barcelona, account for the largest share of the Spain cheese market, contributing approximately 38% of the total market revenue. These metropolitan areas are marked by high population density, greater disposable incomes, and exposure to diverse culinary trends, all of which support robust cheese consumption. Supermarkets, gourmet stores, and specialty cheese outlets are well-established in these cities, offering a wide range of local and imported cheese products. Additionally, the strong presence of the foodservice and hospitality sectors in urban centers fuels consistent demand for cheese in restaurants, hotels, and cafes. Consumer preferences in these regions are also shifting toward premium, organic, and artisanal cheeses, prompting manufacturers to innovate and cater to evolving tastes.
Rural areas
Rural areas contribute about 22% to the overall cheese market in Spain, driven primarily by traditional consumption habits and local production. Rural consumers typically favor regional cheese varieties, such as goat and sheep milk cheeses, which are often produced and consumed within local communities. While the purchasing power may be lower in these areas compared to urban centers, the deep-rooted culture of dairy farming and artisanal cheese-making sustains steady demand. Local cooperatives and family-owned dairies play a significant role in distributing fresh and traditional cheeses to local markets. However, rural regions face challenges related to limited access to premium or innovative cheese formats due to lower retail penetration and reduced exposure to modern distribution channels.
Coastal regions
Coastal regions, including Valencia, Andalusia, and Catalonia’s coastal zones, represent around 20% of the cheese market share. These areas benefit from a vibrant tourism industry, which significantly boosts cheese consumption through restaurants, hotels, and resort-based dining. Cheese is a staple in Mediterranean coastal cuisine, often featured in tapas, seafood pairings, and salads. Seasonal spikes in tourist activity also result in higher sales volumes during peak months. Additionally, coastal consumers tend to experiment with flavored and exotic cheeses, contributing to increased diversity in product offerings. The demand in these regions is supported by both local populations and an international consumer base, making them attractive for brand expansion.
Key Player Analysis
- Arla Foods
- FrieslandCampina
- Groupe Bel
- Fonterra Co-operative Group (Spain Operations)
- Glanbia plc
- Hochland SE
- Parmalat S.p.A.
- Emmi AG
- Valio Ltd.
Competitive Analysis
The Spain cheese market is highly competitive, with key players such as Arla Foods, FrieslandCampina, Groupe Bel, Fonterra Co-operative Group, Glanbia plc, Hochland SE, Parmalat S.p.A., Emmi AG, and Valio Ltd. actively shaping industry dynamics. These companies focus on expanding their product portfolios, leveraging advanced processing technologies, and enhancing distribution networks to strengthen their market presence. Leading players are investing in product innovation, introducing organic, lactose-free, and flavored cheese variants to cater to evolving consumer preferences. Sustainability is also a key strategic focus, with manufacturers adopting eco-friendly packaging and sustainable sourcing practices to align with regulatory and consumer expectations. Additionally, mergers, acquisitions, and strategic partnerships are common as companies seek to expand their reach and enhance operational efficiency. The competitive landscape is further intensified by strong local and artisanal cheese producers who maintain regional dominance through traditional cheese varieties, creating a diverse and fragmented market environment.
Recent Developments
- In March 2025, Arla Foods Ingredients partnered with Valley Queen in South Dakota to increase production of Nutrilac® ProteinBoost, a high-protein whey concentrate, to meet growing demand in North America.
- In March 2025, Sargento introduced three innovations—Natural American Cheese, Seasoned Shredded Cheese in collaboration with McCormick, and Shareables snack trays in partnership with Mondelez International.
- In March 2025, Saputo USA debuted its spicy mozzarella cheese at the International Pizza Expo, combining traditional mozzarella with habanero jack for a zesty twist.
- In February 2025, Kraft Heinz emphasized innovation across three platforms—taste elevation, easy-ready meals, and snacking. This includes new product launches like Lunchables Spicy Nachos and value-sized Kraft Mac & Cheese to cater to shifting consumer preferences.
- In November 2024, Lactalis highlighted emerging trends such as premiumization, hot eating cheeses like Président Extra Creamy Brie, and sustainability-focused products like Seriously Spreadable Black Pepper cheese.
Market Concentration & Characteristics
The Spain cheese market exhibits a moderate to high level of market concentration, with a mix of multinational corporations and regional artisanal producers competing for market share. Leading companies such as Arla Foods, FrieslandCampina, and Groupe Bel dominate the industry through extensive distribution networks, strong brand recognition, and continuous product innovation. These players leverage economies of scale to maintain competitive pricing and expand their presence across both retail and foodservice channels. However, the market also retains a strong presence of small-scale, local cheesemakers, particularly in rural and inland regions, where traditional cheese varieties hold cultural significance. The market is characterized by diverse consumer preferences, ranging from mass-produced processed cheese to premium, aged, and flavored artisanal varieties. Additionally, the increasing demand for organic, lactose-free, and sustainable cheese options is shaping new market trends. This combination of global dominance and regional specialization creates a dynamic competitive environment with opportunities for both large and niche players.
Report Coverage
The research report offers an in-depth analysis based on Category, Source, Type, Distribution Channel and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The Spain cheese market will continue to grow steadily, driven by increasing consumer demand for premium and artisanal cheeses.
- Health-conscious consumers will drive the demand for organic, lactose-free, and clean-label cheese products.
- E-commerce and online grocery platforms will play a significant role in expanding market reach and direct-to-consumer sales.
- Sustainability initiatives, including eco-friendly packaging and ethical sourcing, will become essential for brand differentiation.
- The foodservice industry will remain a key growth driver, with restaurants and cafes incorporating diverse cheese varieties into their menus.
- Innovations in cheese flavors, textures, and functional ingredients will cater to evolving consumer preferences.
- Rising tourism will boost cheese sales in coastal and high-footfall urban areas through hospitality and retail sectors.
- Strategic mergers, acquisitions, and partnerships will strengthen market positioning and global expansion efforts.
- Government regulations and quality standards will continue to shape product development and manufacturing practices.
- Local artisanal cheesemakers will maintain a strong presence, preserving Spain’s rich cheese-making heritage alongside industrial production.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Spain Cheese market?
What factors are driving the growth of the Spain Cheese market?
What are some challenges faced by the Spain Cheese market?
Who are the major players in the Spain Cheese market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Spain Cheese Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Spain Cheese Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 1,952.36 million → 2032: USD 2,538.51 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Spain Cheese Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Spain Cheese Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Spain Cheese Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Spain Cheese Market Drivers
- 3.3 Spain Cheese Market Restraints & Challenges
- 3.4 Spain Cheese Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Spain Cheese Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Spain Cheese Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Spain Cheese category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Spain Cheese Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Spain Cheese Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Spain Cheese market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Spain Cheese Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Spain Cheese Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Spain Cheese Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Spain Cheese (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Spain Cheese Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Spain Cheese Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Spain Cheese Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Spain Cheese Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Spain Cheese Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Spain Cheese Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Spain Cheese Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Spain Cheese Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Spain Cheese Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
