
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Spain Industrial Solvents Market Size 2024 | USD 694.47 million |
| Spain Industrial Solvents Market, CAGR | 5.34% |
| Spain Industrial Solvents Market Size 2032 | USD 1,053.25 million |
Market Overview
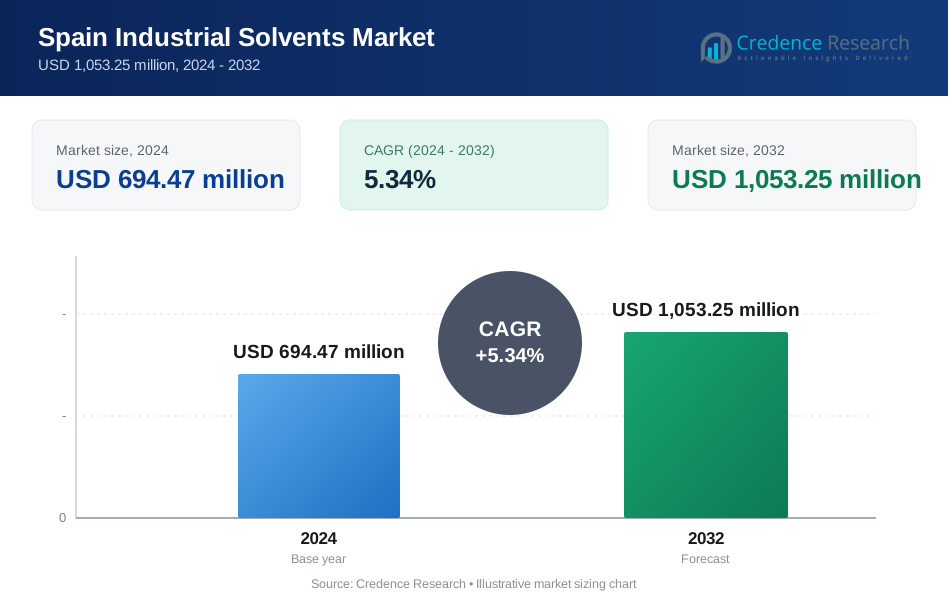
Spain Industrial Solvents market size was valued at USD 694.47 million in 2024 and is anticipated to reach USD 1,053.25 million by 2032, at a CAGR of 5.34% during the forecast period (2024-2032).
The Spain industrial solvents market is experiencing steady growth, driven by rising demand across key end-use industries such as paints and coatings, adhesives, pharmaceuticals, and chemicals. The country's expanding construction and automotive sectors continue to support solvent consumption, particularly for surface coatings and cleaning applications. Increasing focus on sustainability and regulatory compliance is also encouraging the adoption of eco-friendly, bio-based solvents with low VOC emissions. Technological advancements in solvent formulation and recovery systems are enhancing efficiency and environmental safety, further supporting market expansion. Additionally, growing investments in manufacturing and infrastructure projects across Spain are contributing to the rising need for high-performance solvents. Market players are increasingly focused on research and development to introduce innovative and compliant products that meet the evolving needs of both industrial users and regulatory bodies. These trends, combined with consistent economic recovery and industrial output, are expected to propel the industrial solvents market in Spain over the forecast period.
Geographically, Spain's industrial solvents market is concentrated in major urban centers such as Madrid and Barcelona, where a large portion of the demand comes from diverse industries, including automotive, pharmaceuticals, and chemicals. Coastal regions also play a crucial role, particularly in sectors like marine coatings and food processing. Rural areas, although contributing to the market, have a smaller share due to limited industrial activity. Key players in Spain’s industrial solvents market include global and regional leaders such as BASF SE, Shell Chemicals, Solvay S.A., Arkema S.A., and INEOS Group. These companies dominate the market with a wide range of solvent products used across various applications, including paints & coatings, adhesives, pharmaceuticals, and chemical processing. Their continuous innovation in sustainable solutions, coupled with their vast distribution networks, helps them maintain a strong foothold in the competitive Spanish market.
Market Insights
- The Spain industrial solvents market was valued at USD 694.47 million in 2024 and is expected to reach USD 1,053.25 million by 2032, growing at a CAGR of 5.34% during the forecast period (2024-2032).
- The global industrial solvents market was valued at USD 34,660.50 million in 2024 and is expected to reach USD 60,647.79 million by 2032, growing at a CAGR of 7.24% during the forecast period (2024-2032).
- Increasing demand from end-use industries like paints, coatings, pharmaceuticals, and automotive is driving market growth.
- Eco-friendly and bio-based solvents are gaining popularity due to stringent environmental regulations and sustainability trends.
- Technological advancements in solvent recovery and production are boosting market efficiency and innovation.
- The market faces challenges from regulatory pressures, including VOC emission limits and hazardous chemical usage.
- Urban centers like Madrid and Barcelona dominate the market, with strong industrial activity supporting solvent demand.
- Key players include BASF SE, Shell Chemicals, Solvay S.A., Arkema S.A., and INEOS Group, who lead in product innovation and market share.
Report Scope
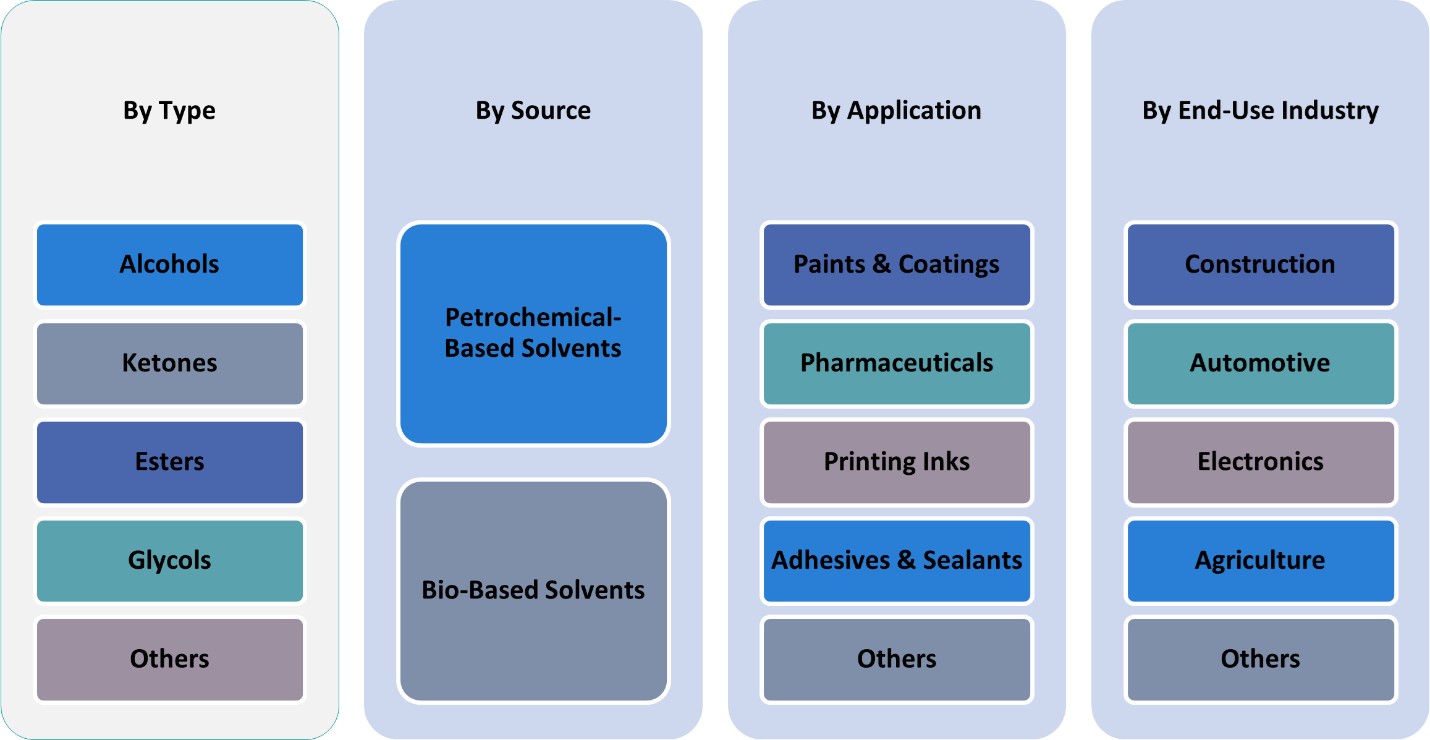
This report segments the Spain Industrial Solvents market as follows:
Market Drivers
Rising Demand from End-Use Industries
One of the primary drivers of the Spain industrial solvents market is the increasing demand from key end-use industries such as paints and coatings, adhesives, pharmaceuticals, and chemicals. The construction and automotive sectors, in particular, are witnessing consistent growth, which boosts the consumption of solvents for applications like degreasing, cleaning, and surface treatment. The paints and coatings industry relies heavily on solvents for formulation and application, especially in residential, commercial, and infrastructure development projects. For instance, Spain’s chemical industry plays a crucial role in supplying raw materials for these sectors, with strong government backing for industrial expansion. Similarly, the pharmaceutical industry utilizes solvents in drug formulation and synthesis, with rising healthcare demands pushing production levels higher. This broad-based demand from multiple industrial segments strengthens the foundation of Spain’s industrial solvents market.
Shift Toward Eco-Friendly and Bio-Based Solvents
Environmental regulations and increasing awareness about sustainable manufacturing practices are driving the shift toward eco-friendly and bio-based solvents in Spain. Regulatory bodies within the European Union, including REACH and the ECHA, have imposed strict controls on volatile organic compound (VOC) emissions and the use of hazardous chemicals. As a result, manufacturers are adopting low-VOC, water-based, and bio-based solvent alternatives to reduce their environmental footprint while maintaining performance standards. These sustainable solvents, derived from renewable resources such as ethanol and soy, are gaining traction across industries due to their biodegradability and low toxicity. For instance, Spain’s chemical sector has been actively investing in green solvent technologies, aligning with EU sustainability goals. This regulatory and consumer-driven shift is reshaping the product landscape and driving innovation in the solvent market.
Technological Advancements in Solvent Production
Advancements in chemical processing and solvent recovery technologies are positively influencing the industrial solvents market in Spain. Modern manufacturing techniques have enabled the production of high-performance solvents with improved stability, purity, and application-specific characteristics. Additionally, the implementation of solvent recycling and recovery systems has become increasingly popular among manufacturers seeking to reduce costs and minimize waste. These technologies allow companies to reuse solvents without compromising on quality, thereby increasing operational efficiency and supporting circular economy goals. The integration of automation and digital monitoring in solvent production also ensures greater precision, compliance, and scalability, positioning Spain’s solvent industry for long-term growth.
Supportive Government Policies and Industrial Growth
Spain's supportive industrial policies and economic recovery efforts contribute significantly to the growth of the industrial solvents market. Government initiatives that promote local manufacturing, infrastructure development, and foreign investment are creating favorable conditions for industrial expansion. This growth translates into higher consumption of solvents in manufacturing, packaging, and maintenance processes. Moreover, public and private sector collaborations in innovation, research, and sustainability further enhance Spain’s position as a competitive industrial hub within Europe. The rising emphasis on energy efficiency, waste reduction, and green chemistry aligns well with solvent market trends, providing a solid platform for future expansion and investment.
Market Trends
Growth in Solvent Demand Across Diverse Industries
Spain's industrial solvents market is experiencing robust growth, driven by increasing demand across various sectors, including paints and coatings, adhesives, pharmaceuticals, and chemicals. The construction and automotive industries, in particular, are significant consumers of solvents for applications such as surface coatings and cleaning. The paints and coatings sector relies heavily on solvents for formulation and application, especially in residential, commercial, and infrastructure development projects. Similarly, the pharmaceutical industry utilizes solvents in drug formulation and synthesis, with rising healthcare demands pushing production levels higher. This broad-based demand from multiple industrial segments strengthens the foundation of Spain’s industrial solvents market.
Technological Advancements in Solvent Production
Advancements in chemical processing and solvent recovery technologies are positively influencing the industrial solvents market in Spain. Modern manufacturing techniques have enabled the production of high-performance solvents with improved stability, purity, and application-specific characteristics. Additionally, the implementation of solvent recycling and recovery systems has become increasingly popular among manufacturers seeking to reduce costs and minimize waste. These technologies allow companies to reuse solvents without compromising on quality, thereby increasing operational efficiency and supporting circular economy goals. For instance, Spain’s industrial modernization efforts have led to increased adoption of solvent recovery systems, supported by government incentives. The integration of automation and digital monitoring in solvent production also ensures greater precision, compliance, and scalability, positioning Spain’s solvent industry for long-term growth.
Supportive Government Policies and Industrial Growth
Spain's supportive industrial policies and economic recovery efforts contribute significantly to the growth of the industrial solvents market. Government initiatives that promote local manufacturing, infrastructure development, and foreign investment are creating favorable conditions for industrial expansion. This growth translates into higher consumption of solvents in manufacturing, packaging, and maintenance processes. Moreover, public and private sector collaborations in innovation, research, and sustainability further enhance Spain’s position as a competitive industrial hub within Europe. For instance, Spain’s Ministry of Industry and Tourism provides extensive support for SMEs and industrial development, fostering innovation and sustainability. The rising emphasis on energy efficiency, waste reduction, and green chemistry aligns well with solvent market trends, providing a solid platform for future expansion and investment.
Shift Toward Eco-Friendly and Bio-Based Solvents
Environmental regulations and increasing awareness about sustainable manufacturing practices are driving the shift toward eco-friendly and bio-based solvents in Spain. Regulatory bodies within the European Union, including REACH and the ECHA, have imposed strict controls on volatile organic compound (VOC) emissions and the use of hazardous chemicals. As a result, manufacturers are adopting low-VOC, water-based, and bio-based solvent alternatives to reduce their environmental footprint while maintaining performance standards. These sustainable solvents, derived from renewable resources such as ethanol and soy, are gaining traction across industries due to their biodegradability and low toxicity. This regulatory and consumer-driven shift is reshaping the product landscape and driving innovation in the solvent market.
Market Challenges Analysis
Stringent Environmental Regulations
The Spain industrial solvents market faces significant challenges due to stringent environmental regulations imposed by both national and European authorities. European Union directives, such as REACH (Registration, Evaluation, Authorization, and Restriction of Chemicals) and the European Chemicals Agency (ECHA) guidelines, have introduced strict limits on the use of volatile organic compounds (VOCs) and hazardous chemicals. Compliance with these regulations requires substantial investments in research and development for the formulation of low-VOC and eco-friendly solvents. Furthermore, regulations related to the disposal and recycling of solvents add complexity to operational processes. For many manufacturers, adhering to these ever-evolving regulatory standards can be both costly and resource-intensive, affecting profitability and operational efficiency.
Volatility in Raw Material Prices and Supply Chain Disruptions
The industrial solvents market in Spain is also hindered by volatility in raw material prices and supply chain disruptions. The cost of key raw materials, such as petrochemical derivatives and bio-based feedstocks, can fluctuate due to geopolitical tensions, trade restrictions, and changes in global demand. For instance, Spain’s reliance on imported raw materials makes it susceptible to external shocks and currency fluctuations. This price instability affects the overall cost structure of solvent production, making it difficult for manufacturers to forecast expenses and maintain competitive pricing. Additionally, the global supply chain for industrial solvents has been impacted by disruptions caused by events like the COVID-19 pandemic and international trade uncertainties. These disruptions can result in delays in production, reduced availability of raw materials, and increased transportation costs, all of which contribute to the market's instability.
Market Opportunities
The Spain industrial solvents market presents significant opportunities driven by the growing demand for sustainable and eco-friendly solutions. With increasing regulatory pressures on VOC emissions and the environmental impact of traditional solvents, there is a clear shift towards bio-based and low-VOC solvents. This change aligns with both consumer and industry preferences for greener alternatives, offering manufacturers the opportunity to innovate and develop products that meet stringent environmental standards. As industries such as paints and coatings, adhesives, and pharmaceuticals strive to reduce their carbon footprint, the demand for sustainable solvents is expected to rise. Companies that invest in research and development of environmentally friendly solvents are well-positioned to capture this emerging market segment and strengthen their competitive edge.
Additionally, the ongoing expansion of Spain’s industrial base provides ample opportunities for growth. With sectors like construction, automotive, and manufacturing experiencing consistent growth, the demand for industrial solvents is likely to increase in the coming years. Solvents are essential in a wide range of applications, including surface cleaning, coating, and chemical processing, all of which are crucial to these industries. The growing focus on infrastructure development and industrial innovation in Spain presents a fertile ground for solvent manufacturers to expand their reach. Moreover, technological advancements in solvent recovery and recycling systems provide opportunities for companies to enhance operational efficiency, reduce waste, and lower production costs, driving profitability. As industries continue to evolve and modernize, the Spain industrial solvents market stands to benefit from these favorable trends and opportunities for innovation.
Market Segmentation Analysis:
By Type:
The Spain industrial solvents market is primarily segmented by type into alcohols, ketones, esters, glycols, and others. Among these, alcohols hold a dominant position due to their versatile applications in various industries, particularly in the manufacturing of paints and coatings, cleaning agents, and pharmaceuticals. Alcohols, such as ethanol and isopropanol, are widely used because of their solvent power and relatively low toxicity. Ketones, including acetone and methyl ethyl ketone (MEK), are another significant segment due to their strong solvent properties and their critical role in the production of coatings, adhesives, and chemical formulations. Esters are also seeing increased demand, especially in the paints and coatings sector, due to their favorable evaporation rates and minimal odor, making them ideal for environmentally-friendly products. Glycols, primarily ethylene glycol and propylene glycol, are key in industrial applications, including antifreeze and de-icing solutions. The "Others" segment includes various specialty solvents that cater to niche applications, but its market share remains comparatively small.
By Application:
In terms of application, the Spain industrial solvents market is widely utilized in paints & coatings, pharmaceuticals, printing inks, adhesives & sealants, and others. The paints & coatings industry is the largest consumer of industrial solvents, driven by the growing demand for decorative and industrial coatings in construction and automotive sectors. The pharmaceutical sector also represents a significant application area, with solvents being essential in drug formulation, extraction, and synthesis processes. The printing inks segment has seen steady demand, particularly in packaging and publishing, with solvents aiding in the production of high-quality printing materials. Adhesives and sealants, another major segment, rely on solvents for formulations used in construction, automotive, and consumer goods. Other applications include cleaning agents, degreasers, and chemical processing, although these represent a smaller portion of the market. As industrial and regulatory trends evolve, the demand for solvents in these applications is expected to grow, particularly for sustainable and bio-based alternatives.
Segments:
Based on Type:
- Alcohols
- Ketones
- Esters
- Glycols
- Others
Based on Application:
- Paints & Coatings
- Pharmaceuticals
- Printing Inks
- Adhesives & Sealants
- Others
Based on End- Use:
- Construction
- Automotive
- Electronics
- Agriculture
- Others
Based on Source:
- Petrochemical-Based Solvents
- Bio-Based Solvents
Based on the Geography:
- Urban Centers (Madrid, Barcelona)
- Rural Areas
- Coastal regions
Regional Analysis
Urban Centers (Madrid, Barcelona)
The urban centers of Spain, particularly Madrid and Barcelona, dominate the industrial solvents market, contributing to approximately 55% of the total market share. These metropolitan regions are home to a large concentration of industries, including automotive, pharmaceuticals, chemicals, and manufacturing. The demand for industrial solvents in these urban hubs is primarily driven by the presence of established industries and a robust infrastructure that supports large-scale manufacturing and industrial production. Madrid, being the political and economic capital, and Barcelona, a key industrial and trade hub, are central to the distribution and consumption of solvents. Additionally, these regions see a high demand for solvents used in paints, coatings, and adhesives due to significant construction, automotive, and renovation projects. The high concentration of research and development activities in these cities further accelerates the need for innovative solvent solutions, particularly for eco-friendly and sustainable products.
Rural Areas
Rural areas in Spain account for approximately 20% of the industrial solvents market. While these regions do not have the same concentration of large-scale industrial operations as urban centers, they contribute to solvent demand through agriculture and smaller manufacturing facilities. In rural Spain, solvents are widely used in agricultural chemicals, cleaning agents, and small-scale production industries. The demand for solvents in these areas is driven by agricultural practices, particularly in the formulation of pesticides, herbicides, and fertilizers. Additionally, smaller industrial applications, such as maintenance, repairs, and local manufacturing, require solvents for cleaning, degreasing, and other processes. However, the overall market share of rural areas is limited due to the relatively lower industrial activity compared to the urban centers.
Coastal Regions
The coastal regions of Spain, particularly along the Mediterranean and Atlantic coasts, contribute to around 15% of the industrial solvents market. These areas are crucial for industries such as shipping, marine coatings, and coastal tourism, which demand solvents for maintenance, painting, and surface treatments. The coastal regions also see substantial use of solvents in the food and beverage industries, as well as in manufacturing and processing plants located near ports and industrial zones. The demand for solvents in these areas is also influenced by the growing tourism sector, where solvents are used in cleaning products, coatings for resorts and restaurants, and various hospitality applications. Despite the significance of coastal industries, the market share remains smaller than that of the urban centers due to fewer large-scale industrial operations.
Other Regions
The remaining 10% of the industrial solvents market in Spain is attributed to other regions, including smaller cities and industrial zones outside the major urban and coastal areas. These regions include parts of Castilla-La Mancha, Extremadura, and some northern areas of Spain. The demand for industrial solvents in these regions is generally driven by localized manufacturing, including food processing, textile production, and chemical industries. While these areas may not have the industrial density of larger cities, they still represent an essential part of the solvent market due to their niche industrial applications. However, due to their smaller industrial base, these regions contribute less to the overall market share compared to the major urban and coastal regions.
Key Player Analysis
- BASF SE
- Shell Chemicals
- Solvay S.A.
- Arkema S.A.
- INEOS Group
- Evonik Industries AG
- Clariant AG
- Synthomer plc
- AkzoNobel N.V.
- Perstorp Holding AB
Competitive Analysis
The Spain industrial solvents market is highly competitive, with several global and regional players dominating the landscape. Leading companies such as BASF SE, Shell Chemicals, Solvay S.A., Arkema S.A., INEOS Group, Evonik Industries AG, Clariant AG, Synthomer plc, AkzoNobel N.V., and Perstorp Holding AB are key contributors to the market’s growth. These companies maintain a competitive edge through their extensive product portfolios, which cater to various applications in industries like paints and coatings, pharmaceuticals, adhesives, and chemicals. Competitive advantage is achieved through product differentiation, with companies focusing on developing specialty solvents tailored for niche applications, such as coatings, adhesives, and pharmaceuticals. Additionally, advancements in solvent recovery and recycling technologies are becoming key differentiators. Companies are increasingly investing in R&D to enhance the performance and efficiency of their solvent products while minimizing their environmental impact. To maintain market leadership, players also prioritize expanding their distribution networks and strengthening relationships with key industry players. Strategic alliances, mergers, and acquisitions are commonly employed to enhance technological capabilities, extend product portfolios, and capture a larger market share. The growing demand for sustainable and high-performance solvents across industries such as construction, automotive, and chemical manufacturing is pushing companies to continuously innovate. As the market for industrial solvents becomes more environmentally conscious, competition is expected to intensify, with companies focusing on providing eco-friendly solutions while maintaining product performance and cost-efficiency.
Recent Developments
- In April 2025, Eastman announced off-list price increases for several EOD (Ethylene Oxide Derivatives) solvents, including Eastman™ DB Solvent, effective April 7, 2025, reflecting ongoing cost and market pressures.
- In March 2025, BASF reported generating approximately €11 billion in 2024 sales from products launched in the past five years, driven by R&D focused on sustainability, biodegradable materials, and digital transformation. The company filed 1,159 new patents in 2024, with 45% targeting sustainability. R&D investment in 2024 was €2.1 billion, with a similar budget planned for 2025.
- In March and April 2025, Shell is restructuring its global chemicals business to boost profitability and reduce capital spending by 2030. This includes exploring strategic partnerships in the U.S., potentially closing some European assets, and selling existing assets like the Singapore refinery and chemical complex. The company aims to streamline operations, focus on core businesses, and improve returns for shareholders.
- In March 2025, BASF is expanding its production capacity for aminic antioxidants at its Puebla, Mexico site, targeting the growing demand for long-life lubricants. The project is set for completion in 2026.
- In March 2025, ExxonMobil announced a $100 million upgrade to its Baton Rouge, Louisiana plant to produce ultra-high-purity (99.999%) isopropyl alcohol (IPA) for the semiconductor industry by 2027.
- In March 2024, Dow announced plans to invest in new ethylene derivatives capacity-including carbonate solvents-on the U.S. Gulf Coast. This investment, supported by the U.S. Department of Energy, aims to supply carbonate solvents for lithium-ion batteries, supporting the domestic EV and energy storage market. The facility will capture over 90% of CO₂ from ethylene oxide production, aligning with sustainability goals.
Market Concentration & Characteristics
The Spain industrial solvents market exhibits moderate concentration, with a mix of global and regional players holding a significant share of the market. A few large multinational companies dominate the market, leveraging their vast production capabilities, established distribution networks, and strong brand presence. These key players often lead in terms of product innovation, focusing on sustainable and eco-friendly solvents to meet evolving regulatory requirements. However, the market also includes a number of smaller, specialized companies that cater to niche applications and offer customized solvent solutions. This combination of large and small players fosters healthy competition, driving continuous innovation and cost-effective solutions. The market is characterized by a steady demand for high-performance solvents, particularly in industries such as paints and coatings, pharmaceuticals, and automotive. The trend towards sustainability and regulatory compliance is shaping the competitive landscape, with a growing focus on bio-based and low-VOC alternatives in response to environmental concerns.
Report Coverage
The research report offers an in-depth analysis based on Type, Application, End-Use, Source and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The demand for eco-friendly and bio-based solvents will continue to rise as environmental regulations become stricter across industries.
- Technological advancements in solvent recovery and recycling will play a crucial role in improving efficiency and reducing waste.
- The shift towards low-VOC and water-based solvents will be driven by both regulatory pressures and consumer demand for sustainable solutions.
- The pharmaceutical and healthcare sectors will remain strong drivers of solvent demand due to their critical role in drug formulation and synthesis.
- Innovation in solvent formulations to meet specific application requirements will lead to the development of specialized solvents for various industries.
- The growth of the automotive and construction sectors will significantly increase the demand for solvents used in coatings, adhesives, and cleaning agents.
- Smaller, specialized solvent manufacturers will increasingly focus on niche markets to differentiate themselves through customized products and services.
- Strong investment in R&D will continue to be a priority for major players in the market, focusing on improving solvent performance and sustainability.
- The trend towards circular economy practices will drive the adoption of solvent recovery and reuse technologies in industrial processes.
- Increasing regulatory requirements for green chemistry and sustainable manufacturing will encourage companies to develop new, environmentally friendly solvent solutions.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Spain Industrial Solvents?
What factors are driving the growth of the Spain Industrial Solvents?
What are some challenges faced by the Spain Industrial Solvents?
Who are the major players in the Spain Industrial Solvents?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Spain Industrial Solvents Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Spain Industrial Solvents Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 694.47 million → 2032: USD 1,053.25 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Spain Industrial Solvents Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Spain Industrial Solvents Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Spain Industrial Solvents Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Spain Industrial Solvents Market Drivers
- 3.3 Spain Industrial Solvents Market Restraints & Challenges
- 3.4 Spain Industrial Solvents Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Spain Industrial Solvents Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Spain Industrial Solvents Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Spain Industrial Solvents category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Spain Industrial Solvents Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Spain Industrial Solvents Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Spain Industrial Solvents market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Spain Industrial Solvents Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Spain Industrial Solvents Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Spain Industrial Solvents Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Spain Industrial Solvents (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Spain Industrial Solvents Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Spain Industrial Solvents Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Spain Industrial Solvents Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Spain Industrial Solvents Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Spain Industrial Solvents Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Spain Industrial Solvents Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Spain Industrial Solvents Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Spain Industrial Solvents Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Spain Industrial Solvents Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
