
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
| Chronic Pain Market Size 2023 | USD 1,701.51 Million |
| Chronic Pain Market, CAGR | 3.55% |
| Chronic Pain Market Size 2032 | USD 2,369.07 Million |
Market Overview
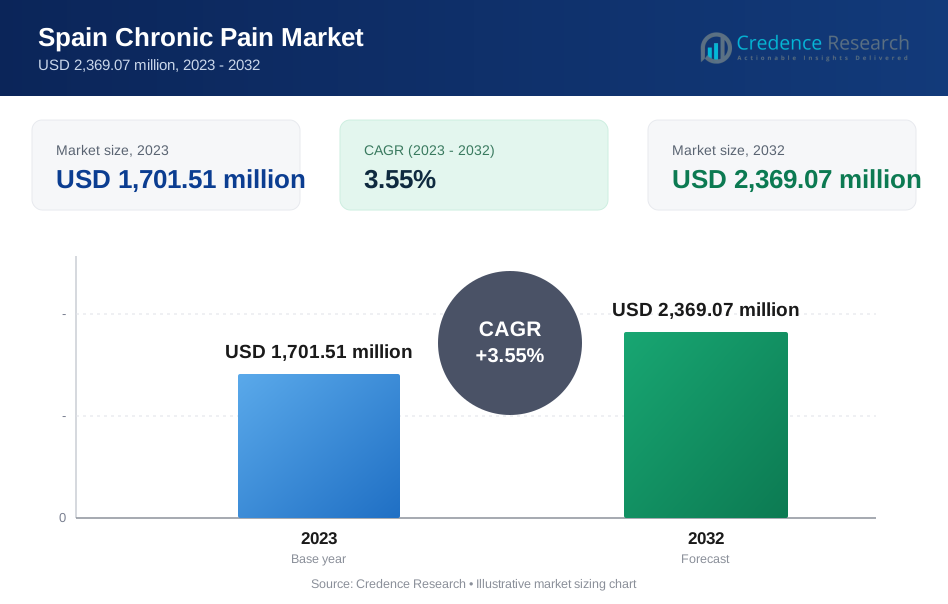
The Chronic Pain Market in Spain is projected to grow from USD 1,701.51 million in 2023 to USD 2,369.07 million by 2032, at a CAGR of 3.55% from 2024 to 2032.
The chronic pain market in Spain is driven by an aging population, increasing prevalence of conditions like arthritis and neuropathy, and greater awareness of pain management options. Advances in treatment modalities, including pharmacological therapies, physical therapies, and innovative technologies, contribute to market growth. Additionally, the rising demand for non-invasive treatments and personalized care solutions is shaping the market. The Spanish healthcare system’s focus on improving pain management programs and expanding access to specialized care further fuels the market’s expansion. Moreover, increased government spending on healthcare initiatives aimed at improving the quality of life for chronic pain sufferers is expected to drive market demand. Trends like digital health solutions, telemedicine for remote pain management, and the integration of AI in personalized treatment plans are expected to enhance patient outcomes and make care more accessible, which will likely boost the market over the forecast period.
Spain’s chronic pain market demonstrates significant geographical disparities, with urban centers like Madrid and Barcelona serving as hubs for advanced pain management solutions due to their concentration of healthcare facilities, specialists, and access to innovative treatments. In contrast, rural areas face challenges such as limited access to specialized care, delayed diagnoses, and lower awareness of treatment options. Efforts to bridge these gaps through telemedicine and government-led healthcare reforms are creating opportunities for growth in underserved regions. The market features several prominent players, including Abbott Laboratories, Pfizer Inc., Eli Lilly & Company, Cara Therapeutics, and Ferrer Spain, among others. These companies are actively driving innovation in pharmacological and non-pharmacological therapies while collaborating with healthcare providers and advocacy groups to expand treatment access. Their focus on targeted drug delivery systems and personalized therapies underscores the dynamic nature of the market, paving the way for advancements in Spain's chronic pain management landscape.
Market Insights
- The Spain chronic pain market was valued at USD 1,701.51 million in 2023 and is projected to reach USD 2,369.07 million by 2032, growing at a CAGR of 3.55%.
- The aging population in Spain is a significant driver, with an increasing number of elderly individuals requiring pain management solutions.
- Sedentary lifestyles and unhealthy habits are contributing to the rising prevalence of chronic pain conditions such as arthritis and back pain.
- Limited access to specialized care, particularly in rural areas, and long wait times for treatments pose significant challenges to market growth.
- Urban centers like Madrid and Barcelona dominate the market due to better healthcare infrastructure and accessibility to advanced treatments.
- Government initiatives, including telemedicine integration, are improving access to care in underserved regions, offering growth opportunities.
- Key players like Abbott Laboratories, Pfizer Inc., and Ferrer Spain are focusing on innovative therapies and collaborations to enhance market reach.
Market Drivers
Aging Population
Spain is experiencing a significant demographic shift, with an increasing number of elderly individuals. As the population ages, the prevalence of chronic pain conditions, such as arthritis and neuropathy, rises, contributing to a growing demand for effective pain management solutions. For instance, as of January 2024, the population aged over 65 years in Spain amounted to 9.93 million people. Older adults are particularly susceptible to these conditions, leading to a surge in the need for treatments that address both acute and chronic pain. This shift is expected to further drive the market for chronic pain therapies in Spain, with healthcare systems focusing on providing better access to pain relief for the aging population.
Advancements in Diagnostic Tools and Targeted Drug Delivery Systems
Recent advancements in diagnostic technologies have enabled earlier and more accurate diagnosis of chronic pain conditions, allowing for more effective management. Enhanced imaging techniques and biomarkers help healthcare providers identify the underlying causes of pain, leading to better-targeted treatments. For instance, advanced neuroimaging techniques have been developed to observe alterations in brain activity associated with chronic pain. Additionally, targeted drug delivery systems are gaining traction, offering more precise and effective pain management. These systems reduce side effects and improve patient outcomes by delivering medications directly to the affected area. As these innovations continue to evolve, they are expected to significantly impact the chronic pain treatment landscape in Spain.
Collaborations and Partnerships
Pharmaceutical companies are increasingly collaborating with healthcare providers, researchers, and patient advocacy groups to develop innovative pain management solutions. These partnerships are crucial in accelerating the development of new therapies, clinical trials, and expanding market access. For instance, Grünenthal Spain has been recognized for its efforts in improving chronic pain management through collaborations with patient groups, healthcare professionals, and public and private institutions. Through these collaborations, companies can leverage expertise from various sectors, ensuring that treatments are tailored to patient needs and are efficiently brought to market. This collaborative approach enhances research and speeds up the delivery of effective solutions, which is essential for addressing the growing demand for chronic pain therapies in Spain.
Increasing Prevalence of Chronic Pain Conditions
Sedentary lifestyles, unhealthy dietary habits, and rising stress levels are contributing factors to the increasing prevalence of chronic pain conditions like arthritis, fibromyalgia, and back pain in Spain. These conditions are becoming more widespread across various age groups, not just the elderly. As the incidence of these ailments rises, there is a growing demand for innovative therapies to manage chronic pain effectively. This trend presents a substantial market opportunity for companies in the pain management sector to develop and offer new, effective treatments that cater to the specific needs of patients suffering from these conditions.
Market Trends
Rising Prevalence of Chronic Pain and Increased Awareness
Spain is witnessing a rise in chronic pain cases, largely driven by the aging population and increasing sedentary lifestyles. As the elderly population grows, the number of individuals susceptible to chronic pain conditions like arthritis, fibromyalgia, and back pain is also rising. For instance, a nationwide study found that chronic pain affects a significant portion of the Spanish population, with many individuals experiencing limitations in their daily activities and impacts on their mental health. Additionally, unhealthy habits such as lack of physical activity and poor dietary choices are contributing to a greater prevalence of these conditions across various age groups. This growing burden of chronic pain is driving the demand for effective treatments and therapies. Increased awareness of chronic pain has empowered patients to seek proper care, with patient advocacy groups playing a key role in highlighting the importance of pain management and pushing for improved access to treatment. Moreover, the rise of digital health solutions is making pain management more accessible, with remote monitoring and telehealth consultations gaining traction. These trends are not only improving patient outcomes but also making chronic pain care more efficient and inclusive.
Advancements in Treatment Options and Government Support
The market for chronic pain management in Spain is evolving rapidly, thanks to advancements in treatment options. Pharmaceutical innovations are driving the development of more effective and targeted pain medications, allowing for better management of chronic conditions. Alongside these drug advancements, non-pharmacological therapies such as physical therapy, acupuncture, and mindfulness-based interventions are gaining popularity as alternative treatment options. For instance, the Spanish Chronic Pain Self-Management Program has been implemented to help patients manage their pain through various techniques and support systems. Targeted drug delivery systems are also revolutionizing pain management by offering more precise and effective treatments with fewer side effects. The Spanish government has played a supportive role by implementing healthcare reforms aimed at increasing access to care and improving affordability for patients. Furthermore, favorable reimbursement policies for chronic pain treatments are encouraging adoption, making it easier for patients to access a range of pain management options. As a result, a multimodal approach combining pharmacological and non-pharmacological therapies is becoming more common, with treatment plans being increasingly personalized to suit the specific needs of patients. The post-COVID-19 landscape has also had a lasting impact, with heightened awareness around chronic pain and the continued adoption of telehealth services for pain management. These combined factors are setting the stage for a dynamic and growing chronic pain market in Spain.
Market Challenges Analysis
Limited Access to Specialized Care and Underdiagnosis
In Spain, limited access to specialized care poses a significant challenge for chronic pain patients. There is a shortage of pain specialists, and their uneven distribution across regions means that many patients in rural or underserved areas struggle to receive timely, specialized treatment. Additionally, long wait times for appointments and diagnostic procedures can further delay effective treatment initiation, prolonging patient suffering. Compounding this issue is the underdiagnosis and misdiagnosis of chronic pain conditions. Limited awareness among both healthcare providers and patients about the full spectrum of chronic pain can lead to conditions being overlooked or misinterpreted. The lack of standardized, comprehensive assessment tools also contributes to difficulties in accurate diagnosis and treatment planning, meaning many patients may not receive the appropriate interventions needed for effective pain management.
Inadequate Reimbursement and Stigma Around Chronic Pain
Another key challenge in Spain is the inadequate reimbursement policies for chronic pain treatments. Non-pharmacological therapies, such as physical therapy, acupuncture, and psychological interventions, often do not receive sufficient coverage under healthcare plans, limiting patient access to holistic pain management options. For instance, reimbursement policies often favor pharmacological treatments over non-pharmacological ones, creating barriers for patients seeking comprehensive care. Furthermore, the strict criteria for drug reimbursement can prevent some patients from accessing newer or more specialized medications that may be crucial for their treatment. Beyond financial and logistical barriers, social stigma surrounding chronic pain adds another layer of difficulty. Misconceptions about chronic pain can lead to stigmatization and discrimination, impacting patients' quality of life and their willingness to seek help. In some cases, patients may be blamed for their pain, resulting in a lack of empathy and support from both healthcare providers and society. Additionally, patients face adherence challenges due to complex treatment regimens that include multiple medications and lifestyle changes. Side effects from treatments can further discourage adherence, undermining treatment efficacy. Finally, a lack of patient education and empowerment remains a significant issue. Without proper understanding of their condition and available treatment options, patients struggle to manage their pain effectively. Empowering patients with the knowledge to actively participate in their care is crucial for improving outcomes.
Market Opportunities
Expansion of Multimodal and Personalized Therapies
The chronic pain market in Spain presents significant opportunities through the development and adoption of multimodal and personalized treatment approaches. As patient needs become increasingly diverse, the integration of pharmacological and non-pharmacological therapies is gaining momentum. Companies have the potential to innovate by creating solutions that combine traditional medications with alternative treatments like physical therapy, cognitive behavioral therapy, and mindfulness practices. Personalized treatment plans tailored to individual patient profiles, including genetic predispositions and lifestyle factors, can improve outcomes and enhance patient satisfaction. The growing focus on precision medicine and advancements in diagnostic tools further enable healthcare providers to deliver more targeted and effective care, opening new avenues for growth in the market.
Growth in Digital Health Solutions and Awareness Campaigns
The rapid advancement of digital health technologies offers another key opportunity in Spain's chronic pain market. Telemedicine platforms, wearable devices, and mobile applications for pain tracking and management are becoming increasingly popular, especially in a post-COVID-19 world. These solutions not only improve accessibility but also empower patients to take an active role in managing their conditions. Additionally, raising awareness about chronic pain through targeted campaigns can bridge knowledge gaps among both patients and healthcare providers. Collaborations with patient advocacy groups and the government to promote awareness and reduce stigma surrounding chronic pain can enhance treatment uptake. These efforts, combined with favorable healthcare policies, provide a fertile ground for businesses to address unmet needs and expand their presence in the Spanish market.
Market Segmentation Analysis:
By Indication:
The chronic pain market in Spain is segmented by indications such as neuropathic pain, arthritis pain, chronic back pain, cancer pain, and migraine. Neuropathic pain represents a significant portion of the market, driven by conditions like diabetes and multiple sclerosis, which are prevalent among the aging population. Arthritis pain is another dominant segment, fueled by the growing elderly demographic and the increasing prevalence of osteoarthritis and rheumatoid arthritis. Chronic back pain is widespread, attributed to sedentary lifestyles and occupational hazards. Cancer pain, while a smaller segment, remains critical due to the necessity for advanced pain management in palliative care settings. Migraines, affecting individuals across various age groups, are seeing an increased focus on innovative therapies to improve patient quality of life. The diverse nature of these indications highlights the need for comprehensive and tailored treatment options, making this segmentation vital for market players targeting Spain's chronic pain landscape.
By Drug Class:
The market is also segmented by drug class, including opioids, non-steroidal anti-inflammatory drugs (NSAIDs), anticonvulsants, antidepressants, and others. Opioids continue to be widely used for severe and unmanageable pain, although concerns over dependency and side effects are encouraging the exploration of alternative options. NSAIDs remain a mainstay for mild to moderate pain, particularly in conditions like arthritis and migraines. Anticonvulsants and antidepressants are gaining traction due to their efficacy in managing neuropathic pain and fibromyalgia. The "other" category encompasses emerging drug classes that hold promise for addressing unmet needs in chronic pain management. The increasing preference for targeted and non-addictive therapies is driving innovation within this segment, creating opportunities for pharmaceutical companies to differentiate themselves in the competitive Spanish market.
Segments:
Based on Indication:
- Neuropathic Pain
- Arthritis Pain
- Chronic Back Pain
- Cancer Pain
- Migraine
Based on Drug Class:
- Opioids
- Non-Steroidal
- Anticonvulsants
- Antidepressants
- Drug Class 5
Based on Application:
- Musculoskeletal
- Neuropathy
- Oncology
- Others
Based on Distribution Channel:
- Hospital Pharmacies
- Retail Pharmacies
- Others
Based on the Geography:
- Urban Centers (Madrid, Barcelona)
- Rural Areas
Regional Analysis
Urban centers
Urban centers, including Madrid and Barcelona, hold a substantial share of Spain's chronic pain market, accounting for approximately 65% of the total market. These cities benefit from a concentration of advanced healthcare facilities, pain management specialists, and greater access to innovative treatments. The urban population’s awareness of chronic pain conditions and treatment options is significantly higher compared to rural areas, leading to better diagnosis and early intervention. Additionally, the availability of multimodal pain management solutions, including pharmacological and non-pharmacological therapies, is more prominent in these regions. Government and private healthcare providers in Madrid and Barcelona are investing heavily in digital health technologies, such as telemedicine and wearable devices, which are transforming chronic pain management. The urban populace also has better access to patient advocacy groups and educational campaigns that promote awareness and reduce stigma, further driving the adoption of pain management solutions. The high concentration of healthcare resources and awareness levels positions urban centers as the primary drivers of market growth.
Rural Areas
Rural areas in Spain represent the remaining 35% of the chronic pain market, characterized by unique challenges that impact market dynamics. These regions often face limited access to specialized pain care due to the uneven distribution of healthcare professionals and facilities. Long travel distances to urban centers and a shortage of pain specialists contribute to delays in diagnosis and treatment, which exacerbate chronic pain conditions among rural residents. Awareness of chronic pain and its management options is also relatively low, hindering timely intervention. Despite these challenges, there is growing potential for market growth in rural areas, driven by government initiatives to improve healthcare access and affordability. Programs aimed at integrating telemedicine and mobile health solutions are bridging the gap between rural patients and specialized care. Furthermore, targeted outreach campaigns by healthcare providers and patient advocacy groups are gradually increasing awareness about chronic pain and its treatment options. As these initiatives gain traction, rural areas are expected to contribute more significantly to Spain’s chronic pain market in the coming years.
Key Player Analysis
- Abbott Laboratories
- Pfizer Inc.
- Eli Lilly & Company
- Cara Therapeutics
- Chattem (Sanofi)
- Endo International plc
- Merck & Co., Inc.
- Hoffmann-La Roche AG
- Ferrer Spain
- Company 11
- Company 12
- Company 13
- Company 14
Competitive Analysis
The competitive landscape of Spain's chronic pain market is characterized by the presence of established pharmaceutical companies focusing on innovative therapies and strategic initiatives. Leading players such as Abbott Laboratories, Pfizer Inc., Eli Lilly & Company, Cara Therapeutics, Ferrer Spain, and Sanofi are driving market advancements through robust research and development efforts. These companies are investing in targeted drug delivery systems, precision medicine, and non-pharmacological pain management solutions to address the growing demand for effective and personalized therapies. Collaborations with healthcare providers and research institutions are common strategies among key players to accelerate the development of novel treatments. Additionally, patient-centric approaches, including education campaigns and advocacy group partnerships, are being prioritized to enhance awareness and accessibility to chronic pain solutions. The entry of advanced digital health platforms and wearable technologies is further intensifying competition, as companies aim to integrate these tools for improved patient monitoring and management.
Recent Developments
- In July 2024, Boston Scientific Corporation announced positive five-year results for the Intracept Intraosseous Nerve Ablation System, presented at the American Society of Pain & Neuroscience (ASPN) conference in Miami Beach, Florida. The data, pooled from three clinical trials, highlight the effectiveness of the Intracept system in treating vertebrogenic low back pain, a condition caused by damage to vertebral endplates.
- In April 2024, Vertex Pharmaceuticals announced significant progress in its suzetrigine pain program, an oral selective NaV1.8 pain signal inhibitor that is poised to become the first new class of medicine for acute and neuropathic pain in over two decades. Following positive Phase 3 results in January 2024, the FDA granted New Drug Application (NDA) submission for suzetrigine in moderate-to-severe acute pain.
- In February 2024, CinCor Pharma, Inc. was acquired by AstraZeneca. Cincor is a clinical stage biopharmaceutical company based out of USA that is focused on developing novel treatments for severe hypertension and chronic kidney disease.
- In January 2024, Bayer AG disclosed its plan to strengthen its pharmaceutical and consumer health businesses. This move will bolster the company’s American market presence.
- In January 2024, Sanofi announced its acquisition of Inhibrx, Inc., aiming to incorporate a potential best-in-class rare disease asset for Alpha-1 Antitrypsin Deficiency into its pipeline.
- In December 2023, Forever Cheer, a pharmaceutical company holding more than 10 global patents, selected Hong Kong as the launchpad for its innovative pain management drugs, aiming to expand its global footprint and significantly impact the healthcare industry
- In August 2023, MOBE and Override, digital health innovators, partnered to introduce a shared savings program for chronic pain management. This initiative focuses on providing personalized pain treatment through data analytics and behavioral health coaching, with the goal of reducing healthcare costs.
Market Concentration & Characteristics
The chronic pain market in Spain exhibits a moderately concentrated structure, with a mix of global pharmaceutical giants and regional players driving its dynamics. Leading companies like Abbott Laboratories, Pfizer Inc., Eli Lilly & Company, and Ferrer Spain dominate the market through a strong portfolio of innovative products, extensive research and development initiatives, and strategic partnerships. These players benefit from their well-established distribution networks and advanced technological capabilities, which allow them to cater to diverse patient needs effectively. The market is characterized by a growing emphasis on personalized therapies, multimodal treatment approaches, and digital health solutions. Non-pharmacological interventions, such as physical therapy and mindfulness practices, are gaining traction alongside traditional medications, reflecting a shift toward holistic pain management. Despite advancements, challenges such as uneven access to care and underdiagnosis in rural areas persist, impacting market uniformity. The integration of telemedicine and government-backed healthcare reforms is addressing these gaps, creating opportunities for smaller players to expand their footprint. This evolving landscape fosters competition while encouraging collaboration, as companies strive to address unmet needs, improve patient outcomes, and expand their market share in Spain's chronic pain segment.
Report Coverage
The research report offers an in-depth analysis based on Indication, Drug Class, Application, Distribution Channel and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The chronic pain market in Spain is expected to witness steady growth, driven by an aging population and increasing prevalence of chronic conditions.
- Advances in diagnostic technologies and personalized medicine will enhance the accuracy of pain management solutions.
- Telemedicine and digital health tools are likely to play a pivotal role in improving access to care, especially in underserved rural areas.
- Government initiatives and healthcare reforms will promote the adoption of cost-effective and innovative treatment options.
- Non-pharmacological therapies such as physical therapy, acupuncture, and mindfulness practices will gain popularity as part of multimodal pain management approaches.
- The demand for targeted drug delivery systems will rise due to their precision and reduced side effects.
- Pharmaceutical companies will continue to invest in research and development to address unmet needs and introduce novel therapies.
- Collaborations between healthcare providers, patient advocacy groups, and industry players will drive awareness and improve access to treatments.
- Efforts to address challenges such as stigma, underdiagnosis, and limited access to specialists will shape the market’s future trajectory.
- The integration of wearable technologies and remote monitoring systems will enhance patient outcomes and revolutionize chronic pain management.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Aging Population
Spain's rapidly aging demographic is leading to a higher prevalence of chronic pain conditions such as arthritis and neuropathy, increasing the demand for effective pain management solutions tailored to older adults.
Advancements in Diagnostic and Treatment Technologies
Innovations in diagnostic tools, targeted drug delivery systems, and digital health solutions are enabling earlier diagnosis and more precise, personalized pain management, improving patient outcomes and expanding market potential.
Government Healthcare Initiatives and Telemedicine
Spanish government reforms and investments in telemedicine are improving access to pain management, especially in underserved rural areas, thereby expanding the market reach and reducing disparities in care.
Rising Prevalence of Chronic Pain Conditions
Sedentary lifestyles, unhealthy habits, and increased stress levels are contributing to a growing incidence of chronic pain conditions across various age groups, driving the need for both pharmacological and non-pharmacological therapies.
Collaborations and Partnerships
Pharmaceutical companies are increasingly partnering with healthcare providers, researchers, and advocacy groups to accelerate the development and adoption of innovative therapies, expanding access and awareness for chronic pain management.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Spain Chronic Pain Market?
What factors are driving the growth of the Spain Chronic Pain Market?
What are the key segments within the Spain Chronic Pain Market?
What are some challenges faced by the Spain Chronic Pain Market?
Who are the major players in the Spain Chronic Pain Market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Drug Class
- 1.2.1 Opioids
- 1.2.2 Non-Steroidal Anti-Inflammatory Drugs (NSAIDs)
- 1.2.3 Anticonvulsants
- 1.2.4 Antidepressants
- 1.2.5 Other Drug Classes
- 1.3 By Indication
- 1.3.1 Neuropathic Pain
- 1.3.2 Arthritis Pain
- 1.3.3 Chronic Back Pain
- 1.3.4 Cancer Pain
- 1.3.5 Migraine
- 1.4 By Application
- 1.4.1 Musculoskeletal
- 1.4.2 Neuropathy
- 1.4.3 Oncology
- 1.4.4 Others
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2023: USD 1,701.51 million → 2032: USD 2,369.07 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2023
- 2.6.2 Forecast Period: 2023-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2023
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Spain Chronic Pain Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Spain Chronic Pain Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2023-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2023-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Spain Chronic Pain Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2023-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Spain Chronic Pain Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Spain Chronic Pain Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Spain Chronic Pain Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Spain Chronic Pain Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Spain Chronic Pain Market Outlook, 2023-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2023: USD 1,701.51 million → 2032: USD 2,369.07 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2023
- 11.2 Market Forecast, 2023-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Spain Chronic Pain Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2023
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Drug Class - Market Size and Forecast, 2023-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2023-2032
- 12.3.4 Volume Forecast, 2023-2032
- 12.3.5 Base-Year Market Share, 2023
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Opioids
- 12.3.7.2 Non-Steroidal Anti-Inflammatory Drugs (NSAIDs)
- 12.3.7.3 Anticonvulsants
- 12.3.7.4 Antidepressants
- 12.3.7.5 Other Drug Classes
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Indication - Market Size and Forecast, 2023-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2023-2032
- 12.4.4 Volume Forecast, 2023-2032
- 12.4.5 Base-Year Market Share, 2023
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Neuropathic Pain
- 12.4.7.2 Arthritis Pain
- 12.4.7.3 Chronic Back Pain
- 12.4.7.4 Cancer Pain
- 12.4.7.5 Migraine
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Application - Market Size and Forecast, 2023-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2023-2032
- 12.5.4 Volume Forecast, 2023-2032
- 12.5.5 Base-Year Market Share, 2023
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Musculoskeletal
- 12.5.7.2 Neuropathy
- 12.5.7.3 Oncology
- 12.5.7.4 Others
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Spain Chronic Pain End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Spain Chronic Pain Geographic Market Outlook, 2023-2032
- 14.1 Domestic Market Distribution and Demand Clusters
- 14.2 State- or Province-Wise Market Size and Forecast, 2023-2032
- 14.3 City and Metropolitan Market Outlook
- 14.4 Industrial, Manufacturing and Commercial Clusters
- 14.5 Geographic Concentration of Key End Users
- 14.6 Local Pricing and Purchasing Differences
- 14.7 Domestic Production Facilities and Capacity Map
- 14.8 Local Infrastructure and Project Pipeline
- 14.9 State-Level Policy and Incentive Differences
- 14.10 Subnational Investment Hotspots and Opportunities
- 14.11 Distribution and Logistics Networks
- 14.12 Domestic Competitive Footprint
Chapter 15 Spain Chronic Pain Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2023-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Spain Chronic Pain Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2023
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2023-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Abbott Laboratories
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Pfizer Inc.
- 18.4 Eli Lilly & Company
- 18.5 Cara Therapeutics
- 18.6 Ferrer Spain
- 18.7 Sanofi (Chattem)
- 18.8 Endo International plc
- 18.9 Merck & Co., Inc.
- 18.10 Hoffmann-La Roche AG
- 18.11 Boston Scientific Corporation
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

