
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
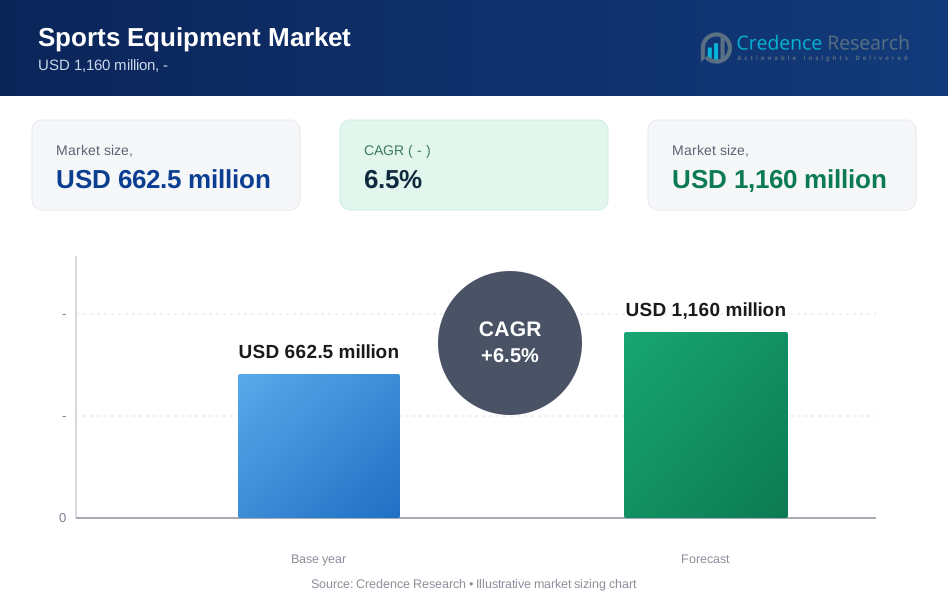
| Sports Equipment Market Size 2024 | USD 662.5 million |
| Sports Equipment Market, CAGR | 6.5% |
| Sports Equipment Market Size 2032 | USD 1,160 million |
Market Overview
The Sports Equipment Market is experiencing substantial growth, driven by increasing participation in sports and fitness activities globally. As of 2024, the global Sports Equipment Market is valued at approximately USD 662.5 million and is projected to grow at a compound annual growth rate (CAGR) of 6.5% over the forecast period, reaching around USD 1,160 million by 2032. This robust growth is reflective of the rising health consciousness among consumers and the growing trend of recreational and competitive sports.
Several key factors are propelling the market's expansion. The increasing number of fitness enthusiasts and the rising popularity of sports leagues and events are major contributors. Additionally, the surge in online retailing and the availability of a wide range of sports equipment at competitive prices are further enhancing market accessibility. Innovations in sports technology, such as smart wearables and performance tracking devices, are also driving demand as consumers seek to improve their athletic performance.
Regionally, North America dominates the Sports Equipment Market, primarily due to a strong sports culture and significant investment in sports infrastructure. Europe follows closely, with a growing emphasis on fitness and wellness. The Asia-Pacific region is expected to witness remarkable growth during the forecast period, fueled by rising disposable incomes, urbanization, and increased government support for sports initiatives. Emerging economies in this region, particularly China and India, present substantial growth opportunities, driven by their large populations and increasing engagement in sports and fitness activities.
Market Drivers:
Increasing Health Consciousness:
The growing awareness of health and fitness among consumers is one of the primary drivers of the Sports Equipment Market. With rising obesity rates and associated health risks, individuals are more inclined to adopt active lifestyles, resulting in increased participation in sports and fitness activities. According to the World Health Organization (WHO), physical inactivity is one of the leading risk factors for global mortality, contributing to approximately 3.2 million deaths annually. This alarming statistic has prompted governments and health organizations to promote physical activity, resulting in initiatives aimed at increasing participation in sports. For instance, the Global Action Plan on Physical Activity 2018-2030 by WHO encourages countries to implement strategies that aim for a 15% reduction in physical inactivity by 2030, further boosting demand for sports equipment.
Growth of Sports Participation and Events:
The rise in sports participation, both recreationally and competitively, significantly contributes to the growth of the Sports Equipment Market. Various global events, such as the Olympics and World Championships, inspire people to engage in sports, leading to increased sales of related equipment. The International Olympic Committee (IOC) reports that the Tokyo 2020 Olympics saw participation from over 11,000 athletes across 33 sports, showcasing the growing interest in competitive sports. Moreover, grassroots initiatives and community sports programs funded by local governments encourage youth participation, fostering a culture of fitness and competition. For instance, initiatives supported by the U.S. Department of Education aim to increase sports participation in schools by 20% over the next five years, driving the demand for sports equipment among younger demographics.
Technological Advancements in Sports Equipment:
Innovations in technology have revolutionized the Sports Equipment Market, leading to the development of advanced and high-performance products. Enhanced materials, such as lightweight composites and moisture-wicking fabrics, are increasingly being used to improve the functionality and performance of sports equipment. According to the International Sports Technology Association (ISTA), technological advancements have led to a 15% increase in the performance efficiency of various sports gear over the past five years. Additionally, the integration of smart technologies-such as wearable fitness trackers and performance-monitoring devices-has gained popularity among consumers, who seek to optimize their training and enhance athletic performance. This trend is further supported by government research initiatives aimed at promoting sports innovation, such as the National Institutes of Health (NIH) in the United States, which allocates funding for projects that have increased research in sports science by 30% in the last decade.
E-commerce and Digital Retail Growth:
The proliferation of e-commerce platforms has significantly transformed how consumers purchase sports equipment. With the rise of online retailing, consumers now have greater access to a wider range of products and brands, leading to increased sales. According to the International Monetary Fund (IMF), e-commerce in the retail sector is projected to grow by approximately 20% annually through 2025, indicating a substantial shift in consumer purchasing behavior. The convenience of online shopping, coupled with the availability of detailed product information and customer reviews, enhances the consumer experience and drives sales. Furthermore, government initiatives supporting digital infrastructure and online commerce, such as those outlined in the Digital Economy Strategy by the European Commission, aim to double the number of e-commerce businesses in Europe by 2025, contributing to the growth of e-commerce in the sports equipment sector.
Market Trends:
Shift Toward Sustainable Products:
The trend toward sustainability is gaining momentum within the Sports Equipment Market, as consumers increasingly prefer eco-friendly products. This shift is driven by heightened awareness of environmental issues and a desire for responsible consumption. Major brands are responding by developing sustainable equipment made from recycled materials and eco-friendly manufacturing processes. For instance, the U.S. Environmental Protection Agency (EPA) has reported that the market for recycled sports equipment is expected to grow by 25% by 2025, as consumers seek products that align with their environmental values. Additionally, the World Wildlife Fund (WWF) emphasizes that sustainable practices can significantly reduce carbon footprints, with studies showing that brands adopting eco-friendly materials can lower emissions by up to 30%. Companies are also investing in transparent supply chains, ensuring that their products are sourced responsibly. This commitment to sustainability is not only appealing to environmentally conscious consumers but also aligns with governmental initiatives promoting green business practices, such as the European Union's Green Deal, which aims to make Europe the first climate-neutral continent by 2050.
Rise of Personalization and Customization:
Another significant trend in the Sports Equipment Market is the increasing demand for personalized and customized products. Consumers are seeking equipment that reflects their individual preferences, styles, and needs. This trend is facilitated by advancements in manufacturing technology, including 3D printing and data analytics, which allow companies to offer tailored products at scale. For instance, the National Institutes of Health (NIH) has highlighted the potential of personalized fitness solutions in improving athletic performance, reporting that customized training equipment can enhance user engagement by up to 40%. Furthermore, the U.S. Department of Commerce has noted that the customization market is projected to reach USD 100 billion by 2025, driven by consumer demand for unique products. Many brands are now offering customizable options, allowing consumers to select colors, materials, and even performance features. This trend is particularly prevalent in sectors like running shoes and cycling gear, where individual biomechanics and personal aesthetics play a crucial role in purchasing decisions. The growing emphasis on personalization is supported by research from governmental bodies, which indicates that consumers are willing to pay a premium for tailored sports equipment that meets their specific requirements.
Market Challenges Analysis:
Intense Competition and Market Saturation:
One of the primary challenges facing the Sports Equipment Market is intense competition and market saturation. With numerous brands vying for consumer attention, differentiating products has become increasingly difficult. Established companies and new entrants alike are investing heavily in marketing and innovation to capture market share. This competitive landscape often leads to price wars, which can erode profit margins and make it challenging for smaller or emerging brands to sustain their operations. For example, according to the International Trade Administration (ITA), the sports equipment industry has seen a consistent influx of new companies over the past decade, resulting in a crowded marketplace where consumer loyalty is hard to secure. Additionally, the rapid pace of product innovation requires companies to continually invest in research and development. This not only strains financial resources but also places pressure on companies to keep up with evolving consumer preferences and technological advancements.
Supply Chain Disruptions:
Another significant challenge impacting the Sports Equipment Market is supply chain disruptions. Recent global events, such as the COVID-19 pandemic, have exposed vulnerabilities in manufacturing and distribution networks. Many companies faced delays in production and shipping, leading to inventory shortages and unmet consumer demand. According to the World Bank, disruptions in global supply chains have contributed to increased costs for raw materials and shipping, which can further strain profit margins for sports equipment manufacturers. Additionally, the reliance on international suppliers complicates logistics and increases the risk of further disruptions due to geopolitical tensions or trade policies. Companies are now forced to rethink their supply chain strategies, considering options like local sourcing or diversifying suppliers to mitigate risks. However, these strategies often come with their own set of challenges, including higher costs and longer lead times. As a result, brands must find a balance between maintaining product availability and managing operational costs, all while navigating an uncertain economic landscape.
Market Segmentation Analysis:
By Type
The Sports Equipment Market can be segmented by type into several categories, including fitness equipment, team sports equipment, individual sports equipment, and outdoor and adventure gear. Fitness equipment encompasses items like treadmills, stationary bikes, and weights, catering to the growing trend of home workouts and personal fitness. Team sports equipment includes gear for popular sports such as soccer, basketball, and cricket, which benefits from the rise of community sports leagues. Individual sports equipment features products for activities like tennis, golf, and swimming, attracting consumers seeking to enhance their personal athletic skills. Outdoor and adventure gear, including hiking, camping, and cycling equipment, appeals to the increasing interest in outdoor recreational activities. Each type responds to distinct consumer needs and preferences, driving targeted marketing and product development strategies.
By Technology
The segmentation by technology highlights the innovations shaping the Sports Equipment Market, such as smart technologies, advanced materials, and manufacturing processes. Smart technologies encompass wearables and connected devices that provide users with real-time performance data, enhancing training regimens and overall athletic performance. Advanced materials, like lightweight composites and moisture-wicking fabrics, are increasingly utilized in sports gear to improve functionality and comfort. Moreover, manufacturing processes such as 3D printing enable customization and rapid prototyping, allowing brands to respond quickly to consumer demands for personalized products. This technological segmentation indicates a trend toward integrating high-tech features into sports equipment, appealing to tech-savvy consumers who prioritize performance and innovation.
By End-User
The Sports Equipment Market can also be segmented by end-user, which includes individual consumers, schools and educational institutions, professional sports teams, and fitness centers. Individual consumers make up a significant portion of the market, driven by increasing health consciousness and interest in personal fitness. Schools and educational institutions often invest in sports equipment to promote physical education and extracurricular activities, while professional sports teams require high-quality gear for training and competition. Fitness centers and gyms are also major consumers, seeking a diverse range of equipment to accommodate various fitness programs. This segmentation reflects the diverse applications of sports equipment and the unique requirements of different user groups, shaping product offerings and marketing strategies within the industry
Segmentations:
Based on Product Type:
- Fitness Equipment
- Team Sports Equipment
- Individual Sports Equipment
- Outdoor and Adventure Gear
Based on Technology:
- Smart Technologies
- Advanced Materials
- 3D Printing and Customization
- Traditional Manufacturing Processes
Based on End-User:
- Individual Consumers
- Schools and Educational Institutions
- Professional Sports
- Teams Fitness
- Centers and Gyms
Based on Region:
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis:
North America
North America holds a significant share of the Sports Equipment Market, accounting for approximately 35% of the total market share. This dominance is primarily driven by a strong sports culture, high disposable incomes, and widespread health consciousness among consumers. The United States, in particular, is a key contributor, with a robust demand for both fitness equipment and team sports gear. Major sporting events, such as the Super Bowl and the Olympics, further stimulate interest and participation in sports, leading to increased sales of related equipment. Additionally, government initiatives promoting physical activity and wellness, such as the President's Council on Sports, Fitness & Nutrition, play a crucial role in encouraging the population to engage in sports and fitness activities. As the trend toward home workouts continues to rise, the demand for fitness equipment in North America is expected to remain strong, further solidifying its market position.
Europe
Europe is another critical region in the Sports Equipment Market, capturing around 30% of the total market share. The region benefits from a diverse sports landscape, with various popular sports, including football (soccer), cricket, and tennis. Countries like Germany, the UK, and France are at the forefront of this growth, driven by both recreational participation and professional sports leagues. The European Union's initiatives to promote sports and physical activity, including funding for community sports programs, have fostered an environment conducive to growth. Moreover, the increasing focus on sustainability has led European manufacturers to develop eco-friendly sports equipment, appealing to environmentally conscious consumers. The rise of e-commerce in Europe also contributes to market growth, providing consumers with greater access to a wide range of sports products and facilitating online shopping for specialized equipment.
Asia-Pacific
The Asia-Pacific region is poised for significant growth in the Sports Equipment Market, currently holding approximately 25% of the market share. This region has seen a surge in health consciousness, urbanization, and increasing disposable incomes, driving demand for sports and fitness products. Countries like China and India are at the forefront of this growth, with a rapidly expanding middle class that values health and wellness. The rise of sports leagues, such as the Indian Premier League (IPL) and the Chinese Super League, has fueled interest in team sports and increased participation rates. Government initiatives aimed at promoting sports, such as the "Fit India Movement" in India, are encouraging citizens to engage in physical activities, leading to a corresponding rise in demand for sports equipment. Additionally, the growing popularity of fitness centers and gyms in urban areas further propels the market, as more consumers seek access to professional-grade equipment. The Asia-Pacific region is expected to see continued expansion, with market analysts predicting a CAGR of over 7% in the coming years, driven by these emerging trends and factors.
Key Players:
- Nike, Inc.
- Adidas AG
- Puma SE
- Under Armour, Inc.
- New Balance Athletics, Inc.
- Reebok International Ltd.
- ASICS Corporation
- Wilson Sporting Goods Co.
- Callaway Golf Company
- Amer Sports Corporation
Competitive Analysis:
The Sports Equipment Market is characterized by intense competition among major players, each striving to capture market share through innovation, branding, and strategic partnerships. Companies like Nike and Adidas lead the market with their strong brand equity and extensive product lines, offering everything from footwear to apparel and equipment. These brands invest heavily in research and development to introduce advanced technologies and sustainable materials, catering to the growing demand for eco-friendly products. In contrast, emerging players are gaining traction by focusing on niche markets and personalized offerings, leveraging advancements in manufacturing, such as 3D printing, to meet specific consumer needs. Additionally, e-commerce has become a critical battleground, with companies enhancing their online presence to reach a broader audience and improve customer engagement. Strategic collaborations and sponsorships in major sporting events also play a pivotal role in boosting brand visibility and consumer loyalty. Furthermore, regional dynamics influence competitive strategies, as companies tailor their products and marketing efforts to align with local preferences and cultural factors. As the market evolves, companies will need to adapt to trends such as sustainability, technological integration, and shifting consumer behaviors to maintain their competitive edge. Overall, the competitive landscape in the Sports Equipment Market is dynamic, requiring constant innovation and agility from all players involved.
Recent Developments:
- In March 2022, Huawei announced significant software updates for its Watch GT 2e and Watch GT 2 series smartwatches. These updates introduce features from the GT 3 and Watch 3 models, including the ability to download third-party apps.
Market Concentration & Characteristics:
The Sports Equipment Market exhibits moderate concentration, dominated by a few key players while still allowing room for smaller brands and niche companies to thrive. Major brands like Nike, Adidas, and Puma control a significant portion of the market share, leveraging their extensive distribution networks and strong brand loyalty to maintain dominance. This concentration is characterized by high investment in marketing, product innovation, and sponsorship of major sporting events, which reinforce their market positions. However, the landscape is also marked by a growing number of emerging companies that focus on specialized products, eco-friendly initiatives, and personalized offerings, catering to specific consumer demands. This diversification fosters a competitive environment where brands must continuously innovate to differentiate themselves. Additionally, the rise of e-commerce has shifted market dynamics, enabling smaller players to reach consumers directly without relying solely on traditional retail channels. As a result, the market is becoming increasingly fragmented, with consumers benefiting from a wider range of choices. Trends such as health consciousness, sustainability, and technological integration are shaping the characteristics of the market, compelling both established and emerging brands to adapt their strategies accordingly. Overall, while a few key players dominate, the market remains dynamic, with diverse characteristics and opportunities for growth.
Report Coverage:
This report provides a comprehensive analysis of the Sports Equipment Market, encompassing various dimensions, including market size, growth trends, and key drivers. It covers segmentation based on product types-such as fitness equipment, team sports gear, and outdoor adventure products-alongside technological innovations like smart technologies and sustainable materials. The report delves into regional dynamics, examining major markets in North America, Europe, and the Asia-Pacific region, highlighting their unique characteristics and growth potential. Additionally, the competitive landscape is thoroughly analyzed, identifying leading players and their strategies, as well as emerging brands that are disrupting the market. The report also addresses current challenges, including intense competition and supply chain disruptions, which could impact market performance. It further explores consumer trends, such as the rising demand for personalized and eco-friendly products, providing insights into how these factors influence purchasing behavior. By combining quantitative data with qualitative insights, this report aims to equip stakeholders-ranging from industry executives and investors to policymakers and market analysts-with the necessary knowledge to make informed decisions and strategically navigate the evolving landscape of the Sports Equipment Market. Overall, this report serves as a valuable resource for understanding the complexities and opportunities within the industry, supporting strategic planning and investment initiatives.
Future Outlook:
- Anticipate continued growth in demand for eco-friendly sports equipment as consumers prioritize sustainability in their purchasing decisions.
- Expect increased integration of smart technologies in sports gear, enhancing user experience through data analytics and performance tracking.
- Observe a rise in personalized and customizable products, catering to individual preferences and enhancing customer satisfaction.
- Anticipate greater investment in digital marketing and e-commerce platforms, enabling brands to reach a broader audience effectively.
- Expect a growing focus on community and grassroots sports initiatives, driven by governmental and non-governmental organizations to promote physical activity.
- Monitor the expansion of fitness centers and health clubs, increasing demand for high-quality equipment in urban areas.
- Observe technological advancements in manufacturing, such as 3D printing, facilitating rapid prototyping and innovation in product design.
- Anticipate a shift towards omnichannel retail strategies, blending online and offline experiences for consumers.
- Expect rising health consciousness to drive participation in various sports, boosting demand across multiple product categories.
- Monitor the emergence of new players in the market, fostering competition and innovation in product offerings and marketing strategies.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Increasing Health Consciousness
Rising awareness of health and fitness, coupled with concerns over obesity and lifestyle diseases, is motivating more consumers to participate in sports and fitness activities, directly boosting demand for sports equipment.
Growth of Sports Participation and Events
The proliferation of both recreational and competitive sports, fueled by global events and grassroots initiatives, is expanding the consumer base for sports equipment across all age groups.
Technological Advancements in Sports Equipment
Innovations such as smart wearables, performance-tracking devices, and advanced materials are enhancing product appeal and functionality, attracting tech-savvy consumers seeking to optimize their athletic performance.
E-commerce and Digital Retail Growth
The expansion of online retail platforms has made sports equipment more accessible, offering consumers a wider selection and competitive pricing, which is accelerating market growth.
Shift Toward Sustainable Products
Growing environmental awareness is driving demand for eco-friendly and sustainably produced sports equipment, prompting brands to innovate with recycled materials and green manufacturing processes.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is driving the growth of the Sports Equipment Market?
What is the projected market value of the Sports Equipment Market by 2032?
How is technology influencing the Sports Equipment Market?
Which region dominates the Sports Equipment Market?
What growth opportunities exist in the Asia-Pacific region?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By End-User
- 1.2.1 Individual Consumers
- 1.2.2 Schools and Educational Institutions
- 1.2.3 Professional Sports Teams
- 1.2.4 Fitness Centers and Gyms
- 1.3 By Technology
- 1.3.1 Smart Technologies
- 1.3.2 Advanced Materials
- 1.3.3 3D Printing and Customization
- 1.3.4 Traditional Manufacturing Processes
- 1.4 By Product Type
- 1.4.1 Fitness Equipment
- 1.4.2 Team Sports Equipment
- 1.4.3 Individual Sports Equipment
- 1.4.4 Outdoor and Adventure Gear
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2032: USD 662.5 million → Forecast year: USD 1,160 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2032
- 3.3 Forecast Market Size
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Sports Equipment Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Sports Equipment Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Sports Equipment Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Sports Equipment Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Sports Equipment Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Sports Equipment Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Sports Equipment Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Sports Equipment Market Outlook
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2032: USD 662.5 million → Forecast year: USD 1,160 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2032
- 11.2 Market Forecast
- 11.2.1 Revenue Forecast
- 11.2.2 Volume Forecast
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Sports Equipment Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2032
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By End-User - Market Size and Forecast
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast
- 12.3.4 Volume Forecast
- 12.3.5 Base-Year Market Share, 2032
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Individual Consumers
- 12.3.7.2 Schools and Educational Institutions
- 12.3.7.3 Professional Sports Teams
- 12.3.7.4 Fitness Centers and Gyms
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Technology - Market Size and Forecast
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast
- 12.4.4 Volume Forecast
- 12.4.5 Base-Year Market Share, 2032
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Smart Technologies
- 12.4.7.2 Advanced Materials
- 12.4.7.3 3D Printing and Customization
- 12.4.7.4 Traditional Manufacturing Processes
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Product Type - Market Size and Forecast
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast
- 12.5.4 Volume Forecast
- 12.5.5 Base-Year Market Share, 2032
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Fitness Equipment
- 12.5.7.2 Team Sports Equipment
- 12.5.7.3 Individual Sports Equipment
- 12.5.7.4 Outdoor and Adventure Gear
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global Sports Equipment End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Sports Equipment Geographic Market Outlook
- 14.1 Regional Market Size and Share, 2032
- 14.2 Regional Market Forecast
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Sports Equipment Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Sports Equipment Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2032
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Nike, Inc.
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Adidas AG
- 18.4 Puma SE
- 18.5 Under Armour, Inc.
- 18.6 New Balance Athletics, Inc.
- 18.7 Reebok International Ltd.
- 18.8 ASICS Corporation
- 18.9 Wilson Sporting Goods Co.
- 18.10 Callaway Golf Company
- 18.11 Amer Sports Corporation
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

