
Market Overview
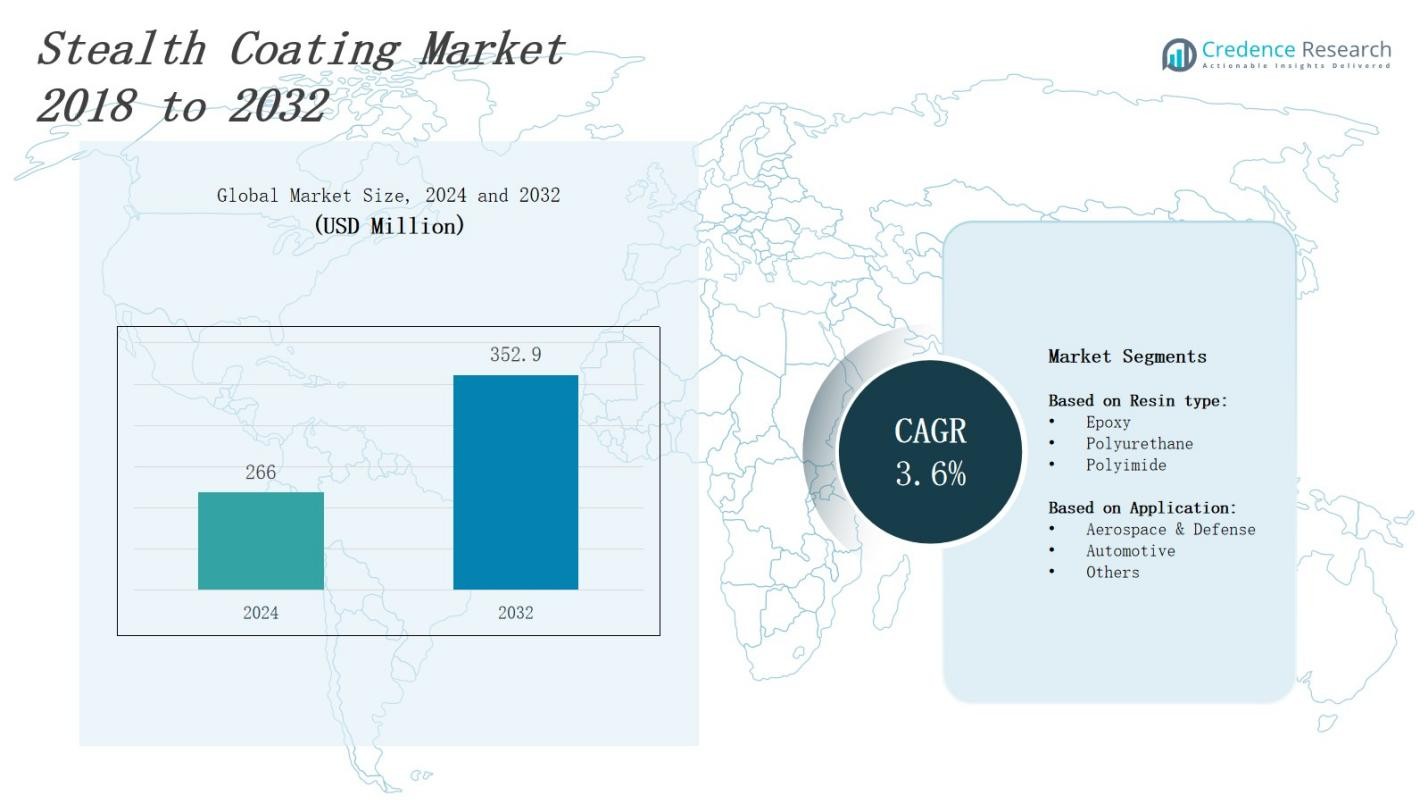
The Stealth Coating Market is projected to grow from USD 266 million in 2024 to USD 352.9 million by 2032, expanding at a CAGR of 3.6%.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2024 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Stealth Coating Market Size 2024 | USD 266 Million |
| Stealth Coating Market, CAGR | 3.6% |
| Stealth Coating Market Size 2032 | USD 352.9 Million |
The stealth coating market grows driven by increasing defense modernization programs and rising demand for advanced military technologies to enhance aircraft and vehicle survivability. Governments worldwide prioritize reducing radar detection, fueling investments in stealth materials. Technological advancements improve coating durability, thermal resistance, and radar-absorbing efficiency, boosting adoption across aerospace and defense sectors. Market trends include development of multifunctional coatings combining stealth with corrosion resistance and environmental protection. Additionally, growing emphasis on lightweight materials to enhance fuel efficiency and maneuverability supports market expansion. Increasing collaborations between defense contractors and research institutions accelerate innovation, strengthening the stealth coating market’s growth trajectory.
The stealth coating market spans key regions including North America, Europe, Asia-Pacific, and the Rest of the World, with North America leading at 35% market share followed by Asia-Pacific at 30%, Europe at 25%, and the Rest of the World at 10%. Major players such as AkzoNobel N.V., BASF SE, Lockheed Martin Corporation, and PPG Industries, Inc. dominate the competitive landscape. These companies focus on innovation, strategic partnerships, and regional expansions to strengthen their presence and address the diverse demands across these global markets.
Market Insights
- The stealth coating market will grow from USD 266 million in 2024 to USD 352.9 million by 2032 at a CAGR of 3.6%.
- Increasing defense modernization programs and demand for advanced military technologies drive growth by enhancing aircraft and vehicle survivability.
- Technological improvements boost coating durability, thermal resistance, and radar-absorbing efficiency, expanding use in aerospace and defense sectors.
- Multifunctional coatings that combine stealth with corrosion resistance and environmental protection gain traction, supporting market expansion.
- Lightweight materials receive growing emphasis to improve fuel efficiency and maneuverability of defense platforms.
- Collaborations between defense contractors and research institutions accelerate innovation, strengthening market growth.
- North America leads with 35% market share, followed by Asia-Pacific at 30%, Europe at 25%, and the Rest of the World at 10%.
Market Drivers
Rising Defense Modernization and Military Expenditure
The stealth coating market benefits from increased defense budgets worldwide focused on modernizing military assets. Countries invest heavily in upgrading aircraft, naval vessels, and ground vehicles to improve survivability against advanced detection systems. It supports governments’ strategic goals to maintain technological superiority and enhance national security. Rising geopolitical tensions drive procurement of stealth technologies to counter evolving radar and sensor threats. This demand encourages manufacturers to develop advanced coatings with improved radar-absorbing properties. Stealth coatings play a critical role in maintaining stealth capabilities in next-generation defense platforms.
Technological Advancements in Coating Materials
Innovation in stealth coating materials propels market growth by enhancing performance and durability. Manufacturers develop coatings with superior radar absorption, thermal resistance, and environmental protection. These advancements extend the operational lifespan of military equipment under harsh conditions. Lightweight formulations also improve fuel efficiency and maneuverability of defense vehicles. The ability to customize coatings for specific applications strengthens their adoption across aerospace, naval, and land platforms. It enables defense forces to optimize stealth performance without compromising other functional requirements.
- For instance, Qingdao Air++ New Materials Co Ltd created a stealth coating combining a reinforced chopped fiber matrix with pressure-resistant hollow microspheres and wave-absorbing agents to provide both thermal insulation and full-frequency radar absorption for aircraft surfaces.
Growing Demand for Multifunctional Coatings
The market experiences strong demand for stealth coatings that offer additional protective features beyond radar absorption. Combining stealth properties with corrosion resistance, anti-icing, and UV protection reduces maintenance costs and operational downtime. This multifunctionality increases coating value and operational efficiency for defense organizations. Manufacturers respond by integrating nanotechnology and advanced polymers into their products. The trend encourages continuous research to meet stringent military specifications and environmental regulations. It also opens opportunities for coating applications in commercial aviation and security sectors.
- For instance, Weihua Cao’s stealth aircraft carrier coating integrates a dual-layered system of polyurethane foam and graphene-based radiation-absorbing layers, delivering combined radar-absorbent and acoustic protection
Strategic Collaborations and Government Initiatives
Collaborations between defense contractors, research institutions, and governments accelerate stealth coating innovations. Joint development projects focus on next-generation materials and application technologies that enhance coating effectiveness. Governments support such initiatives through funding and policy frameworks that prioritize stealth technology advancement. It helps reduce development timelines and lower costs for defense agencies. These partnerships promote knowledge sharing and technological breakthroughs essential for maintaining competitive advantages. The combined efforts strengthen the stealth coating market’s global growth potential.
Market Trends
Rising Defense Modernization and Military Expenditure
The stealth coating market benefits from increased defense budgets worldwide focused on modernizing military assets. Countries invest heavily in upgrading aircraft, naval vessels, and ground vehicles to improve survivability against advanced detection systems. It supports governments’ strategic goals to maintain technological superiority and enhance national security. Rising geopolitical tensions drive procurement of stealth technologies to counter evolving radar and sensor threats. This demand encourages manufacturers to develop advanced coatings with improved radar-absorbing properties. Stealth coatings play a critical role in maintaining stealth capabilities in next-generation defense platforms.
- For instance, Intermat Defense in France produces nanostructured stealth paints and radar-absorbing films used in European defense programs to manage thermal and radar signatures of military platforms.
Technological Advancements in Coating Materials
Innovation in stealth coating materials propels market growth by enhancing performance and durability. Manufacturers develop coatings with superior radar absorption, thermal resistance, and environmental protection. These advancements extend the operational lifespan of military equipment under harsh conditions. Lightweight formulations also improve fuel efficiency and maneuverability of defense vehicles. The ability to customize coatings for specific applications strengthens their adoption across aerospace, naval, and land platforms. It enables defense forces to optimize stealth performance without compromising other functional requirements.
Growing Demand for Multifunctional Coatings
The market experiences strong demand for stealth coatings that offer additional protective features beyond radar absorption. Combining stealth properties with corrosion resistance, anti-icing, and UV protection reduces maintenance costs and operational downtime. This multifunctionality increases coating value and operational efficiency for defense organizations. Manufacturers respond by integrating nanotechnology and advanced polymers into their products. The trend encourages continuous research to meet stringent military specifications and environmental regulations. It also opens opportunities for coating applications in commercial aviation and security sectors.
Strategic Collaborations and Government Initiatives
Collaborations between defense contractors, research institutions, and governments accelerate stealth coating innovations. Joint development projects focus on next-generation materials and application technologies that enhance coating effectiveness. Governments support such initiatives through funding and policy frameworks that prioritize stealth technology advancement. It helps reduce development timelines and lower costs for defense agencies. These partnerships promote knowledge sharing and technological breakthroughs essential for maintaining competitive advantages. The combined efforts strengthen the stealth coating market’s global growth potential.
- For instance, Intermat, a company with over 20 years of in-house R&D, serves as a single-source stealth coating provider for various military applications. Their expertise reflects long-term strategic development aimed at advancing stealth technology coatings for defense use.
Market Challenges Analysis
High Production Costs and Complex Manufacturing Processes Limit Market Expansion
The stealth coating market faces challenges due to the high costs associated with raw materials and advanced manufacturing techniques. Producing radar-absorbing coatings requires specialized materials that often involve expensive polymers and nanomaterials, which increase overall expenses. Complex application processes demand precision and skilled labor, raising production time and cost. These factors restrict widespread adoption, especially in cost-sensitive defense budgets or emerging markets. Manufacturers must balance performance requirements with affordability to gain broader acceptance. The need for strict quality control and compliance with military standards adds further complexity. It often slows down production scaling and limits rapid deployment across platforms.
Environmental and Durability Concerns Impact Long-Term Performance and Regulatory Compliance
Stealth coatings must endure harsh environmental conditions, including extreme temperatures, moisture, and UV exposure, without degrading performance. Maintaining radar-absorbing efficiency while providing corrosion resistance and mechanical strength presents technical difficulties. Coatings can deteriorate under operational stress, requiring frequent maintenance or reapplication, which increases lifecycle costs. Regulatory frameworks targeting environmental safety impose restrictions on hazardous substances used in coatings, complicating formulation development. Manufacturers face challenges in meeting these evolving regulations without compromising stealth capabilities. It demands continuous innovation to develop eco-friendly and durable coatings. Failure to address these issues could hinder market growth and acceptance in global defense sectors.
Market Opportunities
Expansion of Defense Modernization Programs and Increasing Military Expenditure Drive Growth Prospects
The stealth coating market benefits from growing investments in defense modernization across multiple regions. Countries focus on upgrading their military assets to enhance survivability and operational capabilities against advanced detection technologies. Rising geopolitical tensions and strategic defense priorities boost demand for radar-absorbing coatings in aircraft, naval vessels, and ground vehicles. It creates opportunities for manufacturers to introduce advanced products with improved performance and customized solutions. Governments’ commitment to strengthening national security encourages long-term procurement contracts. The increasing shift toward lightweight and multifunctional coatings further supports market expansion. This environment fosters innovation and broad adoption of stealth coatings worldwide.
Technological Innovation and Diversification into Commercial Applications Open New Revenue Streams
Advancements in material science and nanotechnology present significant opportunities to improve stealth coating properties and reduce costs. Manufacturers develop coatings with enhanced durability, thermal resistance, and environmental protection, meeting stringent military standards. It enables stealth technology integration into emerging platforms such as unmanned aerial vehicles and next-generation fighter jets. Expanding applications beyond defense into commercial aerospace, automotive, and security sectors offer additional growth avenues. Customized formulations tailored for specific operating environments create competitive advantages. Collaborations between research institutions and industry players accelerate product development and commercialization. These factors position the stealth coating market for sustained innovation and market penetration.
Market Segmentation Analysis:
By Resin Type
The stealth coating market segments by resin type primarily into epoxy, polyurethane, and polyimide. Epoxy resins dominate because they offer excellent adhesion, chemical resistance, and mechanical strength, making them suitable for harsh operational environments. Manufacturers prefer epoxy coatings for their durability and ability to maintain radar-absorbing properties under extreme conditions. Polyurethane resins gain traction due to flexibility and weather resistance, supporting applications that require impact absorption and corrosion protection. Polyimide coatings serve niche applications requiring high thermal stability. It remains critical for producers to optimize resin formulations to meet evolving military specifications and enhance overall stealth effectiveness.
- For instance, BAE Systems uses polyurethane and radar-absorbing materials for electromagnetic signature management on naval vessels and combat aircraft, supporting multi-spectrum stealth with corrosion resistance and durability.
By Application
The stealth coating market divides applications into aerospace & defense, automotive, and others. Aerospace and defense hold the largest market share due to the high demand for radar-absorbing coatings on military aircraft, naval vessels, and armored vehicles. It plays a vital role in reducing radar signatures and enhancing platform survivability in combat scenarios. The automotive segment shows growth potential with increasing interest in security and advanced coating technologies for specialized vehicles. The others category includes industrial equipment and commercial sectors exploring stealth coatings for niche uses. Expanding defense budgets and technological advancements sustain strong demand across these application segments.
- For instance, the F-117 Nighthawk stealth fighter employs specialized coatings to significantly reduce its radar cross-section, enhancing its survivability in combat.
Segments:
Based on Resin type:
- Epoxy
- Polyurethane
- Polyimide
Based on Application:
- Aerospace & Defense
- Automotive
- Others
Based on the Geography:
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis
North America
North America leads the stealth coating market with a 35% share driven by its advanced defense infrastructure and significant military expenditure. The region’s strong focus on upgrading air and naval fleets with cutting-edge stealth technologies supports continuous demand. The presence of major defense contractors and ongoing research initiatives fosters innovation in radar-absorbing materials. Government policies prioritize enhancing national security and investing in next-generation defense platforms, which stimulates market growth. It also benefits from a well-established supply chain and skilled workforce capable of producing high-performance coatings. The increasing adoption of unmanned systems and advanced fighter jets further strengthens the region’s market position.
Europe
Europe holds 25% of the stealth coating market, supported by robust defense budgets and modernization programs among NATO members. Countries in the region actively invest in upgrading military assets to maintain operational superiority and counter emerging threats. It experiences steady demand for stealth coatings in aerospace, naval, and land platforms. The emphasis on environmental regulations encourages manufacturers to develop eco-friendly and durable coating solutions. Collaborative projects among European defense firms and research institutions accelerate technology advancement. The region’s strategic location and geopolitical dynamics contribute to consistent market activity and growth potential.
Asia-Pacific
Asia-Pacific commands 30% of the stealth coating market due to rapid military modernization in countries such as China, India, and South Korea. The expanding defense expenditure in this region aims to enhance stealth capabilities for aircraft, naval vessels, and armored vehicles. It benefits from increasing domestic production capabilities and government support for indigenous defense technologies. Growing geopolitical tensions drive procurement of advanced radar-absorbing coatings to strengthen national security. The rising number of defense contracts and partnerships with global suppliers boost market development. Expanding aerospace and defense manufacturing hubs also contribute to sustained growth.
Rest of the World
The Rest of the World accounts for 10% of the stealth coating market, driven by emerging economies investing in defense modernization and security enhancements. Countries in Latin America, the Middle East, and Africa seek to upgrade military platforms with stealth technology to improve defense readiness. It faces challenges due to limited domestic manufacturing infrastructure and budget constraints but shows potential through increasing foreign collaborations and technology transfers. The region also explores applications beyond defense, such as commercial aerospace and security systems, expanding market opportunities. Government initiatives and strategic partnerships will remain key to advancing stealth coating adoption in these markets.
Key Player Analysis
- BASF SE
- Lockheed Martin Corporation
- Stealth Veils Inc.
- AkzoNobel N.V.
- The Sherwin-Williams Company
- Intermat Defense
- PPG Industries, Inc.
- Axalta Coating Systems
- BAE Systems
- Hentzen Coatings, Inc.
Competitive Analysis
The stealth coating market features intense competition among leading global players focusing on innovation, product quality, and strategic partnerships. Key companies such as AkzoNobel N.V., BASF SE, Lockheed Martin Corporation, and PPG Industries, Inc. invest heavily in research and development to enhance coating performance, durability, and radar-absorbing efficiency. It drives continuous technological advancements to meet stringent military standards and evolving defense requirements. Companies prioritize expanding their product portfolios with multifunctional coatings that provide corrosion resistance and environmental protection alongside stealth capabilities. Market participants also engage in collaborations with defense agencies and research institutions to accelerate product development and deployment. Competitive differentiation relies on the ability to customize solutions for specific platforms and operational environments. Firms focus on strengthening their global supply chains and enhancing manufacturing capabilities to meet rising demand. The stealth coating market remains dynamic, with companies pursuing mergers, acquisitions, and regional expansions to increase market share and geographical presence.
Recent Developments
- In July 2023, Intermat Defense introduced a new line of stealth coatings designed for military applications. These coatings are engineered to effectively reduce radar signatures, enhancing the stealth capabilities of various defense platforms.
- In late May 2023, Boeing Defense, Space & Security's Phantom Works division announced the construction of a new Advanced Coating Center in St. Louis, set to be operational in 2025.
- In April 2024, BASF's Coatings division launched a new portfolio of eco-efficient clearcoats and undercoats. These products promise improved quality, enhanced productivity, and substantial CO₂ emission reductions, aligning with the growing demand for sustainable solutions in the coatings industry.
Market Concentration & Characteristics
The stealth coating market exhibits a moderately concentrated structure dominated by a few key players such as AkzoNobel N.V., BASF SE, Lockheed Martin Corporation, and PPG Industries, Inc. These companies hold significant market share due to their strong research capabilities, advanced technologies, and extensive defense industry relationships. It demands high capital investment and specialized expertise, creating substantial barriers for new entrants. The market emphasizes continuous innovation to meet stringent military standards and evolving operational requirements. Customization and multifunctionality in coatings drive competitive differentiation. Companies focus on expanding their global footprint through strategic partnerships and regional manufacturing facilities to address diverse customer needs. The stealth coating market relies heavily on government contracts and long-term procurement agreements, which influence market dynamics and stability. This competitive environment fosters technological advancements and promotes steady growth across aerospace, defense, and emerging commercial sectors.
Report Coverage
The research report offers an in-depth analysis based on Resin Type, Application and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Defense modernization programs will continue driving demand for advanced stealth coatings.
- Technological innovation will focus on improving coating durability and radar absorption.
- Lightweight and multifunctional coatings will gain prominence across defense platforms.
- Collaboration between manufacturers and research institutions will accelerate product development.
- Emerging economies will increase investments in stealth coating technologies.
- Environmental regulations will push the development of eco-friendly coating formulations.
- Customization of coatings for specific applications will enhance market competitiveness.
- Expansion into commercial aerospace and security sectors will create new growth avenues.
- Strategic partnerships and regional expansions will strengthen global market presence.
- Integration of nanotechnology will improve performance and reduce production costs.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Rising Defense Modernization and Military Expenditure
Global increases in defense budgets and modernization programs are fueling demand for stealth coatings as countries seek to upgrade aircraft, naval vessels, and ground vehicles to reduce radar detection and enhance survivability.
Technological Advancements in Coating Materials
Continuous innovation in radar-absorbing materials, including the integration of nanotechnology and advanced polymers, is improving coating durability, thermal resistance, and stealth efficiency, making these solutions more attractive for defense applications.
Growing Demand for Multifunctional and Lightweight Coatings
Defense organizations increasingly require coatings that not only provide stealth but also offer corrosion resistance, environmental protection, and reduced weight, supporting operational efficiency and lower maintenance costs.
Strategic Collaborations and Government Initiatives
Partnerships between defense contractors, research institutions, and governments are accelerating the development and deployment of next-generation stealth coatings, supported by funding and policy frameworks that prioritize technological superiority.
Expansion into Emerging Markets and Commercial Sectors
Emerging economies are investing in stealth technologies for defense modernization, while commercial aerospace and security sectors are exploring stealth coatings for niche applications, broadening the market’s growth potential.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for stealth coating market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the stealth coating market projected to grow between 2025 and 2032?
Which stealth coating market segment held the largest share in 2024?
What are the primary factors fueling the growth of the stealth coating market?
Who are the leading companies in the stealth coating market?
Which region commanded the largest share of the stealth coating market in 2024?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Resin Type
- 1.2.1 Epoxy
- 1.2.2 Polyurethane
- 1.2.3 Polyimide
- 1.3 By Application
- 1.3.1 Aerospace & Defense
- 1.3.2 Automotive
- 1.3.3 Others
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 266 million → 2032: USD 352.9 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Stealth Coating Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Stealth Coating Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Stealth Coating Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Stealth Coating Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Stealth Coating Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Stealth Coating Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Stealth Coating Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Stealth Coating Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 266 million → 2032: USD 352.9 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Stealth Coating Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Resin Type - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Epoxy
- 12.3.7.2 Polyurethane
- 12.3.7.3 Polyimide
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Application - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Aerospace & Defense
- 12.4.7.2 Automotive
- 12.4.7.3 Others
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 Segment Growth Comparison
- 12.6 Segment Attractiveness and Priority Matrix
Chapter 13 Global Stealth Coating End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Stealth Coating Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Stealth Coating Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Stealth Coating Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 AkzoNobel N.V.
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 BASF SE
- 18.4 Lockheed Martin Corporation
- 18.5 PPG Industries, Inc.
- 18.6 The Sherwin-Williams Company
- 18.7 Intermat Defense
- 18.8 Axalta Coating Systems
- 18.9 BAE Systems
- 18.10 Hentzen Coatings, Inc.
- 18.11 Stealth Veils Inc.
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

